
 Global Industrial Display System Market | 2026-2036
Global Industrial Display System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Display System Market Outlook
IEC 61010 safety qualification for electrical equipment in industrial environments is collapsing the vendor pool as smaller panel assemblers lack capital for certified testing labs. Samsung Electronics leverages its semiconductor-to-display vertical integration to sustain margin structures in high-brightness outdoor HMI panels. Advantech Co., Ltd. anchors its position through embedded computing platforms that bundle display modules with edge controllers for factory floors.
An industrial display system comprises ruggedized visual interfaces engineered with IP65 ingress protection, wide operating temperature ranges, and anti-glare optical bonding for harsh environments. These systems serve as human-machine interfaces that translate machine telemetry into operator-readable formats across production lines, control rooms, and field equipment. LCD technology dominates installed base economics due to mature supply chains and cost-efficient backlighting architectures, while OLED product types are capturing premium automation segments where contrast ratios and flexible form factors justify higher unit costs. Touchscreen technology leads the technology dimension through capacitive and resistive variants, though interactive digital signage applications in retail and transportation are expanding faster as gesture and voice modalities supplement traditional input methods.
EU F-Gas Regulation and REACH compliance frameworks in Europe restrict fluorinated greenhouse gas use in display manufacturing coolants and chemical substrates, forcing panel makers to reformulate production chemistries or absorb certification costs. The US FAA and NHTSA impose electromagnetic interference and optical clarity standards for displays deployed in aviation and automotive test environments, creating segmented compliance burdens for multi-market suppliers. China's MIIT enforces GB standards for industrial equipment reliability that overlap with international IEC frameworks but require separate in-country testing cycles. Stakeholders must monitor divergence between regional certification regimes as fragmentation risk escalates for manufacturers serving cross-border automation and transportation OEMs.
Market Dynamics
Factory automation in Germany and Japan is absorbing ruggedized touchscreen panels for HMI interfaces, while IEC 61010 safety certification requirements are collapsing the vendor pool as smaller assemblers lack capital for certified testing labs.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated greenhouse gas restrictions in display manufacturing coolants is accelerating reformulation investments among European panel makers, creating first-mover advantages for compliant suppliers.
- Smart manufacturing deployments:China's MIIT enforcement of GB standards for industrial equipment reliability is scaling domestic supply chains through BOE Technology and local system integrators.
- OLED technology:Premium automation segments are absorbing flexible form factors and superior contrast ratios for applications where unit cost premiums justify visual performance gains.
Market Restraints
- Input cost volatility:Rare earth elements and specialized optical bonding materials face price instability from concentrated mining operations in specific geographies.
- Supply concentration risk:Semiconductor-to-display vertical integration at major Korean and Taiwanese producers limits second-source availability for high-brightness outdoor HMI panels.
- Regulatory friction:Divergence between China's GB standards and international IEC frameworks forces separate in-country testing cycles, extending product launch timelines.
Strategic Opportunities
- Underpenetrated field equipment:Agricultural machinery and construction vehicle operators in Brazil and India present untapped demand for IP65-protected displays with wide temperature operating ranges.
- Aviation test environments:US FAA electromagnetic interference standards create a specialized niche for optical clarity-certified panels in aerospace manufacturing quality control.
- Gesture and voice modalities:Interactive digital signage applications in transportation hubs are converging with traditional touchscreen inputs, opening multimodal interface development.
Industry Challenges
- Certification timeline compression:Simultaneous IEC 61010, REACH, and FAA compliance pathways strain testing laboratory capacity and engineering bandwidth.
- Legacy system integration:Edge controller bundling requirements from embedded computing platforms demand proprietary protocol adaptation for brownfield factory floors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Display System Market |
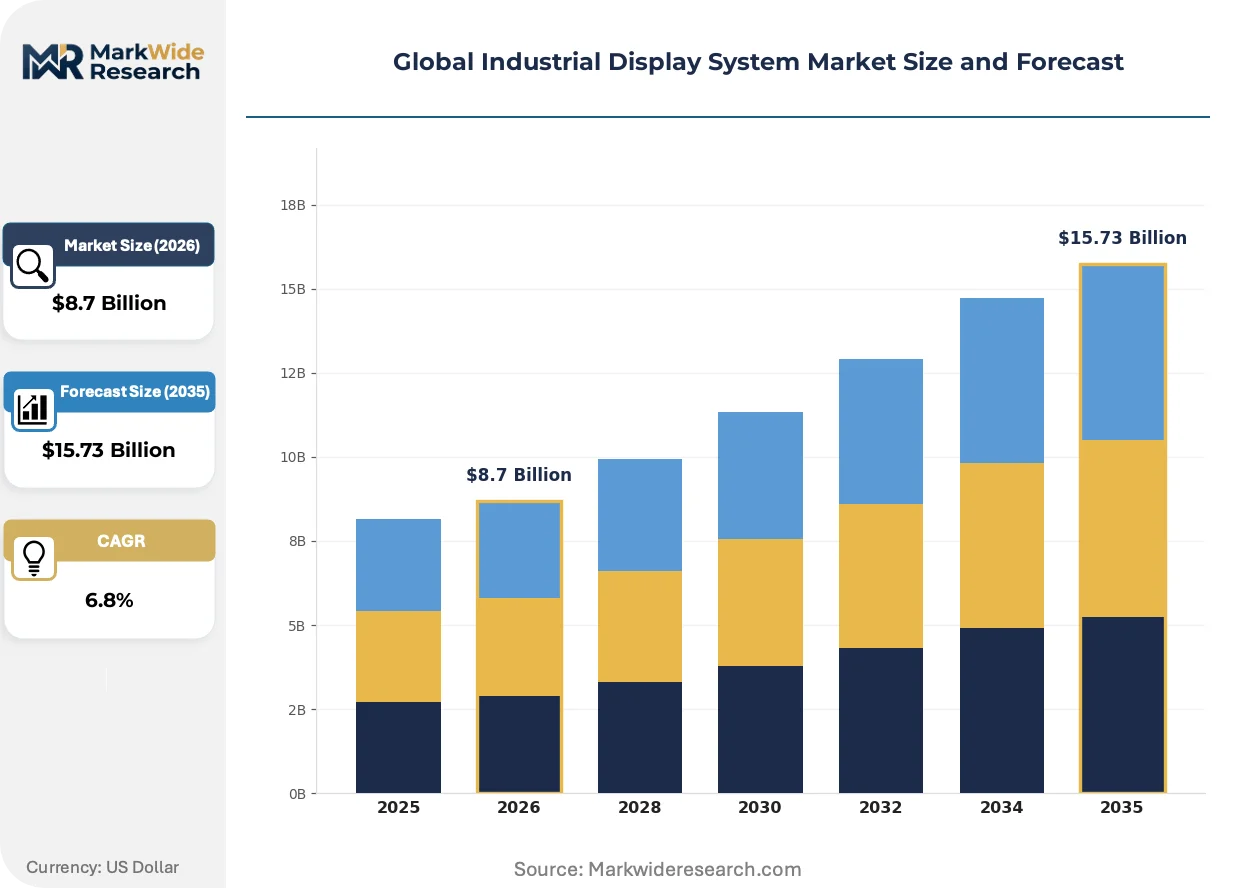
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, LCD, OLED, Projection Application: Manufacturing, Transportation, Retail, Automation Technology: Touchscreen, Interactive, Digital Signage, Virtual Reality End User: Industrial, Commercial, Education, Healthcare |
| Companies Covered | Samsung Electronics, LG Display, Panasonic Holdings, Sharp Corporation, Advantech Co., Ltd., BOE Technology Group Co., Ltd., AUO Corporation, Innolux Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Display System Market Strategic Shifts
Optical bonding chemistries and anti-glare surface treatments are advancing rapidly as display makers compete for specification wins in harsh-environment deployments.
OLED panel technology is displacing LCD architectures in premium automation segments where contrast ratios above 100,000:1 and flexible mounting configurations justify unit cost premiums. Automotive test facilities and semiconductor cleanrooms are adopting these panels fastest, with procurement cycles compressing from 18 months to 9 months for specification approvals. The structural consequence is margin compression for legacy LCD suppliers lacking OLED pilot production lines.
REACH compliance frameworks in Europe are restricting chemical substrates in display manufacturing, forcing reformulation of optical bonding adhesives and coolant chemistries. Panel makers must absorb certification costs or exit European supply chains for industrial automation OEMs. German automotive test equipment manufacturers are responding by consolidating supplier lists to pre-certified vendors with documented substance inventories.
Buyer concentration among Chinese smart manufacturing integrators is consolidating procurement decisions toward domestic panel sources with GB standard pre-certification. System integrators in Shenzhen and Suzhou are replacing distributed multi-vendor purchasing with single-source framework agreements covering display modules and edge controllers. This pattern is most visible in EV battery production line deployments where MIIT reliability mandates intersect with aggressive localization targets.
Global Industrial Display System Market Segmentation
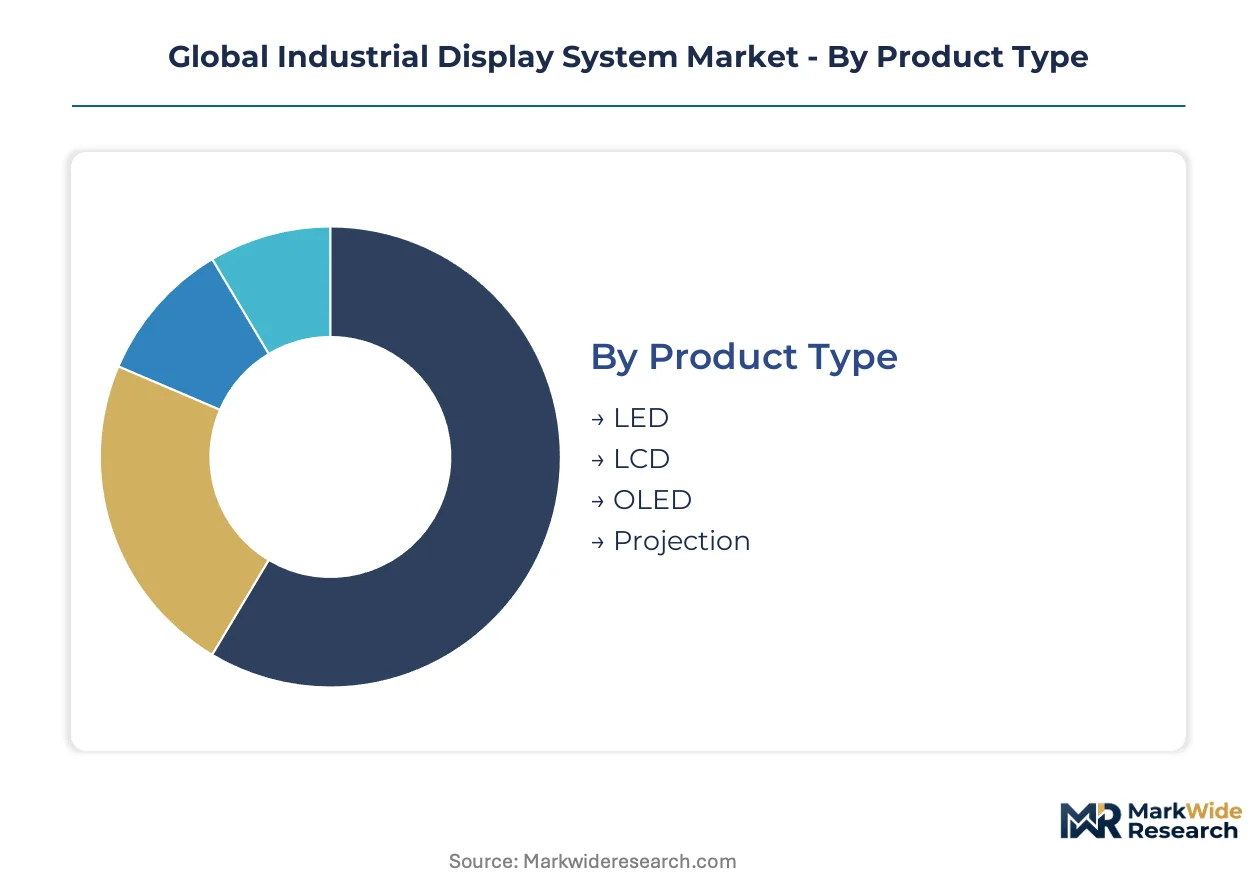
Industrial display systems fragment across four critical dimensions where technology maturity, regulatory exposure, and end-use durability requirements create distinct competitive arenas. Each category isolates procurement decision factors that separate premium specification wins from commodity volume plays.
Product Type:
Regulatory differentiation separates certified outdoor panels from indoor-only alternatives, with IEC 61010 and IP65 ingress ratings governing specification eligibility for factory automation deployments.
- LCD:Mature backlighting architectures and cost-efficient supply chains dominate installed base economics across brownfield manufacturing floors. Demand concentrates in German automotive test facilities where REACH-compliant optical bonding chemistries are mandatory for supplier qualification.
- OLED:Contrast ratios exceeding 100,000:1 and flexible form factors justify unit cost premiums in semiconductor cleanrooms and premium automation segments. Procurement cycles in Japanese automotive test facilities compress from eighteen months to nine months as specification approvals accelerate for these panels.
- LED:High-brightness outdoor HMI panels leverage direct-lit architectures for harsh-environment visibility.
- Projection:Large-format industrial visualization applications in control rooms and training facilities.
Established volume favors LCD; emerging adoption favors OLED.
Application:
Cost tier separation between safety-critical and information-display deployments determines margin structures, with certified HMI interfaces commanding three-to-five-x premiums over signage-only panels.
- Manufacturing:Ruggedized touchscreen panels serve as human-machine interfaces translating machine telemetry into operator-readable formats across production lines. Demand concentrates in China where BOE Technology and local system integrators scale domestic supply chains for smart manufacturing deployments under MIIT GB standards.
- Automation:Edge controller bundling requirements from embedded computing platforms demand proprietary protocol adaptation for factory floor integration. German automotive OEMs consolidate supplier lists to pre-certified vendors with documented REACH substance inventories.
- Transportation:Interactive digital signage in hubs converges with traditional touchscreen inputs for multimodal interface development.
- Retail:Gesture and voice modalities supplement traditional input methods for customer-facing display applications.
Procurement scale favors Manufacturing; specification complexity favors Automation.
Technology:
Volume concentration in mature input modalities contrasts with experimental interface formats where pilot deployments precede standardization.
- Touchscreen:Capacitive and resistive variants lead technology adoption across factory floors, control rooms, and field equipment. Demand concentrates in Japan and Germany where factory automation lines absorb ruggedized panels for HMI interfaces requiring IP65 protection and wide operating temperature ranges.
- Interactive:Gesture and voice modalities expand fastest in transportation and retail applications as multimodal interfaces supplement traditional touchscreen inputs.
- Digital Signage:Information display networks in transportation hubs and commercial facilities.
- Virtual Reality:Immersive training and simulation environments for industrial maintenance and equipment operation.
Deployment maturity favors Touchscreen; interface innovation favors Interactive.
End User:
Customer type determines durability specification intensity, with industrial environments mandating harsher certification regimes than commercial or institutional deployments.
- Industrial:IP65 ingress protection, anti-glare optical bonding, and wide temperature operating ranges define specification minimums for production line and field equipment deployments. Demand concentrates in China, Germany, and Japan where IEC 61010 safety certification collapses the vendor pool as smaller panel assemblers lack capital for certified testing labs.
- Healthcare:Electromagnetic interference standards and optical clarity requirements govern display deployment in medical equipment and diagnostic environments.
- Commercial:Retail and corporate environments with moderated durability requirements compared to industrial specifications.
- Education:Training facilities and institutional learning environments with cost-sensitive procurement patterns.
Certification intensity favors Industrial; procurement volume favors Commercial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT enforcement of GB standards for industrial equipment reliability is scaling domestic supply chains through localization mandates. Germany's IEC 61010 certification requirements are collapsing the vendor pool as smaller panel assemblers lack capital for certified testing labs. Japan's factory automation lines absorb ruggedized touchscreen panels for HMI interfaces under METI industrial policy guidance.
China
Smart manufacturing deployments drive procurement concentration toward domestic panel sources with GB standard pre-certification. MIIT reliability mandates intersect with aggressive localization targets in EV battery production lines. System integrators in Shenzhen and Suzhou consolidate purchasing through single-source framework agreements covering display modules and edge controllers.
Germany
Automotive test equipment manufacturers consolidate supplier lists to pre-certified vendors with documented REACH substance inventories. EU F-Gas Regulation restricts fluorinated greenhouse gas use in display manufacturing coolants, forcing reformulation investments. Industrial clusters in Bavaria and Baden-Württemberg absorb ruggedized panels for factory automation HMI interfaces requiring IP65 protection.
Japan
Factory automation lines in Nagoya and Osaka industrial corridors absorb ruggedized touchscreen panels for HMI interfaces. METI industrial standards govern electromagnetic interference and optical clarity requirements for manufacturing quality control. Procurement cycles compress from eighteen months to nine months as specification approvals accelerate for premium display technologies.
United States
FAA electromagnetic interference standards create specialized niches for optical clarity-certified panels in aerospace manufacturing. NHTSA imposes additional standards for displays deployed in automotive test environments. California and Texas industrial corridors concentrate demand for high-brightness outdoor HMI panels in semiconductor cleanroom applications.
South Korea
Semiconductor-to-display vertical integration sustains margin structures in high-brightness outdoor HMI panels. MFDS-equivalent industrial equipment standards overlap with international IEC frameworks but require separate testing protocols. Seoul-Incheon manufacturing clusters anchor production of premium automation segments where contrast ratios justify unit cost premiums.
Global Industrial Display System Market Competitive Environment
Player mix skews toward diversified electronics conglomerates with captive display manufacturing capabilities. Korean and Taiwanese producers dominate high-brightness outdoor panel supply through backward integration into semiconductor fabrication. Three archetypes define competitive positioning: vertically integrated display manufacturers, embedded computing platform bundlers, and specialized industrial HMI system integrators. Capacity expansion in OLED pilot production lines and strategic partnerships for edge controller protocol adaptation represent the dominant competitive moves.
Within the diversified electronics tier, Samsung Electronics exemplifies vertical integration from semiconductor fabrication through display module assembly. BOE Technology anchors the Chinese domestic supply chain archetype with GB standard pre-certification positioning. Advantech Co., Ltd. occupies a position within the embedded computing platform segment, bundling display modules with edge controllers for factory floor integration.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| Panasonic Holdings |
| Sharp Corporation |
| Advantech Co., Ltd. |
| BOE Technology Group Co., Ltd. |
| AUO Corporation |
| Innolux Corporation |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
IEC 61010 safety certification gates both supplier qualification and price differentiation in industrial display systems, collapsing the vendor pool while concentrating pricing power among certified manufacturers serving German and Japanese factory automation lines.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers, with IEC 61010-qualified panels commanding three-to-five-x premiums over uncertified alternatives in safety-critical HMI deployments. Three-tier pricing structure across premium OLED, standard LCD, and economy indoor-only segments reflects optical bonding chemistry grades and REACH compliance documentation depth. Cost compression in legacy LCD tiers is intensifying because BOE Technology and Chinese domestic suppliers are scaling GB-certified production lines with aggressive localization targets. System integrators in smart manufacturing show the highest price sensitivity, while semiconductor cleanroom operators prioritize contrast ratio performance over unit cost.
Supply Chain Analysis
South Korea and Taiwan anchor semiconductor-to-display fabrication for high-brightness outdoor HMI panels, while China scales domestic LCD module assembly through BOE Technology and Shenzhen-based system integrators. Rare earth elements for specialized optical bonding materials and fluorinated coolants for display manufacturing draw from concentrated mining and chemical processing operations. Single-source vulnerability runs through Korean producers with captive semiconductor fabrication, limiting second-source availability during demand surges. Distribution runs through direct framework agreements between panel makers and automation OEMs, bypassing traditional electronics distributors for volume manufacturing deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial display systems increasingly attach recurring software and edge controller service layers that expand faster than hardware unit growth, particularly in smart manufacturing deployments where predictive maintenance subscriptions accompany panel installations.
For Market Incumbents: Secure pre-certified testing lab capacity under IEC 61010 and REACH frameworks before regulatory divergence accelerates compliance costs. Lock in exclusive edge controller protocol partnerships with German automotive test equipment manufacturers consolidating supplier lists. Extend backward integration into optical bonding chemistry production to defend margin structures against rare earth price volatility.
For New Entrants and Emerging Players: GB standard fast-track certification through MIIT-authorized testing centers in Shenzhen opens procurement access to Chinese EV battery production lines. Target agricultural machinery operators in Brazil and India with IP65-protected displays featuring wide temperature operating ranges where incumbent coverage remains thin. Lead with gesture and voice modality bundles for transportation hub digital signage applications converging with traditional HMI interfaces.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape by stranding non-compliant panel makers lacking reformulated coolant chemistries. Focus on mid-cap specialists with OLED pilot production lines and documented REACH substance inventories for five-to-ten year viability. Watch for procurement cycle compression in Japanese automotive test facilities as a signal of specification approval acceleration favoring premium display technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Pre-Certification Investment | MIIT reliability mandates in China require separate in-country testing cycles for market access. |
| OLED Pilot Production Line Expansion | Japanese automotive test facilities compress procurement cycles from eighteen to nine months for premium panels. |
| Edge Controller Protocol Partnership | Advantech bundles display modules with embedded computing platforms for brownfield factory integration. |
| REACH-Compliant Optical Bonding Reformulation | German automotive OEMs consolidate supplier lists to vendors with documented substance inventories. |
| Agricultural and Construction Field Equipment Entry | Brazilian and Indian machinery operators present untapped demand for IP65-protected harsh-environment displays. |
Study Parameters
A spread of perspectives from plant engineers at German automotive OEMs, procurement leads at Chinese system integrators, aftermarket service heads at Japanese factory automation lines, and technical R&D directors at Korean display manufacturers converged on the working assumptions for this analysis. Primary interview insights combined with secondary validation from SEC filings, customs and trade data, IEC certification registries, and MIIT GB standard documentation. Bottom-up unit demand estimates across product type, application, technology, and end user segments triangulated against top-down market sizing from regional production cluster analysis.
Segmentation dimensions modeled include display technology, application environment, input modality, and end user durability requirements across the projection horizon. CAGRs derived from historical shipment trajectories adjusted for regulatory inflection points and technology substitution curves. Forecast inputs incorporated OLED adoption rates in semiconductor cleanrooms, Chinese localization policy intensity, and REACH compliance cost pass-through assumptions.
Decision-makers should treat outputs as directional under sustained smart manufacturing capital expenditure and stable rare earth supply assumptions; material deviation would warrant model refresh. Recalibration cycles align with shifts in EU F-Gas Regulation enforcement, MIIT GB standard revision schedules, and OLED capacity buildout announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
TFT LCD Modules (11-Inch to 17-Inch) Market
Display Technologies
Graphic LCD Modules Market
Display Technologies
Vietnam Digital Signage Market
Display Technologies
Smartphone Display Market
Display Technologies
Display Mask Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
DLP Projector Market
Display Technologies
Display Fingerprint Technology Market
Display Technologies
Paper-Thin Display Market
Display Technologies
IGZO Display Market
Display Technologies
Global Display Market
Display Technologies
Thin Display Technology Market
Display Technologies
Europe E-Paper Display Market
Display Technologies
Global Embedded Display Market
Display Technologies
Global Display Controllers Market
Display Technologies
Touch Screen Module Market