
 India Semiconductor Market | 2026-2036
India Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
India Semiconductor Market Insights
India's PLI scheme for semiconductor manufacturing is hardening domestic sourcing requirements for government-linked procurement. Samsung Electronics leverages its display and memory ecosystem to anchor component supply relationships with Indian electronics manufacturers. Tata Elxsi sustains design services leadership across automotive and telecommunications verticals. Bharat Electronics Limited dominates defense-grade chip procurement through captive specifications and long-dated supply contracts.
A semiconductor comprises a crystalline solid, typically silicon or gallium arsenide, whose electrical conductivity engineers precisely control through doping with impurities like boron or phosphorus to create p-type and n-type junctions; these junctions form transistors, diodes, and integrated circuits that switch, amplify, or store electronic signals across operating temperatures from minus forty to one hundred twenty-five degrees Celsius. Memory Chips command premium margins as data center operators and mobile device manufacturers expand storage density requirements. Analog ICs compete for design wins in automotive and industrial power management applications where voltage regulation precision determines system reliability. GaN technology displaces silicon in high-frequency power conversion segments where efficiency losses directly increase thermal management costs.
BIS certification requirements and the CEA's technical standards for electronics and IT goods shape product compliance pathways for imported and domestically fabricated semiconductors. CDSCO oversight applies where semiconductor components integrate into regulated medical devices, adding a secondary approval layer for healthcare-facing suppliers. The RBI's foreign exchange frameworks influence capital equipment import timelines for fabs under construction. Stakeholders must weigh India's emerging foundry capacity against established East Asian supply chains when committing to multi-year procurement or partnership structures.
Market Dynamics
India's PLI scheme for semiconductor manufacturing is compressing investment timelines as domestic fabrication capacity races to offset import dependency for critical logic and memory components.
Growth Catalysts
- Production-Linked Incentive scheme:India's PLI framework for semiconductor manufacturing subsidizes capital expenditure for fabs and assembly facilities, accelerating domestic wafer production commitments.
- Electric powertrain demand:Automotive OEMs are scaling chip procurement for battery management systems and motor control units as electric vehicle assembly expands.
- Dholera cluster concentration:Gujarat's Special Investment Region anchors India's first commercial fab ecosystem, concentrating equipment suppliers and technical workforce development.
Market Restraints
- Equipment import dependency:Lithography and deposition tools from Dutch and Japanese suppliers create procurement bottlenecks for fabs under construction.
- Specialized technical workforce scarcity:Process engineers with 300mm wafer experience remain concentrated in Taiwan and South Korea, limiting domestic hiring pipelines.
- Raw material purity requirements:Electronic-grade silicon and specialty gases require import certification under BIS standards, extending qualification timelines.
Strategic Opportunities
- Compound semiconductor white space:Gallium nitride and silicon carbide substrates for power electronics remain underdeveloped domestically, opening captive supply opportunities for automotive and renewable energy converters.
- Design services export expansion:Tata Elxsi and similar firms can extend automotive and telecommunications chip design contracts to European and North American OEMs seeking cost arbitrage.
- Defense procurement localization:Bharat Electronics Limited's captive specifications create pathways for domestic foundries to qualify for military-grade component supply.
Industry Challenges
- Cleanroom construction velocity:Fab infrastructure requires eighteen-to-twenty-four-month build cycles with zero tolerance for particulate contamination, compressing project management margins.
- Multi-regulator compliance layering:BIS certification for electronics, CDSCO oversight for medical device integration, and RBI foreign exchange frameworks for equipment imports create overlapping approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Semiconductor Market |
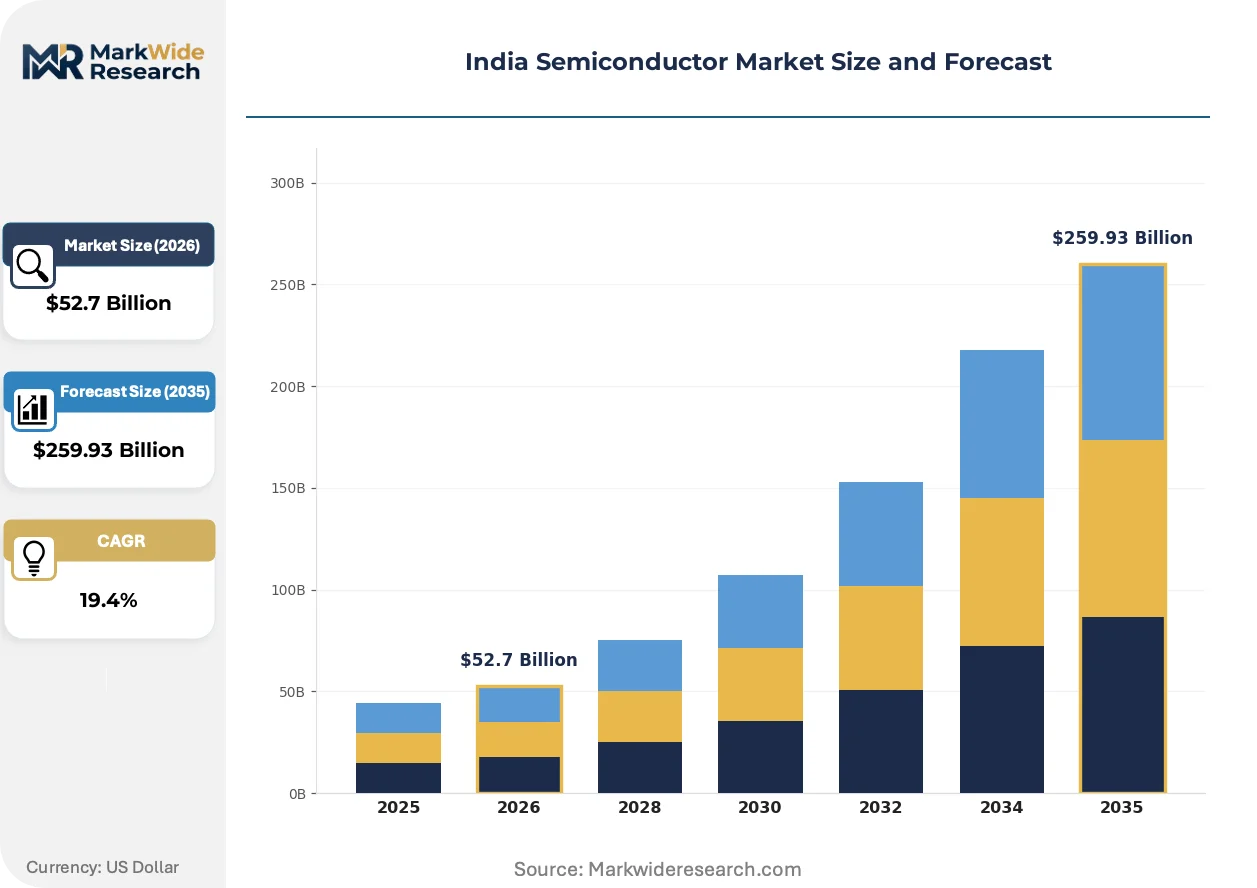
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $259.93 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog ICs, Digital ICs, Microcontrollers, Memory Chips End User: Consumer Electronics, Automotive OEMs, Telecommunications, Industrial Applications Technology: CMOS, BiCMOS, SOI, GaN Application: IoT Devices, Data Centers, Mobile Devices, Gaming Consoles |
| Companies Covered | Intel India, Samsung Electronics, Tata Elxsi, HCL Technologies, Bharat Electronics Limited, STMicroelectronics India, NXP Semiconductors India, Vedanta Semiconductor, Moschip Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Semiconductor Market Trends and Innovations
Silicon carbide power semiconductors are electrifying automotive traction inverters. India's regulatory apparatus is hardening technical standards for electronics imports. Procurement patterns among data center operators are compressing supplier qualification cycles.
Gallium nitride high-electron-mobility transistors are electrifying efficiency benchmarks in server power supplies and electric vehicle onboard chargers. Data center operators in Noida and Hyderabad are specifying GaN-based totem-pole PFC stages to reduce cooling loads. This technology is electrifying competitive positioning among power supply manufacturers serving hyperscale facilities.
BIS certification requirements for electronics and IT goods are tightening conformity assessment pathways for imported semiconductors. The Bureau's technical standards now mandate local testing for categories spanning memory modules to microcontrollers. Importers are responding by pre-qualifying domestic testing laboratories to compress clearance timelines.
Data center operators are consolidating procurement authority to direct volume toward qualified domestic assembly partners. Long-standing distribution relationships through Mumbai and Bengaluru electronics markets are giving way to direct foundry contracts. This concentration is most visible in Tamil Nadu, where Chennai's server manufacturing corridor anchors captive component supply agreements.
India Semiconductor Market Segmentation
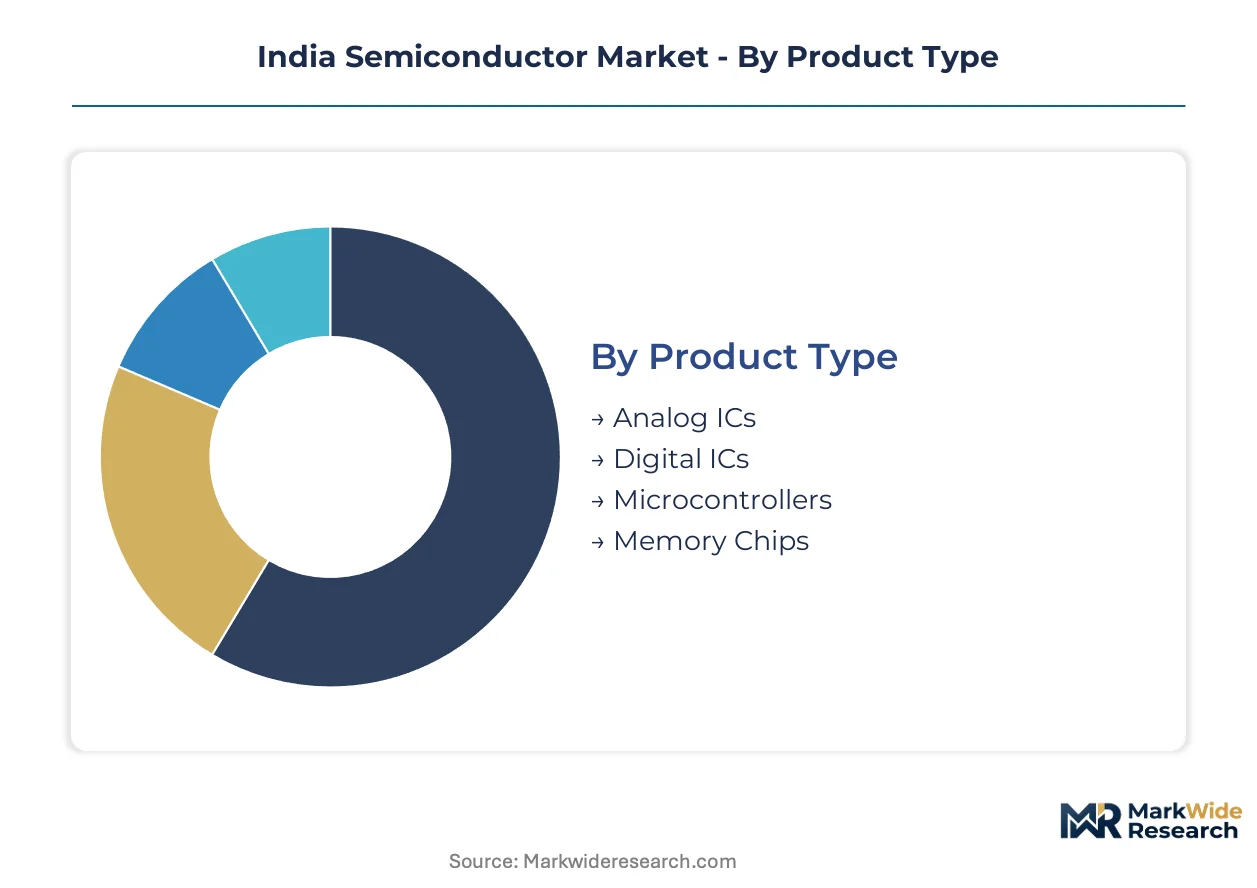
Semiconductor procurement patterns in India diverge sharply across product architectures and end-use specifications. Buyers prioritize power efficiency in automotive traction systems, density in data center storage, and cost optimization in consumer electronics assembly.
Product Type:
Cost tiers separate premium precision components from commodity logic chips in procurement negotiations.
- Analog ICs:These components manage voltage regulation, signal conversion, and sensor interfacing through continuous electrical signal processing. Automotive OEMs in Chennai and Pune specify automotive-grade analog ICs for battery management systems, with BIS certification requirements extending qualification timelines for imported variants.
- Memory Chips:DRAM and NAND flash architectures store executable code and user data through transistor-based charge retention. Data center operators in Hyderabad and Noida are consolidating procurement authority toward qualified domestic assembly partners, compressing traditional distribution relationships.
- Digital ICs:Logic gates and processors execute computational operations through binary state switching.
- Microcontrollers:Integrated processing units combine CPU, memory, and peripherals on single dies for embedded control applications.
Memory Chips lead volumes today; Analog ICs are gaining share fastest.
End User:
Application maturity determines whether buyers accept longer lead times for qualified supply or demand immediate availability.
- Automotive OEMs:Electric powertrain assembly requires silicon carbide MOSFETs and battery management ICs with AEC-Q100 reliability grading. Gujarat's Dholera cluster is concentrating equipment suppliers to serve this vertical as domestic fab capacity scales.
- Telecommunications:Baseband processors and RF front-end modules enable 5G network infrastructure through high-frequency signal handling. TRAI spectrum allocation timelines are accelerating equipment deployment schedules, tightening component delivery windows.
- Consumer Electronics:Smartphone and appliance manufacturers specify cost-optimized logic and memory components.
- Industrial Applications:Programmable logic controllers and motor drives demand extended temperature range operation.
Consumer Electronics leads volumes today; Automotive OEMs are expanding most quickly.
Technology:
Process node geometry and substrate material dictate thermal performance ceilings and switching efficiency benchmarks.
- CMOS:Complementary metal-oxide-semiconductor pairs p-type and n-type transistors for low static power consumption. Mobile device manufacturers specify CMOS for application processors, with foundry capacity constraints in Taiwan affecting Indian OEM delivery schedules.
- GaN:Gallium nitride wide-bandgap semiconductors enable higher breakdown voltages and switching frequencies than silicon. Data center operators specify GaN-based totem-pole PFC stages to reduce cooling loads in Noida and Hyderabad facilities.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with low-power CMOS logic.
- SOI:Silicon-on-insulator structures reduce parasitic capacitance for RF and low-power applications.
CMOS leads volumes today; GaN is climbing the fastest.
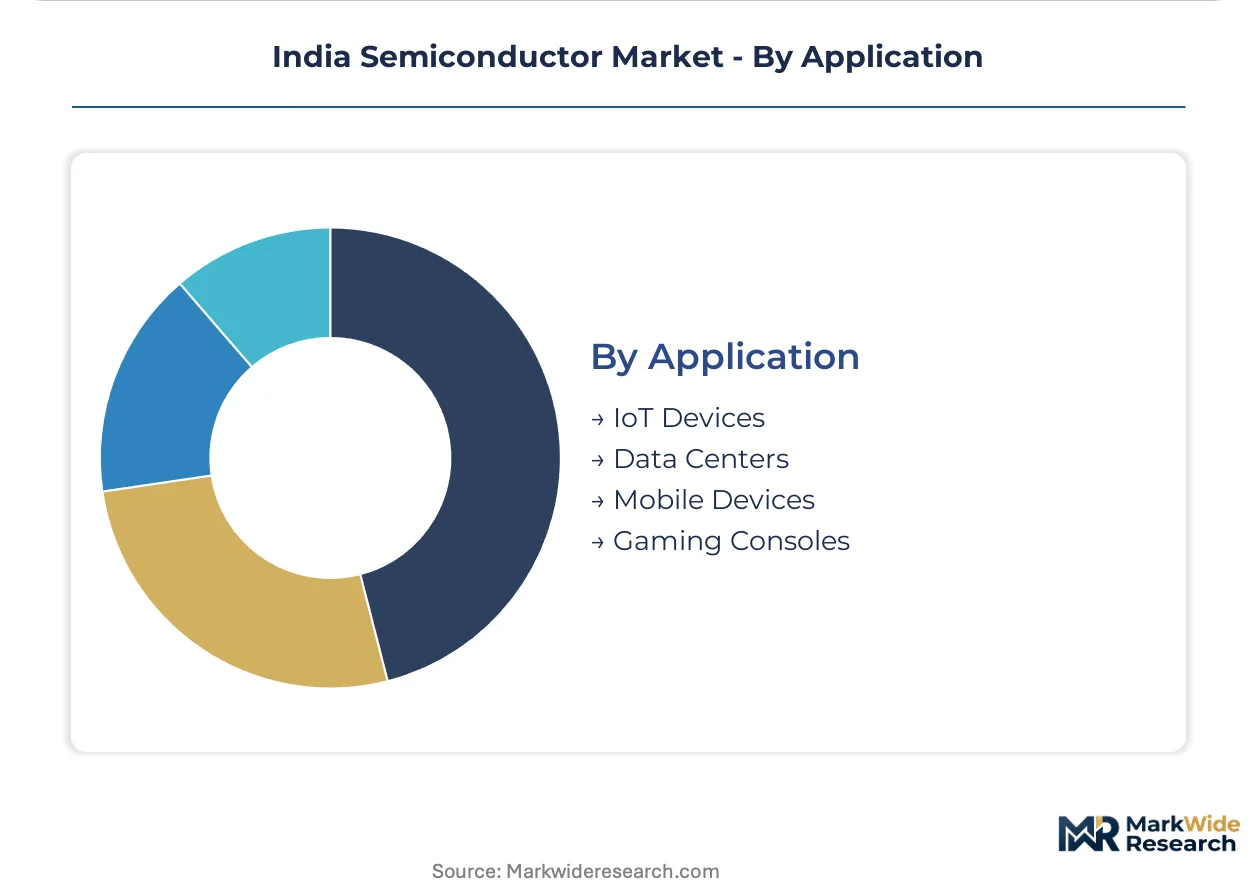
Application:
Volume concentration and margin structure vary dramatically between high-unit consumer devices and infrastructure-scale deployments.
- Data Centers:Server processors, memory modules, and networking ASICs demand 24/7 reliability with minimal failure rates. Tamil Nadu's Chennai corridor anchors captive component supply agreements as operators consolidate procurement authority.
- Mobile Devices:Smartphone SoCs, display drivers, and power management ICs prioritize die size minimization and thermal efficiency. Assembly partners in Noida and Bengaluru source application processors through direct foundry contracts.
- IoT Devices:Sensor nodes and edge controllers require ultra-low power operation with intermittent connectivity.
- Gaming Consoles:High-performance GPUs and memory subsystems deliver real-time graphics rendering.
Mobile Devices leads volumes today; Data Centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's semiconductor industry traces its origins to 1980s public-sector initiatives in Bangalore, where state-owned enterprises established the country's first chip design capabilities before private investment accelerated in the 2000s.
Gujarat
Electric vehicle powertrain assembly and renewable energy inverters drive silicon carbide demand across Ahmedabad and Vadodara industrial zones. The state's PLI scheme allocations subsidize capital expenditure for wafer fabrication facilities. Dholera Special Investment Region anchors India's first commercial fab cluster, concentrating lithography equipment suppliers and process engineering talent pipelines.
Karnataka
Data center expansion and 5G base station deployment sustain demand for memory modules and RF front-end components in Bengaluru. BIS certification requirements for electronics imports shape compliance pathways for semiconductor distributors. The city's Electronics City and Whitefield corridors host captive design centers serving telecommunications and automotive OEMs.
Tamil Nadu
Server manufacturing and industrial automation equipment sustain procurement of power management ICs and microcontrollers around Chennai. CDSCO oversight applies where semiconductor components integrate into regulated medical devices manufactured in Sriperumbudur. The Chennai-Sriperumbudur corridor anchors direct foundry contracts as data center operators consolidate procurement authority.
Telangana
Hyperscale data center construction and cloud infrastructure deployment drive gallium nitride adoption for server power supplies in Hyderabad. TRAI spectrum allocation timelines accelerate 5G equipment deployment schedules, tightening component delivery windows. The city's HITEC City and Genome Valley clusters concentrate fabless design operations and system-level integration facilities.
Maharashtra
Automotive electronics assembly and consumer appliance manufacturing sustain demand for analog ICs and microcontrollers across Pune and Mumbai. RBI foreign exchange frameworks influence capital equipment import timelines for fabs under construction. The Pune-Chakan industrial belt hosts battery management system integrators sourcing AEC-Q100 graded components.
India Semiconductor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across design complexity and certification grade, with defense-grade and automotive-qualified components commanding sustained price premiums over consumer-tier alternatives. The vendor base stratifies into three tiers: multinational fabrication subsidiaries with established foundry relationships, domestic design services specialists with vertical expertise, and emerging domestic fabrication ventures scaling first-mover capacity. Consolidation pressures favor players with captive government procurement channels and multi-year supply contracts. Competitive dynamics center on qualification timelines for BIS certification and strategic partnerships with Gujarat-based fab infrastructure.
Within the multinational fabrication tier, Intel India and Samsung Electronics occupy positions as anchors for process technology access and memory supply relationships. Among domestic specialists, Tata Elxsi exemplifies the design services archetype with embedded automotive and telecommunications vertical expertise. Bharat Electronics Limited represents the defense-captive tier, securing long-dated supply contracts through specialized procurement specifications.
| Leading Market Players |
|---|
| Intel India |
| Samsung Electronics |
| Tata Elxsi |
| HCL Technologies |
| Bharat Electronics Limited |
| STMicroelectronics India |
| NXP Semiconductors India |
| Vedanta Semiconductor |
| Moschip Technologies |
| Others |
Pricing and Supply Chain Analysis
Process engineers with 300mm wafer fabrication experience concentrated in Taiwan and South Korea widen labor-cost differentials between premium automotive-grade chips and economy consumer logic tiers. This workforce scarcity feeds directly into pricing spreads as domestic fabs compete for qualified talent against established East Asian foundries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 automotive-qualified components from industrial-grade and consumer-tier alternatives. Price differentiation rests on certification grade and volume scale, with defense-grade specifications commanding sustained premiums over commercial variants. Cost compression in consumer logic tiers is intensifying as smartphone OEMs consolidate procurement authority toward direct foundry contracts. Consumer electronics manufacturers exhibit highest price sensitivity, while defense procurement through Bharat Electronics Limited shows lowest elasticity due to captive specifications.
Supply Chain Analysis
Single-source vulnerability sits with Dutch lithography equipment suppliers and Japanese deposition tool manufacturers, creating procurement bottlenecks for fabs under construction in Gujarat. Geographic supply concentration centers on Taiwan for leading-edge foundry capacity, South Korea for memory fabrication, and the USA for advanced process technology. Raw material dependencies draw from electronic-grade silicon, specialty gases, and photoresist chemicals subject to BIS import certification. Tariff exposure on capital equipment imports through RBI foreign exchange frameworks compounds delivery risk. Distribution runs through direct foundry contracts replacing traditional Mumbai and Bengaluru electronics market relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in India's semiconductor market rests on domestic fab scale-up compressing import dependency costs and premium-tier shift toward automotive-qualified components. The PLI scheme's capital expenditure subsidies accelerate this transition.
For Market Incumbents: Deepen captive government procurement channels through BIS certification pre-qualification and long-dated supply contracts with defense and automotive OEMs. Add 300mm wafer process engineering capacity in Gujarat's Dholera cluster to offset Taiwan talent competition. Strengthen backward integration into electronic-grade silicon purification to reduce import certification delays. For New Entrants and Emerging Players: Launch via compound semiconductor substrate supply for silicon carbide power electronics serving electric vehicle traction inverters. Target gallium nitride high-electron-mobility transistors for data center power supplies in Hyderabad and Noida, where hyperscale operators specify efficiency benchmarks. Pursue design services export contracts with European automotive OEMs seeking cost arbitrage. For Investors and Strategic Acquirers: Domestic automotive OEMs are the most active acquirer in this space, securing captive component supply through equity stakes in fab ventures. Long-term viability favors vertically integrated players with qualified domestic assembly partnerships. Watch Dholera cluster equipment supplier concentration as inflection indicator for domestic fabrication momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fab Capacity Buildout | Gujarat's Dholera cluster anchors India's first commercial wafer fabrication ecosystem with concentrated equipment suppliers. |
| Automotive Qualification Investment | AEC-Q100 certification pathways open premium-margin supply relationships with Chennai and Pune electric vehicle OEMs. |
| Compound Semiconductor Development | Gallium nitride and silicon carbide substrate production addresses underdeveloped domestic power electronics supply. |
| Design Services Export Expansion | Tata Elxsi and similar firms extend automotive and telecommunications chip design contracts to European cost-sensitive buyers. |
| Defense Procurement Localization | Bharat Electronics Limited specifications create pathways for domestic foundries to qualify military-grade component supply. |
Research Methodology
Direct dialogue with fab construction project managers, semiconductor procurement officers at automotive OEMs, BIS certification specialists, and design services executives grounded qualitative findings in operational reality. Secondary validation drew from RBI foreign exchange notifications, CDSCO medical device integration guidelines, TRAI spectrum allocation records, and PLI scheme disbursement documentation. Bottom-up and top-down triangulation cross-checked wafer production estimates against end-use consumption patterns.
Bottom-up modeling built consumption forecasts from segment-level adoption curves across automotive, telecommunications, and data center verticals. Top-down analysis anchored projections to macro semiconductor trade flows and capital expenditure commitments. Segmentation dimensions span product architecture, end-use specification, process technology, and application intensity. CAGR derivation incorporated equipment import timeline assumptions and workforce development lag factors across the analysis window.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan foundry supply, abrupt PLI scheme modification, and faster-than-anticipated process node migration. Forecasts reflect documented assumptions regarding cleanroom construction velocity and regulator approval timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Organic Polymer Electronics Market
Semiconductors
Germanium Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
Global FD-SOI Wafers Market
Semiconductors
Europe Discrete Semiconductor Market
Semiconductors
Europe Automotive Semiconductor Market
Semiconductors
Gaas Wafer Market
Semiconductors
Global Automotive Semiconductor Market
Semiconductors
Organic Electronics Market
Semiconductors
Global Computer Microchip Market
Semiconductors
Smartphone Battery Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Logic Semiconductor Market
Semiconductors
Semiconductor Bonding Market
Semiconductors
Semiconductor Market
Semiconductors
South Korea Discrete Semiconductors Market