
 Semiconductor Glass Market | 2026-2036
Semiconductor Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Glass Market Intelligence
Feature-size scaling below three nanometers is narrowing the thermal and dimensional tolerance window for interposer substrates, forcing foundries to evaluate glass as a silicon alternative. Corning Incorporated leverages its fusion-draw expertise to supply ultra-thin borosilicate wafers for trial production lines. SCHOTT AG anchors European supply through specialized alkali-free formulations optimized for through-glass via processing. Shin-Etsu Chemical Co. Ltd. competes via backward integration into synthetic quartz and precision polishing chemistries.
Semiconductor glass denotes thermally stable, ultra-pure silicate substrates engineered for flatness below one micron total thickness variation and coefficient of thermal expansion matched to silicon at roughly three parts per million per degree Celsius, serving as interposers, photomask blanks, and hermetic packaging barriers in chip fabrication. Photomask substrates retain the largest value pool due to EUV lithography qualification requirements and replacement-cycle predictability, while specialty glass for fan-out wafer-level packaging records the fastest expansion as panel sizes scale toward 600 millimeter formats. Optical glass for extreme ultraviolet collector optics commands premium pricing but remains concentrated among a qualified supplier base.
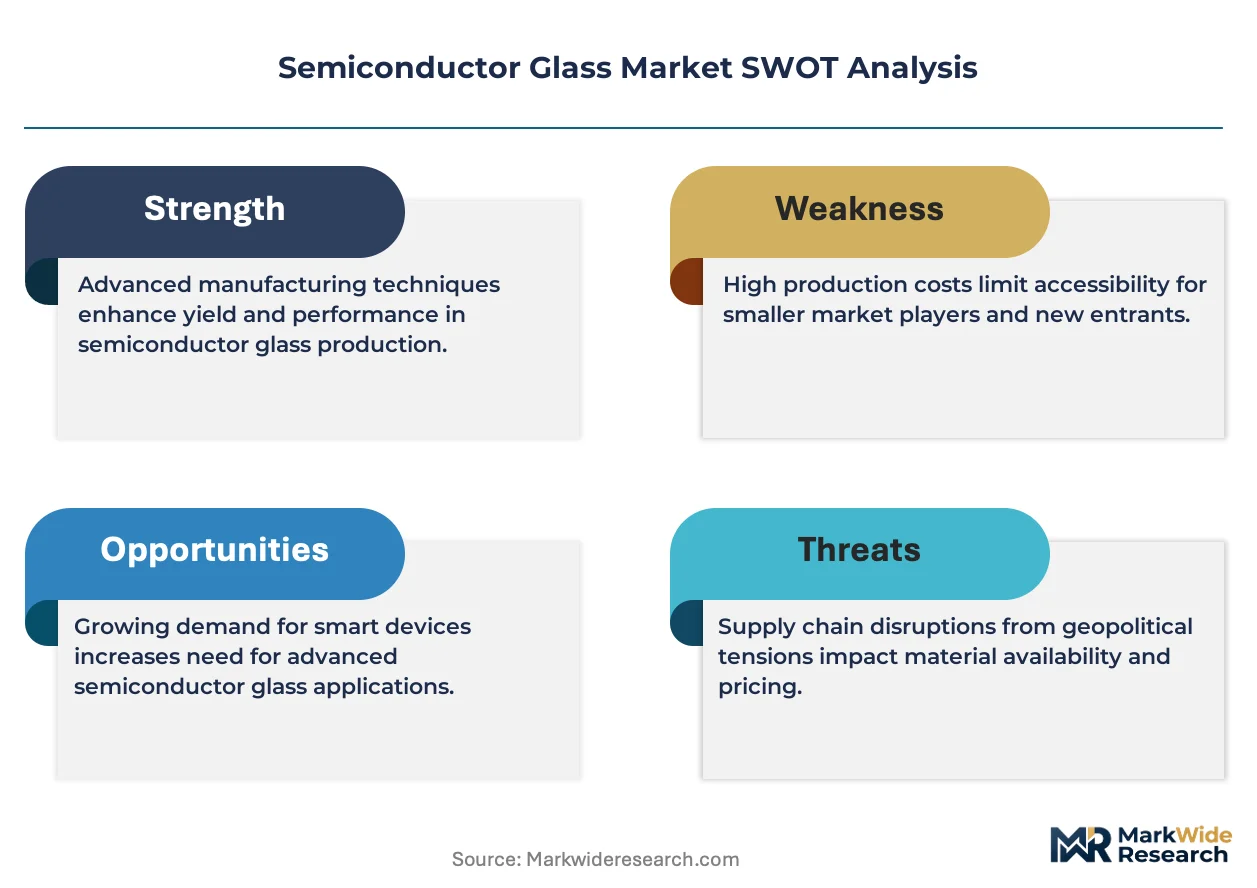
EPA air-quality standards and OSHA silica-exposure limits raise capital costs for North American melting operations, while REACH and RoHS frameworks in Europe restrict heavy-metal dopants in glass compositions destined for consumer-facing electronics. Japan's METI subsidizes domestic substrate supply-chain resilience through designated critical-material status. Stakeholders must track qualification timelines at leading foundries and assess captive versus merchant supply strategies before committing to capacity expansion.
Market Dynamics
Sub-three-nanometer lithography is compressing thermal tolerance windows for interposer substrates, forcing foundries to qualify glass as a silicon alternative despite decades of monocrystalline dominance.
Growth Catalysts
- Advanced packaging architectures:High-performance computing clusters in Taiwan, South Korea, and Japan are expanding substrate-level glass adoption for fan-out wafer-level formats.
- REACH and RoHS frameworks:European restrictions on heavy-metal dopants are accelerating alkali-free glass formulation R&D for consumer-facing electronics.
- EUV lithography qualification:Photomask blank replacement cycles create predictable demand pools as semiconductor fabrication node transitions intensify.
Market Restraints
- Energy input volatility:Fused silica melting operations face sustained electricity cost pressure from China's dual carbon goals tightening emissions controls.
- Qualified supplier concentration:Extreme ultraviolet collector optics remain captive to a narrow base of certified European and Japanese manufacturers.
- Coefficient of thermal expansion matching:Precision alignment with silicon at three parts per million per degree Celsius limits compositional flexibility and process yield.
Strategic Opportunities
- Panel size scaling:600-millimeter glass formats for fan-out packaging present white space for equipment and materials suppliers outside established silicon wafer supply chains.
- Japan's METI subsidies:Designated critical-material status for domestic substrate production creates incentive pools for supply-chain resilience investments.
- Hermetic packaging barriers:Convergence of photonics and quantum computing is opening new specification tiers for ultra-pure silicate encapsulation.
Industry Challenges
- Through-glass via processing:Laser drilling and metallization of sub-50-micron vias demands specialized equipment operator skills in short supply across fabrication clusters.
- Qualification timeline compression:Leading foundries require 18-to-24-month certification cycles for new interposer materials, delaying volume ramp timing.
- Total thickness variation control:Maintaining sub-micron flatness across 300-millimeter and larger formats strains precision polishing chemistry consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Glass Market |
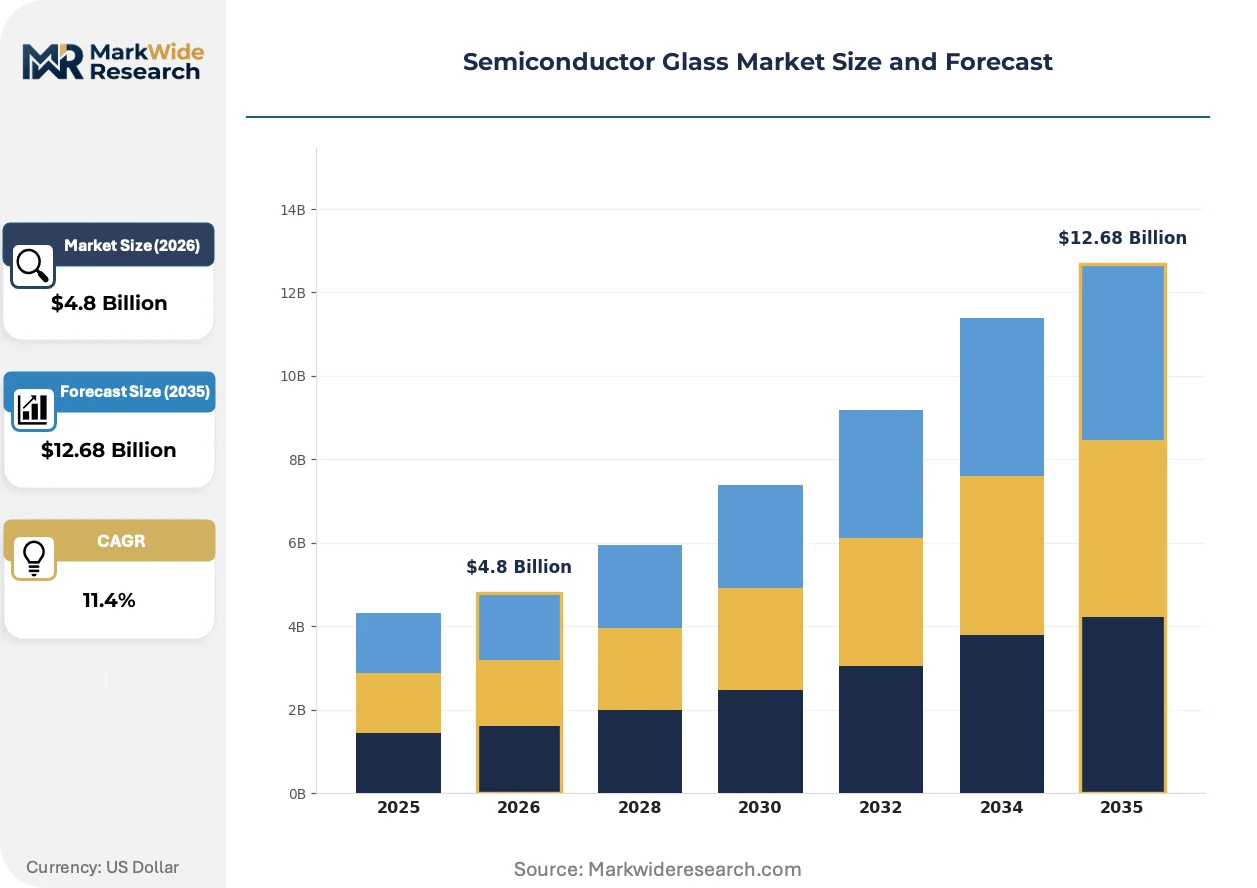
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Glass, Photomask, Optical Glass, Specialty Glass End Use: Consumer Electronics, Telecommunications, Automotive Components, Aerospace Applications Technology: Thin Film, Anisotropic Conductive Film, Laser Direct Structuring, Electron Beam Lithography Size: Small-Sized, Medium-Sized, Large-Sized, Ultra-Large |
| Companies Covered | Nippon Electric Glass Co. Ltd., Shin-Etsu Chemical Co. Ltd., Corning Incorporated, Compagnie de Saint-Gobain, Tosoh Corporation, AGC Inc., Hoya Corporation, Heraeus Holding GmbH, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Glass Market Strategic Shifts & Innovations
Glass substrate virtualization is redrawing the boundary between semiconductor front-end and packaging processes, collapsing traditional equipment procurement categories.
Fusion-draw borosilicate manufacturing is virtualizing the wafer supply chain by enabling direct production of sub-100-micron substrates without mechanical grinding. Memory and logic foundries in Taiwan and South Korea are piloting these wafers for 2.5D interposer stacks. The technology is virtualizing capital allocation decisions between silicon and glass substrate lines.
China's NMPA-aligned environmental standards are tightening particulate emissions thresholds for synthetic quartz production facilities. MEE enforcement actions have idled capacity at several inland melting operations. Specialty glass suppliers are responding with closed-loop scrubber retrofits and geographic concentration toward coastal industrial zones with superior air-quality infrastructure.
Long-term supply agreements are displacing spot-market purchasing for photomask blank procurement. Leading semiconductor equipment manufacturers in Japan and Germany are locking three-to-five-year volume commitments directly with alkali-free glass melters. This pattern is most visible in the extreme ultraviolet optics segment, where qualification costs create bilateral dependency between mask shops and substrate vendors.
Semiconductor Glass Market Segmentation
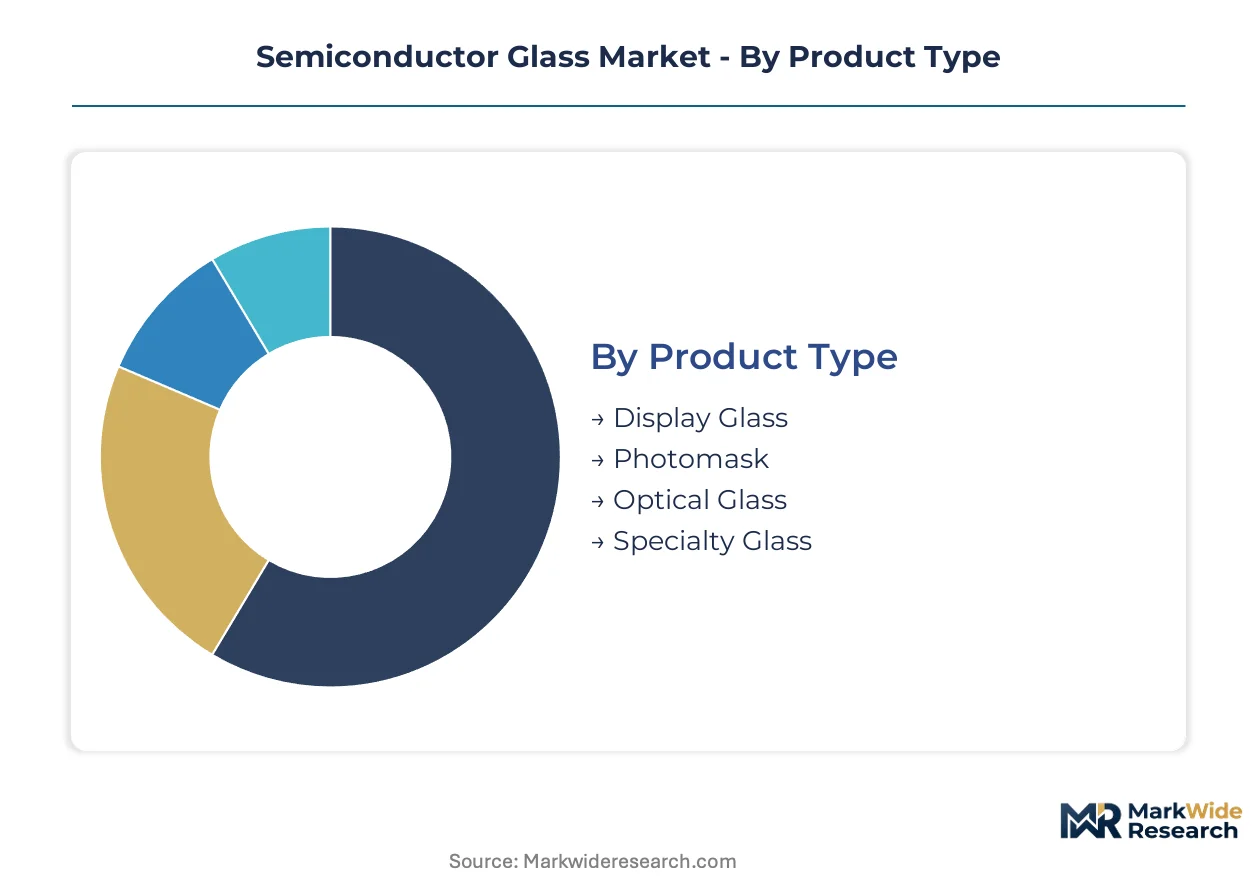
Semiconductor glass procurement cycles vary dramatically by application, with photomask blanks turning on predictable replacement schedules while advanced packaging formats demand rapid qualification of new substrate geometries. Understanding these divergent velocity profiles helps suppliers align inventory and R&D bets against actual revenue timing.
Product Type:
Photomask substrates command the longest replacement cycles tied to node transitions, while specialty glass for fan-out packaging refreshes on compressed timelines driven by panel-size roadmaps.
- Photomask:EUV-grade fused silica blanks require atomic-level defect control below 50 nanometers for high-NA lithography systems. Taiwan and South Korea mask shops lock in three-to-five-year supply agreements with alkali-free glass melters to amortize steep qualification costs.
- Specialty Glass:Borosilicate and alkali-free formulations for fan-out wafer-level packaging scale toward 600-millimeter panel formats. Corning and SCHOTT AG are trialing fusion-draw substrates below 100 microns for 2.5D interposer stacks in Hsinchu and Yongin.
- Display Glass:Thermal expansion matched to silicon enables direct bonding for microLED backplanes.
- Optical Glass:Extreme ultraviolet collector optics concentrate among certified Japanese and European suppliers with decades of ion-beam polishing heritage.
Photomask anchors the volume base while specialty glass gains share at the steepest rate.
End Use:
Procurement scale and specification stringency diverge sharply between high-volume consumer devices and qualification-heavy aerospace applications.
- Consumer Electronics:Smartphones and wearables drive alkali-free glass demand for hermetic MEMS encapsulation. REACH and RoHS frameworks restrict heavy-metal dopants in compositions bound for EU consumer markets.
- Telecommunications:5G baseband and optical transceiver modules require ultra-low-loss glass for high-frequency signal integrity. Japan's METI subsidizes domestic substrate supply to reduce import dependency for critical 6G precursor materials.
- Automotive Components:LiDAR and camera module substrates must survive thermal cycling from minus 40 to 150 degrees Celsius.
- Aerospace Applications:Radiation-hardened optical systems for satellite payloads demand synthetic quartz with cosmic-ray stability certification.
Consumer electronics absorbs the highest absolute volume while telecommunications climbs fastest on infrastructure buildouts.
Technology:
Process maturity spans decades-old thin-film deposition against emerging laser-based patterning still seeking equipment standardization.
- Electron Beam Lithography:Maskless direct-write systems pattern photomask blanks and prototype wafers without optical proximity correction overhead. Leading Japanese equipment manufacturers integrate proprietary glass-stage metrology to sub-nanometer precision.
- Laser Direct Structuring:Femtosecond pulses drill through-glass vias below 50 microns for 2.5D interposers. Equipment operator shortages in Taichung and Suwon constrain throughput scaling for fan-out packaging lines.
- Thin Film:Sputtered and CVD dielectric layers on glass substrates enable passive component integration.
- Anisotropic Conductive Film:Z-axis conductive adhesives bond driver ICs to display glass with fine-pitch alignment.
Thin film retains the broadest installed base while laser direct structuring expands most quickly on advanced packaging adoption.
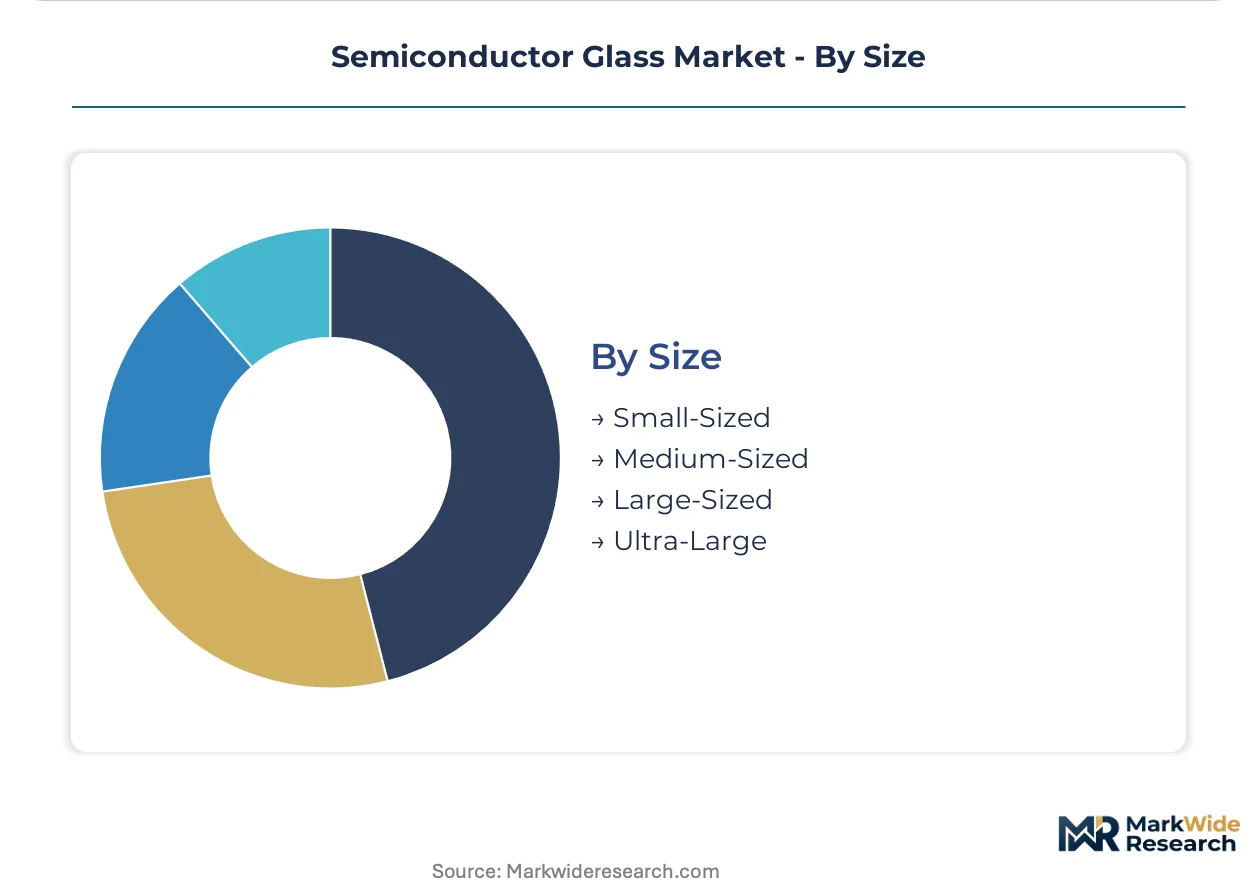
Size:
Capital intensity and yield economics shift nonlinearly as formats cross 300-millimeter thresholds where silicon wafer infrastructure no longer transfers.
- Large-Sized:300-millimeter and 510-millimeter square panels dominate photomask blank and fan-out wafer-level packaging production. Taiwan foundries are qualifying 600-millimeter glass formats that exceed legacy silicon wafer handling equipment limits.
- Ultra-Large:Gen 8.5 and larger display glass substrates enable microLED mass transfer at television scale. China's NMPA-aligned emissions standards concentrate new melting capacity in coastal zones with superior air-quality infrastructure.
- Medium-Sized:200-millimeter formats serve legacy MEMS and power device packaging.
- Small-Sized:Specialty optical components and quantum computing encapsulation use sub-100-millimeter precision blanks.
Large-sized formats anchor current revenue while ultra-large climbs fastest on display technology roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in semiconductor glass tilt heavily toward East Asian fabrication clusters, with Taiwan, South Korea, and Japan running structural deficits in raw substrate supply against concentrated European and Japanese melting capacity.
United States
Domestic demand from Intel's Arizona and Ohio fabs drives fused silica imports for EUV photomask blanks. EPA air-quality standards and OSHA silica-exposure limits raise capital costs for local melting operations. The Phoenix-Tucson corridor hosts emerging substrate qualification labs serving domestic logic foundries.
China
Dual carbon goals and NMPA-aligned environmental standards tighten emissions controls on synthetic quartz production. MEE enforcement actions have idled capacity at several inland melting operations. Coastal zones in Jiangsu and Zhejiang concentrate new closed-loop scrubber retrofits for specialty glass output.
Japan
METI subsidies for designated critical-material status protect domestic substrate supply-chain resilience. JIS standards govern alkali-free formulations for through-glass via processing. The Kyushu-Tokyo corridor anchors synthetic quartz production with precision polishing heritage.
South Korea
Memory and logic foundries in Yongin and Pyeongtaek pilot fusion-draw borosilicate substrates below 100 microns. MFDS-aligned import inspections delay qualification timelines for non-domestic suppliers. The Suwon cluster strains for equipment operators skilled in laser direct structuring.
Germany
REACH and RoHS frameworks restrict heavy-metal dopants in glass compositions bound for consumer-facing electronics. ECHA registration requirements extend lead times for novel alkali-free formulations. Mainz and Jena concentrate ion-beam polishing expertise for extreme ultraviolet collector optics.
Semiconductor Glass Market Key Industry Players
On the supply side, the industry is bifurcated between a narrow tier of qualified EUV optics suppliers and a broader base of packaging substrate specialists. Consolidation concentrates around photomask blank certification, while fragmentation persists in fan-out wafer-level formats. Two archetypes dominate: fusion-draw scale players and precision-polishing specialists. Competitive moves center on three-to-five-year volume commitments and geographic concentration toward coastal industrial zones with superior air-quality infrastructure.
Among Japanese specialists, Nippon Electric Glass Co. Ltd. and Shin-Etsu Chemical Co. Ltd. occupy positions within the synthetic quartz and alkali-free formulation tiers, while Corning Incorporated anchors the fusion-draw scale archetype. SCHOTT AG exemplifies the European precision-polishing specialist model. These three represent the geographic and technological poles around which merchant supply strategies organize.
| Leading Market Players |
|---|
| Nippon Electric Glass Co. Ltd. |
| Shin-Etsu Chemical Co. Ltd. |
| Corning Incorporated |
| Compagnie de Saint-Gobain |
| Tosoh Corporation |
| AGC Inc. |
| Hoya Corporation |
| Heraeus Holding GmbH |
| SCHOTT AG |
| Others |
Cost & Logistics Intelligence
Idled capacity at inland Chinese melting operations signals tightening supply discipline, forcing alkali-free glass melters toward coastal zones where superior air-quality infrastructure supports premium pricing posture against synthetic quartz alternatives.
Pricing Analysis
EUV-grade photomask blanks command three-to-five-year contract premiums against prior-generation DUV substrates, while fusion-draw borosilicate trials for 2.5D interposers price at experimental tiers pending foundry qualification. Long-term offtake agreements dominate procurement, with price differentiation resting on ion-beam polishing certification and atomic-level defect control thresholds. Cost compression in fan-out packaging substrates intensifies as panel formats scale toward 600 millimeters. Memory foundries in South Korea exhibit highest price sensitivity due to cyclical margin pressure, while EUV mask shops absorb premium tiers given qualification cost amortization.
Supply Chain Analysis
Corning, SCHOTT AG, and Shin-Etsu Chemical concentrate captive melting and precision polishing capacity across Taiwan, Germany, and Japan. Raw material flows draw from high-purity sand deposits in the US Southeast, synthetic quartz precursors from Japan's Kyushu corridor, and rare-earth dopants subject to China's export licensing. Single-source vulnerability concentrates in extreme ultraviolet collector optics where decades of ion-beam polishing heritage limit supplier substitution. Distribution runs through direct long-term agreements between mask shops and substrate vendors, bypassing merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass substrate virtualization collapses traditional front-end and packaging equipment categories, creating platform-economics inflection as fusion-draw manufacturing enables direct production of sub-100-micron formats without silicon wafer grinding infrastructure.
For Market Incumbents: Harden qualification-timeline advantages by locking three-to-five-year volume commitments with leading mask shops before emerging fusion-draw specialists achieve EUV-grade defect thresholds. Prioritize backward integration into synthetic quartz precursors to offset China's dual carbon emissions controls on inland melting capacity. Defend against SCHOTT AG and Corning's coastal concentration by securing JIS-certified alkali-free formulation capacity in Japan's METI-subsidized corridors. For New Entrants and Emerging Players: 600-millimeter fan-out wafer-level packaging formats in Taiwan and South Korea represent the most penetrable entry point, as legacy silicon wafer handling equipment reaches dimensional limits. Laser direct structuring equipment operator shortages in Taichung and Suwon create service-layer white space for specialized via-drilling contractors. Target qualification partnerships with memory foundries piloting 2.5D interposer stacks, leveraging faster certification cycles versus logic foundry timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among photomask blank suppliers with EUV qualification heritage and replacement-cycle predictability tied to node transitions. Five-to-ten year viability favors precision-polishing specialists with ion-beam heritage over commodity fusion-draw scale players facing energy input volatility. Monitor foundry qualification announcements for 2.5D glass interposer volume ramps as inflection indicator for substrate demand migration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Mask shops in Taiwan lock three-to-five-year volume commitments with alkali-free glass melters to amortize EUV qualification costs. |
| Backward Integration | Shin-Etsu Chemical's captive synthetic quartz production insulates margin pressure from China's inland emissions enforcement. |
| Geographic Concentration | Coastal Jiangsu and Zhejiang zones attract closed-loop scrubber retrofits under NMPA-aligned environmental standards. |
| Capacity Expansion | 600-millimeter panel format trials in Hsinchu and Yongin exceed legacy silicon wafer equipment limits. |
| Joint Venture | Corning's fusion-draw expertise pairs with South Korean memory foundries for sub-100-micron interposer pilot lines. |
Research Approach
Cross-validation between trade customs data and foundry procurement disclosures anchors the qualitative findings across this analysis. Primary interviews with photomask blank procurement managers, fusion-draw plant engineers, EUV equipment metrology specialists, and alkali-free glass R&D directors combine with secondary validation from SEC filings, Japan's METI critical-material designations, and ECHA REACH registration databases. Bottom-up panel format adoption curves triangulate against top-down substrate demand forecasts.
Calibration against historical node transition timelines and photomask replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end-use application, processing technology, and substrate format size. CAGRs derive from equipment installation rates at leading foundries and qualification timeline compression patterns. Forecast inputs incorporate China's MEE enforcement intensity and Japan's METI subsidy disbursement trajectories.
Practitioners should monitor foundry qualification announcements, coastal melting capacity utilization, and EUV high-NA lithography deployment schedules for early signals of substrate material substitution velocity. Quarterly review of mask shop inventory builds, fusion-draw yield improvements, and NMPA enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Middle East Silicon Carbide (Sic) Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Zinc Oxide Nanoparticles Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Indium Market