
 Indium Market | 2026-2036
Indium Market Size, Share, and Industry Trends Forecast 2026-2036
Indium Market Outlook
Single-source dependency on Chinese zinc smelter byproduct output is decoupling as downstream buyers diversify procurement geography. Indium Corporation leverages its vertical integration from refined metal to solder paste formulations. Korea Zinc Co., Ltd. anchors Asia-Pacific supply through integrated zinc-lead smelting operations. Umicore competes on closed-loop recycling capabilities that reduce primary ore reliance.
Indium is a soft, malleable post-transition metal extracted primarily as a byproduct of zinc mining, with atomic number 49 and melting point of 156.6 degrees Celsius, serving as a critical input for transparent conductive oxides and low-melting-point alloys. Indium tin oxide dominates product type revenue due to irreplaceable optoelectronic performance in touchscreens and OLED panels. Semiconductor applications represent the fastest-growing application segment as indium phosphide and indium antimonide compounds enable high-frequency and infrared devices. Electronics end users command the largest volume share, though energy sector demand for copper indium gallium selenide photovoltaic cells is expanding fastest.
China's MIIT enforces GB standards on rare metal processing emissions that elevate compliance costs for indium refiners. REACH registration requirements in Europe restrict unregistered indium compound imports, while the EU Green Deal accelerates recycling mandates. Korea's MFDS and Japan's METI coordinate strategic stockpiling protocols that buffer supply disruptions. Stakeholders must monitor substitution progress in transparent electrode materials and assess captive recycling investments before supply tightens structurally.
Market Dynamics
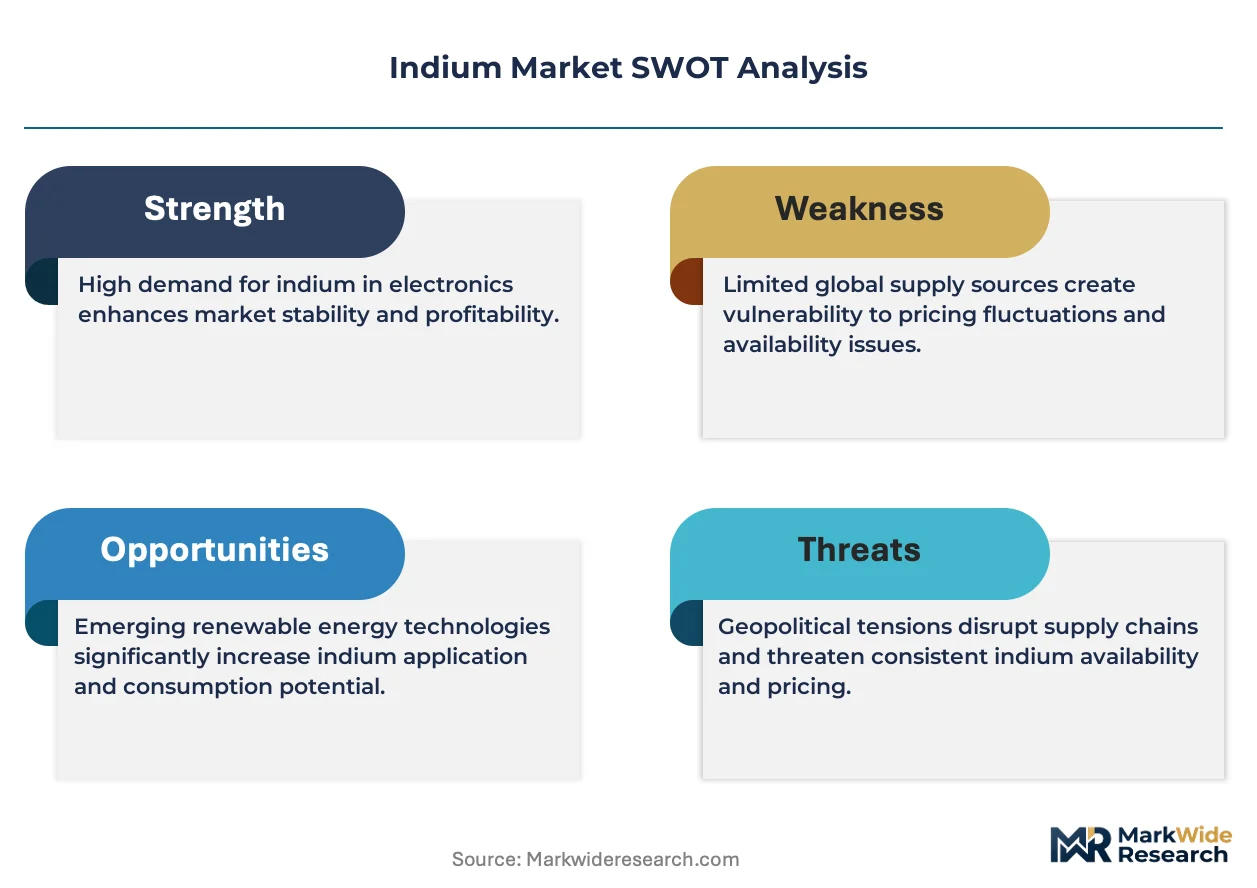
The indium market faces structural pressure from China's dual carbon goals and GB standards tightening rare earth processing emissions, forcing refiners to absorb elevated compliance costs or exit production entirely.
Growth Catalysts
- Flat-panel display procurement:Indium tin oxide coatings remain irreplaceable for optoelectronic performance in OLED panels and touchscreens, locking in electronics sector demand from East Asian manufacturing clusters.
- REACH registration:The European regulation restricts unregistered indium compound imports, creating preferential access for compliant refiners who have completed substance dossiers.
- Semiconductor compound demand:Indium phosphide and indium antimonide enable high-frequency and infrared devices, pulling material into defense and telecommunications applications.
Market Restraints
- Zinc smelter byproduct dependency:Indium extraction concentrates at zinc-lead smelting operations, binding supply to base metal mining economics and limiting primary production flexibility.
- Substitution threat from silver nanowires:Alternative transparent conductive materials are penetrating flexible display applications, compressing long-term indium tin oxide volume assumptions.
- MIIT emissions enforcement:China's Ministry of Industry and Information Technology standards on rare metal processing are elevating capital requirements for refinery environmental controls.
Strategic Opportunities
- Copper indium gallium selenide photovoltaics:Thin-film solar cell manufacturing is expanding fastest in the energy sector, creating new indium demand outside traditional electronics.
- Closed-loop recycling mandates:The EU Green Deal accelerates requirements for recovering indium from manufacturing scrap and end-of-life displays, favoring refiners with hydrometallurgical recycling capabilities.
- Strategic stockpiling coordination:Korea's MFDS and Japan's METI protocols buffer supply disruptions, creating offtake certainty for qualified suppliers.
Industry Challenges
- Refinery metallurgical expertise scarcity:Indium purification requires specialized solvent extraction and electrowinning knowledge that is concentrated among aging technical workforces in China and South Korea.
- Multi-jurisdictional compliance synchronization:Exporters must simultaneously satisfy REACH registration, MIIT emissions standards, and Korea's MFDS documentation requirements, extending certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indium Market |
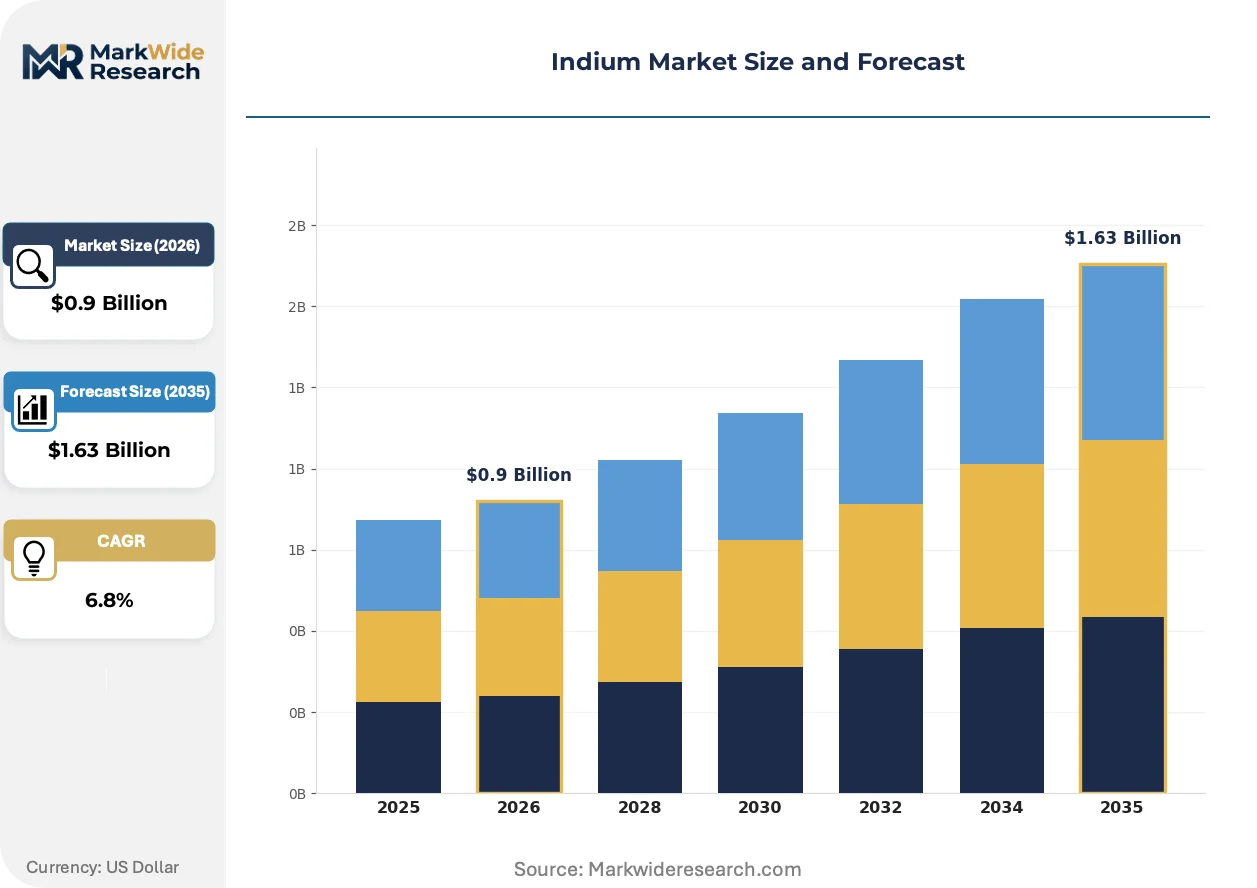
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.63 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indium Metal, Indium Compounds, Indium Oxide, Indium Tin Oxide Application: Displays, Solders, Coatings, Semiconductors End User: Electronics, Aerospace, Automotive, Energy Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Indium Corporation, Umicore, Teck Resources Limited, Nyrstar, Avalon Advanced Materials Inc., Nippon Rare Metal, Inc., ESPI Metals, Inc., Lipmann Walton & Co Ltd, Korea Zinc Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indium Market Strategic Shifts
Transparent electrode material science and supply chain geography are actively restructuring competitive positioning in indium procurement, with recycling technology and regulatory compliance emerging as differentiating capabilities.
Silver nanowire transparent conductors are integrating into flexible display manufacturing as a complementary layer to indium tin oxide, reducing sheet resistance for foldable smartphone panels. Samsung Display and LG Display are adopting hybrid architectures that preserve indium tin oxide for rigid substrates while deploying silver nanowires for bendable segments. This integration is compressing pure-play indium tin oxide volume growth while sustaining total transparent conductor market expansion.
REACH authorization requirements are tightening supply chain documentation burdens for indium compound importers into the European Union, with ECHA evaluating additional substance restrictions under SVHC candidate listing. Refiners without completed registration dossiers face market exclusion, concentrating European supply among Umicore and a handful of Asian exporters with compliance infrastructure. Specialty chemical distributors are responding by consolidating indium compound sourcing through registered channels, raising effective procurement costs for smaller European manufacturers.
Electronics assemblers are consolidating indium procurement through direct refinery relationships, bypassing traditional metal traders and merchant banks that historically intermediated spot transactions. Foxconn and Luxshare Precision are negotiating annual volume contracts with Korea Zinc and Chinese state-owned smelters, securing price stability and origin documentation for customer ESG reporting. This disintermediation is most visible in China's Pearl River Delta manufacturing corridor, where display panel makers now source over half of indium requirements through direct agreements rather than exchange-linked purchases.
Indium Market Segmentation
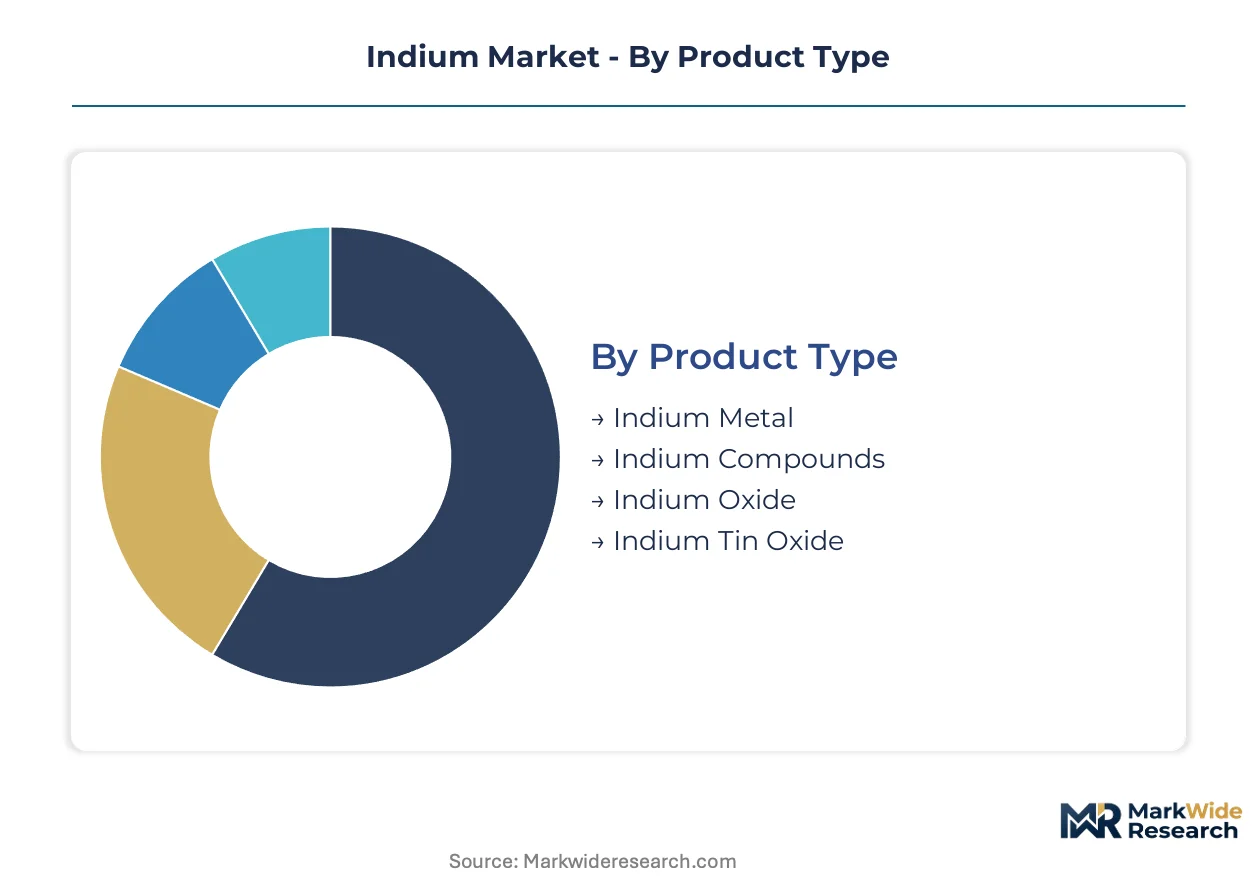
Indium procurement patterns diverge sharply across product specifications and end-use certifications. REACH registration requirements for compounds, MIIT emissions compliance for oxides, and customer ESG documentation for metals create distinct regulatory burdens per segment that reshape supplier selection criteria.
Product Type:
REACH dossier completion and MIIT GB standard certification burden concentrates most heavily on oxide and compound segments, while metal purity specifications dominate customer qualification protocols.
- Indium Metal:Refined ingots and shot meeting 99.99% purity specifications serve as feedstock for solder paste formulations and semiconductor compound synthesis. Electronics assemblers in Shenzhen and Suzhou procurement clusters demand origin documentation for Scope 3 emissions reporting, tightening smelter qualification requirements.
- Indium Tin Oxide:Sputtering targets and nanopowders combine indium oxide with tin oxide in 90:10 weight ratios to achieve sheet resistance below 10 ohms per square for display applications. Samsung Display and LG Display annual volume contracts lock in Korean and Chinese refinery capacity, constraining spot market availability for smaller panel makers.
- Indium Compounds:Indium phosphide and indium antimonide crystals enable infrared detectors and high-frequency telecommunications devices.
- Indium Oxide:Ceramic-grade powders feed transparent conductive coating deposition processes.
Leading the category by volume: Indium Tin Oxide. Expanding most quickly: Indium Compounds.
Application:
Application segments separate by thermal processing intensity and deposition technology, with vacuum sputtering dominating display coatings versus wet chemistry for solder formulations.
- Displays:Thin-film transistor liquid crystal and organic light-emitting diode panels consume sputtering targets in magnetron deposition chambers operating at 10^-6 Torr vacuum levels. Guangzhou and Hefei manufacturing corridors concentrate procurement, with Foxconn and BOE Technology Group negotiating multi-year supply agreements.
- Semiconductors:Indium phosphide substrates for 5G radio frequency amplifiers and indium antimonide focal plane arrays for thermal imaging drive compound semiconductor foundry demand. Defense procurement through Korea's DAPA and Japan's MOD buffers commercial cycle volatility.
- Solders:Low-melting-point indium-tin and indium-silver alloys join temperature-sensitive components without thermal damage.
- Coatings:Antireflective and conductive layers protect aerospace optics and solar thermal collectors.
Dominating volume: Displays. Steepest expansion trajectory: Semiconductors.
End User:
End-user segments stratify by specification stringency, with aerospace and automotive demanding lot traceability and failure analysis protocols absent from commodity electronics procurement.
- Electronics:Display panel manufacturers, printed circuit board assemblers, and semiconductor packaging operations concentrate demand in China's Pearl River Delta, South Korea's Gyeonggi Province, and Japan's Kyushu region. Direct refinery relationships now exceed 50% of procurement volume, displacing traditional metal traders.
- Energy:Copper indium gallium selenide photovoltaic module manufacturers in Germany and South Korea pull material into thin-film solar cell absorber layers. EU Green Deal recycling mandates favor refiners with closed-loop hydrometallurgical recovery capabilities.
- Aerospace:Infrared countermeasure systems and satellite thermal control coatings require indium alloys with full material pedigree documentation.
- Automotive:Power module solders and LED headlamp thermal interface materials penetrate electric vehicle manufacturing.
Highest volume concentration: Electronics. Gaining share fastest: Energy.
Distribution Channel:
Channel selection correlates with purchase scale and documentation requirements, with direct sales capturing annual contract volumes and distributors serving spot needs.
- Direct Sales:Korea Zinc, Indium Corporation, and Umicore negotiate annual take-or-pay contracts with display panel makers and semiconductor foundries. These agreements specify origin smelter, purity certification, and ESG compliance documentation required for customer sustainability reporting.
- Distributors:Specialty chemical distributors including Univar Solutions and Brenntag consolidate indium compound sourcing for European manufacturers lacking REACH registration infrastructure, extending certification timelines and raising effective procurement costs.
- Online Retail:Small-lot metal sales serve research institutions and prototype workshops.
- Wholesalers:Regional metal traders intermediate spot transactions for uncontracted requirements.
Channel concentration by volume: Direct Sales. Expanding service scope: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc smelter byproduct extraction in China, South Korea, and Japan anchors indium supply geography. Electronics manufacturing clusters in these markets consume the majority of refined output for transparent conductive oxide deposition.
China
Flat-panel display manufacturing in Guangzhou and Hefei drives indium tin oxide procurement from Korea Zinc and domestic state-owned smelters. MIIT enforces GB standards on rare metal processing emissions that elevate refinery compliance costs. The Pearl River Delta manufacturing corridor sources over half of indium requirements through direct smelter agreements rather than spot market purchases.
South Korea
Samsung Display and LG Display annual volume contracts lock in Korean refinery capacity for sputtering target supply. MFDS coordinates strategic stockpiling protocols that buffer supply disruptions for qualified suppliers. The Gyeonggi Province electronics cluster concentrates semiconductor foundry demand for indium phosphide and indium antimonide compounds.
Japan
Indium phosphide substrates for 5G radio frequency amplifiers pull material into compound semiconductor manufacturing. METI protocols align with Korea's MFDS on strategic reserve coordination. The Kyushu region hosts specialized refiners serving defense procurement through DAPA-linked supply chains for infrared detector applications.
Germany
Copper indium gallium selenide photovoltaic module manufacturers pull material into thin-film solar cell absorber layers. REACH registration requirements restrict unregistered indium compound imports, creating market exclusion for non-compliant refiners. The ECHA SVHC candidate listing process evaluates additional substance restrictions that extend certification timelines for specialty chemical distributors.
United States
Defense procurement for infrared countermeasure systems and satellite thermal control coatings requires indium alloys with full material pedigree documentation. EPA regulations on hazardous waste from metal refining operations affect secondary recovery economics. Research institutions and prototype workshops in the Mountain West and Northeast Corridor source small-lot metal through specialty distributors.
Indium Market Competitive Environment
Backward integration into zinc-lead smelting operations dominates the current landscape as refiners secure captive byproduct feedstock. The vendor base concentrates around integrated base metal producers and specialty metal refiners with hydrometallurgical expertise. Three archetypes define competitive positioning: zinc smelter-integrated refiners, independent specialty metal processors, and closed-loop recycling operators. Geographic expansion through direct refinery relationships and portfolio diversification into compound semiconductor materials represent the dominant competitive moves.
Among zinc smelter-integrated refiners, Korea Zinc Co., Ltd. and Teck Resources Limited exemplify the feedstock-secured archetype that anchors Asia-Pacific and North American supply respectively. Indium Corporation occupies a position within the specialty processor tier, representing independent refining and downstream formulation capabilities. Umicore sits within the closed-loop recycling operator archetype, exemplifying European compliance infrastructure that satisfies REACH registration and EU Green Deal mandates.
| Leading Market Players |
|---|
| Indium Corporation |
| Umicore |
| Teck Resources Limited |
| Nyrstar |
| Avalon Advanced Materials Inc. |
| Nippon Rare Metal, Inc. |
| ESPI Metals, Inc. |
| Lipmann Walton & Co Ltd |
| Korea Zinc Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
State-owned smelter networks in China anchor upstream supply concentration, binding pricing discipline to zinc-lead mining economics and MIIT emissions compliance costs that refiners either absorb or pass downstream.
Pricing Analysis
Certification-bundled contracts dominate premium tier transactions, with REACH-registered indium compounds commanding price premiums over unregistered alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ESG-documented direct sales from spot market metal. Cost compression in standard-grade metal is intensifying because electronics assemblers consolidate procurement through annual volume agreements. Display panel manufacturers exhibit lowest price sensitivity due to irreplaceable optoelectronic performance requirements, while research institutions face highest sensitivity in small-lot purchases.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Samsung Display and LG Display, bypassing traditional metal traders that historically intermediated spot transactions. Supply concentrates in China, South Korea, and Japan where zinc-lead smelting operations feed captive byproduct extraction. Indium purification draws from specialized solvent extraction and electrowinning expertise concentrated among aging technical workforces. Single-source vulnerability to Chinese zinc smelter output is decoupling as downstream buyers diversify procurement geography. Distribution runs through direct refinery relationships for contracted volumes and specialty chemical distributors for spot compound needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The indium market is a vertical-integration race where captive zinc-lead smelting feedstock determines supply security and margin capture.
For Market Incumbents: Lock in multi-year offtake agreements with Korea Zinc and Chinese state-owned smelters before stockpiling protocols tighten qualified supplier pools. Secure backward integration into zinc-lead mining operations to reduce primary ore reliance. Invest in hydrometallurgical recycling capabilities to satisfy EU Green Deal mandates and offset substitution threats from silver nanowires in flexible displays. For New Entrants and Emerging Players: Begin with closed-loop recycling operations serving European photovoltaic manufacturers facing REACH registration barriers. Target copper indium gallium selenide thin-film solar cell supply chains in Germany and South Korea where demand expands fastest outside traditional electronics. Partner with specialty chemical distributors to bridge compliance infrastructure gaps for smaller European manufacturers. For Investors and Strategic Acquirers: Distressed-cycle entries favor hydrometallurgical recycling specialists in Germany with completed REACH dossiers and EU Green Deal alignment. Long-term viability hinges on securing captive feedstock streams or recycling technology that reduces primary ore dependence. Watch substitution progress in transparent electrode materials as the inflection indicator for indium tin oxide volume assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc-Lead Smelting | Captive byproduct feedstock secures supply independence from base metal mining economics. |
| Hydrometallurgical Recycling Capacity Buildout | EU Green Deal mandates favor refiners recovering indium from manufacturing scrap and end-of-life displays. |
| REACH Registration Dossier Completion | Compliant refiners gain preferential access to European specialty chemical distribution channels. |
| Direct Refinery Relationship Consolidation | Electronics assemblers bypass traders to secure origin documentation for Scope 3 emissions reporting. |
| Indium Phosphide Compound Semiconductor Investment | 5G radio frequency amplifier demand pulls material into defense and telecommunications applications. |
Study Parameters
Independent corroboration across primary interviews with zinc smelter operations managers, indium refinery technical directors, display panel procurement leads, and specialty chemical distribution executives underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC 10-K filings of integrated base metal producers, MIIT emissions standard documentation, and ECHA REACH registration databases. Bottom-up segmentation modeling triangulates against top-down industry association estimates from regional zinc and indium trade bodies.
Rate-of-change decomposition separates volume drivers across product type, application technology, end-user industry, and regional regulatory cluster dimensions. CAGRs derive from historical production and consumption trajectories adjusted for substitution elasticity and regulatory compliance cost pass-through. Forecast inputs incorporate zinc-lead mining output correlations, display panel manufacturing capacity announcements, and photovoltaic deployment targets in thin-film solar segments.
Underlying measurement precision varies by segment; indium tin oxide display applications carry tighter precision than emerging semiconductor compound categories. Forecasts reflect assumptions about silver nanowire substitution timelines, MIIT emissions enforcement intensity, and strategic stockpiling coordination between Korea's MFDS and Japan's METI. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Chromium Oxide Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Indium Gallium Zinc Oxide Market