
 Semiconductor Glass Wafer Market | 2026-2036
Semiconductor Glass Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Glass Wafer Market Outlook
Multi-sourcing from fused silica suppliers is broadening as chipmakers reduce dependency on single-origins for advanced interposers. SCHOTT AG anchors European supply through its specialty glass melting expertise, while Corning Incorporated leverages its fusion draw process to dominate ultra-thin wafer segments. Ohara Corporation competes on tight thermal expansion tolerances for photonics applications.
A semiconductor glass wafer is a precision-substrate disc manufactured from fused silica, borosilicate, or soda-lime compositions, typically polished to nanometer-scale flatness for lithographic patterning and hermetic device sealing. Fused silica wafers command premium positioning due to near-zero thermal expansion coefficients essential for EUV lithography stages, whereas borosilicate variants sustain volume demand from cost-sensitive MEMS and sensor packaging. Photovoltaics and optoelectronics represent the fastest-growing application clusters as solar concentrator and LiDAR module builds accelerate.
REACH substance restrictions and RoHS hazardous material limits in Europe compel reformulation of glass compositions and traceability documentation, while FDA and EPA oversight in the United States shapes environmental compliance for manufacturing facilities. Japan's METI and PMDA frameworks influence export-grade quality protocols through JIS standards alignment. Stakeholders must monitor evolving dual-use export controls and substrate thickness roadmaps as sovereign chip programs reshape procurement geography.
Market Dynamics
Advanced packaging architectures for high-performance computing are redrawing procurement specifications across the semiconductor glass wafer value chain, compressing tolerance windows while multiplying substrate format requirements.
Growth Catalysts
- EUV Lithography Stages:Fused silica wafers with near-zero thermal expansion coefficients anchor next-generation photolithography tooling as chipmakers push below 3nm nodes.
- REACH Substance Restrictions:Tightened purity mandates across Europe are accelerating substrate qualification cycles and locking in premium glass suppliers with traceable supply chains.
- LiDAR Module Builds:Automotive and robotics sensor deployments are consuming borosilicate wafers for hermetic photonics packaging at volumes outpacing traditional MEMS applications.
Market Restraints
- Fused Silica Feedstock Volatility:High-purity quartz sand concentration in limited geographic deposits creates input cost instability for ultra-low expansion substrates.
- Single-Origin Melting Expertise:Advanced fusion draw and flame hydrolysis capabilities cluster with a handful of specialty glass manufacturers, amplifying supply disruption risk.
- Alternative Ceramic Substrates:Silicon carbide and aluminum nitride interposers are capturing thermal management applications where glass thermal conductivity falls short.
Strategic Opportunities
- Sovereign Chip Programs:Subsidized fab construction in the United States and Europe is creating captive demand for localized glass wafer finishing and metrology services.
- Solar Concentrator Photovoltaics:High-transmission borosilicate substrates for concentrated solar power receivers represent an underpenetrated demand vertical outside traditional semiconductor channels.
- Quantum Computing Packaging:Superconducting qubit modules require hermetic glass-to-metal seals with cryogenic stability specifications that command substantial pricing premiums.
Industry Challenges
- Precision Metrology Talent:Nanometer-scale flatness measurement and defect classification expertise resides with a shrinking cohort of specialized technicians across Taiwan, Japan, and Germany.
- Multi-Regulatory Certification:Simultaneous compliance with RoHS substance limits, REACH documentation, and JIS dimensional standards extends qualification timelines for new substrate formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Glass Wafer Market |
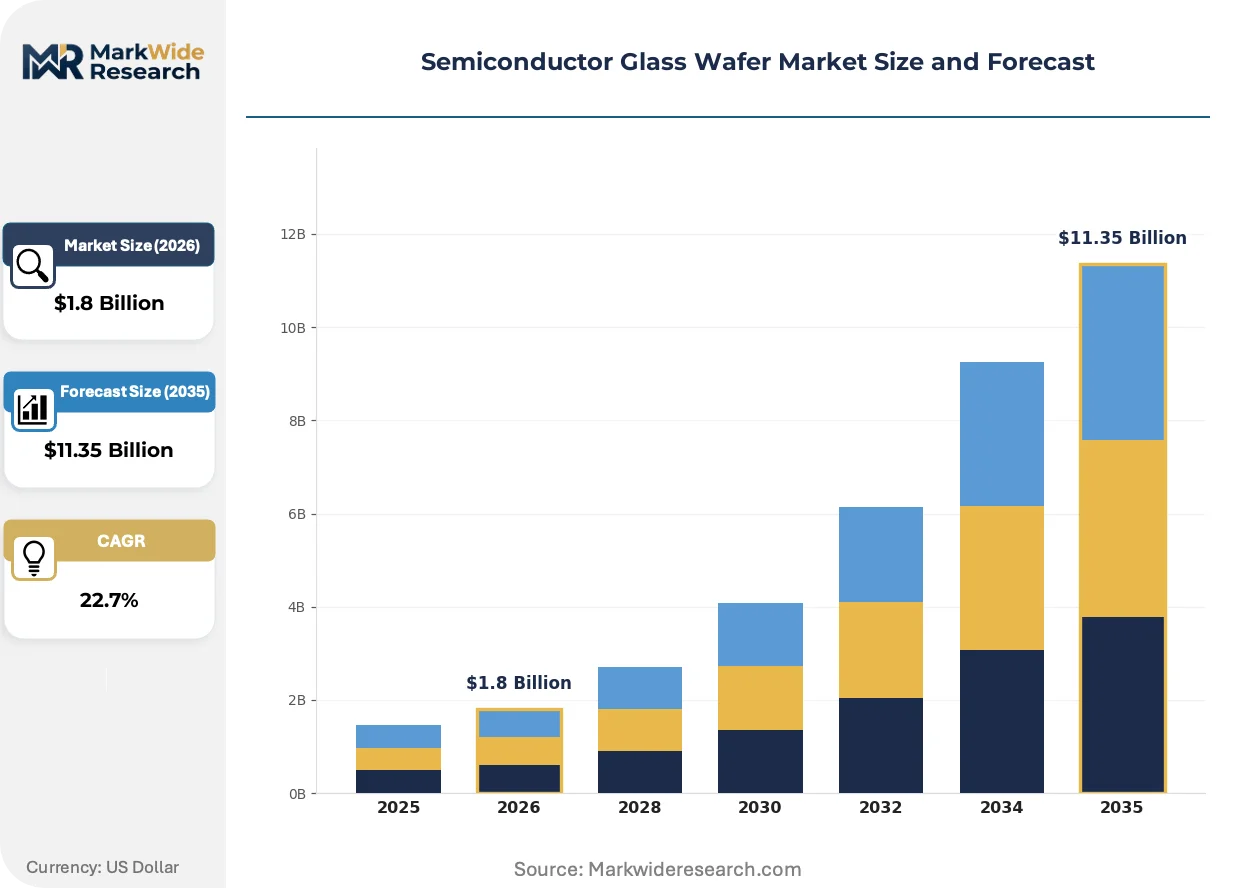
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fused Silica Wafer, Borosilicate Wafer, Float Glass Wafer, Other Application: Optoelectronics, Photovoltaics, Microelectronics, Displays End User: Semiconductor Manufacturers, Research Institutions, Electronic Device Producers, Automotive Suppliers Distribution Channel: Direct Sales, Online Marketplaces, Distributors, Others |
| Companies Covered | Nippon Electric Glass, Ohara Corporation, Corning Incorporated, Shin-Etsu Chemical, Plan Optik AG, AGC Inc., Hoya Corporation, SUMITA Optical Glass, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Glass Wafer Market Strategic Shifts
Substrate thinning roadmaps and hermetic sealing architectures are converging to redefine performance benchmarks, while regulatory documentation requirements and procurement consolidation reshape commercial relationships.
Ultra-thin glass wafers below 100 micrometers are expanding into 2.5D and 3D interposer stacks where through-glass via formation enables vertical signal routing. Memory fabricators in South Korea and logic foundries in Taiwan are qualifying these formats for high-bandwidth memory integration. The technology is expanding into package configurations previously dominated by organic laminates, compressing cost structures for advanced fan-out wafer-level packaging.
Europe's F-Gas Regulation and associated ECHA restrictions on fluorinated greenhouse gases are forcing reformulation of etching chemistries used in glass wafer surface preparation. Wet processing equipment suppliers must certify alternative cleaning protocols that eliminate sulfur hexafluoride and nitrogen trifluoride without compromising surface roughness specifications. Specialty glass processors with established green chemistry credentials are capturing qualification priority from automotive and medical device end-users.
Consolidated procurement through semiconductor equipment OEMs is displacing direct substrate purchasing by individual fabs. Applied Materials and Tokyo Electron now specify certified glass wafer formats for their lithography and inspection platforms, compressing vendor lists to pre-qualified suppliers. This pattern concentrates most acutely in Taiwan's foundry corridor where tool-standardization drives volume commitments toward single-source substrate partnerships.
Semiconductor Glass Wafer Market Segmentation
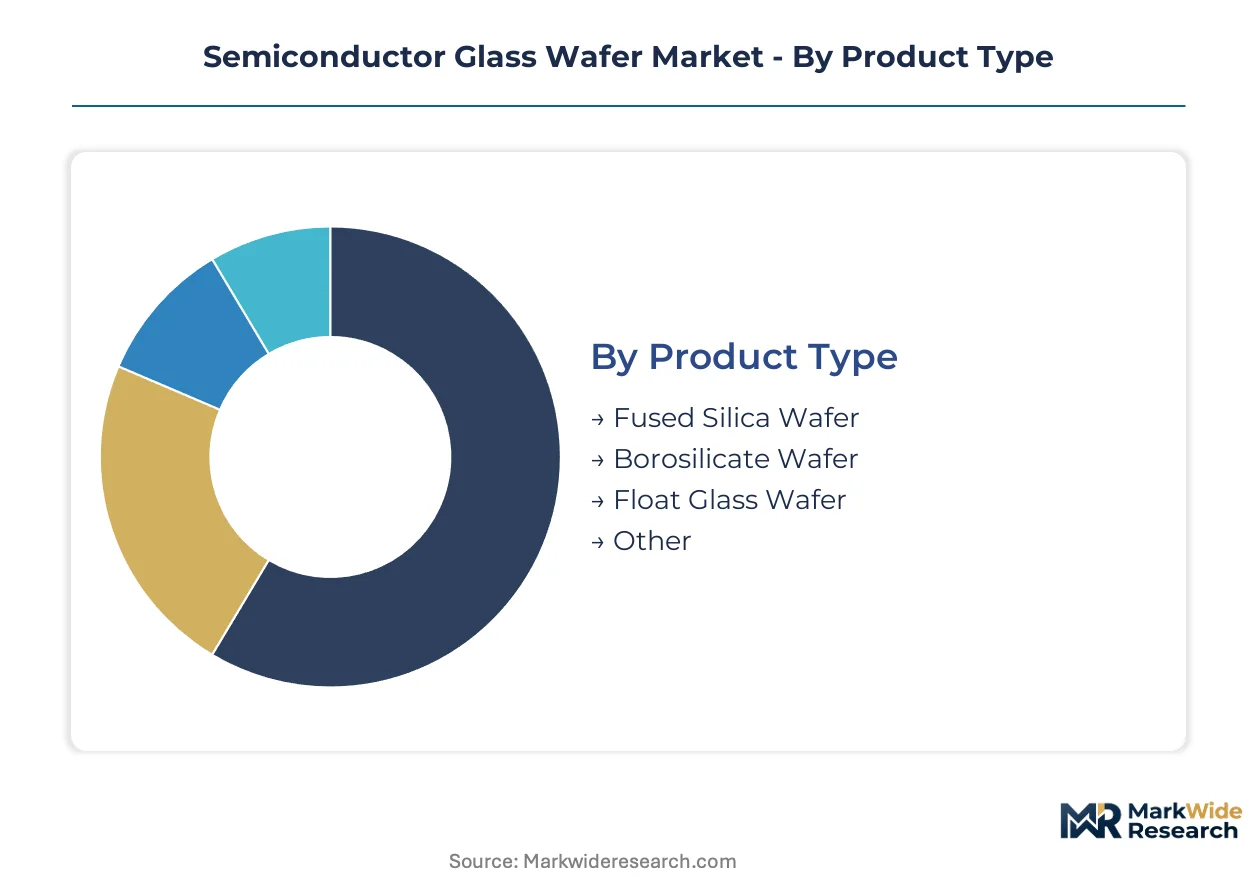
Semiconductor glass wafer procurement splits across material purity grades, device integration requirements, and supply chain access modes. Understanding these divisions reveals where specification premiums concentrate and which channels capture volume flows.
Product Type:
Material composition determines thermal stability, optical transmission, and chemical resistance profiles for downstream patterning and sealing operations.
- Fused Silica Wafer:Manufactured through flame hydrolysis of silicon tetrachloride, achieving near-zero thermal expansion coefficients essential for EUV lithography stages and precision photonics. Demand concentrates in Taiwan's foundry corridor where sub-3nm node tooling requires nanometer-scale dimensional stability under thermal cycling.
- Borosilicate Wafer:Lower coefficient formulations trade absolute thermal precision for cost efficiency in MEMS cavities and sensor packaging. South Korean memory fabricators consume substantial volumes for hermetic device sealing where moderate thermal budgets suffice.
- Float Glass Wafer:Soda-lime compositions processed through molten tin bath floating deliver economical substrates for display backplanes and non-critical microfluidics.
- Other:Specialty aluminosilicate and phosphate glass formulations address niche applications in radiation-hardened electronics and extreme UV transmission windows.
Mature deployment sits with borosilicate formats across established MEMS supply chains. Newer deployment is concentrated in fused silica as EUV lithography stages multiply.
Application:
End-use requirements reshape substrate thickness, surface roughness, and hermetic sealing specifications across divergent device architectures.
- Optoelectronics:LiDAR emitters, optical transceivers, and photonic integrated circuits demand ultra-low birefringence fused silica for polarization-maintaining signal paths. Automotive qualification timelines in Germany and Japan are compressing as Tier-1 suppliers integrate glass interposers into ADAS sensor modules.
- Photovoltaics:Concentrated solar power receivers and perovskite cell encapsulation consume high-transmission borosilicate with tailored iron content for UV stability. Deployment is climbing fastest in utility-scale installations across Spain and the southwestern United States.
- Microelectronics:Interposer substrates for 2.5D packaging and through-glass via formation enable vertical signal routing in high-bandwidth memory stacks.
- Displays:Flexible OLED encapsulation and micro-LED transfer carriers utilize chemically strengthened ultra-thin glass below 50 micrometers.
Established volume sits with microelectronics packaging. Photovoltaics is gaining share fastest as solar concentrator architectures proliferate.
End User:
Procurement scale and specification authority vary sharply across integrated device manufacturers, research entities, and subsystem suppliers.
- Semiconductor Manufacturers:Foundries and IDMs in Taiwan and South Korea drive fused silica volume through direct qualification of substrate formats for lithography and advanced packaging toolsets.
- Research Institutions:National laboratories and university cleanrooms in the United States, Germany, and Japan purchase small-lot specialty formats for process development and device prototyping.
- Electronic Device Producers:Consumer electronics OEMs specify borosilicate wafers for MEMS microphones, pressure sensors, and fingerprint modules through consolidated component supplier agreements.
- Automotive Suppliers:Tier-1 sensor and lighting module manufacturers in Germany and Japan are qualifying hermetic glass-to-metal seals for LiDAR and camera systems under extended temperature cycling protocols.
Direct procurement authority sits with semiconductor manufacturers. Research institutions are expanding most quickly as sovereign chip programs fund pilot line construction.
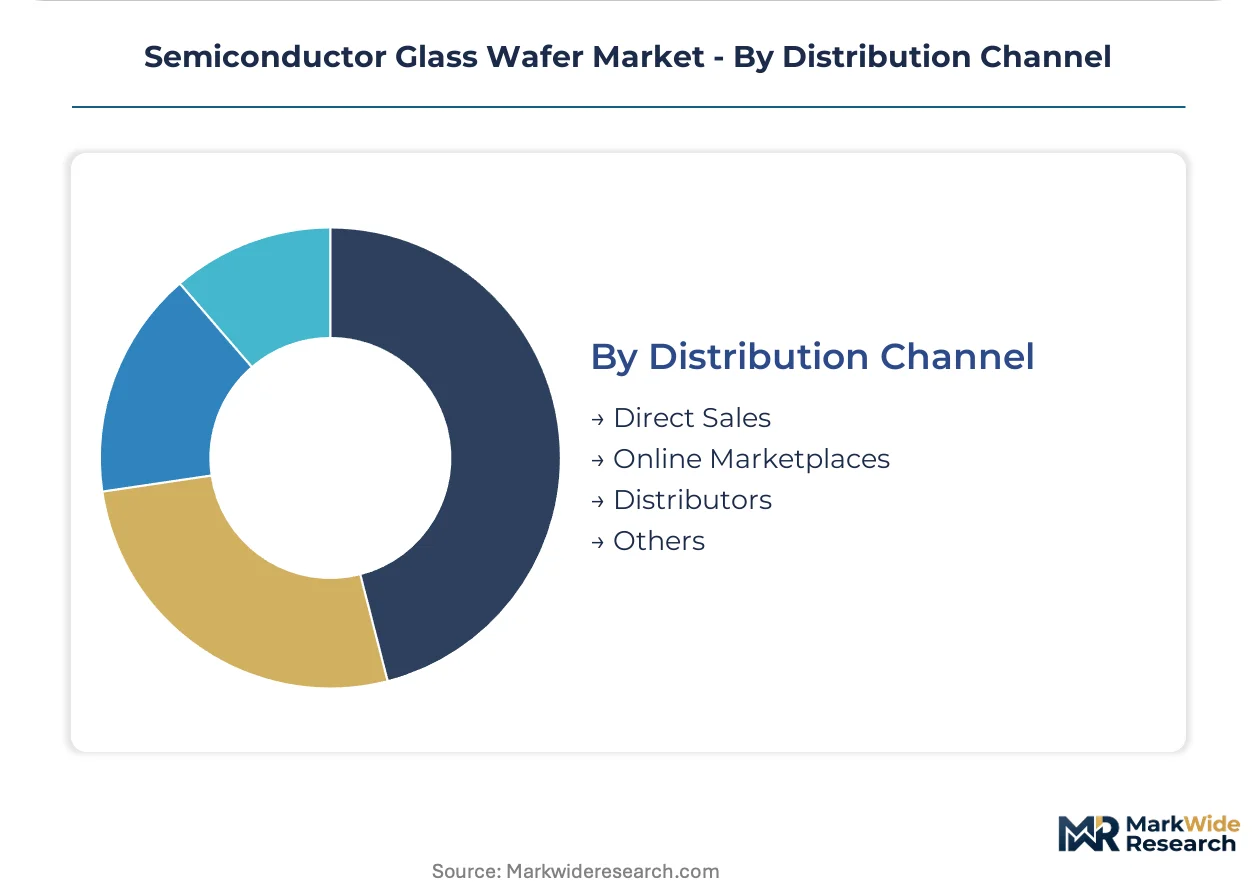
Distribution Channel:
Channel selection reflects lot size requirements, technical support needs, and qualification documentation burdens.
- Direct Sales:High-volume fused silica contracts with SCHOTT, Corning, and Ohara bypass intermediaries for lithography-grade material with full traceability documentation.
- Distributors:Regional specialty chemical and materials distributors in Europe and North America stock standard borosilicate formats for mid-tier MEMS fabricators.
- Online Marketplaces:Small-lot procurement platforms serve research institutions and startup device developers requiring rapid sample turnaround.
- Others:Consignment arrangements and vendor-managed inventory programs support just-in-time delivery for high-volume packaging houses.
Transaction concentration sits with direct sales for premium grades. Online marketplaces are expanding most quickly in research and prototyping segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor glass wafer procurement concentrates in three distinct manufacturing corridors where lithography tool deployment and advanced packaging capacity drive substrate specifications. Taiwan's foundry ecosystem and South Korea's memory fabrication belt absorb premium fused silica volumes, while Germany's precision optics cluster sustains specialty demand for metrology-grade formats.
Taiwan
TSMC and United Microelectronics drive fused silica consumption for EUV lithography stages and 2.5D interposer production. The island's Industrial Development Bureau subsidizes advanced packaging infrastructure under its semiconductor initiative. Hsinchu Science Park anchors the densest concentration of glass wafer finishing and metrology services outside Japan.
South Korea
Samsung Electronics and SK Hynix consume borosilicate wafers for hermetic memory packaging and emerging through-glass via architectures. MFDS alignment with JIS standards shapes export-grade quality protocols for photonics applications. Pyeongtaek and Yongin host the primary qualification centers for ultra-thin substrate formats in high-bandwidth memory stacks.
United States
Intel and GlobalFoundries are expanding domestic fused silica procurement for sub-3nm node tooling under CHIPS Act incentives. EPA oversight shapes environmental compliance for manufacturing facilities in Arizona and Oregon. Albany Nanotech Complex in New York serves as the primary R&D hub for next-generation lithography substrate development.
Germany
Zeiss and Trumpf anchor demand for precision fused silica in lithography optics and laser systems. REACH substance restrictions and RoHS hazardous material limits compel reformulation of glass compositions with full traceability documentation. Jena and Mainz host specialized melting operations for EUV-grade substrates with nanometer-scale flatness specifications.
Japan
Tokyo Electron and Canon drive qualification of ultra-low expansion substrates for inspection and lithography platforms. METI frameworks influence export-grade quality protocols through JIS standards alignment. Yamanashi and Shizuoka prefectures concentrate flame hydrolysis expertise for near-zero thermal expansion coefficient wafers.
Semiconductor Glass Wafer Market Competitive Environment
Capacity expansion dominates the current landscape as specialty glass manufacturers scale flame hydrolysis and fusion draw operations to match EUV lithography demand. The vendor base clusters around three tiers: integrated materials conglomerates with captive melting technology, precision optics specialists with nanometer-scale polishing expertise, and regional processors serving cost-sensitive MEMS applications. Strategic archetypes include technology licensors leveraging proprietary draw processes, vertically integrated suppliers controlling quartz sand-to-wafer value chains, and niche players concentrating on medical-grade hermetic sealing formats. Geographic expansion into subsidized US and European fab corridors and portfolio diversification into quantum computing substrates represent the dominant competitive moves.
Among German-based specialty glass producers, SCHOTT AG occupies a position exemplifying premium-tier fused silica supply with established green chemistry credentials. Corning Incorporated represents the scale-driven archetype, leveraging fusion draw process expertise across ultra-thin wafer segments. Ohara Corporation sits within the precision optics specialist tier, competing on tight thermal expansion tolerances for photonics applications in Japan and Taiwan.
| Leading Market Players |
|---|
| Nippon Electric Glass |
| Ohara Corporation |
| Corning Incorporated |
| Shin-Etsu Chemical |
| Plan Optik AG |
| AGC Inc. |
| Hoya Corporation |
| SUMITA Optical Glass |
| SCHOTT AG |
| Others |
Value Chain & Pricing Dynamics
Captive backward integration into high-purity quartz sand mining and flame hydrolysis melting anchors pricing power for premium fused silica suppliers, while outsourced finishing operations in Taiwan and Germany compress margins for mid-tier borosilicate processors serving cost-sensitive MEMS markets.
Pricing Analysis
Full metrology documentation and JIS certification bundling separate lithography-grade fused silica contracts from unbundled borosilicate spot purchases. Three-tier pricing structure across premium, standard, and economy levels reflects thermal expansion coefficient precision, REACH traceability depth, and volume commitment scale. Cost compression in standard-grade borosilicate intensifies as South Korean memory fabricators consolidate procurement through equipment OEM specifications. Research institutions exhibit highest price sensitivity due to small-lot sampling requirements, while EUV lithography toolmakers demonstrate lowest sensitivity given near-zero expansion coefficient mandates.
Supply Chain Analysis
Domestic-content mandates under the US CHIPS Act and EU Chips Act are reshaping sourcing patterns for finishing and metrology services, pressuring Asian-dominant supply chains to establish Arizona and Dresden processing nodes. Raw material concentration draws from Spruce Pine high-purity quartz deposits in North Carolina, Japanese flame hydrolysis expertise in Yamanashi, and German precision polishing capabilities in Jena. Single-source vulnerability clusters in flame hydrolysis reactor construction, where Tokyo Electron and Canon qualification protocols lock in vendor relationships. Distribution runs through direct sales for premium fused silica, regional distributors for standard borosilicate, and online marketplaces for research prototyping volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The semiconductor glass wafer market sits in a technology-transition phase as EUV lithography stages displace DUV immersion tooling, redefining substrate thermal stability specifications and supplier qualification hierarchies.
For Market Incumbents: Anticipate ceramic interposer substitution in high-thermal-flux packaging by deepening captive supply of ultra-low expansion fused silica and securing equipment OEM pre-qualification status. Priority capacity addition in Arizona and Saxony captures CHIPS Act and EU Chips Act subsidized demand. Defensive certification investment in green chemistry protocols addresses Europe's F-Gas Regulation compliance timelines. For New Entrants and Emerging Players: REACH documentation requirements in Europe open a window for specialty glass processors with established traceability systems to penetrate automotive LiDAR qualification pipelines. White-space targets concentrate in quantum computing hermetic sealing and solar concentrator photovoltaics outside traditional semiconductor channels. Go-to-market execution should leverage distributor relationships in European research clusters rather than direct fab sales. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by lithography equipment OEMs seeking captive substrate supply. Long-term viability favors vertically integrated processors controlling quartz sand-to-wafer value chains with equipment pre-qualification status. Watch for inflection in through-glass via adoption rates in high-bandwidth memory stacks as signal for format transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Flame Hydrolysis Capacity Expansion | Captive reactor construction in Arizona and Dresden secures CHIPS Act-aligned supply proximity to Intel and GlobalFoundries. |
| Green Chemistry Certification | ECHA-compliant etching protocols without sulfur hexafluoride capture automotive and medical device qualification priority from European Tier-1 suppliers. |
| Equipment OEM Pre-Qualification | Tokyo Electron and Applied Materials substrate specification locks in volume commitments from Taiwan's foundry corridor. |
| Ultra-Thin Wafer Process Development | Sub-100 micrometer through-glass via formation enables 2.5D interposer penetration previously dominated by organic laminates. |
| Quantum Computing Substrate Qualification | Cryogenic hermetic sealing specifications for superconducting qubit modules command substantial pricing premiums outside traditional semiconductor demand cycles. |
Study Parameters
Independent corroboration across primary interviews with lithography tool engineers, advanced packaging procurement leads, and specialty glass melting technicians, combined with secondary validation through SEMI equipment market data, ECHA substance restriction filings, and SEC disclosures from materials conglomerates, underwrites the qualitative findings. Bottom-up triangulation against top-down equipment capex forecasts ensures segmentation integrity across material composition, application, and end-user dimensions.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects, with CAGRs derived from equipment installation timelines and substrate consumption ratios per lithography stage. Segmentation modeling spans product type, application cluster, end-user procurement authority, and distribution channel access mode. Forecast inputs incorporate EUV scanner deployment schedules, sovereign fab construction subsidies, and REACH compliance cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for high-NA EUV lithography or ceramic interposer substitution would alter the outlook. Forecasts reflect assumptions regarding equipment OEM pre-qualification timelines, quartz sand deposit access continuity, and regulatory enforcement intensity across jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Thermal Paste Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
EV Capacitor Films Market