
 Water Quality Sensor Market | 2026-2036
Water Quality Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Water Quality Sensor Market Intelligence
German industrial sensor manufacturing is restructuring around modular optical platforms built for continuous online deployment. Danaher Corporation leverages its life-sciences filtration heritage to anchor premium probe assemblies for pharmaceutical water systems. HORIBA, Ltd. dominates electrochemical sensor exports across East Asian utilities with proprietary solid-state reference architectures. Siemens competes on integrated SCADA compatibility, extending its automation stack into smart-citizen water grids.
A water quality sensor is an instrument that detects chemical, physical, or biological parameters in aqueous environments, typically resolving dissolved oxygen within 0.1 mg/L, turbidity to 0.001 NTU, or pH to 0.01 units for process control and environmental compliance. These devices serve primary industrial and commercial purposes in safeguarding potable water supplies, optimizing wastewater treatment throughput, and maintaining aquaculture stock health. Optical technology leads installed value due to drift-resistant spectrophotometric designs, while electrochemical methods sustain the largest unit volume through lower-cost dissolved oxygen and pH electrodes. Online sensors represent the fastest-expanding product configuration as utilities abandon manual grab-sampling programs in favor of real-time distribution network visibility.
The EPA enforces Safe Drinking Water Act maximum contaminant levels that directly mandate turbidity and disinfectant residual monitoring, compelling municipal procurement of certified sensor systems. EU Drinking Water Directive revisions under ECHA coordination are phasing in stricter microplastic and endocrine-disruptor surveillance that optical sensors with fluorescence channels can address. China's MEE administers surface water quality grading standards that drive provincial procurement of multiparameter probe stations. Stakeholders must decide whether to prioritize sensor platform standardization against fragmented national certification requirements or accept redundant regional product variants.
Market Dynamics
Online sensor deployment is displacing manual grab-sampling programs across municipal water networks, driven by EPA Safe Drinking Water Act amendments and EU Drinking Water Directive revisions mandating real-time residual chlorine and turbidity visibility. This shift compresses replacement cycles for legacy electrochemical probes while accelerating demand for drift-resistant optical platforms.
Growth Catalysts
- EU Drinking Water Directive revisions:ECHA-coordinated mandates for microplastic and endocrine-disruptor surveillance are expanding fluorescence-channel optical sensor procurement across German, French, and Dutch utilities.
- Japan's METI infrastructure modernization:Tokyo and Osaka metropolitan water authorities are replacing aging electrochemical networks with solid-state reference architectures for dissolved oxygen monitoring.
- Optical spectrophotometry maturation:Drift-resistant UV-Vis designs are extending calibration intervals from weeks to months, reducing total cost of ownership for continuous deployment.
Market Restraints
- Premium optical component supply concentration:German and Japanese photodiode foundries control critical supply for spectrophotometric light sources, creating single-source vulnerability.
- Reference electrode drift in electrochemical sensors:Liquid-junction pH and dissolved oxygen probes require frequent recalibration, limiting unattended deployment in remote distribution nodes.
- Fragmented national certification requirements:EPA, ECHA, and China's MEE maintain non-harmonized approval pathways, forcing redundant product variants and delaying market entry.
Strategic Opportunities
- India's Ganga rejuvenation and smart-city programs:BIS standards alignment with WHO guidelines is opening procurement channels for multiparameter probe stations in Kanpur, Varanasi, and Patna.
- SCADA-native sensor integration:Convergence of Modbus and IoT protocols with cloud analytics platforms is creating white space for automation-stack vendors to bundle water-quality modules.
- Aquaculture health monitoring expansion:Dissolved oxygen and ammonia sensing in Norwegian, Chilean, and Vietnamese salmon and shrimp farms represents an underpenetrated vertical with high sensor density requirements.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Firms struggle to hire chemists with embedded systems firmware expertise for miniaturized probe development.
- Legacy analog infrastructure integration:Municipal utilities with 4-20 mA SCADA backbones face costly retrofitting to accommodate digital smart-sensor outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Quality Sensor Market |
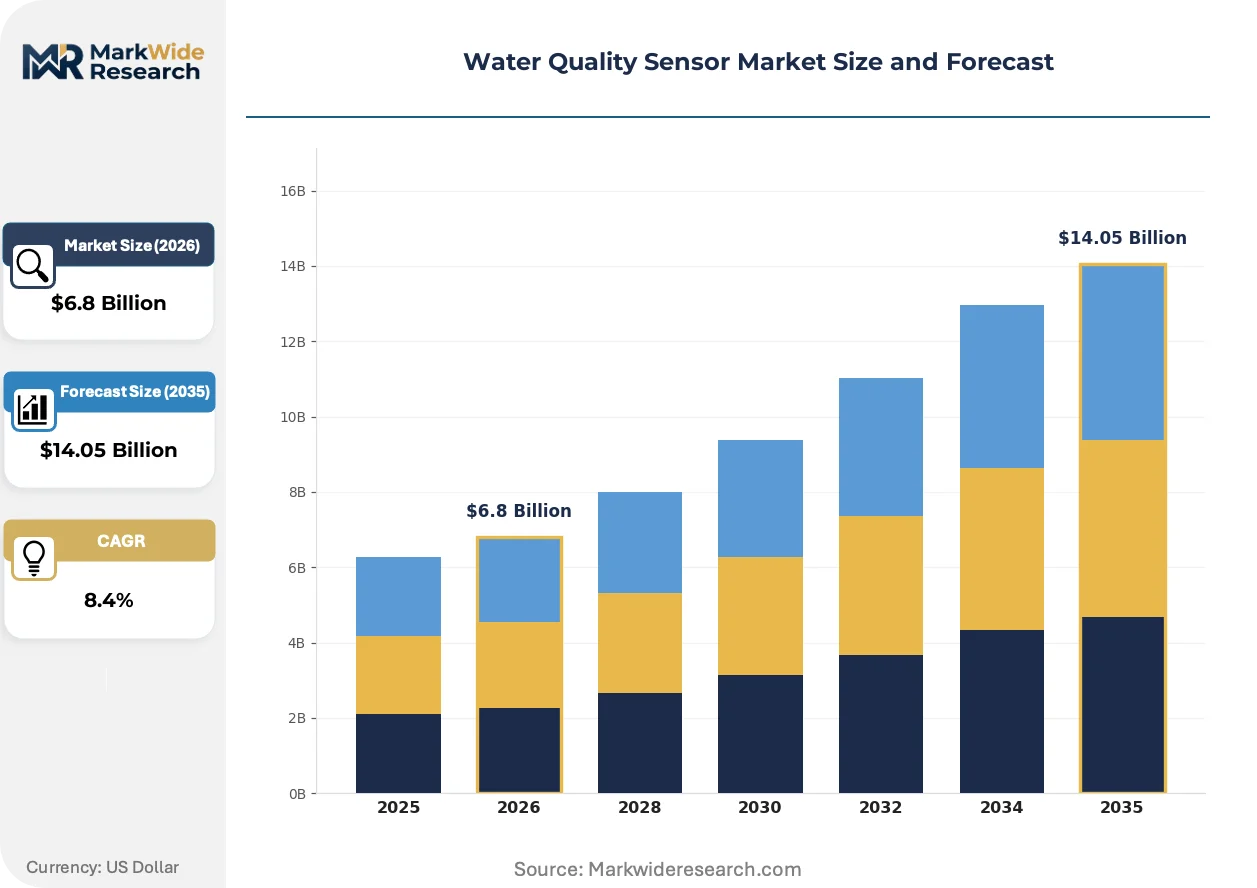
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Sensors, Handheld Sensors, Probes, Online Sensors Technology: Optical, Electrochemical, Mechanical, Conductivity-Based End User: Agriculture, Laboratories, Industrial Enterprises, Municipalities Application: Groundwater Monitoring, Wastewater Treatment, Surface Water Analysis, Aquaculture |
| Companies Covered | Agilent Technologies, Inc., HORIBA, Ltd., General Electric Company, Endress+Hauser, Emerson Electric Co., Danaher Corporation, Teledyne Technologies Incorporated, Siemens, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Quality Sensor Market Strategic Shifts & Innovations
Sensor architecture is bifurcating between premium optical platforms for compliance-critical nodes and cost-optimized electrochemical probes for density coverage. This divergence is reshaping R&D allocation and partnership strategies across the vendor base.
Multi-parameter MEMS sensing is converging with machine-learning drift compensation algorithms to enable single-probe resolution of pH, turbidity, and dissolved oxygen. Japanese and German utilities are piloting these consolidated units in distribution network dead zones where maintenance access is constrained. The structural consequence is compression of installed probe count per monitoring station, threatening revenue-per-site metrics for single-parameter specialists.
EPA Safe Drinking Water Act amendments are tightening maximum contaminant level enforcement for disinfection byproducts, compelling municipal procurement of trihalomethane-capable sensors with integrated residual chlorine correlation. This regulatory pressure is accelerating replacement of standalone free-chlorine amperometric cells with combined optical-electrochemical platforms. US Midwest and Southeast utilities with aging surface water treatment plants represent the most affected buyer segment, with procurement committees now requiring NSF/ANSI 61 certification as a gate criterion.
Utility procurement committees are unbundling sensor hardware from calibration service contracts, reversing decade-long bundled leasing arrangements. European water operators in Germany and the Netherlands are leading this disintermediation, awarding separate tenders for probe supply and third-party validation laboratory services. This pattern is most visible in the Ruhr industrial corridor, where municipal purchasing cooperatives are aggregating volume across multiple water boards to extract modular pricing.
Water Quality Sensor Market Segmentation
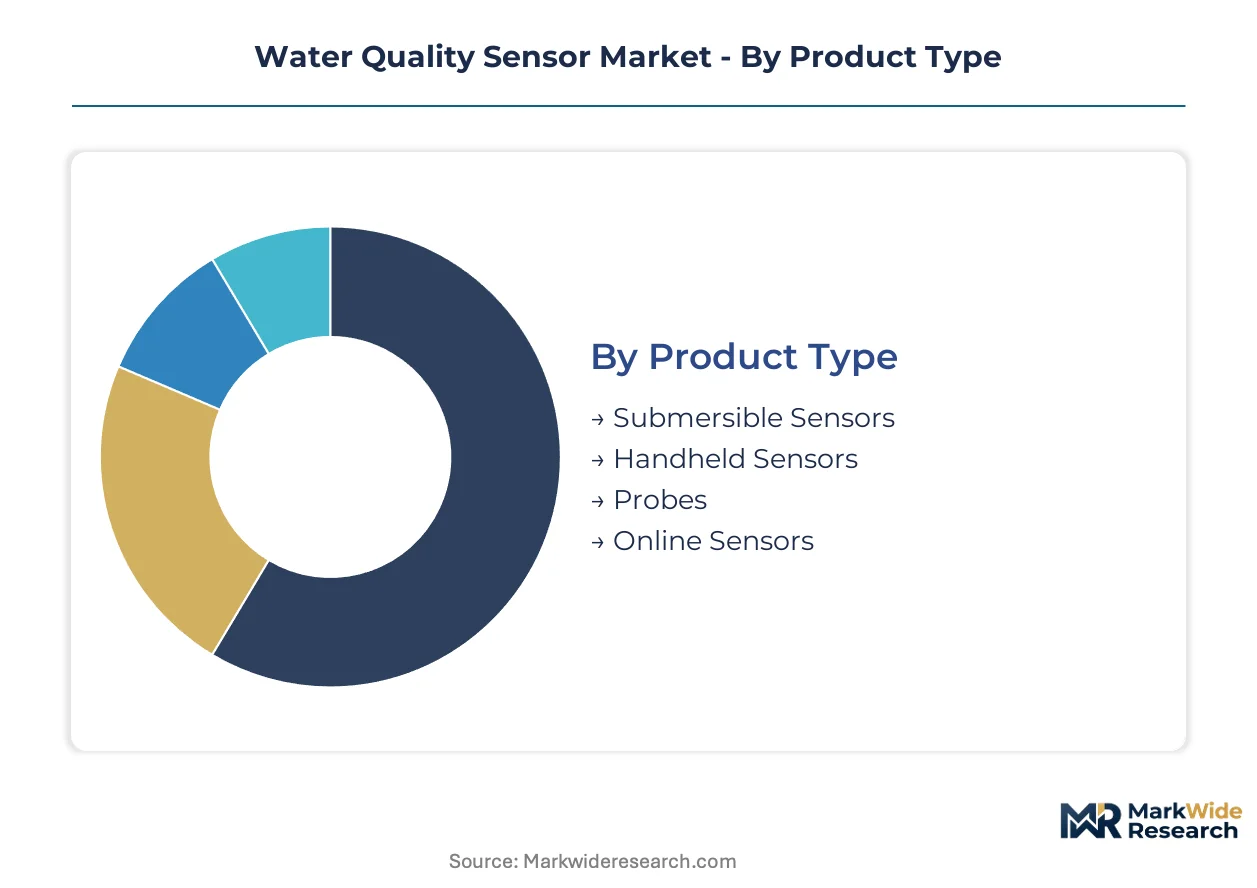
Water quality sensor procurement follows divergent certification pathways depending on deployment context. EPA, ECHA, and China's MEE each impose distinct approval requirements that shape vendor product strategies across segment categories.
Product Type:
NSF/ANSI 61 certification gates municipal drinking water applications, while ATEX and IECEx approvals govern submersible deployments in hazardous industrial environments. Pharmaceutical water systems require USP Class VI compliance for probe materials.
- Online Sensors:Continuous monitoring platforms integrate directly into distribution network SCADA architectures. German utilities in the Ruhr corridor and Japanese metropolitan water authorities are replacing manual sampling programs with these units to meet real-time residual chlorine mandates.
- Probes:Modular assemblies with interchangeable sensing heads allow field-swappable parameter configurations. Danaher Corporation anchors premium probe supply for pharmaceutical water systems where USP compliance is non-negotiable.
- Submersible Sensors:Pressure-rated housings rated for depths exceeding 100 meters serve reservoir and deep-well applications.
- Handheld Sensors:Battery-powered portable units with data logging capability support field verification and regulatory spot-checking.
Online sensors sit at the top of the volume ranking, with probes climbing the fastest.
Technology:
Cost tiers separate premium optical platforms from commodity electrochemical cells, with mechanical and conductivity methods occupying intermediate price positions.
- Optical:Spectrophotometric and fluorometric designs achieve drift-resistant measurement of turbidity, dissolved organic carbon, and fluorescence-channel microplastics. UV-Vis platforms extend calibration intervals from weeks to months, reducing total cost of ownership for continuous deployment.
- Electrochemical:Amperometric and potentiometric cells dominate unit volume through lower manufacturing cost. HORIBA, Ltd. exports solid-state reference architectures across East Asian utilities, though liquid-junction drift limits unattended remote deployment.
- Conductivity-Based:Four-electrode and toroidal designs measure total dissolved solids and salinity in process water and brine monitoring.
- Mechanical:Physical measurement of flow-dependent parameters including suspended solids and sludge volume index.
Electrochemical technology commands the largest unit shipment base, while optical methods capture the highest installed value per sensor.
End User:
Customer type determines service contract bundling preferences, with municipalities unbundling hardware from calibration services while industrial buyers favor integrated maintenance agreements.
- Municipalities:Public water utilities operate under EPA Safe Drinking Water Act and EU Drinking Water Directive mandates. Procurement committees in Germany and the Netherlands now separate probe supply from third-party validation laboratory contracts.
- Industrial Enterprises:Pharmaceutical, semiconductor, and power generation facilities require validated water quality data for process control. These buyers prioritize SCADA-native integration and audit trail documentation.
- Agriculture:Irrigation water quality monitoring supports salinity management and nutrient runoff compliance.
- Laboratories:Reference-grade instrumentation for method validation and regulatory arbitration.
Municipalities generate the highest sensor density per monitoring station, with industrial enterprises expanding most quickly.
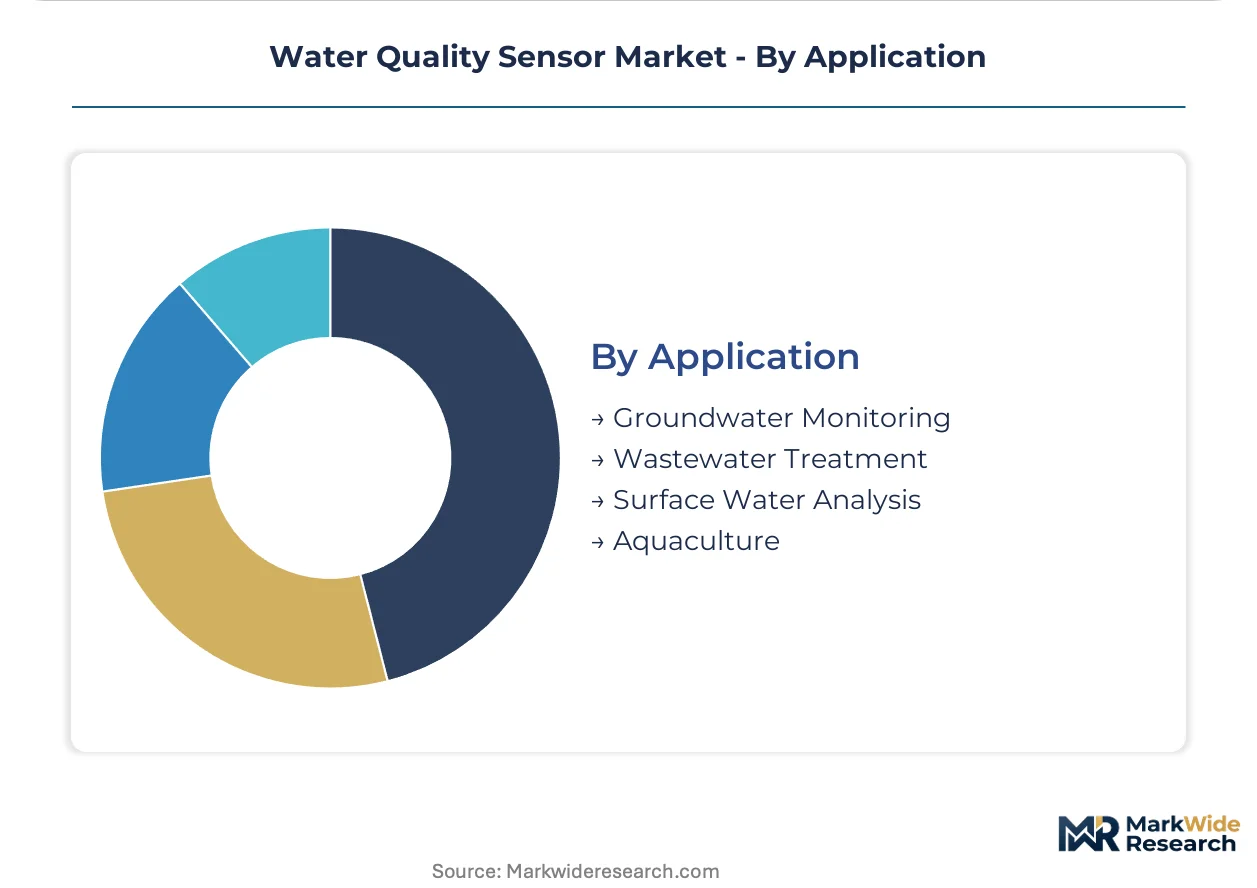
Application:
Geographic deployment patterns cluster around regulatory enforcement intensity and infrastructure replacement cycles.
- Wastewater Treatment:Activated sludge process control demands continuous dissolved oxygen and ammonia monitoring. US Midwest and Southeast utilities with aging surface water treatment plants are procuring trihalomethane-capable sensors under tightened EPA disinfection byproduct rules.
- Groundwater Monitoring:Well-head and plume-tracking deployments require ruggedized submersible units with extended battery life. India's Ganga rejuvenation program is opening procurement channels for multiparameter probe stations in Kanpur, Varanasi, and Patna.
- Surface Water Analysis:River, lake, and reservoir monitoring for China's MEE surface water quality grading standards.
- Aquaculture:Dissolved oxygen and ammonia sensing in Norwegian, Chilean, and Vietnamese salmon and shrimp farms represents an underpenetrated vertical with high sensor density requirements per hectare.
Wastewater treatment absorbs the largest installed base, with aquaculture gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as sensor producers migrate assembly toward jurisdictions with streamlined certification pathways. Cost-of-compliance gaps between EPA, ECHA, and China's MEE approval regimes create locational incentives that concentrate production in Germany, Japan, and the United States despite divergent end-market demands.
United States
Midwest and Southeast utilities with aging surface water treatment plants are procuring trihalomethane-capable sensors under tightened EPA Safe Drinking Water Act enforcement. NSF/ANSI 61 certification gates municipal drinking water applications, compelling vendors to maintain domestic testing facilities. The Ohio River Valley industrial corridor hosts concentrated demand from power generation and chemical processing facilities requiring validated process water monitoring.
Germany
Ruhr industrial corridor municipalities are aggregating procurement volume across water boards to extract modular pricing for online sensor networks. ECHA-coordinated EU Drinking Water Directive revisions mandate microplastic and endocrine-disruptor surveillance that fluorescence-channel optical sensors address. Bavarian and Baden-Württemberg industrial clusters anchor precision manufacturing of photodiode components for spectrophotometric light sources.
Japan
Tokyo and Osaka metropolitan water authorities are replacing aging electrochemical networks with solid-state reference architectures under METI infrastructure modernization programs. JIS standards alignment with international optical specifications accelerates export qualification for domestic sensor producers. Kansai region utilities pilot multi-parameter MEMS sensing with machine-learning drift compensation in distribution network dead zones.
China
Provincial governments are procuring multiparameter probe stations to meet MEE surface water quality grading standards across the Yangtze River Delta. GB standards harmonization with ISO protocols reduces technical barriers for imported optical platforms in municipal applications. Shenzhen and Shanghai industrial zones concentrate assembly operations for cost-optimized electrochemical probes serving domestic aquaculture and wastewater treatment markets.
India
BIS standards alignment with WHO guidelines is opening procurement channels for multiparameter probe stations under Ganga rejuvenation and smart-city programs in Kanpur, Varanasi, and Patna. Central Pollution Control Board enforcement of real-time monitoring mandates for industrial effluent discharge drives sensor deployment in Gujarat and Maharashtra chemical clusters. Karnataka and Tamil Nadu technology corridors host emerging domestic assembly operations targeting price-sensitive municipal segments.
Water Quality Sensor Market Key Industry Players
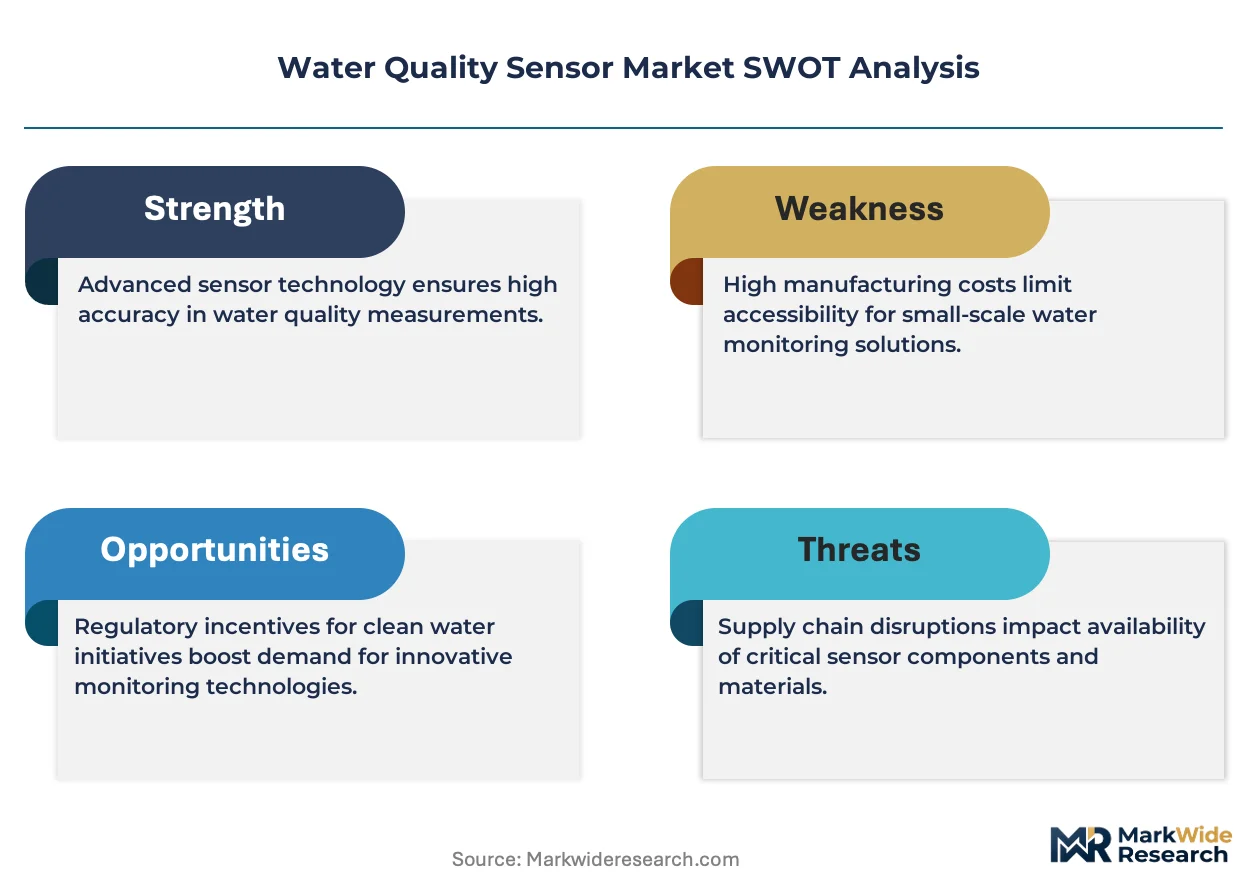
German and Japanese producers anchor the premium optical tier; United States-based automation specialists hold integrated SCADA compatibility positions. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with water-automation extensions, dedicated sensor specialists with proprietary optical or electrochemical architectures, and life-sciences filtration companies leveraging membrane expertise into pharmaceutical water systems. Dominant competitive moves include backward integration into photodiode component supply and strategic partnerships with cloud analytics platforms to bundle hardware-software offerings.
Within the diversified industrial tier, Siemens and General Electric exemplify automation-stack extension strategies, occupying positions that emphasize SCADA-native integration over standalone sensor performance. Among dedicated sensor specialists, HORIBA, Ltd. and Danaher Corporation represent contrasting archetypes: the former anchoring electrochemical exports across East Asian utilities, the latter leveraging life-sciences filtration heritage into premium probe assemblies for pharmaceutical water systems where USP Class VI compliance is non-negotiable. These three companies collectively illustrate how competitive positioning bifurcates between scale-driven platform breadth and certification-locked vertical depth.
| Leading Market Players |
|---|
| Agilent Technologies, Inc. |
| HORIBA, Ltd. |
| General Electric Company |
| Endress+Hauser |
| Emerson Electric Co. |
| Danaher Corporation |
| Teledyne Technologies Incorporated |
| Siemens |
| Xylem |
| Others |
Cost & Logistics Intelligence
EU Drinking Water Directive revisions mandating microplastic and endocrine-disruptor surveillance gate qualified supply to vendors with fluorescence-channel optical platforms and premium-tier pricing access to German, French, and Dutch utilities with bundled validation service requirements.
Pricing Analysis
Distributor margins of 15-25 percent sit atop manufacturer list prices for online sensor networks sold to municipal procurement committees. Three-tier pricing structure across premium optical, standard electrochemical, and economy handheld levels separates NSF/ANSI 61-certified units from ATEX-rated industrial variants and portable spot-check devices. Cost compression in the electrochemical tier is intensifying because Chinese assemblers are flooding domestic aquaculture markets with unbranded dissolved oxygen probes. Industrial pharmaceutical buyers show the least price sensitivity due to USP Class VI compliance non-negotiability, while Indian municipal tenders under Ganga rejuvenation programs exhibit acute bid-price competition.
Supply Chain Analysis
Specialized photonics engineering talent scarcity in Bavarian and Baden-Württemberg manufacturing zones constrains expansion of spectrophotometric light source production. German and Japanese foundries anchor critical photodiode component supply, with Shenzhen and Shanghai zones handling cost-optimized electrochemical probe assembly. Single-source vulnerability concentrates in liquid-junction reference electrode materials sourced from Japanese specialty chemical producers. Distribution runs through authorized industrial automation distributors serving municipal utilities and direct OEM relationships with pharmaceutical water system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Safe Drinking Water Act amendments and EU Drinking Water Directive revisions continuously reset compliance baselines and refresh replacement demand across installed municipal networks.
For Market Incumbents: To counter MEMS-based multi-parameter consolidation threatening single-parameter probe counts per monitoring station, Danaher Corporation and HORIBA should deepen backward integration into solid-state reference architectures and photodiode component supply. Certification investment in India's BIS standards alignment opens defensive positioning against emerging domestic assemblers in Karnataka and Tamil Nadu corridors. For New Entrants and Emerging Players: Cloud analytics platform partnerships offer white-space access to utilities unbundling hardware from calibration service contracts in Germany's Ruhr corridor and Dutch municipal cooperatives. Norwegian, Chilean, and Vietnamese aquaculture verticals present the most penetrable segment due to high sensor density requirements per hectare and limited incumbent specialization. Direct-to-utility pilot programs demonstrating machine-learning drift compensation algorithms bypass established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier electrochemical specialists because fragmented national certification requirements force redundant regional product variants that scale advantages can consolidate. Five-to-ten year viability hinges on optical platform transition capture rates among East Asian utilities replacing aging networks. Watch for EPA enforcement intensity signals around trihalomethane maximum contaminant levels as inflection indicators for combined optical-electrochemical platform procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodiode Supply | German and Japanese foundry control creates captive supply security for spectrophotometric platforms. |
| Multi-Parameter MEMS Platform Launch | Machine-learning drift compensation enables single-probe replacement of three discrete sensors in distribution dead zones. |
| Cloud Analytics Partnership | SCADA-native integration bundles position automation-stack vendors against standalone sensor specialists. |
| BIS Standards Certification Investment | Indian Ganga rejuvenation and smart-city procurement channels require WHO-aligned validation for probe station tenders. |
| Aquaculture Vertical Specialization | Dissolved oxygen and ammonia sensing density in Norwegian and Vietnamese salmon farms exceeds municipal network concentration. |
Research Approach
Bottom-up municipal and industrial end-use modeling reconciled against top-down sensor manufacturer shipment tracking forms the analytical core of this study. Primary interviews with water utility procurement directors, SCADA integration engineers, pharmaceutical validation managers, and aquaculture operations heads combined with secondary validation from EPA enforcement databases, ECHA regulatory filings, MEE surface water grading reports, and municipal tender aggregation platforms. Cross-referencing installation records against certification approval timelines enables triangulation of replacement cycle velocity and real-time monitoring adoption rates.
Input-output matrices map optical and electrochemical technology penetration across online sensor, probe, submersible, and handheld product configurations over the projection horizon. Segmentation dimensions include technology type, product form factor, end-user category, and application context with regional regulatory cluster overlays. CAGRs derive from fitted diffusion curves calibrated to historical replacement patterns and regulatory mandate effective dates. Forecast inputs incorporate METI infrastructure modernization program allocations and China's MEE provincial procurement targets for multiparameter probe stations.
Revisions become necessary when EPA Safe Drinking Water Act enforcement intensity shifts, EU Drinking Water Directive implementation timelines accelerate, or photodiode foundry capacity constraints materialize beyond current German and Japanese supply bases. Forecasts reflect assumptions about regulatory harmonization progress and certification pathway streamlining that may not materialize. Material deviation in named triggers warrants pause and re-evaluation of optical platform transition timing and electrochemical probe volume expectations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Confocal Displacement Sensor Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
US Distributed Acoustic Sensing Market
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Industrial Transmitters Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
United States (US) Industrial Sensors Market
Sensors and Controls
Smart Hydrophone Market