
 Synthetic Sapphire Market | 2026-2036
Synthetic Sapphire Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Sapphire Market Outlook
China is fragmenting synthetic sapphire capacity as domestic producers scale Kyropoulos and Czochralski furnaces for LED and smartphone cover applications. Saint-Gobain leverages its European industrial base to sustain high-purity boule production for aerospace and defense optics. KYOCERA Corporation anchors Japanese supply through integrated ceramic-to-sapphire processing chains. Monocrystal dominates Ukrainian-grown crystal output, specializing in large-diameter substrates for gallium nitride epitaxy.
Synthetic sapphire is a single-crystal aluminum oxide (Al₂O₃) material produced through melt or solution growth, valued for Mohs hardness of 9, thermal stability above 2000°C, and optical transmission from ultraviolet to mid-infrared wavelengths. Its primary purpose spans scratch-resistant watch crystals, LED epitaxial substrates, infrared missile domes, and medical implant coatings. Substrate segments lead volume due to gallium nitride LED expansion, while optical component grades command premium margins from defense and medical laser systems. Electronic grade material is concentrating in East Asian supply chains as display manufacturers tighten specifications for sapphire-on-glass laminates.
China's MIIT enforces GB standards for sapphire wafer dimensional tolerances, while REACH in Europe restricts chromium and iron dopants in optical grades destined for medical devices. The US FDA classifies synthetic sapphire for dental and orthopedic implants under 510(k) pathways, shaping biocompatibility testing protocols. Japan's METI coordinates JIS standards with domestic crystal growers to maintain export competitiveness in precision optics. Stakeholders must monitor furnace energy economics and rare earth co-doping patents as determinants of cost structure and product differentiation.
Market Dynamics
LED substrate specifications are tightening faster than furnace capacity can adapt, forcing crystal growers to prioritize diameter scaling over boule count expansion.
Growth Catalysts
- GaN-on-sapphire LED epitaxy:Display manufacturers in South Korea and Taiwan are specifying 6-inch and 8-inch substrates for micro-LED backplanes, pulling volume through the supply chain.
- REACH chromium restrictions:European medical device OEMs are sourcing high-purity optical grades from certified furnaces, creating preference premiums for compliant producers.
- Kyropoulos furnace scaling:Chinese producers are installing 300kg+ capacity units to reduce unit economics for smartphone cover glass applications.
Market Restraints
- Tungsten crucible cost volatility:Furnace consumables represent 15-20% of crystal production costs, with tungsten prices tracking rare earth mining constraints.
- Ukrainian supply concentration:Monocrystal's large-diameter substrate dominance creates single-source risk for gallium nitride foundries dependent on 8-inch material.
- Synthetic quartz substitution:UV-grade optical applications below 300nm are migrating to fused silica where transmission efficiency outweighs hardness requirements.
Strategic Opportunities
- India PLI scheme:Domestic LED assembly incentives are attracting substrate importers to establish local wafer processing and edge-polishing operations.
- Sapphire-on-glass laminates:Foldable display manufacturers are testing chemically strengthened sapphire layers bonded to polyimide substrates for scratch resistance.
- Japan METI precision optics coordination:JIS standard harmonization with export markets is reducing certification duplication for defense and aerospace contractors.
Industry Challenges
- Czochralski seed crystal preparation:Defect-free seed rod fabrication requires 8-12 week lead times, constraining furnace utilization rates during demand spikes.
- Dual carbon compliance documentation:China's MEE enforcement of energy intensity metrics per ton of boule output is forcing furnace operators to retrofit thermal insulation and power monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Sapphire Market |
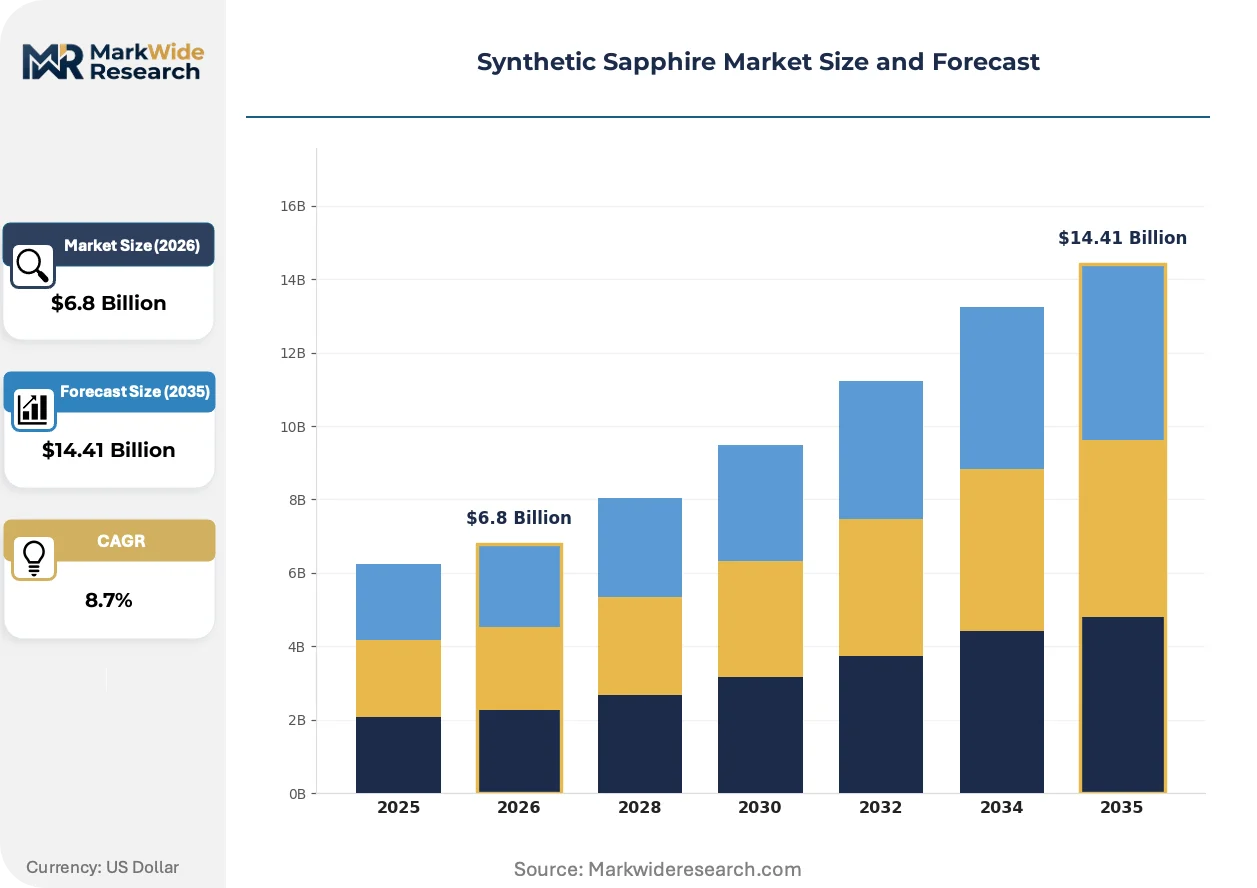
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Crystal, Bulk Crystal, Substrate, Optical Component End Use Industry: Electronics, Automotive, Aerospace, Healthcare Grade: Electronic Grade, Gem Quality, Industrial Grade, High Purity Technology: Verneuil Process, Hydrothermal Method, Czochralski Method, Edge-defined Film-fed Growth |
| Companies Covered | Saint-Gobain, Crystalwise Technology Co Ltd, Monocrystal, Adamant Namiki Precision Jewel Co Ltd, ILJIN Display Co Ltd, Rubicon Technology Inc, Rayotek Scientific Inc, Silian Optoelectronic Science & Technology, KYOCERA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Sapphire Market Strategic Shifts
Furnace automation and in-situ monitoring are compressing defect detection cycles from post-growth inspection to real-time process intervention.
Edge-defined film-fed growth (EFG) ribbon technology is digitizing yield prediction through thermal camera arrays and machine learning models that correlate meniscus shape to crystal defect probability. LED substrate manufacturers in Japan are piloting these systems to reduce kerf loss during wire sawing. The structural consequence is digitizing quality assurance from a batch-sampling discipline to a continuous feedback loop that adjusts pull rates mid-growth.
China's GB standards for sapphire wafer dimensional tolerances are tightening flatness and bow specifications for 6-inch substrates used in gallium nitride power electronics. MIIT enforcement of these metrics is disqualifying second-tier domestic producers from automotive inverter supply chains. European automotive Tier 1s are responding by dual-sourcing from Japanese and Ukrainian certified suppliers while auditing Chinese furnace traceability.
Defense procurement offices are unbundling crystal growth from optical fabrication, awarding separate contracts for boule production and precision polishing to capture specialized expertise. This disintermediation is fragmenting the traditional integrated supply chain model where Saint-Gobain or KYOCERA handled both stages. The shift is most visible in US missile dome programs, where Raytheon and Lockheed Martin now specify crystal origin and processing shop independently.
Synthetic Sapphire Market Segmentation
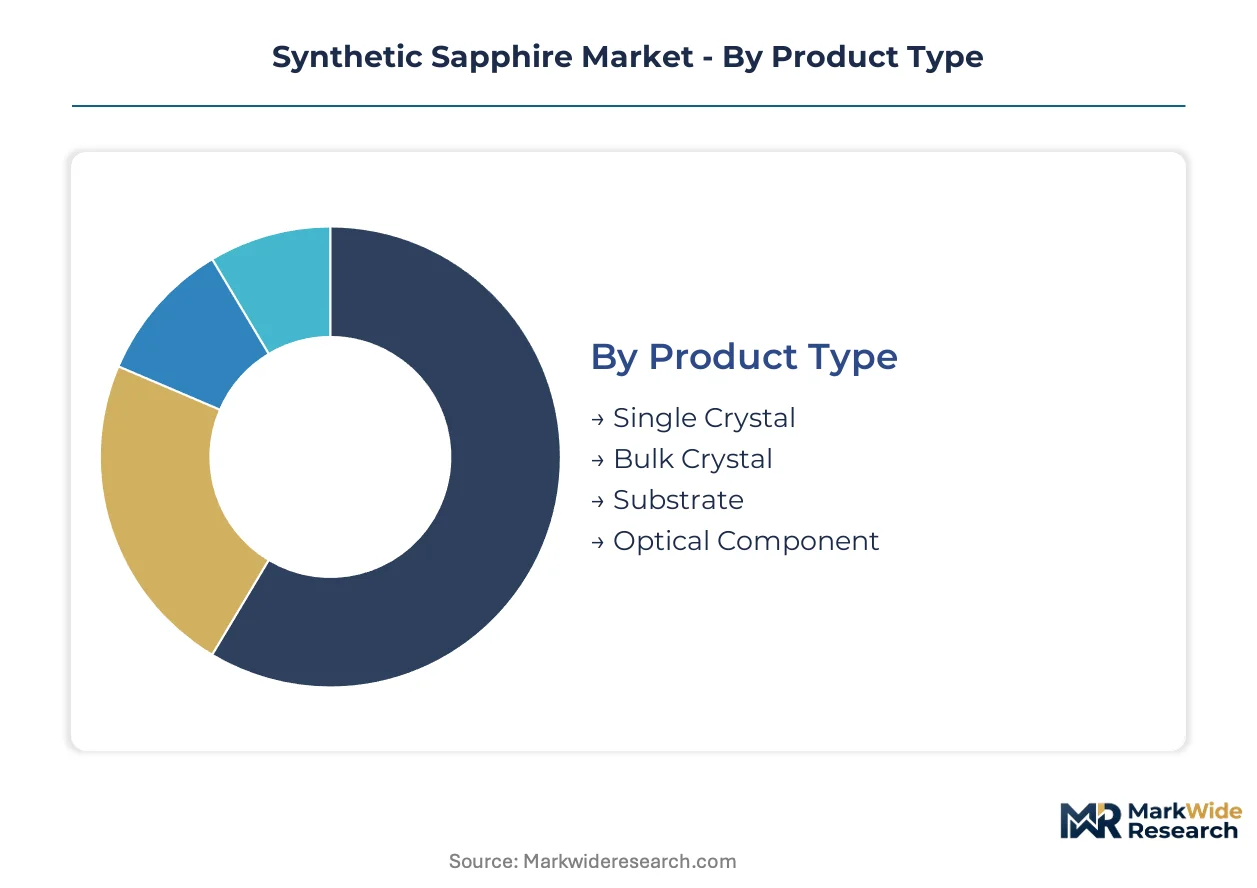
Synthetic sapphire markets fragment across crystal structure, end-use performance requirements, and growth methodology. Each segmentation axis reveals distinct margin profiles and supply chain configurations that determine competitive positioning.
Product Type:
Use-case spectrum spans from raw boule material to precision-finished components serving defense optics and consumer electronics.
- Single Crystal:Monocrystalline aluminum oxide ingots grown via melt processes serve as feedstock for subsequent wafering and polishing operations. Kyropoulos furnace operators in China concentrate capacity here for LED substrate pull-through, though kerf loss during wire sawing erodes yield economics.
- Substrate:Lapped and polished wafers with specified crystallographic orientation enable gallium nitride epitaxy for solid-state lighting and power electronics. South Korean display manufacturers are specifying 6-inch and 8-inch diameters for micro-LED backplanes, tightening flatness tolerances beyond legacy furnace capabilities.
- Bulk Crystal:Large-diameter boules for optical window and dome applications require extended growth cycles that strain tungsten crucible lifetimes.
- Optical Component:Precision-polished lenses, prisms, and missile domes command premium margins from aerospace and medical laser OEMs.
The dominant share belongs to Substrate, while Single Crystal is closing the gap fastest.
End Use Industry:
Customer concentration varies sharply by application, with electronics absorbing volume and aerospace capturing margin.
- Electronics:LED epitaxial substrates and smartphone cover glass consume the majority of tonnage output. Taiwan and South Korea-based display manufacturers are consolidating supplier qualifications around 8-inch diameter capability.
- Aerospace:Infrared missile domes and cockpit display windows require bubble-free, strain-minimized crystal with trace iron content below 10 ppm. US defense procurement offices now unbundle crystal growth from polishing contracts.
- Automotive:Gallium nitride power electronics for electric vehicle inverters are migrating to sapphire substrates as silicon carbide supply tightens.
- Healthcare:Dental implants and surgical instrument coatings exploit biocompatibility and wear resistance under FDA 510(k) pathways.
Electronics holds volume leadership, though Aerospace delivers the steepest expansion trajectory in value terms.
Grade:
Specification tiers separate commodity material from certified optical and electronic grades commanding 3-5x price multiples.
- Electronic Grade:Controlled defect density and surface preparation enable gallium nitride heteroepitaxy with dislocation densities below 10^8 cm^-2. MIIT enforcement of GB dimensional standards is disqualifying second-tier Chinese producers from automotive inverter supply chains.
- High Purity:Trace element constraints below 1 ppm total metallic impurities serve medical laser systems and spectroscopy applications where chromium and iron dopants degrade optical transmission. REACH restrictions in Europe are redirecting medical device OEMs toward certified furnace sources.
- Gem Quality:Colorless crystal for jewelry applications competes with natural sapphire on price and ethical sourcing credentials.
- Industrial Grade:Bearing surfaces, watch crystals, and mechanical seals prioritize hardness and thermal stability over optical perfection.
Electronic Grade commands the dominant position, while High Purity is gaining share fastest among specification tiers.
Technology:
Growth methodology determines crystal size, defect structure, and economic scalability for target applications.
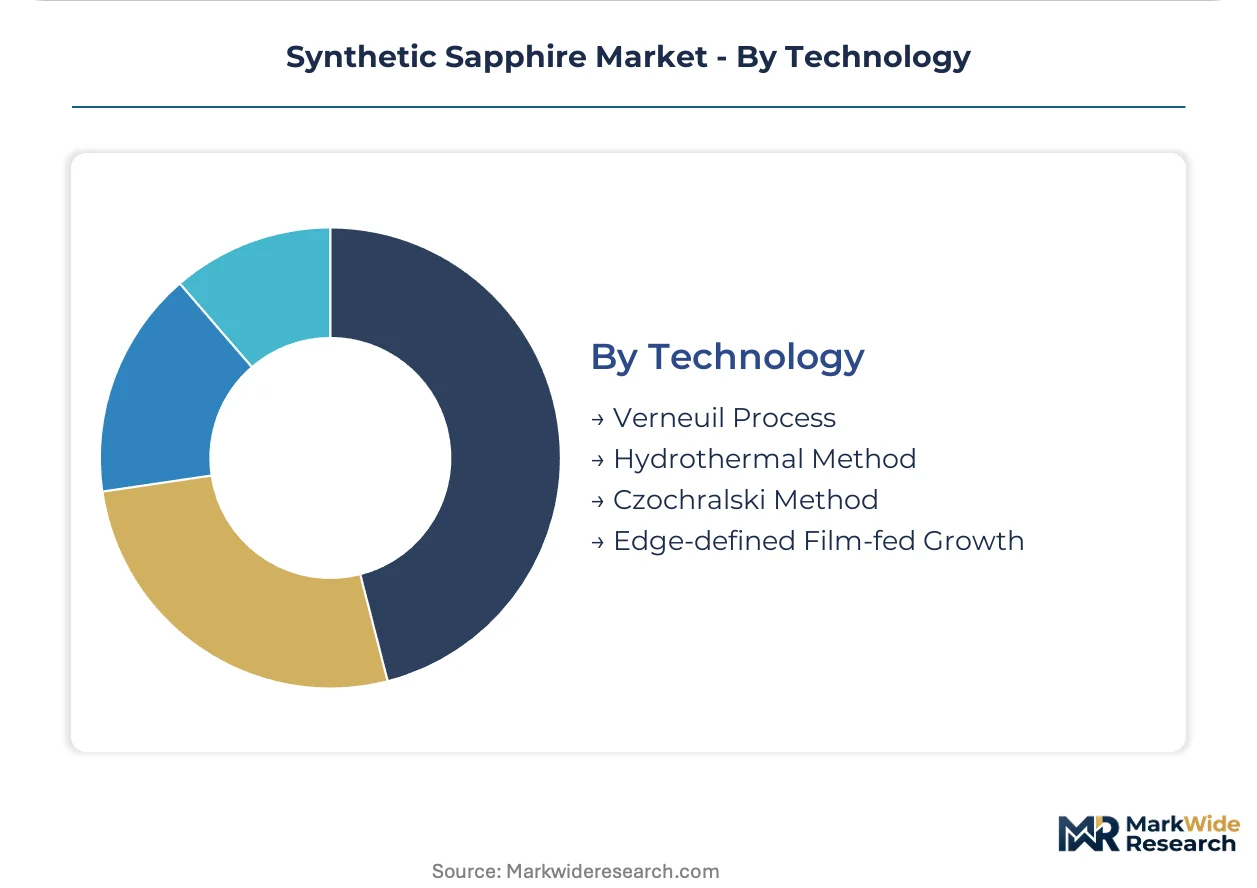
- Czochralski Method:Rotational pulling from iridium crucibles yields large-diameter boules with controlled oxygen content for semiconductor substrates. Seed crystal preparation requires 8-12 week lead times that constrain furnace utilization during demand spikes.
- Edge-defined Film-fed Growth:Ribbon crystal formation through die-controlled meniscus shape enables near-net-shape production of optical windows with reduced kerf loss. Japanese LED substrate manufacturers are piloting thermal camera arrays and machine learning for real-time defect prediction.
- Kyropoulos Process:Low thermal gradient growth produces low-dislocation crystal for high-brightness LED applications. Chinese producers are installing 300kg+ capacity units to compress unit economics for smartphone cover glass.
- Verneuil Process:Flame fusion remains economical for small-diameter rods and gem material though limited by thermal stress cracking in larger dimensions.
- Hydrothermal Method:High-pressure aqueous growth enables doped and colored crystal variants for specialty optical and gem applications.
Czochralski Method retains the dominant installed base, while Edge-defined Film-fed Growth is climbing the fastest as furnace automation reduces yield variance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT enforcement of GB dimensional standards in China shapes furnace economics across East Asian supply chains. Crystal growers in South Korea and Japan calibrate capacity expansion against Chinese unit cost compression.
China
LED substrate demand from display manufacturers in Shenzhen and Dongguan pulls volume through domestic Kyropoulos furnace installations. MEE dual carbon compliance documentation forces operators to retrofit thermal insulation and power monitoring systems. Yangtze River Delta clusters concentrate 300kg+ capacity units for smartphone cover glass applications.
South Korea
Samsung Display and LG specify 6-inch and 8-inch substrates for micro-LED backplanes, tightening flatness tolerances beyond legacy furnace capabilities. MFDS coordination with METI on JIS standard harmonization reduces certification duplication for defense contractors. Seoul Capital Area foundries dual-source from Japanese and Ukrainian certified suppliers while auditing Chinese furnace traceability.
Japan
Precision optics for aerospace and medical laser systems command premium margins from Kanto-based fabricators. METI JIS standard harmonization with export markets maintains competitiveness against Chinese cost structures. Chubu-Nagoya corridors pilot thermal camera arrays and machine learning for real-time defect prediction in EFG ribbon growth.
United States
Defense procurement offices unbundle crystal growth from optical fabrication, awarding separate contracts for boule production and precision polishing. FDA 510(k) pathways for dental and orthopedic implants shape biocompatibility testing protocols. Greater Boston and Pacific Northwest clusters concentrate infrared missile dome and medical laser system suppliers.
Germany
REACH chromium and iron restrictions redirect medical device OEMs toward certified furnace sources, creating preference premiums for compliant producers. KBA automotive standards for gallium nitride power electronics in EV inverters tighten substrate specifications. Bavarian industrial clusters sustain high-purity boule production for aerospace optics against Chinese volume competition.
Synthetic Sapphire Market Competitive Environment
Capability concentration sits with integrated ceramic-to-sapphire processors; scale advantage sits with furnace operators installing 300kg+ Kyropoulos units. The vendor base stratifies across three tiers: defense-aerospace specialists commanding premium margins, LED substrate volume producers optimizing kerf loss economics, and gem-quality material suppliers competing on ethical sourcing credentials. Dominant competitive moves include furnace automation investments compressing defect detection cycles and dual-sourcing arrangements mitigating Ukrainian supply concentration risk.
Within the integrated processing tier, KYOCERA Corporation and Saint-Gobain exemplify vertical control from boule growth through precision polishing. Monocrystal anchors the large-diameter substrate segment despite geographic concentration exposure. Among Asian furnace operators, ILJIN Display Co Ltd and Crystalwise Technology Co Ltd occupy positions calibrated to South Korean and Taiwanese display manufacturer specifications.
| Leading Market Players |
|---|
| Saint-Gobain |
| Crystalwise Technology Co Ltd |
| Monocrystal |
| Adamant Namiki Precision Jewel Co Ltd |
| ILJIN Display Co Ltd |
| Rubicon Technology Inc |
| Rayotek Scientific Inc |
| Silian Optoelectronic Science & Technology |
| KYOCERA Corporation |
| Others |
Value Chain & Pricing Dynamics
Kyropoulos furnace overcapacity in China's Yangtze River Delta compresses unit economics for smartphone cover glass, forcing suppliers to absorb tungsten crucible volatility while buyers extract volume discounts. This utilization imbalance concentrates pricing power with display manufacturers in South Korea and Taiwan, who dual-source to maintain leverage over substrate specifications.
Pricing Analysis
Chinese-origin 6-inch substrates trade at a discount to Japanese and Ukrainian certified material, with price spreads widening as MIIT enforcement of GB dimensional standards disqualifies second-tier domestic producers from automotive inverter supply chains. Three-tier pricing structure across premium, standard, and economy levels separates aerospace optical grades from LED substrate volume and industrial bearing applications. Cost compression in standard-grade material is intensifying because 300kg+ furnace installations accelerate output without matching demand pull from micro-LED backplane adoption. Display manufacturers exhibit the sharpest price sensitivity, while defense contractors accept premiums for traceable furnace documentation.
Supply Chain Analysis
Contract manufacturing concentration sits with KYOCERA Corporation and Saint-Gobain for integrated ceramic-to-sapphire processing, while Monocrystal anchors large-diameter substrate output. Supply concentrates in China, Ukraine, and Japan, with raw material dependencies on tungsten crucibles, high-purity alumina feedstock, and iridium furnace components. Single-source vulnerability runs through Monocrystal's 8-inch substrate dominance for gallium nitride foundries. Distribution runs through direct long-term offtake agreements between crystal growers and display manufacturers, bypassing merchant distributors for electronic-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic sapphire markets operate as a defensive-moat industry where regulatory entrenchment through FDA 510(k) pathways and REACH certification creates sticky supplier relationships that resist price-based displacement.
For Market Incumbents: Harden furnace traceability documentation to capture preference premiums from European medical device OEMs responding to REACH chromium restrictions. Deepen upstream control over tungsten crucible supply through captive sourcing or long-term offtake with rare earth miners, insulating margin structures from the 15-20% cost volatility that erodes Kyropoulos economics. Priority investment targets EFG ribbon automation with thermal camera arrays and machine learning, compressing defect detection cycles before Chinese competitors scale equivalent capabilities. For New Entrants and Emerging Players: India's PLI scheme for domestic LED assembly offers white-space territory for edge-polishing and wafer processing operations, avoiding capital-intensive boule growth where Chinese 300kg+ furnaces dominate unit economics. Target automotive inverter supply chains as gallium nitride power electronics migrate from silicon carbide-constrained sources, exploiting GB standard disqualification of second-tier Chinese producers. Go-to-market leverage rests on dual-carbon compliance documentation that satisfies China's MEE enforcement for European automotive Tier 1 audits. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated ceramic-to-sapphire processors with captive precision polishing capabilities, where defense procurement offices now unbundle contracts to capture specialized expertise. Long-term viability favors acquisition targets with JIS standard certification and METI-coordinated export harmonization, positioning for sustained margin capture against Chinese volume competition. Signal to monitor: wire sawing kerf loss rates as EFG ribbon technology displaces traditional boule-to-wafer conversion, reshaping yield economics across the supply chain.| Strategic Initiative | Industry Significance |
|---|---|
| EFG Ribbon Automation Investment | Japanese LED substrate manufacturers pilot thermal camera arrays to reduce kerf loss during wire sawing. |
| Dual-Carbon Compliance Documentation | China's MEE enforcement forces furnace operators to retrofit thermal insulation and power monitoring systems. |
| Long-Term Tungsten Crucible offtake | Rare earth mining constraints on furnace consumables drive backward integration into critical input supply. |
| JIS Standard Harmonization | METI coordination reduces certification duplication for defense contractors exporting precision optics. |
| India PLI Scheme Localization | Domestic LED assembly incentives attract substrate importers to establish local wafer processing operations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with crystal growth engineers, LED substrate procurement managers, defense procurement officers, and medical device regulatory affairs leads; and secondary validation through SEC filings of sapphire producers, MIIT GB standard enforcement notices, REACH restriction updates, and customs trade data on tungsten and alumina flows. Bottom-up triangulation across furnace capacity installations and top-down demand modeling from display manufacturer capex disclosures cross-validated volume estimates.
Forecast inputs considered technology segmentation by growth methodology, grade tier differentiation, and end-use concentration across electronics, aerospace, automotive, and healthcare verticals across the analysis window. CAGRs derived from elasticity-adjusted demand curves for gallium nitride LED epitaxy and power electronics substrate adoption, incorporating furnace energy economics and rare earth co-doping patent landscapes as cost-structure determinants.
The forecast holds incumbent behavior within observed patterns; aggressive furnace automation investments by Chinese operators or sudden tungsten supply disruption would shift outcomes beyond modeled ranges. Quarterly review of MIIT enforcement actions, display manufacturer substrate qualification timelines, and defense procurement unbundling announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Gallium Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Encapsulant Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Monocrystalline Silicone Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Silicon Germanium Material Market