
 Semiconductor Grade PTFE Market | 2026-2036
Semiconductor Grade PTFE Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Grade PTFE Market Insights
Capital intensity divergence between integrated resin-to-part producers and compounders is reorganizing competitive tiers in semiconductor grade PTFE. Daikin Industries sustains captive fluorine chemistry operations that secure feedstock purity for critical chip manufacturing applications. The Chemours Company leverages its North American fluorspar access and vertical infrastructure to dominate standard-grade sheet and rod supply. Gujarat Fluorochemicals Limited anchors cost-positioned tube extrusion for non-critical semiconductor equipment tiers.
Semiconductor grade PTFE denotes perfluorinated polymer resin purified to sub-ppb metallic contamination thresholds, extruded or molded into components that withstand aggressive plasma chemistries and thermal cycling in wafer processing environments. Sheet products command mature margins in chamber liner replacement cycles, while tube segments capture faster expansion as single-wafer tool architectures proliferate. Coating applications for clean room infrastructure represent concentrated margin pools where fluoropolymer purity certifications determine vendor qualification timelines.
EPA emissions standards and REACH fluoropolymer restrictions shape material certification burdens, with FDA overlap governing medical-grade crossover supply that competes for identical resin pools. Japan's METI semiconductor revitalization subsidies and South Korea's K-Battery/K-Semiconductor tax credits redirect regional demand toward domestic-qualified PTFE vendors. Stakeholders must monitor resin allocation priority shifts between semiconductor and battery end uses as both sectors scale simultaneously.
Market Dynamics
Wafer processing equipment manufacturers in East Asia are expanding procurement of high-purity fluoropolymer components as single-wafer tool architectures displace batch processing systems. Stricter volatile organic compound limits under REACH and EPA frameworks are pushing fabs toward certified ultra-clean materials.
Growth Catalysts
- Single-wafer tool proliferation:Advanced logic and memory fabs in South Korea's Pyeongtaek-Yongin corridor are replacing batch chambers with single-wafer architectures that demand higher volumes of precision-extruded PTFE tubing.
- REACH fluoropolymer restrictions:The European Chemicals Agency's tightening limits on volatile organic compound emissions are disqualifying standard-grade fluoropolymers from wafer processing applications.
- Plasma chemistry intensification:Aggressive fluorine-based etch chemistries in 3nm node production are accelerating replacement cycles for chamber liners and gas delivery components.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in China and Mexico, exposing resin producers to export quota volatility and geopolitical supply interruptions.
- Sub-ppb purification bottlenecks:Metallic contamination thresholds below one part per billion require ion-exchange and distillation infrastructure that limits qualified resin supply.
- Perfluoroalkyl substance scrutiny:Draft restrictions under the EPA TSCA framework and EU persistent organic pollutant assessments are extending certification timelines for new resin grades.
Strategic Opportunities
- India PLI scheme leverage:Semiconductor fabrication incentives under India's production-linked incentive program are attracting equipment vendors who require certified PTFE component supply.
- Battery-PTFE resin competition:Lithium-ion cell manufacturing is competing for identical high-purity fluoropolymer pools, creating allocation priority negotiations for semiconductor-qualified vendors.
- Clean room infrastructure coatings:Wall and ceiling fluoropolymer coatings for ISO Class 1-3 environments represent margin pools where purity certifications determine vendor qualification timelines.
Industry Challenges
- Plasma etch chemist scarcity:Formulating PTFE compounds that withstand fluorine-rich plasma environments requires specialized materials scientists that resin producers struggle to recruit.
- Fab qualification timelines:OEM validation cycles for new PTFE component suppliers extend eighteen to thirty-six months, freezing out speculative entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Grade PTFE Market |
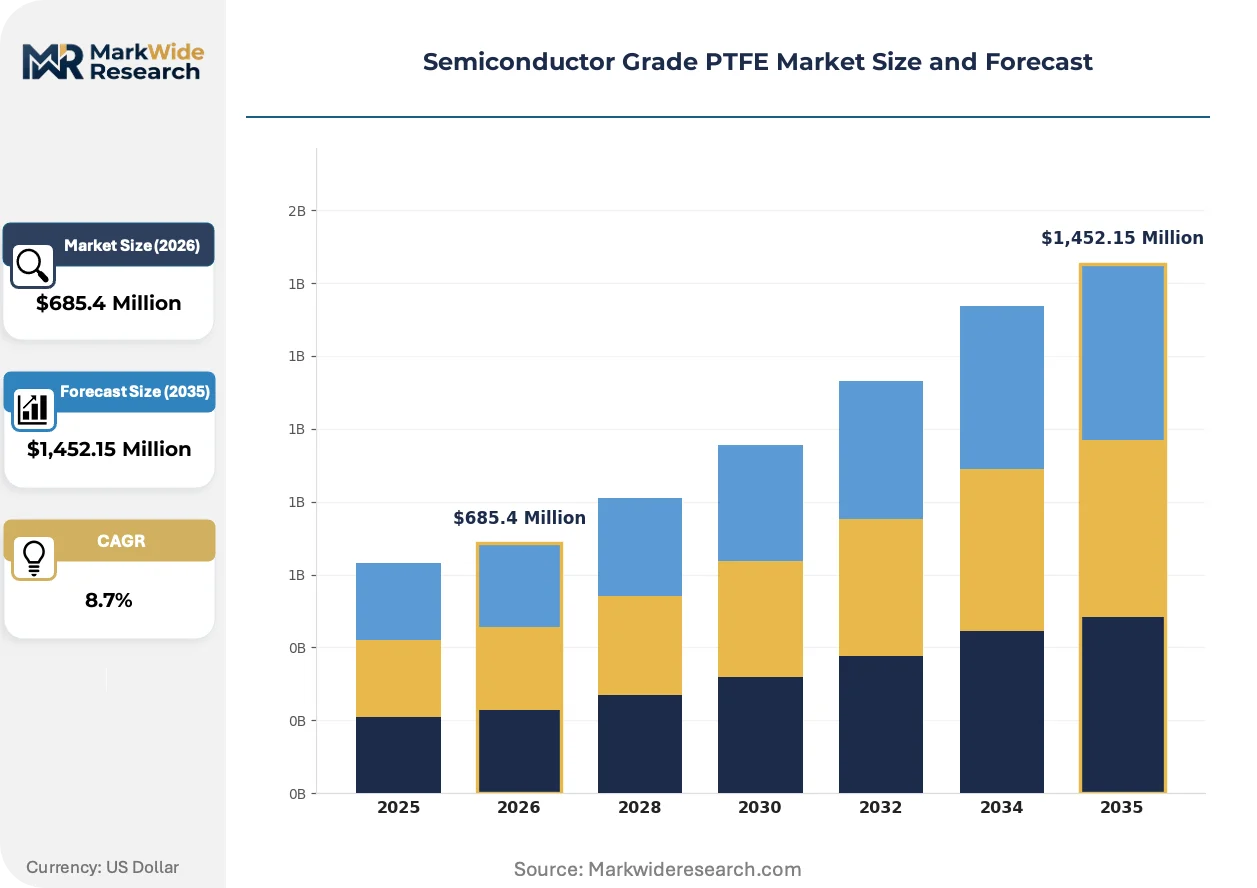
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Rod, Tube, Coating End Use Industry: Electronics, Aerospace, Medical, Automotive Form: Films, Gaskets, Sealants, Insulators Application: Chip Manufacturing, Clean Rooms, Insulation, Semiconductor Equipment |
| Companies Covered | The Chemours Company, Daikin Industries, Ltd., AGC Inc., 3M, Dongyue Group, Syensqo, Gujarat Fluorochemicals Limited, Shamrock Technologies, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Grade PTFE Market Trends and Innovations
Material science advances and regulatory stringency are splitting the competitive landscape between integrated resin-to-part producers and compounders dependent on merchant supply. Three developments are restructuring how semiconductor grade PTFE is specified, sourced, and deployed.
Modified PTFE with improved weldability and reduced cold flow is bifurcating the component supply base. Integrated device manufacturers in Taiwan and South Korea are specifying this grade for chamber hardware requiring complex geometries. The technology is compressing margins for standard-grade sheet suppliers while enabling premium pricing for resin producers with captive modification capabilities.
EPA emissions standards for hazardous air pollutants from fluoropolymer production are forcing capital deployment into abatement systems at US-based resin plants. The industrial consequence is a widening cost gap between North American and Asian production. Sheet and rod segments serving non-critical equipment tiers are absorbing the compliance burden through longer delivery timelines rather than price premiums.
Consolidated procurement by memory and logic fabs is compressing vendor panels from six qualified suppliers to two or three strategic partners. Equipment OEMs in Japan and South Korea are unbundling component supply from system integration contracts. The shift is most visible in gas delivery manifold assemblies where fab engineers now specify resin grade independently of equipment vendor recommendations.
Semiconductor Grade PTFE Market Segmentation
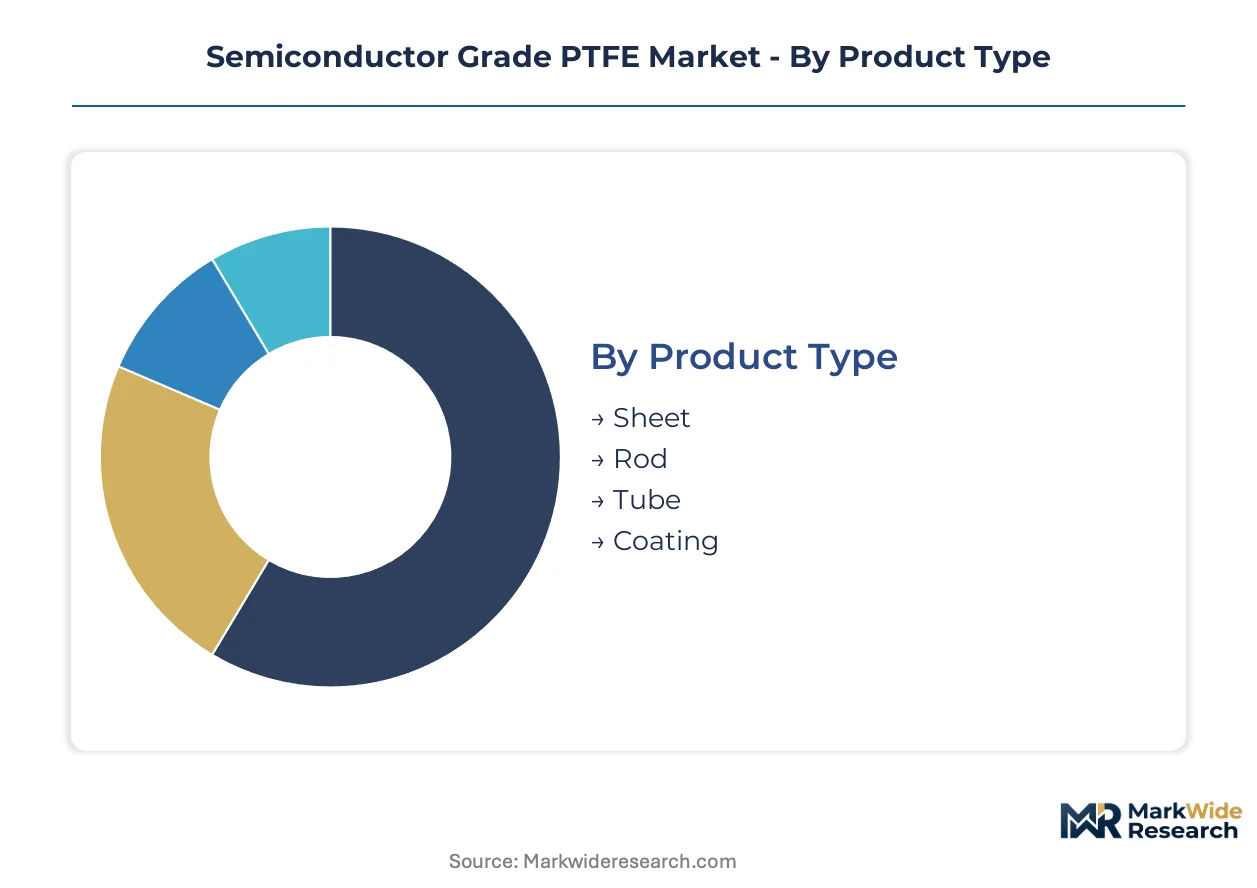
Segmentation in semiconductor grade PTFE reveals how purity certification tiers, form factor constraints, and end-use thermal requirements fragment vendor qualification pathways. Each dimension carries distinct margin structures and substitution vulnerabilities that reshape procurement strategies across wafer processing ecosystems.
Product Type:
Tube products face acute substitution pressure from PFA and FEP alternatives in gas delivery architectures, while sheet formats maintain structural dominance in chamber liner replacement cycles due to plasma erosion resistance thresholds.
- Tube:Precision-extruded PTFE tubing delivers sub-ppb metallic purity for fluorine-based etch chemistry delivery in single-wafer tools. Samsung and SK Hynix fabs in South Korea's Pyeongtaek-Yongin corridor are expanding procurement volumes as batch processing systems retire.
- Sheet:Compression-molded or skived PTFE sheets form chamber liners and baffles that withstand aggressive plasma cycling. Mature replacement cycles in legacy batch tools sustain volume, though 3nm node intensification is accelerating wear rates.
- Rod:Extruded rod stock serves machined components for gas distribution manifolds and valve seats. Standard-grade rod competes with modified PTFE grades in Taiwan and South Korea where weldability specifications are tightening.
- Coating:Dispersion-based fluoropolymer coatings protect clean room infrastructure and equipment surfaces from chemical attack. ISO Class 1-3 certification requirements extend vendor qualification timelines.
Sheet retains volume leadership in replacement-driven procurement; tube holds the steepest expansion curve as single-wafer architectures proliferate.
End Use Industry:
Cost tier stratification separates aerospace qualification burdens from automotive volume opportunities, with electronics commanding premium pricing for sub-ppb contamination thresholds.
- Electronics:Semiconductor wafer processing equipment demands the highest purity grades with metallic contamination below one part per billion. REACH and EPA volatile organic compound limits are disqualifying standard fluoropolymers from advanced logic and memory fab applications.
- Medical:FDA crossover requirements govern implantable device and diagnostic equipment applications that compete for identical resin pools. Medical-grade certifications extend production lot traceability requirements.
- Aerospace:Fuel system seals and wire insulation applications prioritize thermal stability over metallic purity, accessing lower-cost resin tiers. FAA material qualification protocols add documentation layers.
- Automotive:Battery cell manufacturing is competing for high-purity fluoropolymer supply as lithium-ion production scales, creating allocation priority negotiations with semiconductor-qualified vendors.
Electronics commands the dominant revenue share; battery-related automotive demand is expanding most quickly as electric vehicle production accelerates.
Form:
Application-specific performance requirements drive margin differentiation, with films capturing precision coating premiums and gaskets absorbing price pressure from molded seal alternatives.
- Films:Skived or cast PTFE films enable dielectric insulation and membrane applications with controlled thickness tolerance. Clean room wall and ceiling coatings represent concentrated margin pools where purity certifications determine vendor selection.
- Gaskets:Molded or machined gasket forms seal process chambers and gas delivery interfaces. Modified PTFE grades with reduced cold flow are displacing standard formulations in Taiwan and South Korea chamber hardware.
- Sealants:Paste and tape sealant configurations service field installation and maintenance operations. Non-critical equipment tiers absorb cost pressure through extended delivery timelines rather than material substitution.
- Insulators:Rod, tube, and film insulator forms protect electrical connections in plasma generation and RF delivery systems. Plasma chemistry intensification in 3nm production is accelerating replacement cycles.
Gaskets maintain the broadest installed base; films are gaining share fastest in clean room infrastructure expansion.
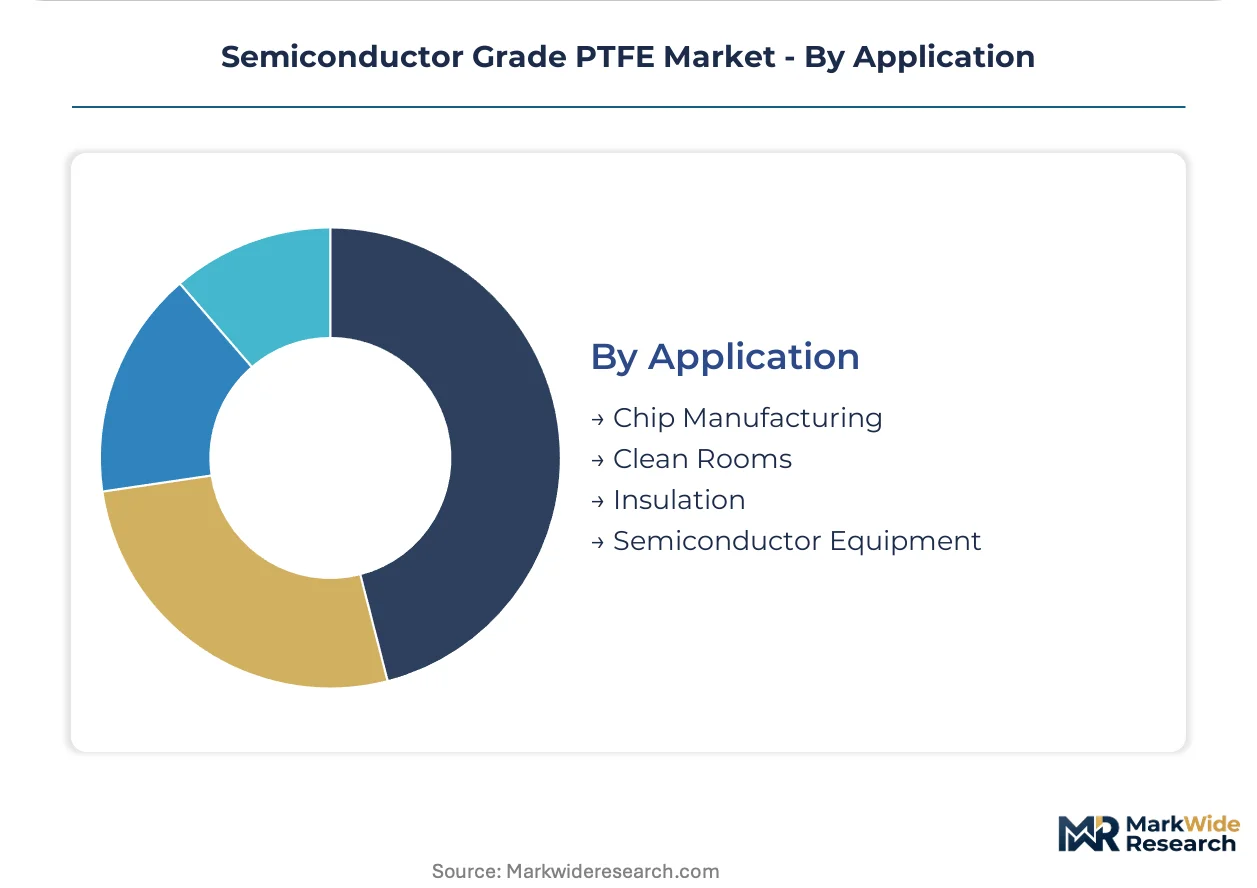
Application:
Customer type concentration splits procurement between captive fab engineering teams and independent equipment OEMs, with qualification timeline disparities locking in incumbent suppliers.
- Chip Manufacturing:Wafer etch, deposition, and cleaning processes consume PTFE chamber components, gas delivery tubing, and seals. Aggressive fluorine-based chemistries in advanced node production accelerate erosion and replacement frequency.
- Semiconductor Equipment:OEM manufacturing of process tools requires qualified component supply with eighteen to thirty-six month validation cycles. Japanese and South Korean equipment vendors are unbundling component specification from system integration contracts.
- Clean Rooms:Wall, ceiling, and equipment surface coatings demand ISO Class 1-3 purity certifications. METI semiconductor revitalization subsidies and South Korea's K-Semiconductor tax credits redirect regional demand toward domestic-qualified vendors.
- Insulation:Electrical and thermal insulation applications in RF generators and plasma sources access broader resin purity tiers. Performance specifications prioritize dielectric strength over metallic contamination thresholds.
Chip manufacturing anchors volume demand; clean room coatings are climbing the fastest as fab construction accelerates in India under PLI scheme incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for semiconductor grade PTFE concentrate in East Asian manufacturing corridors where captive resin production meets equipment fabrication demand. South Korea and Japan maintain structural surpluses in high-purity fluoropolymer supply, while the United States and Germany balance domestic consumption against specialized component trade.
South Korea
Samsung and SK Hynix fabs in the Pyeongtaek-Yongin corridor drive procurement of precision-extruded PTFE tubing for single-wafer etch tools. K-Semiconductor tax credits under the Ministry of Economy and Finance redirect capital toward domestic-qualified component vendors. The Seoul Capital Area anchors both memory production and specialized fluoropolymer compounding operations serving adjacent fab clusters.
Japan
Tokyo Electron and Shin-Etsu Chemical anchor demand for modified PTFE grades in chamber hardware requiring complex weld geometries. METI semiconductor revitalization subsidies prioritize domestic resin-to-part supply chain integrity. The Chubu region around Nagoya concentrates precision machining capabilities for gas distribution manifolds.
United States
Intel and Applied Materials facilities in Arizona and Oregon require REACH-equivalent purity certifications for export-qualified equipment. EPA hazardous air pollutant standards for fluoropolymer production impose abatement capital burdens at domestic resin plants. The Pacific Northwest hosts specialized clean room infrastructure coating applicators serving semiconductor construction.
Germany
Infineon and Bosch semiconductor operations in Saxony and Baden-Württemberg source PTFE components through qualified European distributors. ECHA REACH fluoropolymer restrictions disqualify standard-grade materials from wafer processing applications. The Eindhoven-adjacent corridor extends into North Rhine-Westphalia for gas delivery system integration.
China
Yangtze Memory Technologies and SMIC fabs in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor expand procurement despite import substitution pressures. MIIT domestic semiconductor targets accelerate local qualification of fluoropolymer vendors. The Pearl River Delta concentrates equipment assembly operations consuming standard-grade PTFE rod and sheet formats.
Semiconductor Grade PTFE Market Competitive Landscape
Concentration sits with integrated resin-to-part producers who control captive fluorine chemistry from acid-grade fluorspar through sub-ppb purification. Three archetypes define competitive positioning: diversified chemical conglomerates with vertical fluoropolymer chains, specialized fluoropolymer compounders dependent on merchant resin supply, and regional fabricators serving non-critical equipment tiers. Dominant competitive moves include backward integration into fluorspar mining concessions and strategic partnerships with wafer processing equipment OEMs to compress eighteen-month qualification timelines.
Within the integrated chemical conglomerate tier, Daikin Industries and The Chemours Company exemplify archetypes of geographic supply control. Daikin anchors Asia-Pacific high-purity resin production through captive fluorine operations. The Chemours occupies a position leveraging North American fluorspar access for standard-grade material supply. Gujarat Fluorochemicals Limited represents the cost-positioned regional specialist archetype serving tube extrusion demand in price-sensitive equipment categories.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries, Ltd. |
| AGC Inc. |
| 3M |
| Dongyue Group |
| Syensqo |
| Gujarat Fluorochemicals Limited |
| Shamrock Technologies |
| Solvay |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-thirty-six month fab qualification timelines for new PTFE component vendors compress pricing power toward incumbent resin producers with captive fluorine chemistry operations. This lead-time rigidity concentrates margin capture among integrated suppliers in Japan and South Korea while forcing compounders into price-competitive standard-grade segments. REACH and EPA volatile organic compound limits add certification cost layers that widen spreads between qualified and unqualified material tiers.
Pricing Analysis
Configured-to-order pricing for sub-ppb certified PTFE tubing commands substantial premiums over standard-grade sheet and rod formats. Three-tier pricing structure across premium, standard, and economy levels stratifies by metallic contamination thresholds and certification documentation depth. Cost compression in standard-grade segments is intensifying because Chinese equipment assemblers in the Pearl River Delta prioritize delivery speed over resin pedigree. Memory fabs in South Korea's Pyeongtaek-Yongin corridor exhibit lowest price sensitivity due to single-wafer tool downtime costs, while Indian PLI-scheme entrants negotiate hardest on tube extrusion contracts.
Supply Chain Analysis
Inventory buffers at wafer processing equipment OEMs rarely exceed sixty days given sub-ppb resin shelf-life constraints and fab just-in-time procurement protocols. Fluorspar mining concentrates in China and Mexico, with acid-grade ore drawing from Mexican Sonora deposits and Chinese Guizhou reserves. Metallic contamination thresholds below one part per billion rest on ion-exchange and distillation infrastructure vulnerable to power interruption at Japanese and South Korean purification plants. Distribution runs through qualified component distributors serving Tokyo Electron, Applied Materials, and Lam Research assembly facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor grade PTFE sits in early-cycle expansion as 3nm node production and single-wafer tool proliferation create fresh demand pools for precision-extruded tubing and modified weldable grades. India's PLI-scheme fab construction and South Korea's K-Semiconductor tax credits extend the adoption runway beyond current supply base capacity.
For Market Incumbents: Consolidate resin allocation priority through long-term offtake agreements with Samsung and SK Hynix before battery cell manufacturers capture equivalent fluoropolymer volumes. Expand Nagoya-area precision machining capabilities to capture unbundled gas manifold specification from Japanese equipment OEMs. Modified PTFE weldability patents and eighteen-month qualification timelines protect position against merchant resin compounders. For New Entrants and Emerging Players: Lead with clean room infrastructure coating applications where ISO Class 1-3 certification barriers are lower than wafer processing component qualification. Target Indian fab construction corridors under PLI incentives before domestic fluoropolymer vendors achieve local qualification. Position as specialized applicator serving Pacific Northwest Intel and Applied Materials facility expansion rather than competing directly on resin purity. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fluoropolymer purification assets and dormant medical-grade crossover certifications. Five-to-ten year viability hinges on resin producers' ability to pivot between semiconductor and battery end uses without purity dilution. Watch for SK Hynix or Samsung procurement team statements on dual-source qualification timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Secures acid-grade ore supply against Chinese export quota volatility for resin producers. |
| Modified PTFE Capacity Expansion | Captures premium pricing from Taiwan and South Korea chamber hardware weldability specifications. |
| Long-term Supply Agreement with Memory Fabs | Locks in tube volume commitments before battery manufacturers compete for identical resin pools. |
| EPA Abatement System Investment | Maintains US plant operating permits under hazardous air pollutant standards for fluoropolymer production. |
| Joint Venture with Indian Equipment Vendor | Accelerates PLI-scheme fab qualification timelines through local component fabrication partnerships. |
Research Methodology
Cross-validation between primary interviews with fluoropolymer plant managers and secondary customs trade data anchors the qualitative findings on resin allocation patterns. Technical R&D directors at Japanese and South Korean integrated resin-to-part producers, procurement leads at Tokyo Electron and Applied Materials, distribution channel partners serving German and US fab equipment markets, and clean room infrastructure contractors in the Pacific Northwest provided operational perspective. SEC 10-K filings, ECHA REACH substance dossiers, METI subsidy disclosure records, and Indian PLI scheme beneficiary lists furnished secondary validation. Bottom-up tube and sheet volume estimates triangulated against top-down wafer processing equipment capex disclosures.
Sensitivity analysis around fluorspar price volatility and qualification timeline compression shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include purity certification tier, product format, end-use industry, and regional production hub. CAGRs derive from equipment installation forecasts and replacement cycle intensity assumptions. Plasma chemistry aggressiveness in 3nm node production and single-wafer tool penetration rates serve as key forecast inputs.
Underlying assumptions cover stable REACH and EPA regulatory stringency, with deviation risk concentrated in perfluoroalkyl substance restriction acceleration or Chinese fluorspar export quota tightening. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Metallurgical Grade Silicon Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Chalcocite-Digenite Group Market
Semiconductor Material
Cadmium Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Europium Market
Semiconductor Material
Hafnium Market
Semiconductor Material
Silicon Metal Market