
 Centerless Grinding Market | 2026-2036
Centerless Grinding Market Size, Share, and Industry Trends Forecast 2026-2036
Centerless Grinding Market Analysis
Modular machine configurations that bundle automated loading, in-process gauging, and coolant filtration into single-platform offerings is hardening buyer preference toward integrated cell purchases rather than standalone grinder procurement. Cincinnati Machinery leverages its century-long installed base to sustain aftermarket parts revenue across North American automotive plants. Glebar competes through micro-grinding specialization in medical guidewire and catheter applications. JUNKER anchors European demand with high-volume through-feed systems serving tier-one bearing manufacturers.
Centerless grinding removes material from a workpiece without spindle or fixture constraints, using a regulating wheel and grinding wheel rotating in the same direction with differing speeds to achieve diametrical tolerances typically within 0.0001 inches. The process serves critical dimensioning for fuel injectors, hydraulic pistons, and orthopedic implant rods where roundness and surface integrity determine component lifespan. Through-feed centerless grinding dominates high-volume automotive and bearing production where continuous bar feeding maximizes throughput, while plunge grinding captures margin pools in aerospace and medical device work requiring complex profiles on interrupted cuts. Stainless steel and titanium material segments are expanding fastest as medical and aerospace specifications shift toward corrosion-resistant and high-strength alloys.
OSHA machine guarding standards and EPA metalworking fluid emissions rules shape equipment design requirements in the United States, while CE marking under the EU Machinery Directive governs European market access for automated grinding cells. FDA device manufacturing regulations and ISO 13485 quality standards drive validation protocols for medical-focused grinding operations. Stakeholders must monitor evolving carbon steel tariffs and titanium supply chain constraints that reshape material segment profitability and equipment specification trends.
Market Dynamics
Precision component manufacturers in automotive, aerospace, and medical device supply chains are consolidating equipment procurement around automated grinding cells that integrate loading, gauging, and filtration into single-platform configurations, compressing the standalone grinder market and elevating capital requirements for competitive participation.
Growth Catalysts
- EU Machinery Directive compliance cycles:Tighter surface-finish mandates under REACH and CE marking requirements are forcing European manufacturers to replace legacy equipment with precision centerless systems capable of sub-micron tolerance grinding.
- Medical guidewire demand:Catheter and stent manufacturers in Switzerland and the United States are expanding dedicated micro-grinding capacity to meet FDA device manufacturing regulations and ISO 13485 validation protocols.
- Titanium alloy specifications:Aerospace OEMs in Japan are specifying corrosion-resistant high-strength alloys for fuel injector and hydraulic piston components, driving material-specific grinding system upgrades.
Market Restraints
- Skilled operator scarcity:The specialized craft of regulating wheel setup and through-feed calibration requires years of apprenticeship, constraining output expansion even where capital is available.
- Coolant chemistry volatility:EPA metalworking fluid emissions rules and OSHA machine guarding standards in the United States are escalating compliance costs for smaller job shops without in-house environmental engineering.
- Grinding wheel supply concentration:Superabrasive bond formulations for titanium and stainless steel applications depend on concentrated synthetic diamond and CBN suppliers, creating input cost vulnerability.
Strategic Opportunities
- Indian bearing manufacturing expansion:Tier-one suppliers near Pune and Chennai are investing in high-volume through-feed systems to serve domestic automotive OEMs and export markets, creating greenfield equipment demand.
- Remanufacturing service models:Equipment builders can capture recurring revenue streams by offering spindle rebuild, control retrofits, and process optimization subscriptions to extend machine life cycles.
- Orthopedic implant rod growth:Aging demographics in Germany and Japan are expanding hip and knee replacement volumes, requiring precision-ground cobalt-chrome and titanium rods with validated surface integrity documentation.
Industry Challenges
- CNC programming specialization:Complex profile plunge grinding for aerospace interrupted cuts requires operators fluent in CAM systems and grinding parameter optimization, a skill set in short supply across Midwestern US manufacturing clusters.
- Validation timeline compression:FDA device manufacturing regulations and ISO 13485 quality standards demand extensive first-article inspection protocols, extending time-to-revenue for medical-focused grinding operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centerless Grinding Market |
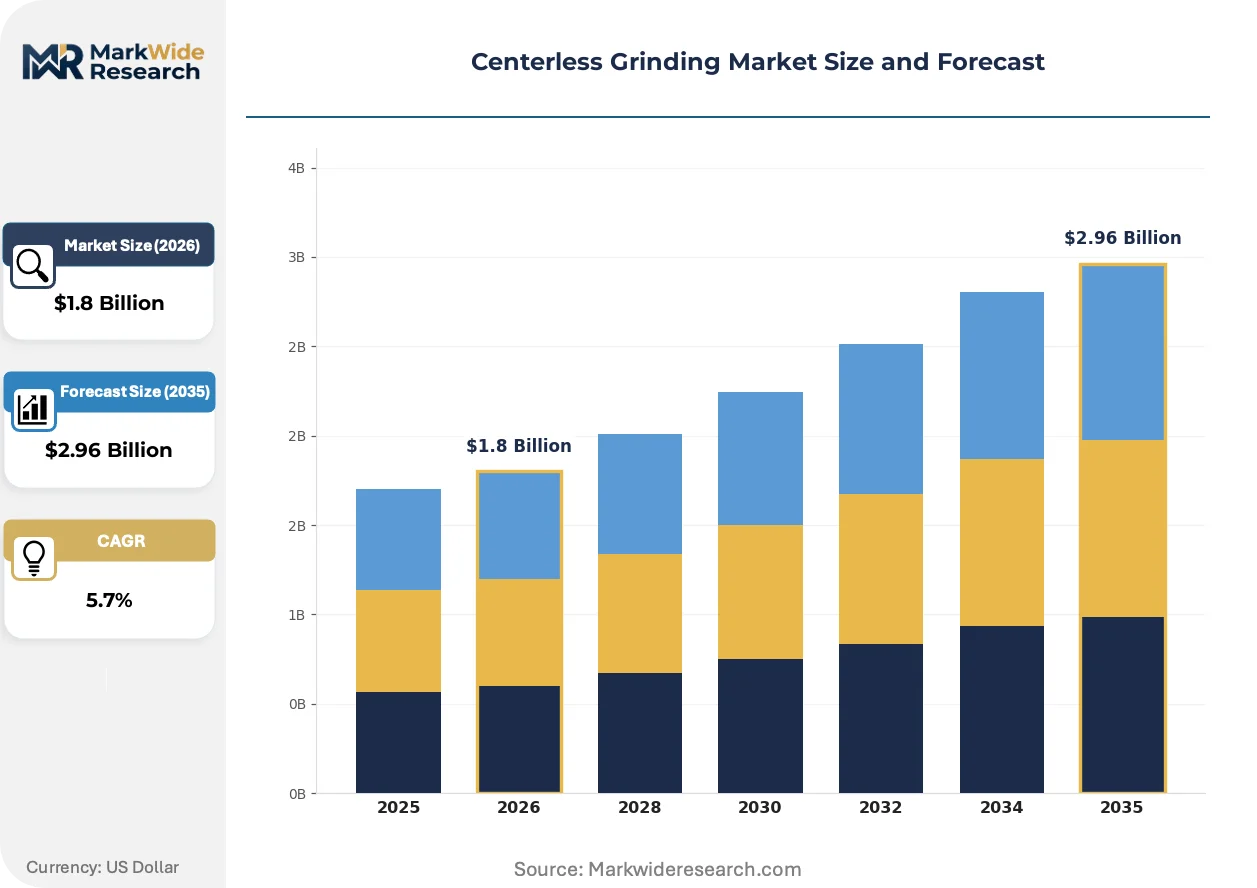
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive Components, Medical Devices, Metal Fabrication Type: Cylindrical, Plunge, Through-feed, Auto-feed Material: Stainless Steel, Aluminum, Titanium, Carbon Steel End User: Manufacturing, Construction, Defense, Electronics |
| Companies Covered | Fives Group, Cincinnati Machinery, Schaudt Mikrosa, Royal Master, Glebar, JUNKER, KMT Precision Grinding, Acme Manufacturing, Danobat Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centerless Grinding Market Emerging Trajectories
Machine tool builders are embedding artificial intelligence and advanced sensor arrays into centerless grinding platforms, enabling real-time process adjustment and predictive maintenance that shifts competitive advantage from mechanical precision to data-driven throughput optimization.
Adaptive control systems using in-process acoustic emission and force sensors are electrifying the transition from operator-dependent setup to autonomous grinding parameter adjustment. Medical device manufacturers in Massachusetts and Baden-Württemberg are deploying these systems fastest, compressing changeover times from hours to minutes and enabling economically viable batch sizes below fifty units.
REACH substance restrictions and the EU Green Deal's carbon border adjustment mechanisms are tightening requirements for metalworking fluid chemistry and energy consumption disclosure. German equipment builders are responding with minimum quantity lubrication systems and closed-loop coolant filtration that reduce waste volumes by orders of magnitude, though these configurations carry thirty to fifty percent capital premiums over conventional flood coolant designs.
Aftermarket service unbundling is fragmenting traditional equipment sale economics. Cincinnati Machinery and JUNKER are competing to attach remote diagnostics, spare part subscription tiers, and process engineering retainers to original equipment placements, converting capital transactions into recurring revenue relationships. This model is penetrating deepest among automotive component manufacturers in Michigan and Bavaria where plant consolidation has concentrated buying power among fewer procurement executives.
Centerless Grinding Market Segmentation
Centerless grinding equipment specifications diverge sharply across end-use requirements, with aerospace tolerances demanding sub-micron precision while automotive through-feed systems prioritize bar-feed throughput. Material hardness and thermal conductivity dictate wheel bond selection and coolant architecture, creating distinct equipment configurations that resist standardization.
Application:
Buyers in this category separate by certification burden and tolerance specification rather than unit volume alone.
- Aerospace:Interrupted cut profiles on titanium fuel injectors and hydraulic pistons require plunge grinding systems with adaptive force control. Japanese OEMs in Nagoya and German suppliers in Bavaria specify validated surface integrity documentation under FAA airworthiness directives and EASA certification protocols.
- Automotive Components:Continuous bar feeding of bearing races and drive shafts dominates equipment throughput metrics. Tier-one manufacturers near Stuttgart and Detroit deploy high-volume through-feed cells where regulating wheel calibration consistency determines line utilization rates.
- Medical Devices:Swiss guidewire producers and Massachusetts catheter manufacturers operate micro-grinding platforms under FDA device manufacturing regulations and ISO 13485 validation timelines.
- Metal Fabrication:General job shops across the American Midwest and India's Pune industrial corridor purchase versatile plunge-feed configurations for mixed-batch production.
Automotive Components leads volumes today; Medical Devices is gaining share fastest.
Type:
Equipment selection here tracks production economics—continuous flow versus complex geometry capability.
- Through-feed:Bar stock enters at one end and exits ground at diameter, enabling unattended operation for bearing and automotive shaft volumes. German equipment builders anchor European demand with systems serving tier-one bearing manufacturers in Schweinfurt.
- Plunge:The grinding wheel feeds radially into a profiled workpiece, capturing complex geometries for aerospace interrupted cuts and orthopedic implant rods. CNC programming specialization requirements constrain deployment to shops with CAM fluency.
- Cylindrical:Center-type grinding retains relevance for shaft work requiring shoulder features and tapers, though centerless configurations displace it in pure diameter reduction.
- Auto-feed:Robotic loading integration reduces operator dependency where skilled setup craft is scarce, particularly in Midwestern US manufacturing clusters facing apprenticeship pipeline gaps.
Through-feed dominates unit shipments; Plunge commands premium pricing per installation.
Material:
Thermal behavior and abrasiveness determine wheel wear rates and coolant chemistry requirements.
- Stainless Steel:Austenitic grades generate high grinding temperatures requiring synthetic diamond bonds and high-pressure coolant delivery. Medical device specifications in Switzerland and the United States favor 316L and 17-4 PH for corrosion-resistant guidewires and implant rods.
- Titanium:Low thermal conductivity concentrates heat at the cutting zone, demanding superabrasive wheels and minimum quantity lubrication systems. Aerospace OEMs in Japan specify Ti-6Al-4V for fuel injector components requiring fatigue resistance.
- Aluminum:Soft gumming tendency favors silicon carbide wheels and aggressive coolant flushing for general fabrication and electronics housing applications.
- Carbon Steel:Standard ferrous grinding with aluminum oxide wheels serves construction and general manufacturing where tariff volatility and scrap price swings reshape batch economics.
Carbon Steel retains volume leadership; Titanium shows steepest expansion trajectory.
End User:
Capital availability and in-house metrology capability separate procurement patterns in this category.
- Manufacturing:Precision component producers consolidate around automated grinding cells integrating gauging and filtration. Automotive, aerospace, and medical device supply chains compress standalone grinder markets through integrated platform procurement.
- Defense:Long validation timelines and ITAR export controls constrain equipment sourcing for US and European military component suppliers.
- Construction:Rebar and structural fastener grinding operates at lower precision tiers with reduced automation penetration.
- Electronics:Miniaturized connector pin and semiconductor equipment component grinding requires micro-feed precision in California and South Korean fabrication clusters.
Manufacturing absorbs the majority of precision system placements; Electronics shows climbing adoption rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The centerless grinding industry traces its commercial origins to Cincinnati, Ohio, where Cincinnati Machinery pioneered through-feed systems for automotive bearing production in the early twentieth century. This American foundation established technical standards that German and Japanese builders later refined for higher-precision applications.
Germany
Tier-one bearing manufacturers in Schweinfurt and Stuttgart drive demand for high-volume through-feed systems. The EU Machinery Directive and REACH substance restrictions mandate equipment upgrades with sub-micron tolerance capability. Baden-Württemberg's medical device cluster near Tuttlingen deploys micro-grinding platforms for orthopedic implant validation.
United States
Automotive component plants in Michigan and Ohio consolidate procurement around integrated grinding cells with automated loading. OSHA machine guarding standards and EPA metalworking fluid emissions rules shape equipment specifications. Massachusetts catheter manufacturers expand micro-grinding capacity under FDA device manufacturing regulations.
Japan
Aerospace OEMs in Nagoya specify Ti-6Al-4V titanium grinding systems for fuel injector fatigue resistance. METI industrial standards and JIS certification protocols govern equipment qualification. Chubu region suppliers invest in adaptive control systems for complex profile plunge grinding.
Switzerland
Guidewire producers in the Jura Arc and Lake Geneva region operate precision micro-grinding platforms for catheter applications. Swissmedic device regulations and ISO 13485 validation timelines constrain process changeover. Biel and Solothurn industrial zones concentrate dedicated medical grinding capacity.
India
Tier-one bearing suppliers near Pune and Chennai invest in high-volume through-feed systems for domestic automotive OEMs and export markets. BIS standards and the PLI scheme for manufacturing incentivize precision equipment adoption. Tamil Nadu's automotive corridor anchors greenfield grinding cell deployment.
Centerless Grinding Market Vendor Landscape
The competitive structure tilts toward heritage equipment builders with century-long installed bases sustaining aftermarket revenue streams. Cincinnati Machinery and JUNKER exemplify this archetype, leveraging replacement part dependencies and remanufacturing relationships to offset cyclical equipment sales. A second archetype comprises micro-grinding specialists targeting medical device validation requirements with process engineering retainers. A third group includes diversified machine tool conglomerates bundling grinding into broader metalworking portfolios. Dominant competitive moves center on service model unbundling—converting capital transactions into recurring diagnostics subscriptions—and geographic expansion through distributor networks in emerging manufacturing clusters.
Among American heritage builders, Cincinnati Machinery occupies a position exemplifying the installed-base archetype, while Glebar represents the medical-specialist vector with its Massachusetts concentration. JUNKER, a GmbH-structured European entity, anchors the high-volume through-feed segment serving tier-one bearing manufacturers. These three exemplify how competitive positioning fragments across technical specialization rather than consolidating around scale.
| Leading Market Players |
|---|
| Fives Group |
| Cincinnati Machinery |
| Schaudt Mikrosa |
| Royal Master |
| Glebar |
| JUNKER |
| KMT Precision Grinding |
| Acme Manufacturing |
| Danobat Group |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions and the EU Green Deal's carbon border adjustment mechanisms gate qualified supply for precision grinding equipment, permitting only builders with closed-loop coolant filtration and minimum quantity lubrication systems to access premium-tier pricing while relegating conventional flood-coolant configurations to commodity-margin tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automated grinding cells with integrated gauging and filtration from standalone through-feed systems and basic plunge configurations. Price differentiation hinges on ISO 13485 validation documentation for medical device applications and CE marking complexity under the EU Machinery Directive. Cost compression in the economy tier is intensifying because tariff volatility on carbon steel inputs squeezes job shop margins. Tier-one automotive bearing manufacturers in Germany and Japan exhibit lowest price sensitivity, while Midwestern US metal fabrication shops face acute budget constraints.
Supply Chain Analysis
Skilled operator scarcity across the American Midwest and India's Tamil Nadu automotive corridor constrains output expansion even where capital deployment is available. Superabrasive bond formulations for titanium and stainless steel applications draw from concentrated synthetic diamond and CBN suppliers in Japan and the United States. Single-source vulnerability in grinding wheel feedstock creates input cost spikes when aerospace OEMs accelerate Ti-6Al-4V specifications. Distribution runs through heritage equipment builders with century-long installed bases sustaining aftermarket parts revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through service model unbundling, as remote diagnostics subscriptions and process engineering retainers convert capital transactions into recurring revenue while reducing buyer sensitivity to upfront equipment pricing.
For Market Incumbents: Extend aftermarket service penetration by attaching spindle rebuild subscriptions and control retrofit packages to original equipment placements, defending against micro-grinding specialists capturing medical device validation revenue. Backward integration into superabrasive wheel production reduces dependency on concentrated Japanese and US bond suppliers.
For New Entrants and Emerging Players: The PLI scheme for manufacturing in India opens a window for greenfield grinding cell deployment near Pune and Chennai, where tier-one bearing suppliers seek high-volume through-feed systems without legacy installed-base obligations. Target medical guidewire producers in Switzerland's Jura Arc with ISO 13485-compliant micro-grinding platforms and process engineering partnerships.
For Investors and Strategic Acquirers: Roll-up economics work for heritage equipment builders with dense North American automotive installed bases because aftermarket parts dependency creates predictable revenue streams through replacement cycles. Watch for inflection when EPA metalworking fluid emissions rules trigger compliance-driven upgrade waves among smaller US job shops.
| Strategic Initiative | Industry Significance |
|---|---|
| Service Model Unbundling | Remote diagnostics subscriptions convert Cincinnati Machinery's installed base into recurring revenue. |
| Backward Integration | In-house superabrasive wheel production insulates JUNKER from synthetic diamond supply concentration. |
| Regulatory Certification Investment | ISO 13485 validation capabilities capture orthopedic implant rod demand in Germany and Japan. |
| Geographic Manufacturing Footprint | Tamil Nadu production hubs serve Indian automotive OEMs under BIS standards and PLI incentives. |
| Adaptive Control System Deployment | AI-enabled grinding parameter adjustment compresses medical device changeover times in Massachusetts. |
Methodological Framework
Coverage spans Germany, Japan, the United States, Switzerland, and India, with primary inputs from each market gathered through structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at precision component manufacturers. Secondary validation draws from SEC 10-K filings, METI industrial standards documentation, BIS equipment certification records, and EU Machinery Directive compliance databases. Bottom-up equipment shipment data triangulates against top-down automotive and aerospace production forecasts.
Granularity-level modeling disaggregates volume and value outputs by application, type, material, and end user, with additional dimensioning for regional regulatory clusters and certification burden tiers. CAGRs across the analysis window derive from regression against automotive bearing production indices, medical device implant procedure volumes, and aerospace OEM titanium specification trends. Industry-specific forecast inputs include through-feed system utilization rates at tier-one bearing manufacturers and micro-grinding platform deployment timelines under FDA device manufacturing regulations.
Revisions become necessary when carbon steel tariffs shift materially, titanium supply chain constraints intensify, or EPA metalworking fluid emissions rules escalate compliance costs beyond modeled thresholds. Material deviation in these triggers warrants pause and re-evaluation of equipment demand assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Tools
Jigs and Other Tools Market
Industrial Tools
Global Tool Presetters Market
Industrial Tools
Digital Tool Presetter Market
Industrial Tools
Industrial Wire Stripping Machine Market
Industrial Tools
Tool Holder Market
Industrial Tools
Coordinate Measuring Machine Market
Industrial Tools
Deburring Machine Market
Industrial Tools
Drill Drivers Market
Industrial Tools
India Power Tool Market
Industrial Tools
Tool Wire Cutters Market
Industrial Tools
Die Grinders Market
Industrial Tools
Height Gauge Market
Industrial Tools
Dies, Jigs and Other Tools Market
Industrial Tools
Precision Components and Tooling Systems Market
Industrial Tools
Insulated Screwdriver Market
Industrial Tools
Plasma Arc Cutting Market