
 Global Polybutylene Terephthalate (PBT) Market | 2026-2036
Global Polybutylene Terephthalate (PBT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polybutylene Terephthalate (PBT) Market Foresight
Market Context
Polymer engineering talent scarcity in compounding and flame-retardant formulation is bifurcating the competitive landscape into integrated resin producers and specialized compounders. BASF SE leverages its Ludwigshafen Verbund site to sustain captive supply of adipic acid precursors for PBT polymerization. Mitsubishi Chemical Corporation anchors its position through proprietary catalyst technologies that enable low-VOC grades for interior automotive applications. SABIC competes via its Yanbu facility, which controls feedstock integration from purified terephthalic acid through to modified resin outputs.
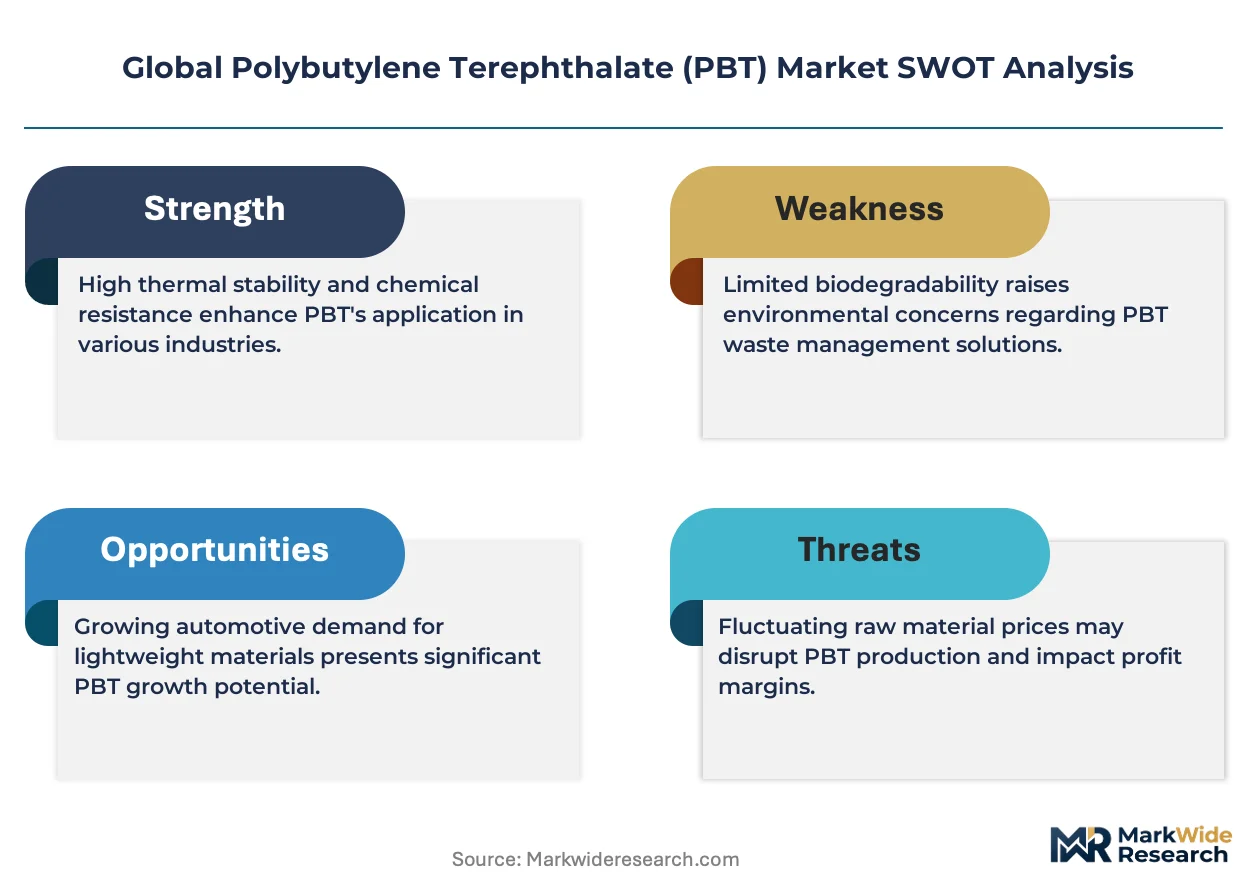
Polybutylene terephthalate is a semi-crystalline thermoplastic polyester produced through polycondensation of 1,4-butanediol with terephthalic acid, exhibiting melting points between 220°C and 267°C depending on copolymer content, and serving primarily as a dimensionally stable, moisture-resistant engineering resin for precision injection-molded components. Glass-Filled PBT dominates volume applications where stiffness and heat deflection temperatures above 200°C are mandatory, particularly in automotive under-hood connectors. Flame-Retardant PBT represents the fastest-expanding formulation segment as OEM Manufacturers face UL 94 V-0 requirements without halogenated additives, creating margin pools for compounders with certified phosphorus-based systems.
EPA regulations under TSCA Section 6 are restricting decabromodiphenyl ether in electrical housings, while REACH Annex XVII limitations on halogenated compounds are shaping European formulation roadmaps toward phosphorus-nitrogen synergists. China's GB standards through SAMR are tightening flame-retardant labeling requirements for consumer electronics enclosures, directly impacting export-oriented PBT compounders. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional product variants or unified global formulations offer superior returns.
Market Dynamics
Automotive electrification is compressing development cycles for connector-grade PBT formulations, forcing compounders to synchronize resin certification timelines with platform launches from battery-electric vehicle programs. This pressure is redistributing margin pools toward flame-retardant specialists capable of halogen-free UL 94 V-0 compliance.
Growth Catalysts
- REACH Annex XVII restrictions on halogenated flame retardants:European OEMs are accelerating qualification of phosphorus-nitrogen PBT systems for electrical housings, expanding addressable market for certified compounders.
- Electric vehicle connector demand:High-voltage battery architectures require moisture-resistant, dimensionally stable housings that glass-filled PBT delivers at scale.
- China's GB standard enforcement through SAMR:Tightened labeling requirements for consumer electronics are redirecting export-oriented compounders toward certified resin streams.
Market Restraints
- Purified terephthalic acid supply concentration:Feedstock integration at Asian petrochemical complexes limits independent compounder access to cost-competitive monomer.
- Polycondensation catalyst scarcity:Proprietary titanium-based systems for low-VOC automotive grades remain concentrated among integrated resin producers.
- Polyamide 6/6 substitution in high-temperature connectors:PA66's superior heat deflection above 240°C is capturing select under-hood applications from glass-filled PBT.
Strategic Opportunities
- India's PLI scheme for automotive components:Localization incentives are attracting PBT compounders to establish compounding operations near Chennai and Pune manufacturing clusters.
- Recycled-content PBT for consumer electronics:Post-industrial regrind streams from fiber optic scrap are qualifying for EPEAT certification in laptop chassis applications.
- Phosphorus-based flame retardant convergence with laser-direct structuring:Modified PBT grades enabling antenna integration in 5G small cell housings are commanding formulation premiums.
Industry Challenges
- Flame-retardant formulation chemist scarcity:Expertise in phosphorus-nitrogen synergist systems for UL 94 V-0 compliance without halogens remains concentrated among a narrow technical cohort.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA Section 6, REACH Annex XVII, and China GB standard compliance is extending product qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polybutylene Terephthalate (PBT) Market |
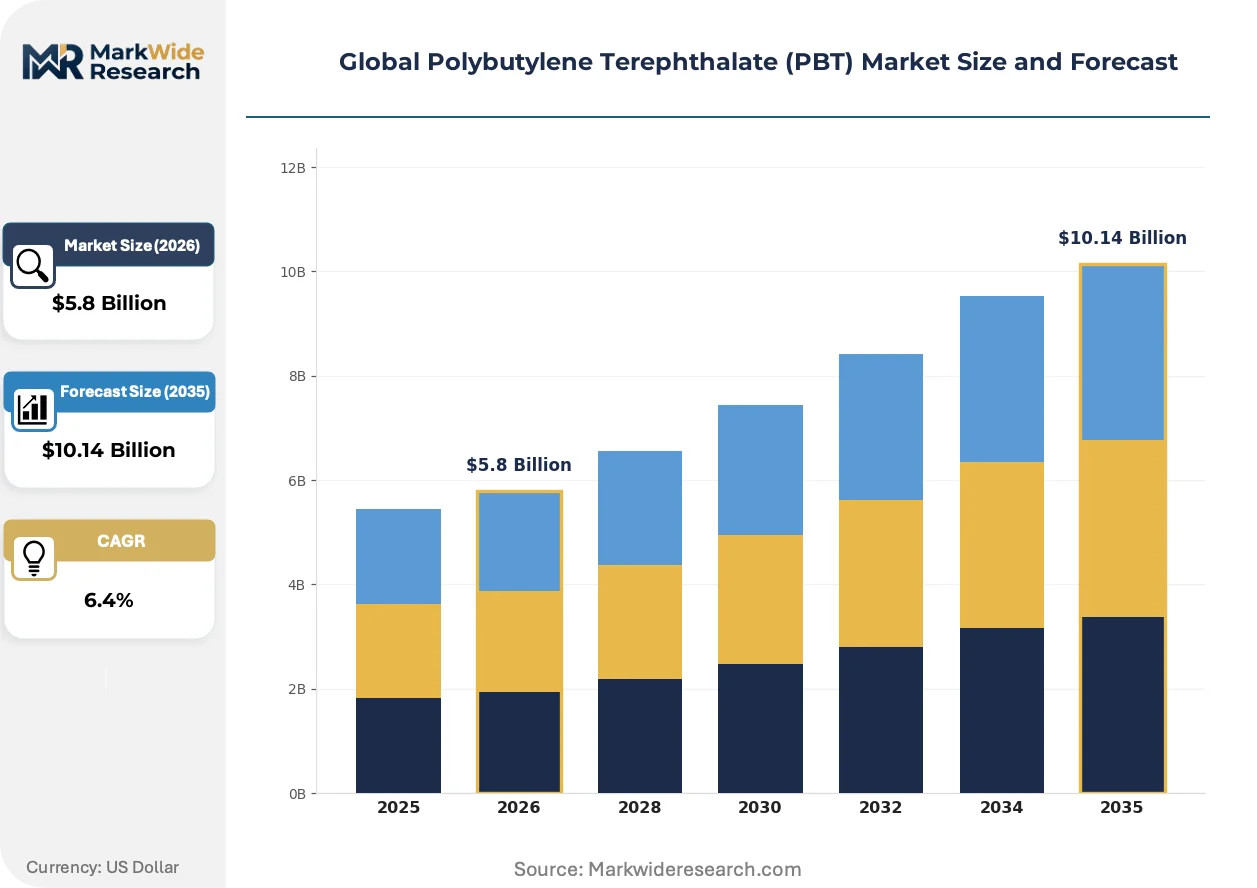
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PBT, Glass-Filled PBT, Heat-Stabilized PBT, Flame-Retardant PBT, High-Flow PBT Application: Electrical Components, Automotive Parts, Consumer Electronics, Industrial Machinery, Household Appliances End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Service Providers, Component Distributors, Engineering Firms Form: Pellets, Powders, Films, Sheets, Granules |
| Companies Covered | Celanese Corporation, Evonik Industries AG, Chang Chun Group, Lanxess AG, Koninklijke DSM N.V., BASF SE, Hengli Group Co. Ltd., Mitsubishi Chemical Corporation, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polybutylene Terephthalate (PBT) Market Shifts & Advancements
Formulation chemistry and regulatory compliance are converging to redefine competitive advantage in engineering thermoplastics. Three developments are compressing traditional development cycles and redistributing value capture across the supply chain.
Bio-based 1,4-butanediol derived from renewable feedstocks is displacing petroleum-derived monomer in premium PBT grades targeted at carbon-conscious automotive OEMs. European and Japanese automakers are specifying mass-balance-certified resins for interior trim components. This displacement is compressing the cost premium between conventional and sustainable PBT formulations from historical 40-50% spreads toward 15-20% parity.
EPA TSCA Section 6 restrictions on decabromodiphenyl ether are accelerating reformulation of electrical housing grades across North American appliance and tool manufacturers. The industrial consequence is a qualification backlog at third-party testing laboratories for phosphorus-based alternatives. Consumer electronics OEMs with export exposure to European markets are responding by consolidating supplier bases around compounders with dual REACH and TSCA certification.
Direct resin purchasing from automotive Tier-1 connectors is consolidating procurement decisions previously fragmented across multiple molding subcontractors. This disintermediation is compressing price negotiation cycles and transferring formulation specification authority to platform engineering teams. The shift is most visible in Germany and South Korea, where Volkswagen Group and Hyundai Motor Company have centralized resin qualification at the OEM level.
Global Polybutylene Terephthalate (PBT) Market Segmentation
PBT formulations diverge sharply in their vulnerability to polyamide substitution, with thermal performance and flame-retardant certification determining which grades defend their application footholds. Segment boundaries are hardening around regulatory compliance tiers rather than traditional performance metrics.
Product Type:
Substitution pressure from polyamides and polyphenylene sulfide intensifies as operating temperatures climb, forcing each formulation to defend its technical-economic position.
- Glass-Filled PBT:Reinforced with 10-30% glass fiber to achieve flexural modulus above 8 GPa and heat deflection temperatures exceeding 200°C. Automotive under-hood connectors in Germany and South Korea specify this grade for dimensional stability against thermal cycling. Polyamide 6/6 captures marginal share above 240°C service temperatures.
- Flame-Retardant PBT:Phosphorus-nitrogen synergist systems achieve UL 94 V-0 at 0.8mm without halogenated additives. Consumer electronics OEMs in China face SAMR labeling mandates that favor certified compounders with dual REACH and TSCA documentation.
- Standard PBT:Unfilled base resin with 220-230°C melting range serves cost-sensitive industrial applications where moisture resistance trumps mechanical load.
- Heat-Stabilized PBT:Hindered phenol antioxidant packages extend long-term thermal aging performance for continuous service above 150°C.
- High-Flow PBT:Reduced viscosity grades enable thin-wall molding below 0.5mm for miniaturized connector geometries.
Glass-Filled PBT retains volume leadership; Flame-Retardant PBT holds the steepest expansion curve.
Application:
Electrification intensity and regulatory exposure split applications into high-margin specification battles versus commodity procurement cycles.
- Electrical Components:Circuit breaker housings, relay bases, and terminal blocks demand tracking resistance above 600V per IEC 60112. EPA TSCA Section 6 restrictions on decabromodiphenyl ether force reformulation timelines that favor pre-certified compounders.
- Automotive Parts:High-voltage battery connectors and sensor modules require moisture absorption below 0.1% to prevent electrical leakage. Volkswagen Group and Hyundai Motor Company centralize resin qualification at OEM level, disintermediating traditional Tier-2 procurement.
- Consumer Electronics:Laptop chassis and smartphone structural frames drive laser-direct structuring compatibility for 5G antenna integration.
- Industrial Machinery:Pump housings and valve components prioritize chemical resistance to automotive fluids and industrial lubricants.
- Household Appliances:Coffee machine housings and dishwasher components specify food-contact compliant grades with low VOC emissions.
Automotive Parts commands the highest formulation premiums; Electrical Components expands most quickly on regulatory-driven replacement cycles.
End User:
Procurement authority is migrating upstream from molders to platform engineers, restructuring how formulation specifications enter production pipelines.
- OEM Manufacturers:Automotive and electronics brand owners increasingly direct resin qualification through centralized materials engineering teams. Direct purchasing contracts compress price negotiation cycles and demand global formulation consistency.
- Tier-1 Suppliers:Connector specialists like Aptiv and TE Connectivity maintain formulation specification authority for proprietary housing designs. Margin pressure from OEM consolidation forces inventory reduction and vendor base narrowing.
- Aftermarket Service Providers:Repair and replacement channels prioritize inventory availability over performance optimization, favoring standard grades with shorter lead times.
- Component Distributors:Digi-Key and Mouser Electronics stock certified flame-retardant grades for rapid prototyping and low-volume production.
- Engineering Firms:Design consultancies specify PBT for custom industrial equipment where metal replacement drives material selection.
OEM Manufacturers concentrate procurement leverage; Tier-1 Suppliers face the steepest margin compression from upstream authority shifts.
Form:
Processing economics and part geometry requirements determine form selection, with pellet dominance eroding only in specialized film and sheet applications.
- Pellets:Standard cylindrical extrusion feedstock with 2-4mm diameter serves injection molding at throughputs exceeding 500 kg/hour. Automotive and electronics manufacturing clusters in China, Germany, and South Korea consume pellet volumes at scale.
- Films:Biaxially oriented PBT achieves tensile strength above 200 MPa for flexible circuit substrates and insulation layers.
- Powders:Rotational molding and coating applications utilize finely ground resin for complex hollow geometries.
- Sheets:Thermoforming feedstock for equipment housings and structural panels requires uniform thickness tolerance below 5%.
- Granules:Irregular regrind particles from post-industrial scrap feed recycling streams for non-critical applications.
Pellets retain volume leadership; Films gains share fastest on flexible electronics expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR enforces GB standards that redirect PBT formulation strategies across Asia, while REACH Annex XVII in Europe and EPA TSCA Section 6 in North America create divergent compliance pathways. Resin producers must navigate this regulatory fragmentation to maintain cross-border supply chains.
China
Electric vehicle production scales in parallel with domestic resin capacity expansion. GB standards through SAMR tighten flame-retardant labeling for consumer electronics exports. Manufacturing clusters in Shanghai and Guangdong Province concentrate compounding operations near BYD and CATL battery assembly plants.
Germany
Automotive OEMs centralize resin qualification at the platform engineering level. REACH Annex XVII restrictions on halogenated compounds accelerate phosphorus-nitrogen PBT adoption. The Ludwigshafen chemical complex anchors integrated production from purified terephthalic acid through modified resin outputs.
United States
EPA TSCA Section 6 restrictions on decabromodiphenyl ether force electrical housing reformulation cycles. Appliance and power tool manufacturers consolidate supplier bases around dual-certified compounders. Michigan and Ohio automotive corridors drive connector-grade PBT consumption for EV platform launches.
Japan
METI promotes low-VOC material specifications for interior automotive applications. Proprietary titanium-based catalyst technologies enable premium grades with reduced emissions. The Nagoya industrial zone concentrates precision molding operations supplying Toyota and Honda electrification programs.
South Korea
Hyundai Motor Company and Kia Corporation centralize materials engineering decisions at the OEM level. MFDS maintains alignment with REACH-equivalent chemical safety standards. The Gyeonggi-do province hosts battery connector manufacturing clusters serving domestic EV export markets.
Global Polybutylene Terephthalate (PBT) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that captures margin pools in certified flame-retardant formulations. European and Asian petrochemical conglomerates control feedstock integration from terephthalic acid through polymerization. Strategic archetypes include captive supply operators, halogen-free formulation specialists, and regional compounders serving automotive qualification pipelines. Dominant competitive moves center on backward integration into purified terephthalic acid supply and certification pre-positioning across EPA, REACH, and GB standard regimes.
Within the integrated leader tier, BASF SE and Mitsubishi Chemical Corporation exemplify divergent geographic anchoring strategies. SABIC occupies a position bridging Middle Eastern feedstock access with Asian compounding demand. These three entities represent distinct archetypes: European Verbund-site integration, Japanese catalyst technology specialization, and Saudi Arabian feedstock-to-resin vertical control.
| Leading Market Players |
|---|
| Celanese Corporation |
| Evonik Industries AG |
| Chang Chun Group |
| Lanxess AG |
| Koninklijke DSM N.V. |
| BASF SE |
| Hengli Group Co. Ltd. |
| Mitsubishi Chemical Corporation |
| SABIC |
| Others |
Supply & Pricing Matrix
REACH Annex XVII and EPA TSCA Section 6 compliance gates simultaneously qualify suppliers for premium electrical housing contracts while stratifying price tiers around certification status. Compounders with dual-certified phosphorus-nitrogen formulations command formulation premiums over uncertified competitors, compressing margins for regional players lacking testing laboratory relationships.
Pricing Analysis
Long-term offtake agreements dominate procurement between integrated resin producers and automotive OEMs, insulating volume pricing from purified terephthalic acid spot volatility. Price differentiation rests on UL 94 V-0 certification tier and glass fiber loading percentage, with halogen-free flame-retardant grades capturing the widest spreads. Cost compression in standard unfilled resin is intensifying because Chinese domestic capacity expansion outpaces regional demand growth. Tier-1 connector manufacturers exhibit lowest price sensitivity; aftermarket distributors face the steepest procurement pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for European compounders sourcing modified resins from Chinese polymerization facilities. Supply concentrates in China, Germany, and Saudi Arabia, with feedstock integration at Asian petrochemical complexes limiting independent compounder access to cost-competitive monomer. Raw material dependencies center on purified terephthalic acid, 1,4-butanediol, and titanium-based polycondensation catalysts. Single-source vulnerability in proprietary catalyst technologies from Mitsubishi Chemical Corporation and select integrated producers threatens supply continuity for low-VOC automotive grades. Distribution runs through direct OEM purchasing contracts and authorized distributor networks serving rapid-prototyping channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority consolidation at Volkswagen Group and Hyundai Motor Company platform engineering teams has shifted buyer power upstream, fragmenting traditional Tier-2 molding subcontractor influence over resin specification.
For Market Incumbents: Secure captive supply of adipic acid precursors through backward integration or long-term offtake with petrochemical complexes. BASF SE's Ludwigshafen Verbund model demonstrates how feedstock control defends margin position against polyamide 6/6 substitution in high-temperature connector applications. Certification investment in dual REACH-TSCA phosphorus-nitrogen systems remains the critical lever for electrical housing premium retention. For New Entrants and Emerging Players: UL 94 V-0 fast-track qualification through third-party laboratory partnerships enables rapid entry into consumer electronics export supply chains serving SAMR-compliant Chinese manufacturers. India's PLI scheme for automotive components offers the most penetrable geography, with Chennai and Pune manufacturing clusters lacking localized flame-retardant compounding capacity. A technical-service-heavy go-to-market model targeting Tier-1 connector designers bypasses entrenched OEM-direct relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across halogen-free flame-retardant formulation segments as multi-jurisdiction certification timelines extend qualification cycles. The viable acquisition archetype centers on mid-scale compounders with pre-certified phosphorus-nitrogen systems and established automotive OEM technical relationships. The signal to watch is EPA TSCA Section 6 enforcement acceleration against decabromodiphenyl ether, which would force immediate reformulation demand and strain third-party testing laboratory capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purified Terephthalic Acid | BASF SE's Ludwigshafen complex demonstrates captive feedstock control insulating margin from monomer price volatility. |
| Dual-Certification Fast-Track Investment | REACH Annex XVII and EPA TSCA Section 6 pre-qualification opens electrical housing contracts with export-exposed OEMs. |
| Regional Compounding Localization | India's PLI scheme attracts operations near Chennai automotive clusters reducing logistics exposure. |
| Phosphorus-Nitrogen Formulation R&D Expansion | Proprietary synergist systems defend technical moats against commodity flame-retardant substitution. |
| Direct OEM Technical Partnership | Hyundai Motor Company's centralized materials engineering rewards compounders with platform-level specification authority. |
Research Methodology
Operator-level perspectives from resin plant managers, automotive Tier-1 procurement leads, flame-retardant formulation chemists, and third-party testing laboratory directors anchored the qualitative base. Primary interviews combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings of listed chemical producers, and SAMR GB standard documentation. Bottom-up resin consumption estimates by application triangulated against top-down polymerization capacity assessments across major production hubs.
Sensitivity analysis around electric vehicle platform launch timelines and regulatory enforcement probability informed scenario-weighted projections across the analysis window. Segmentation dimensions modeled include formulation grade tier, end-use industry vertical, flame-retardant certification status, and regional production cluster. CAGRs derived from regression against historical polymer demand elasticities and automotive content-per-vehicle trajectories. Industry-specific forecast inputs incorporated battery-electric vehicle connector density assumptions and phosphorus-based additive supply constraints.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive electrification and phased halogenated flame-retardant restriction; material deviation would warrant model refresh. Forecasts reflect assumptions of continued REACH Annex XVII enforcement trajectory and SAMR GB standard alignment with European chemical safety thresholds. Specific risk factors include polyamide 6/6 technical substitution above 240°C service temperatures and titanium catalyst supply concentration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Barium Titanate Market