
 Fullerene Market | 2026-2036
Fullerene Market Size, Share, and Industry Trends Forecast 2026-2036
Fullerene Market Intelligence
The push for material efficiency under frameworks like the EU's REACH regulation and China's dual carbon goals is repositioning fullerene applications in high-performance sectors. Nano-C specializes in the production of high-purity fullerenic materials for electronics. Frontier Carbon Corporation leverages its scale in manufacturing carbon nanotubes and other fullerene structures. Mitsubishi Chemical Holdings operates with a focus on integrating these materials into advanced polymer and composite applications.
Fullerenes are a class of carbon allotropes composed entirely of carbon, forming a hollow sphere, ellipsoid, or tube. Structures like the C60 buckminsterfullerene feature unique electronic and physical properties, making them valuable in advanced materials science. While the C60 product type remains foundational, functionalized fullerenes are gaining traction for specialized uses. Applications in drug delivery systems and high-performance lubricants represent significant areas of commercial development and investment.
The US FDA scrutinizes fullerene use in biomedical applications, particularly for drug delivery systems. In parallel, compliance with material safety standards set by Europe's ECHA and Japan's METI governs industrial market access. Stakeholder focus remains on balancing the high cost of purification with the performance demands of emerging end-user industries. This decision point dictates the commercial viability of new fullerene-based products.
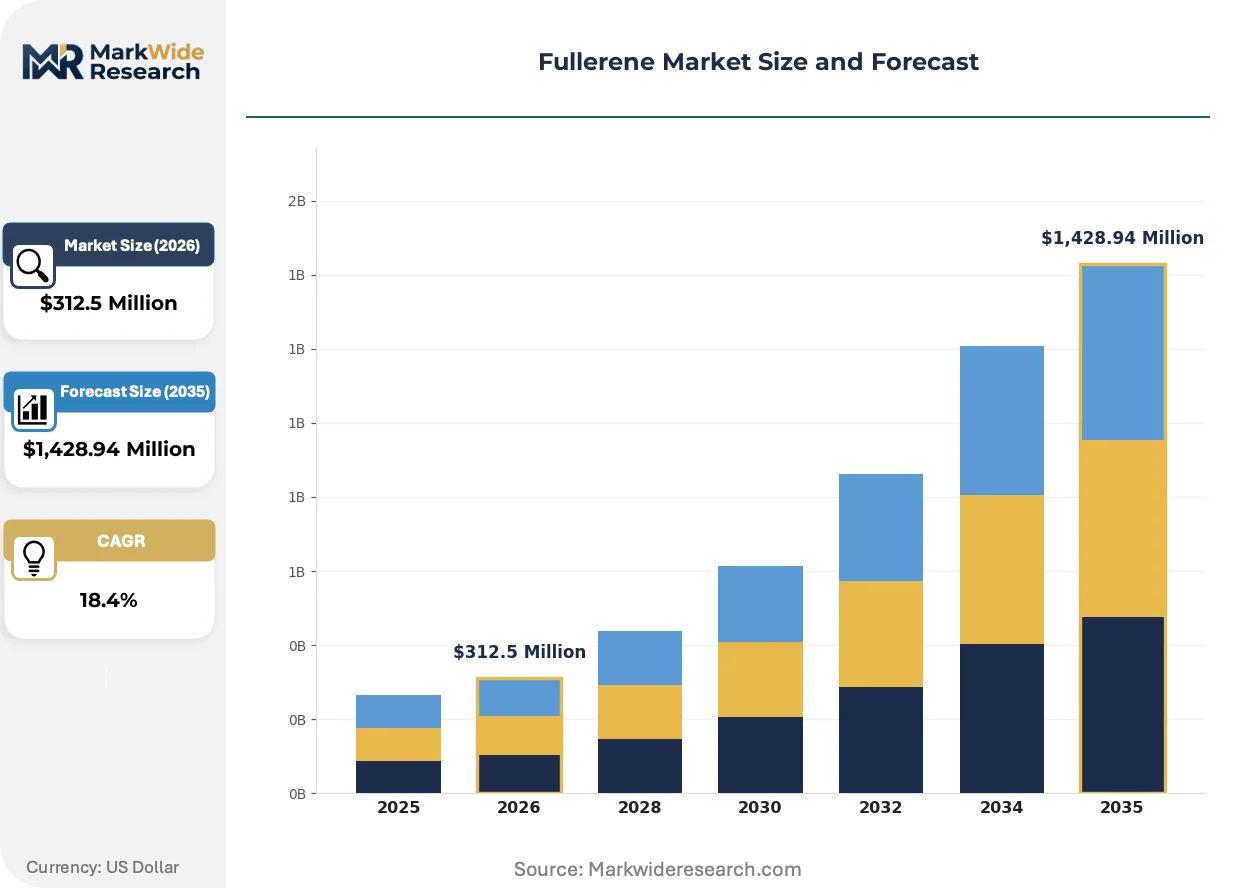
Market Dynamics
The central tension shaping the fullerene market is the push for production scalability against the rising demand for highly purified, functionalized materials. Advances in chemical vapor deposition are critical, but the high cost of purification remains a barrier, creating a decision point between volume production and high-margin specialization for end-users.
Growth Catalysts
- Organic Photovoltaics Demand:The expansion of the organic photovoltaics (OPV) industry serves as a primary demand driver, requiring high-purity fullerenes as electron acceptors to improve solar cell efficiency and stability.
- Advanced Production Methods:Progress in Chemical Vapor Deposition (CVD) and other synthesis techniques is improving the scalability and cost-effectiveness of producing complex fullerene structures beyond basic C60, opening new commercial pathways.
- Supportive Industrial Policies:Frameworks like China's dual carbon goals and the EU's focus on material efficiency encourage the use of high-performance materials like fullerenes in sectors from electronics to advanced composites.
Market Restraints
- High Purification Costs:The significant expense associated with separating and purifying specific fullerene isomers, particularly for high-purity grades required in electronics and pharmaceuticals, limits broader adoption and price competitiveness against alternative materials.
- Regulatory Scrutiny:Stringent evaluation by bodies such as the US FDA for biomedical uses and ECHA in Europe for industrial applications creates long development timelines and high compliance burdens, slowing commercialization.
- Technical Production Hurdles:While foundational C60 production is mature, scaling the synthesis of endohedral or functionalized fullerenes with consistent quality remains a significant technical challenge, constraining supply for specialized applications.
Strategic Opportunities
- High-Performance Lubricants:Formulating fullerene-based additives for industrial and automotive lubricants represents a significant opportunity, offering superior performance in extreme pressure and temperature environments where conventional lubricants fail.
- Advanced Biomedical Applications:Beyond drug delivery, opportunities exist in developing fullerenes for use as contrast agents in medical imaging and as antioxidant therapies, pending successful clinical trials and regulatory approvals.
- Hybrid Carbon Materials:The convergence of fullerenes with other carbon allotropes like graphene and carbon nanotubes allows for the creation of hybrid materials with unique synergistic properties for next-generation composites and electronics.
Industry Challenges
- Standardization Deficit:A lack of globally recognized standards for fullerene characterization, purity, and functionalization creates transactional friction and complicates quality assurance for end-users in performance-critical industries like aerospace and medicine.
- Intellectual Property Complexity:The landscape of patents covering fullerene synthesis, purification, and application is dense, creating potential licensing challenges and litigation risks for new market entrants and innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fullerene Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,428.94 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: C60, C70, Carbon Nanotubes, Carbon Nanohorns, Functionalized Fullerenes Technology: Arc Discharge, Laser Ablation, Chemical Vapor Deposition, Solvent Extraction, Ball Milling Application: Organic Photovoltaics, Drug Delivery Systems, Lubricants, Catalysts, Superconductors End User Industry: Electronics Manufacturing, Pharmaceutical Firms, Lubricant Producers, Chemical Processing, Renewable Energy |
| Companies Covered | Nanotech Industrial Solutions, BuckyUSA, Nano-C, MTR Ltd, MER Corporation, SES Research Inc., IoLiTec Ionic Liquids Technologies GmbH, Frontier Carbon Corporation, Mitsubishi Chemical Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fullerene Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from foundational C60 to application-specific functionalized fullerenes. This shift is driven by the dual forces of technological capability in materials science and increasing regulatory demands for substance characterization and safety, particularly in biomedical and electronics applications.
Functionalized fullerenes are carbon cages modified with external chemical groups to tailor their solubility and electronic properties for specific tasks. The biomedical and semiconductor industries are steadily adopting these materials for drug delivery systems and organic thin-film transistors. This focus on tailored structures is absorbing research and development capital previously allocated to scaling basic C60, altering the industry's value chain.
Europe’s REACH regulation imposes strict data requirements on all chemical substances, including nanomaterials like fullerenes, manufactured or imported into the EU. This legislation forces producers to generate extensive toxicological and environmental impact data, increasing the cost and complexity of market access. The industrial coatings and composites segments are most impacted, now integrating lifecycle assessments into their product development to ensure compliance.
A notable behavioral shift is occurring as end-users in sectors like photovoltaics and cosmetics demand lot-to-lot consistency and application-specific certifications. This change diminishes the role of bulk chemical distributors and favors suppliers who can provide extensive characterization data and collaborate on formulation. This trend is most prominent in materials science clusters in Japan and Germany, where material performance is directly tied to final product value.
Fullerene Market Segmentation
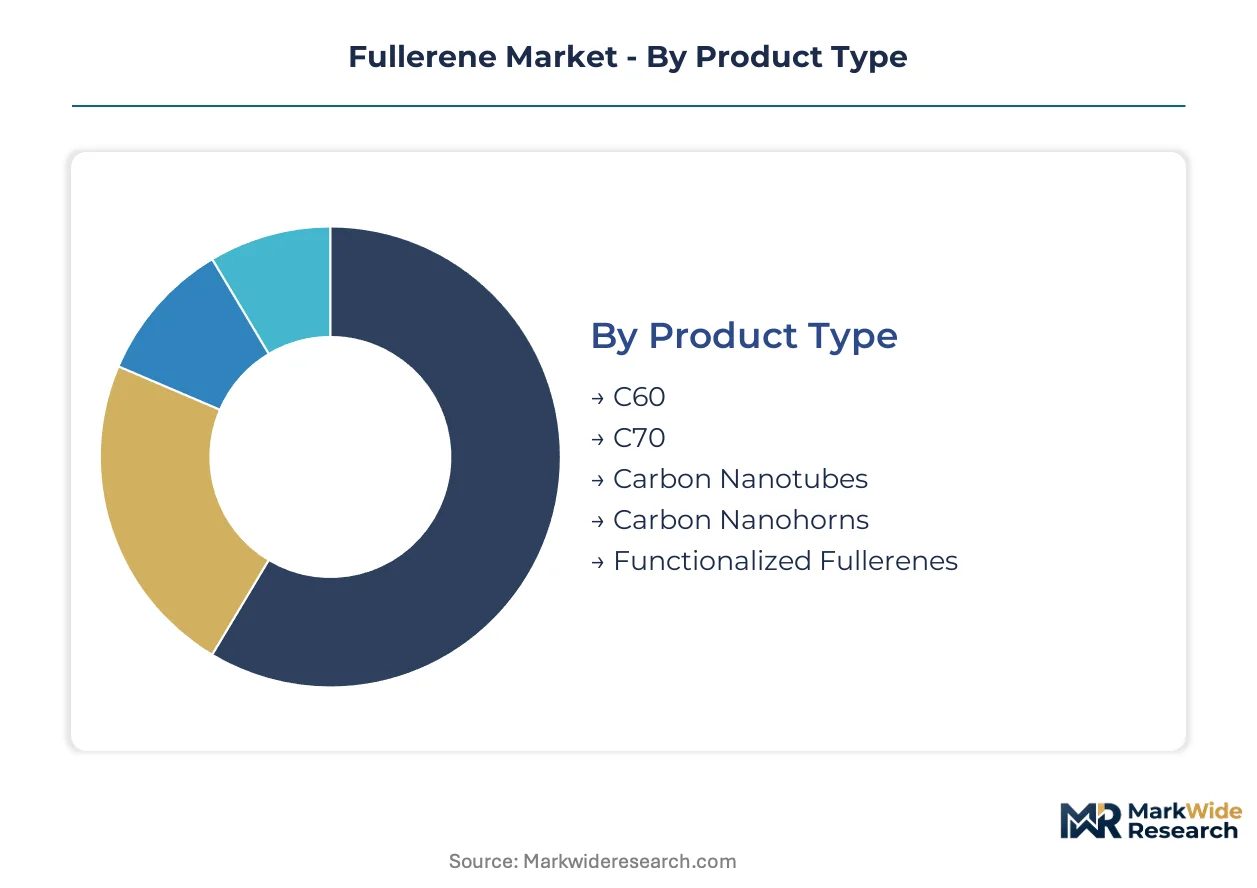
The Fullerene Market segmentation reflects the diverse forms and specialized applications of these carbon allotropes. Understanding these distinct segments is essential for stakeholders to identify high-growth areas and navigate the complex technical and regulatory landscapes.
Product Type:
Certification burdens significantly shape the market for fullerene product types, with specific regulatory approvals dictating commercial viability.
- Functionalized Fullerenes:These modified carbon cages are tailored for enhanced solubility and electronic properties, crucial for specific tasks. Biomedical and semiconductor industries adopt these materials for drug delivery and organic thin-film transistors, requiring rigorous US FDA and ECHA scrutiny.
- C60:Buckminsterfullerene features unique electronic and physical properties, foundational in advanced materials science. Demand for C60 remains high from organic photovoltaics manufacturers, who rely on its electron acceptor properties to improve solar cell efficiency.
- C70:This fullerene isomer offers distinct electronic characteristics for specific advanced material applications.
- Carbon Nanotubes:These cylindrical carbon allotropes are manufactured by companies like Frontier Carbon Corporation for diverse high-performance applications.
- Carbon Nanohorns:These horn-shaped carbon nanostructures find niche applications in areas like energy storage and biomedical imaging.
C60 sits at the top of the volume ranking, with Functionalized Fullerenes climbing the fastest.
Technology:
Production technologies vary significantly in their cost structures and scalability, directly impacting the final price and purity of fullerene materials.
- Chemical Vapor Deposition:This advanced synthesis technique improves production scalability for complex fullerene structures, reducing cost-effectiveness for specialized applications. Demand for CVD-produced materials is increasing in electronics manufacturing.
- Arc Discharge:A traditional method for producing fullerenes, involving vaporizing carbon electrodes in an inert atmosphere. This method provides foundational C60 and C70, serving bulk requirements in industrial applications.
- Laser Ablation:This method uses high-power lasers to vaporize carbon targets, yielding high-purity fullerene products.
- Solvent Extraction:A purification technique crucial for separating fullerene isomers after synthesis, impacting material purity and cost.
- Ball Milling:This mechanical process is employed for grinding and modifying fullerene structures or creating composite materials.
Market adoption of Chemical Vapor Deposition is expanding due to its scalability for complex structures, while Arc Discharge maintains its position for foundational C60 production.
Application:
Fullerene applications span diverse sectors, each leveraging specific material properties to enhance product performance.
- Organic Photovoltaics:This application utilizes fullerenes as electron acceptors to improve solar cell efficiency and stability. Demand from renewable energy manufacturers drives this segment.
- Drug Delivery Systems:Fullerenes act as nanocarriers for targeted drug delivery in biomedical applications. US FDA scrutiny significantly impacts commercial development timelines in this high-value segment.
- Lubricants:Fullerene-based additives enhance performance in extreme pressure and temperature environments for industrial and automotive uses.
- Catalysts:Fullerenes exhibit catalytic activity, finding use in various chemical reactions and industrial processes.
- Superconductors:Certain fullerene compounds display superconducting properties at low temperatures, offering potential in advanced physics research.
The growth trajectory in Organic Photovoltaics is particularly steep, driven by renewable energy targets, while Lubricants demonstrate consistent expansion.
End User Industry:
The regulatory landscape significantly influences market access for fullerene end-user industries, with compliance requirements varying by sector.
- Electronics Manufacturing:This industry requires high-purity fullerenic materials for components like organic thin-film transistors and displays. Companies like Nano-C specialize in providing materials for this sector.
- Pharmaceutical Firms:These companies leverage fullerenes for advanced biomedical applications, including drug delivery systems and diagnostics. Strict US FDA and ECHA regulations govern product development and market entry.
- Lubricant Producers:These firms integrate fullerene additives to create high-performance lubricants for industrial and automotive sectors.
- Chemical Processing:This industry uses fullerenes in various chemical synthesis and material science applications.
- Renewable Energy:This sector drives demand for fullerenes in organic photovoltaics and advanced energy storage solutions.
Demand from Renewable Energy is accelerating due to global sustainability goals, whereas Pharmaceutical Firms show steady, specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fullerene industry's foundational research and early scaling efforts emerged from advanced materials science clusters. These pioneering regions established initial pathways for commercial fullerene applications. Ongoing research and development activity continues to drive market expansion in key geographic areas.
United States
Electronics manufacturing and advanced biomedical applications drive significant demand for fullerenes in the United States. The US FDA rigorously scrutinizes fullerene use in drug delivery systems, influencing product development timelines. Silicon Valley and Boston's biotech hubs foster innovation in fullerene-based materials for these high-value sectors.
Germany
Germany's industrial sectors demand fullerenes for high-performance lubricants and advanced composites. The EU's REACH regulation and ECHA framework heavily influence material safety standards and market access. Materials science clusters in cities like Dresden and Munich accelerate commercial applications for specialized industrial uses.
Japan
Organic photovoltaics and specialized electronics components represent key demand drivers in Japan. METI governs industrial market access and actively promotes advanced material innovation. Research and development activity in Tsukuba and Kyoto is accelerating commercial applications for next-generation electronic devices.
China
China's renewable energy sector and electronics manufacturing industries generate substantial fullerene demand. The country's dual carbon goals incentivize the use of high-performance materials like fullerenes in energy solutions. Industrial parks in Shenzhen and Shanghai are integrating fullerenes into advanced energy storage and electronic display technologies.
South Korea
Advanced displays and cutting-edge battery technologies are significant application areas for fullerenes in South Korea. The country's national regulatory bodies actively support research and development in new material sciences. Material science research centers in Daejeon and Seoul focus on incorporating fullerenes into next-generation electronic components.
Fullerene Market Key Industry Players
Premium-margin players sit above commodity-margin players across product purity and application specificity. The market exhibits a tiered structure, from bulk C60 producers to specialized functionalized fullerene manufacturers. Archetypes include material science innovators, high-volume carbon allotrope suppliers, and integrated chemical conglomerates. Strategic partnerships and technology licensing are dominant competitive moves.
Among companies focused on advanced carbon structures, Nano-C exemplifies specialization in high-purity fullerenic materials for electronics manufacturing. Frontier Carbon Corporation represents a scale-driven approach, leveraging its extensive manufacturing capabilities across various carbon nanotubes and fullerene structures. Mitsubishi Chemical Holdings occupies a position as an integrated chemical conglomerate, focusing on incorporating these advanced materials into polymer and composite applications.
| Leading Market Players |
|---|
| Nanotech Industrial Solutions |
| BuckyUSA |
| Nano-C |
| MTR Ltd |
| MER Corporation |
| SES Research Inc. |
| IoLiTec Ionic Liquids Technologies GmbH |
| Frontier Carbon Corporation |
| Mitsubishi Chemical Holdings |
| Others |
Cost & Logistics Intelligence
Specialized materials scientists and chemical engineers represent a concentrated workforce, and labor-cost differentials influence the pricing tiers for high-purity fullerenes. The complexity of synthesis and purification directly correlates with production expenses, affecting final product pricing across different grades.
Pricing Analysis
A tiered pricing structure across premium, standard, and economy levels characterizes the fullerene market. Price differentiation stems from material purity, certification level (e.g., US FDA for biomedical, ECHA for industrial), and volume scale. Pricing pressure stems from the significant expense associated with separating specific fullerene isomers and achieving consistent quality. Organic photovoltaics manufacturers often exhibit higher price sensitivity compared to pharmaceutical firms developing drug delivery systems.
Supply Chain Analysis
Logistics and freight costs for specialized chemical precursors and final high-purity fullerenes impact regional market pricing. The supply chain for fullerenes draws from specialized carbon precursors and advanced chemical solvents. Geographic supply concentration exists in Japan, Germany, and the United States, where advanced materials science clusters are prevalent. Single-source vulnerability for highly specialized functionalized fullerenes represents a structural risk. Distribution runs through direct sales channels to specialized end-users and collaborative R&D partnerships, rather than broad bulk chemical distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with frameworks like Europe's REACH regulation driving demand for extensive material characterization and safety data.
For Market Incumbents: Deploy advanced purification R&D to reduce per-unit costs for functionalized fullerenes. Secure long-term supply contracts with key end-users in electronics manufacturing and organic photovoltaics to mitigate demand volatility. Invest in achieving application-specific certifications like US FDA approvals for drug delivery systems, countering the threat of alternative nanomaterials. Diversify the functionalized fullerene portfolio to address emerging high-performance sectors.
For New Entrants and Emerging Players: Launch via collaborative R&D partnerships with academic institutions and specialized end-user firms. Target niche biomedical applications or specialized industrial coatings where existing solutions underperform. The functionalized fullerenes segment for specific material science clusters offers a penetrable entry point. Focus on developing proprietary synthesis methods that reduce purification costs to gain a competitive edge.
For Investors and Strategic Acquirers: Valuations sit cheapest among companies focused solely on foundational C60 production, while functionalized fullerene specialists command higher premiums. The long-term viability favors firms with strong intellectual property in tailored structures for high-performance sectors. Acquisition targets should possess advanced purification technologies or established regulatory compliance pathways. The signal to watch is the successful completion of clinical trials for fullerene-based drug delivery systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Purification R&D | Reduces production costs and enhances competitiveness for high-purity fullerenes. |
| Secure Long-Term Offtake Agreements | Provides revenue stability and ensures consistent supply for key end-user industries. |
| Pursue Application-Specific Certifications | Unlocks market access and builds trust in regulated sectors like pharmaceuticals. |
| Form Strategic R&D Partnerships | Accelerates innovation and tailors fullerene solutions to specific industry needs. |
| Diversify Functionalized Fullerene Portfolio | Expands market reach into emerging high-value applications beyond C60. |
Research Approach
Multiple input streams—primary interviews, secondary validation, and expert panel discussions—were reconciled to build a comprehensive market understanding. This approach involved engaging R&D directors, procurement leads, regulatory affairs specialists, and materials scientists across global regions. Secondary data sources included patent databases, government science reports, academic journals, and company financial disclosures, ensuring robust bottom-up and top-down triangulation.
The analytical framework cross-referenced historical market performance against expert panel input to project future trends across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from a synthesis of historical trends, demand forecasts, and projected technological advancements. Key industry-specific forecast inputs included organic photovoltaic efficiency targets and US FDA approval timelines for biomedical applications.
Several conditions sit outside the modeled scope, including unforeseen regulatory changes or sudden technological breakthroughs in competing materials. Forecasts reflect assumptions regarding economic stability and continued investment in advanced materials science. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Neodymium Sputtering Target Market
Semiconductor Material
Compound Semiconductor Materials Market