
 Asia-Pacific Semiconductor Materials Market | 2026-2036
Asia-Pacific Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Semiconductor Materials Market Analysis
Specialized photolithography engineering talent is rotating from mature-node facilities toward advanced packaging and EUV-compatible materials development across the region. JSR Corporation leverages its deep R&D footprint in ArF and EUV photoresists to sustain technology leadership in chemically amplified resists. Shin-Etsu Chemical anchors the silicon wafer segment through unmatched crystal-growth scale and vertical integration from polysilicon to epitaxial wafers. Sumitomo Chemical competes aggressively in high-purity process gases and CMP slurries, extending its supply relationships with leading memory foundries.
Asia-Pacific semiconductor materials encompass the engineered substrates, deposition precursors, patterning chemicals, and planarization slurries that enable transistor fabrication at nodes below seven nanometers. Photoresists require precise control of photoacid generator concentration and dissolution contrast to achieve sub-ten-nanometer resolution in EUV lithography. Silicon wafers command the largest value pool within material type segmentation due to their irreplaceable role as the crystalline foundation for every chip, though dielectric low-k films represent the fastest-growing category as interconnect capacitance reduction becomes critical at advanced nodes. Consumer electronics absorbs the dominant share of materials by end user, while automotive-grade semiconductors for electric vehicle power modules are expanding fastest as silicon carbide substrates penetrate traction inverters.
Japan's METI coordinates domestic materials resilience through the Semiconductor and Digital Industry Strategy, while South Korea's K-Semiconductor Belt receives regulatory support from the Ministry of Trade, Industry and Energy to localize supply chains. China's MIIT enforces GB standards and dual carbon goals that constrain foreign chemical imports while elevating domestic qualified suppliers. REACH-equivalent chemical registration frameworks in multiple jurisdictions are tightening purity documentation requirements for imported precursors. Stakeholders must monitor which country-level qualification protocols achieve mutual recognition, as divergent certification paths threaten to fragment procurement strategies across the East Asian foundry network.
Market Dynamics
Foundry capacity expansion for artificial intelligence accelerators is pulling advanced photoresists and high-purity gases into Taiwan and South Korea at unprecedented rates, while China's MIIT-directed import substitution redirects domestic procurement toward local silicon wafer and electronic chemicals suppliers.
Growth Catalysts
- EUV Lithography Scale-Up:Advanced foundries in Taiwan and South Korea are consuming chemically amplified photoresists for sub-seven-nanometer nodes, creating sustained demand for photoacid generators and dissolution-controlled polymers.
- K-Semiconductor Belt:South Korea's Ministry of Trade, Industry and Energy is concentrating materials demand through tax incentives and infrastructure investment across the Pyeongtaek-Yongin corridor.
- Silicon Carbide Traction Inverters:Automotive-grade semiconductor demand for electric vehicle power modules is expanding substrate requirements for wide-bandgap materials in Japan and South Korea.
Market Restraints
- High-Purity Gas Supply Concentration:Bulk specialty gas production clusters in Japan and South Korea, creating vulnerability to shipping disruptions or regional logistics constraints.
- GB Standard Compliance Costs:China's MIIT enforces dual carbon goals and chemical registration protocols that elevate qualification expenses for imported precursors.
- ArF Immersion Lithography Maturity:Mature-node facilities face technical limitation in extending 193-nanometer resolution without costly multi-patterning overlays.
Strategic Opportunities
- Vietnam Emerging Packaging Hub:Underpenetrated assembly and test capacity in Bac Ninh and Ho Chi Minh City corridors offers materials entry points for die-attach films and molding compounds.
- METI Materials Resilience Fund:Japan's Semiconductor and Digital Industry Strategy provides regulatory tailwind for domestic photoresist and CMP slurry production scale-up.
- Photoresist-Coater Convergence:Track-integrated lithography systems combining deposition and patterning are creating bundled procurement channels for integrated materials-process offerings.
Industry Challenges
- EUV Resist Chemist Scarcity:Specialized photolithography engineering talent is rotating from mature-node facilities, creating acute skill gaps in photoacid generator formulation and dissolution kinetics.
- Multi-Year Qualification Timelines:Foundry certification of new silicon wafer suppliers requires extensive crystal-defect characterization and epitaxial-layer validation, compressing competitive entry windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Semiconductor Materials Market |
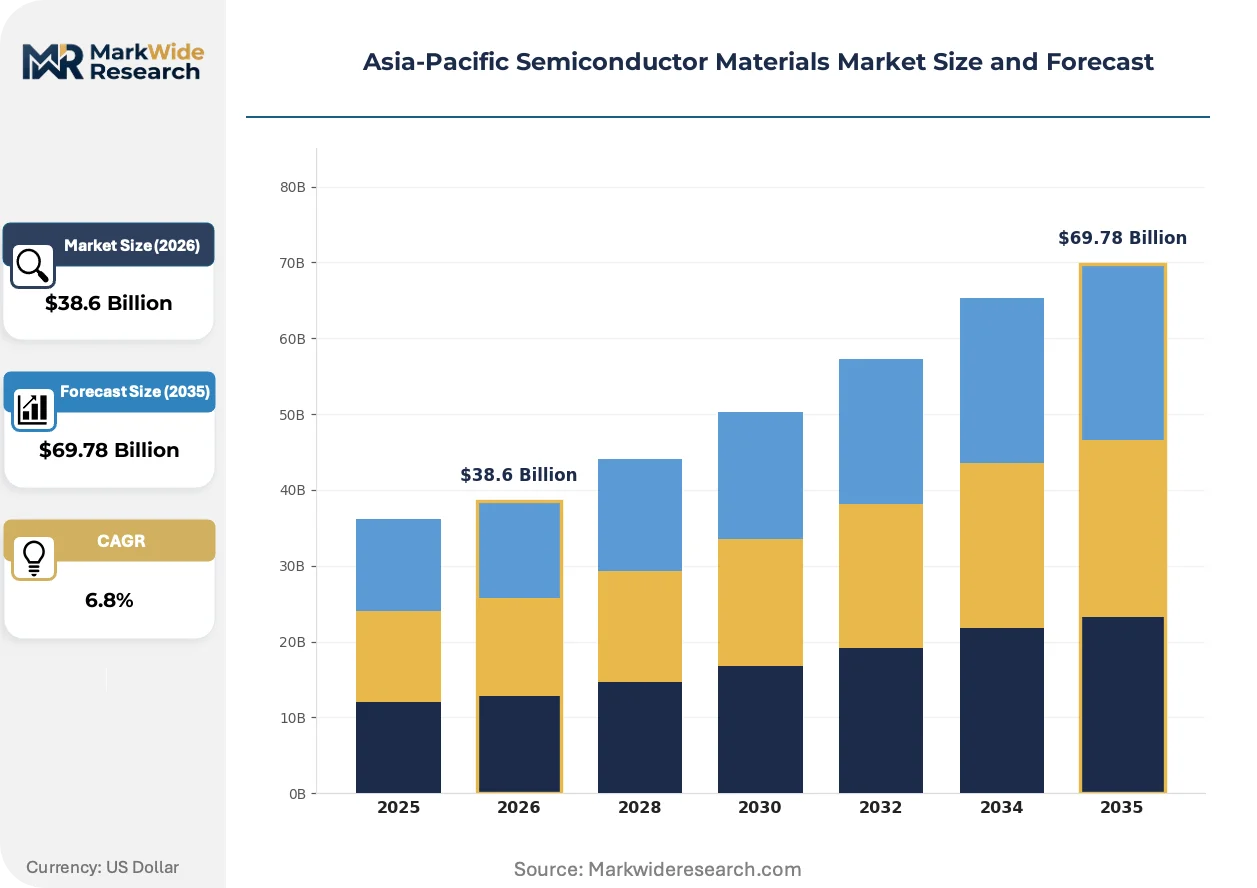
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Silicon Wafers, Dielectric Materials, Conductive Polymers, Photoresists End User: Consumer Electronics, Automotive, Telecommunications, Industrial Application: Integrated Circuits, Optoelectronics, Sensors, Power Devices Form Factor: Bulk, Film, Coating, Precursor |
| Companies Covered | JSR Corporation, Tokyo Ohka Kogyo Co., Ltd., FUJIFILM Holdings Corporation, BASF, Honeywell International Inc., Sumitomo Chemical, Shin-Etsu Chemical, Entegris, Merck KGaA, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Semiconductor Materials Market Emerging Trajectories
Materials innovation across the Asia-Pacific semiconductor supply chain is compressing development cycles for advanced node enablement while regulatory frameworks in China, Japan, and South Korea reshape qualification pathways for imported chemicals.
Metal oxide resists with enhanced etch selectivity are supplanting conventional organic chemically amplified platforms for high-numerical-aperture EUV patterning. Memory foundries in South Korea are piloting these inorganic platforms for three-nanometer-class contacts and vias. The transition is compressing supplier qualification timelines while elevating purity requirements for precursor metals.
China's MIIT enforces GB standards and dual carbon goals that constrain foreign chemical imports while elevating domestic qualified suppliers. Electronic chemicals manufacturers face divergent documentation requirements for purity certification compared to REACH-equivalent frameworks. Domestic foundries are responding by accelerating local supplier qualification for silicon wafers and wet process chemicals.
Long-term supply agreements with volume commitments are displacing spot-market purchasing for advanced photoresists and high-purity gases. Leading foundries in Taiwan and South Korea are locking in multi-year contracts with Japanese and Korean materials suppliers. This concentration is most visible in the EUV resist segment, where three suppliers now capture the majority of contracted volume.
Asia-Pacific Semiconductor Materials Market Segmentation
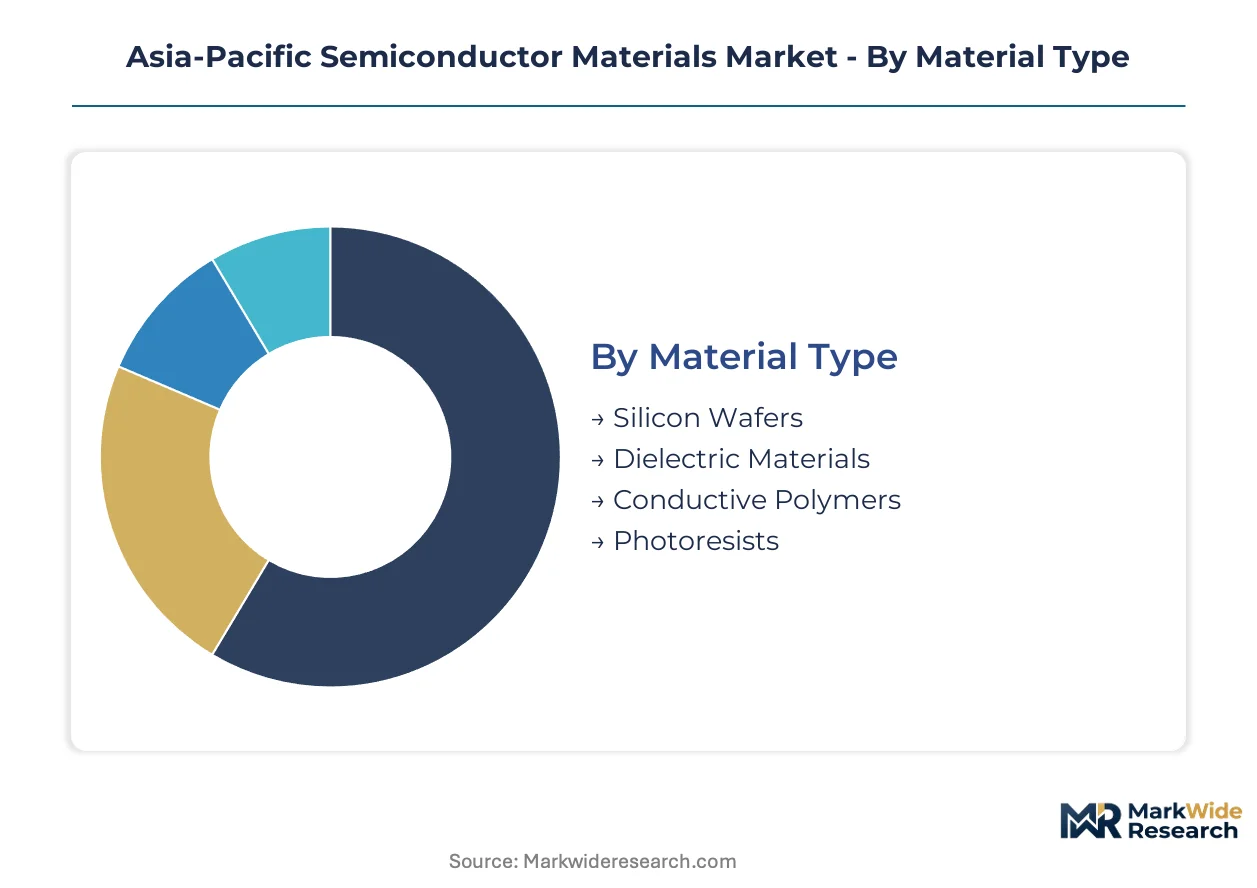
Segmentation of Asia-Pacific semiconductor materials reveals how substitution pressures and node transitions redistribute value across substrate types, end-use sectors, and physical forms. Understanding these divisions exposes where procurement concentration and qualification bottlenecks create competitive leverage.
Material Type:
Substitution pressure runs deepest where alternative substrates threaten incumbent dominance, particularly as wide-bandgap materials encroach on silicon's historical monopoly.
- Silicon Wafers:Single-crystal silicon ingots sliced into polished or epitaxial substrates remain the irreplaceable foundation for logic and memory chips. Demand concentrates in Taiwan and South Korea where TSMC and Samsung Foundry operate the world's densest advanced-node capacity, with 300mm wafer specifications tightening as crystal-defect tolerances shrink toward atomic-scale thresholds.
- Photoresists:Chemically amplified formulations containing photoacid generators enable sub-ten-nanometer patterning through EUV lithography. Taiwan and South Korea foundries are locking in multi-year supply agreements with Japanese suppliers as ArF immersion resists face technical ceilings at 193-nanometer resolution without costly multi-patterning overlays.
- Dielectric Materials:Low-k and ultra-low-k films reduce interconnect capacitance in advanced node metallization stacks.
- Conductive Polymers:Organic formulations serve emerging flexible and printed electronics applications with lower thermal budgets.
Silicon wafers anchor the volume base while photoresists gain share at the steepest rate.
End User:
Cost tier stratification separates high-volume consumer applications from qualification-intensive automotive and industrial segments.
- Consumer Electronics:Smartphones, tablets, and wearables drive the dominant materials volume through high-turnover product cycles and dense integration requirements. South Korean memory foundries and Taiwanese logic fabs feed this segment with chips fabricated on 300mm wafers using advanced photoresists, though price pressure from OEMs compresses materials margins.
- Automotive:Electric vehicle power modules and advanced driver-assistance systems demand automotive-grade silicon carbide substrates and wide-temperature-range packaging materials. Japan and South Korea lead qualification of these materials for traction inverters, with reliability standards far exceeding consumer-grade specifications.
- Telecommunications:5G baseband processors and RF front-end modules require specialized compound semiconductor substrates.
- Industrial:Factory automation and power management applications favor mature-node chips with extended supply continuity guarantees.
Consumer electronics commands the procurement volume while automotive expands most quickly on silicon carbide penetration.
Application:
Customer type divergence separates captive foundry demand from merchant memory and specialty device requirements.
- Integrated Circuits:Logic and memory chips consume the majority of silicon wafer area and advanced photoresist volumes across Taiwan and South Korea. Foundry consolidation around EUV-capable facilities is concentrating materials demand among fewer high-volume customers with stringent supplier qualification protocols.
- Power Devices:Silicon carbide and gallium nitride substrates for high-voltage switching applications are expanding fastest in Japan's automotive and industrial corridors. METI's semiconductor revitalization strategy directs domestic materials suppliers toward these wide-bandgap opportunities.
- Optoelectronics:Laser diodes and photodetectors for data centers and consumer sensing require compound semiconductor epitaxy.
- Sensors:MEMS and image sensor fabrication employs specialized wafer bonding and thin-film deposition materials.
Integrated circuits dominate materials consumption while power devices climb the fastest on electrification trends.
Form Factor:
Supply concentration shapes availability constraints, with bulk gases and solid substrates facing tighter logistics than liquid or vapor precursors.
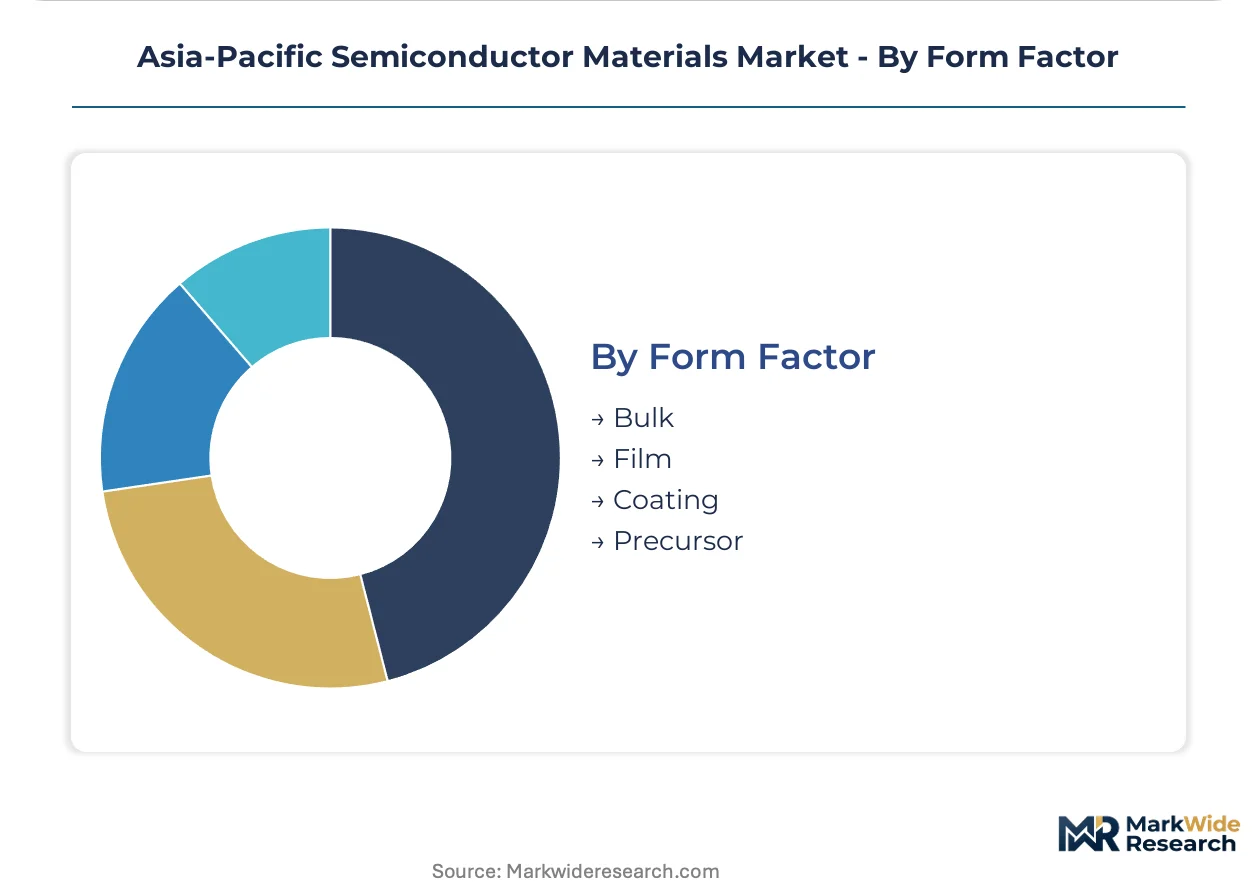
- Bulk:Solid silicon ingots and cylinder-packaged specialty gases move through concentrated logistics corridors from Japan and South Korea to Taiwanese foundries. Shipping disruptions or port congestion in these lanes create immediate supply vulnerability for high-volume consumers.
- Film:Photoresist-coated wafers and dielectric spin-on materials ship in controlled-atmosphere containers with temperature and humidity monitoring.
- Coating:Applied layers for CMP slurries and wet process chemicals require just-in-time delivery matching fab consumption rates.
- Precursor:Organometallic vapors for atomic layer deposition demand ultra-high-purity packaging with minimal contamination risk.
Bulk forms dominate tonnage movements while precursor volumes expand fastest on advanced node deposition complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan and South Korea consume advanced photoresists and high-purity gases at intensities unmatched elsewhere, while China redirects procurement toward domestic silicon wafer suppliers under import substitution mandates. Japan anchors specialty gas and CMP slurry production, creating a three-velocity consumption pattern across the region.
Taiwan
TSMC's foundry expansion for AI accelerators drives unprecedented consumption of EUV-compatible photoresists and ultra-high-purity process gases. The National Development Council coordinates infrastructure support for the Hsinchu Science Park cluster. Taichung's emerging fab corridor concentrates new materials demand as advanced packaging capacity scales.
South Korea
Samsung Foundry and SK hynix lock in long-term supply agreements for ArF immersion resists and atomic layer deposition precursors. The Ministry of Trade, Industry and Energy channels tax incentives through the K-Semiconductor Belt initiative. The Pyeongtaek-Yongin corridor concentrates memory and logic materials demand as the world's densest advanced-node manufacturing zone.
China
Domestic foundries accelerate qualification of local silicon wafer and wet chemical suppliers under MIIT-directed self-sufficiency targets. GB standards and dual carbon goals constrain foreign precursor imports while elevating domestic qualified vendors. The Yangtze River Delta cluster around Shanghai drives import substitution for electronic chemicals as Yangtze Memory Technologies scales NAND production.
Japan
Shin-Etsu Chemical and JSR Corporation anchor global supply for silicon wafers and chemically amplified photoresists through captive crystal-growth and resist-formulation capabilities. METI's Semiconductor and Digital Industry Strategy directs public funding toward materials resilience. The Kanto and Kansai corridors concentrate R&D and production for EUV resists, CMP slurries, and high-purity fluorinated gases.
Vietnam
Assembly and test capacity expansion in Bac Ninh and Ho Chi Minh City creates entry points for die-attach films, molding compounds, and substrate materials. The Ministry of Planning and Investment offers tax holidays for semiconductor packaging investments. Northern industrial zones attract materials suppliers serving Intel and Amkor facilities as the region's underpenetrated backend sector scales.
Asia-Pacific Semiconductor Materials Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive supply chains from polysilicon to epitaxial wafers and the latter dominating niche formulation categories. Three archetypes define competitive positioning: diversified chemical conglomerates with resist and gas portfolios, pure-play wafer manufacturers with crystal-growth scale, and materials-science specialists in deposition precursors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as foundries demand multi-year volume commitments and co-development relationships.
Within the integrated chemical conglomerate tier, JSR Corporation and Shin-Etsu Chemical occupy positions that exemplify technology leadership through deep R&D footprints. Sumitomo Chemical represents the diversified materials-science archetype with exposure across high-purity gases and planarization slurries. These three Japanese entities anchor the competitive structure, with their geographic concentration in East Asia reinforcing procurement relationships with Taiwan and South Korean foundries.
| Leading Market Players |
|---|
| JSR Corporation |
| Tokyo Ohka Kogyo Co., Ltd. |
| FUJIFILM Holdings Corporation |
| BASF |
| Honeywell International Inc. |
| Sumitomo Chemical |
| Shin-Etsu Chemical |
| Entegris |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
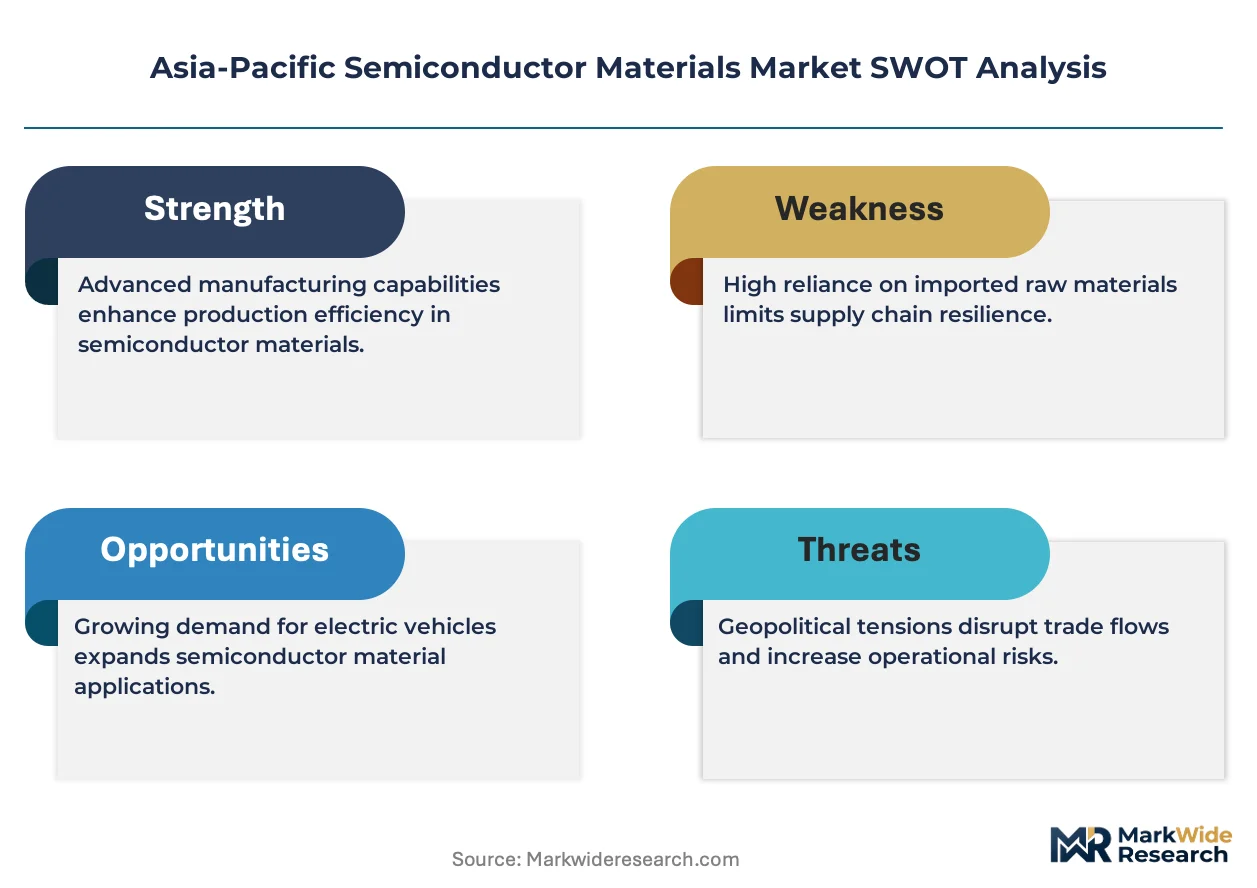
Silicon carbide substrate substitution for silicon wafers in automotive traction inverters is simultaneously redrawing supply geography toward Japan and South Korea while compressing pricing premiums for incumbent silicon suppliers serving mature-node fabs.
Pricing Analysis
Long-term offtake agreements dominate advanced photoresist and high-purity gas procurement as TSMC and Samsung Foundry lock in multi-year volume commitments with Japanese suppliers. Three-tier pricing structure across EUV-grade, ArF immersion, and mature-node resists reflects qualification intensity and volume scale. Cost compression in ArF immersion tiers is intensifying because Chinese domestic suppliers are undercutting on GB-standard compliance. Memory foundries exhibit the highest price sensitivity due to cyclical margin pressure, while automotive power module manufacturers accept premium pricing for silicon carbide reliability certification.
Supply Chain Analysis
Inventory buffers for photoresists and fluorinated gases rarely exceed three weeks at Taiwanese foundries given shelf-life constraints and just-in-time delivery contracts. Production clusters in Japan, South Korea, and Taiwan feed the East Asian manufacturing corridor through concentrated maritime lanes. The network draws from polysilicon feedstock in China and Germany, high-purity fluorine chemistry from Japan, and specialty photoresist polymers from JSR and Tokyo Ohka Kogyo facilities. Single-source vulnerability pervades EUV resist supply where three Japanese suppliers control qualified volumes. Distribution runs through bonded warehouse networks at Hsinchu and Pyeongtaek science parks with direct pipeline connections to fab chemical delivery systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wide-bandgap materials substitution threatens silicon wafer incumbents as automotive electrification accelerates qualification of silicon carbide and gallium nitride substrates for traction inverters.
For Market Incumbents: Fortify EUV resist formulation capabilities through captive R&D in metal oxide platforms before memory foundries complete supplier transitions. Secure backward integration into high-purity fluorine gas production to defend margin position against South Korean chemical conglomerates expanding upstream. Lock in five-year supply agreements with Chinese foundries ahead of MIIT domestic qualification mandates. For New Entrants and Emerging Players: CMP slurry technical service gaps at Vietnam packaging facilities offer entry points where incumbent suppliers lack localized application engineering. Target die-attach film qualification at Bac Ninh assembly corridors as Intel and Amkor capacity scales. Pursue joint development agreements with Yangtze Memory Technologies for wet chemical import substitution under dual carbon compliance timelines. For Investors and Strategic Acquirers: The market sits at a substitution acceleration phase that favors materials-science specialists with compound semiconductor epitaxy capabilities. Long-term viability hinges on exposure to wide-bandgap substrate growth rather than silicon wafer cyclicality. Watch for METI funding disbursement velocity as inflection indicator for Japanese domestic capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | TSMC and Samsung Foundry are locking in multi-year photoresist volumes with JSR and Tokyo Ohka Kogyo. |
| Backward Integration | Shin-Etsu Chemical controls polysilicon-to-epitaxial-wafer production, insulating crystal-growth margins. |
| Capacity Expansion | South Korea's K-Semiconductor Belt is concentrating atomic layer deposition precursor production in Pyeongtaek. |
| Joint Venture | Domestic foundries in China are partnering with local wet chemical suppliers to meet MIIT self-sufficiency targets. |
| Green Manufacturing Transition | GB standards and dual carbon goals are forcing reformulation of fluorinated process gases with lower global warming potential. |
Methodological Framework
Two parallel data streams informed the analysis: structured interviews with fab materials procurement managers, photoresist R&D directors, and semiconductor chemical distribution executives; and secondary validation through customs trade databases, METI semiconductor strategy documents, MIIT GB standard filings, and foundry capex disclosures. Triangulation between bottom-up supplier shipment estimates and top-down foundry consumption models anchored volume projections.
Across the analysis window, forecasts segment by material type, end-user industry, application node, and regional regulatory cluster. CAGRs derive from fitted growth curves against historical foundry capacity expansion patterns and node transition timelines. Model inputs include EUV lithography adoption rates at leading logic fabs, silicon carbide substrate penetration in automotive inverters, and MIIT domestic qualification velocity for electronic chemicals.
Forecasts assume regulatory continuity in Japan's METI Semiconductor and Digital Industry Strategy, South Korea's K-Semiconductor Belt tax incentives, and China's MIIT import substitution mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Compound Semiconductor Materials Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Electronic Assembly Materials Market
Semiconductor Material
Indium Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Silicon Nitride Market
Semiconductor Material
Titanium Diboride Market