
 Metallurgical Grade Silicon Market | 2026-2036
Metallurgical Grade Silicon Market Size, Share, and Industry Trends Forecast 2026-2036
Metallurgical Grade Silicon Market Outlook
The EU Green Deal is shifting procurement criteria for metallurgical grade silicon across European aluminum and solar supply chains, forcing smelters to document embodied carbon. Ferroglobe leverages its Spanish and French furnace assets to supply low-carbon silicon metal to automakers with science-based targets. Elkem ASA anchors its position through integrated quartz mining and ferroalloy operations in Norway, backing claims with hydroelectric power. Hoshine Silicon Industry Co., Ltd. dominates global volume through massive Xinjiang-based smelting complexes that compete on scale.
Metallurgical grade silicon is a silicon-rich alloy or refined metal containing 98-99% elemental silicon, produced by carbothermic reduction of quartz in submerged-arc electric furnaces at temperatures exceeding 1800°C, serving primarily as a deoxidizer in steelmaking and as feedstock for aluminum alloys and polysilicon. The ferroalloys segment sustains mature demand from steel mills seeking precise sulfur and oxygen control in specialty grades. Metal silicon differentiates through purity tiers, with chemical-grade material commanding margin pools from semiconductor and solar precursor buyers. Solar cells application leads growth velocity as polysilicon producers expand metallurgical-to-solar-grade purification capacity.
China's MIIT enforces GB standards on silicon metal energy consumption per ton, capping inefficient capacity and reshaping provincial production quotas. The EPA in the United States monitors particulate and fluoride emissions from silicon smelters under Clean Air Act provisions, raising compliance costs for domestic producers like Mississippi Silicon LLC. REACH in Europe mandates full supply chain disclosure of silicon metal impurities, affecting import access for non-EU refiners. Stakeholders must monitor how carbon border mechanisms and purity standards bifurcate premium from commodity-grade supply pools.
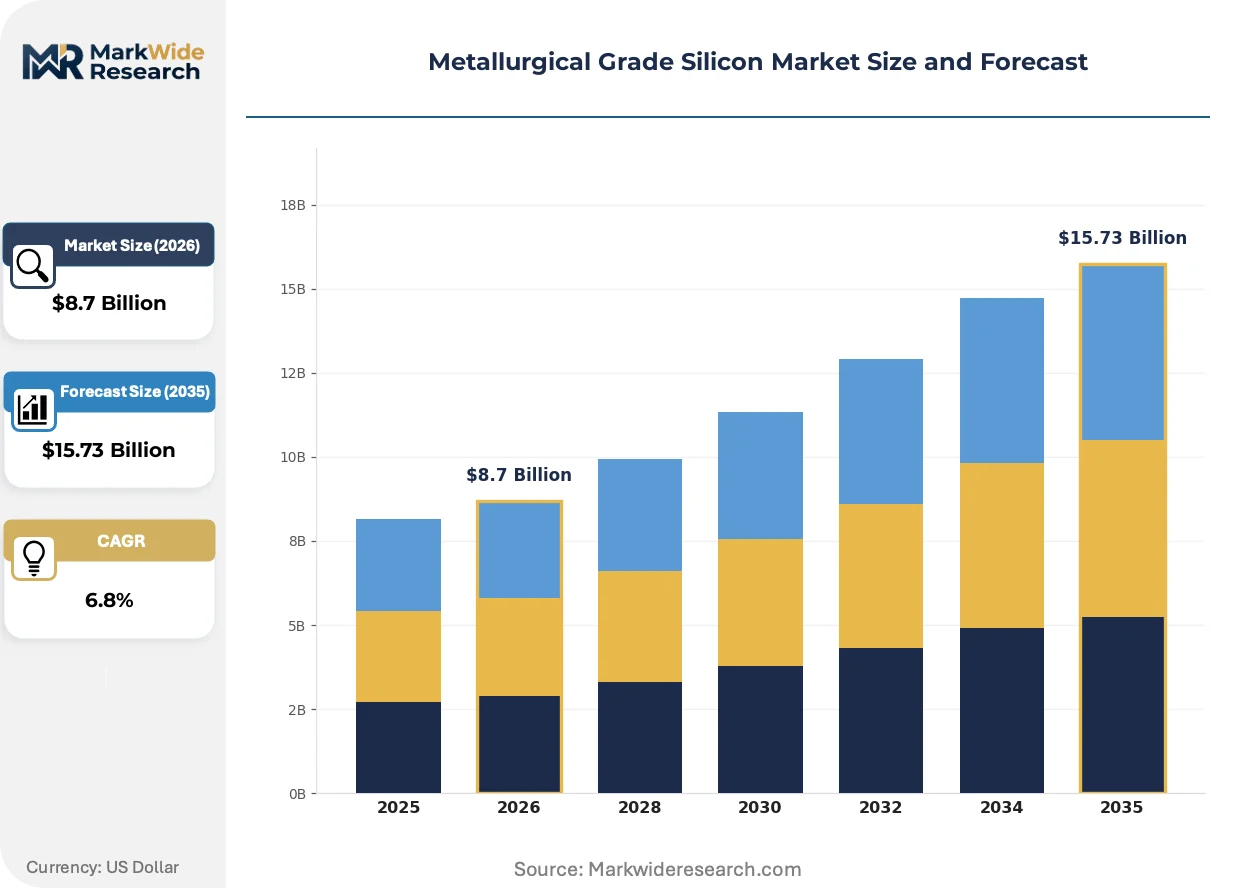
Market Dynamics
The EU Green Deal's carbon border adjustment mechanism is bifurcating metallurgical grade silicon procurement, forcing buyers to document embodied emissions and suppliers to reconfigure smelting energy sources or lose European market access.
Growth Catalysts
- Solar-grade purification expansion:Polysilicon producers in China are scaling metallurgical-to-solar-grade refining capacity, pulling higher-purity feedstock through the value chain.
- EU Green Deal carbon border adjustments:European automakers with science-based targets now mandate low-carbon silicon metal certificates, creating premium demand pools for hydropower-smelted material.
- Aluminum alloy specification tightening:Aerospace and automotive casting operations require tighter sulfur and oxygen control, sustaining deoxidizer demand from specialty steel mills.
Market Restraints
- Quartz supply concentration:High-purity quartz deposits concentrate in limited geographies, exposing smelters to raw material bottlenecks and long-haul freight exposure.
- Energy cost volatility:Submerged-arc furnace operations consume megawatt-hours per ton; electricity price spikes in coal-dependent grids compress margin pools.
- Fluoride emission compliance:The EPA's Clean Air Act monitoring raises fixed-cost burdens for US-based producers versus hydropower competitors.
Strategic Opportunities
- Low-carbon certification premiums:Smelters with captive hydropower or geothermal access can capture margin premiums from European buyers facing CBAM liability.
- Semiconductor precursor verticals:Chemical-grade silicon metal for electronic-grade polysilicon remains underpenetrated relative to solar feedstock, offering purity-tier arbitrage.
- Integrated quartz-to-metal operations:Backward integration into high-purity quartz mining secures feedstock quality and insulates against concentrate supply shocks.
Industry Challenges
- Smelter engineering talent scarcity:Submerged-arc furnace design and electrode management expertise concentrates among retiring cohorts, constraining capacity expansion timelines.
- REACH compliance documentation:European importers face full supply chain disclosure mandates for silicon metal impurities, extending qualification cycles for non-EU refiners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallurgical Grade Silicon Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferroalloys, Metal Silicon, Silicon Carbide, Silicon Metal End User: Automotive, Electronics, Construction, Chemicals Application: Aluminum Alloys, Steel Production, Solar Cells, Chemical Manufacturing Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Wacker Chemie AG, RIMA Group, Ferroglobe, REC Silicon, Mississippi Silicon LLC, Elkem ASA, Globe Specialty Metals, Shin-Etsu Chemical Co. Ltd., Hoshine Silicon Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallurgical Grade Silicon Market Strategic Shifts
Smelting technology and procurement specifications are converging around carbon intensity metrics, with furnace energy source and process emissions now treated as product attributes rather than cost inputs.
Advanced submerged-arc furnace controls with real-time electrode positioning and off-gas recapture are consolidating operational efficiency gains among large-scale producers. Solar-grade polysilicon manufacturers in China adopt these systems fastest, compressing per-ton energy consumption and widening cost advantages over legacy furnace operators. The technology is consolidating market share toward integrated smelters with capital depth for automation retrofits.
China's MIIT enforcement of GB standards on silicon metal energy consumption per ton is capping inefficient furnace capacity and reshaping provincial production quotas. Smelters in Xinjiang and Yunnan face output limits unless they document hydropower sourcing or achieve efficiency benchmarks. The regulation is accelerating consolidation toward grid-advantaged producers in southwestern provinces with abundant renewable baseload.
Automotive aluminum casters are unbundling silicon metal procurement from legacy ferroalloy distributors, establishing direct offtake relationships with certified low-carbon smelters. Tier-1 suppliers to European OEMs now require batch-level carbon accounting, bypassing commodity traders who cannot document furnace energy sources. This pattern is most visible in German and French automotive supply chains, where science-based target commitments have reached casting operations.
Metallurgical Grade Silicon Market Segmentation
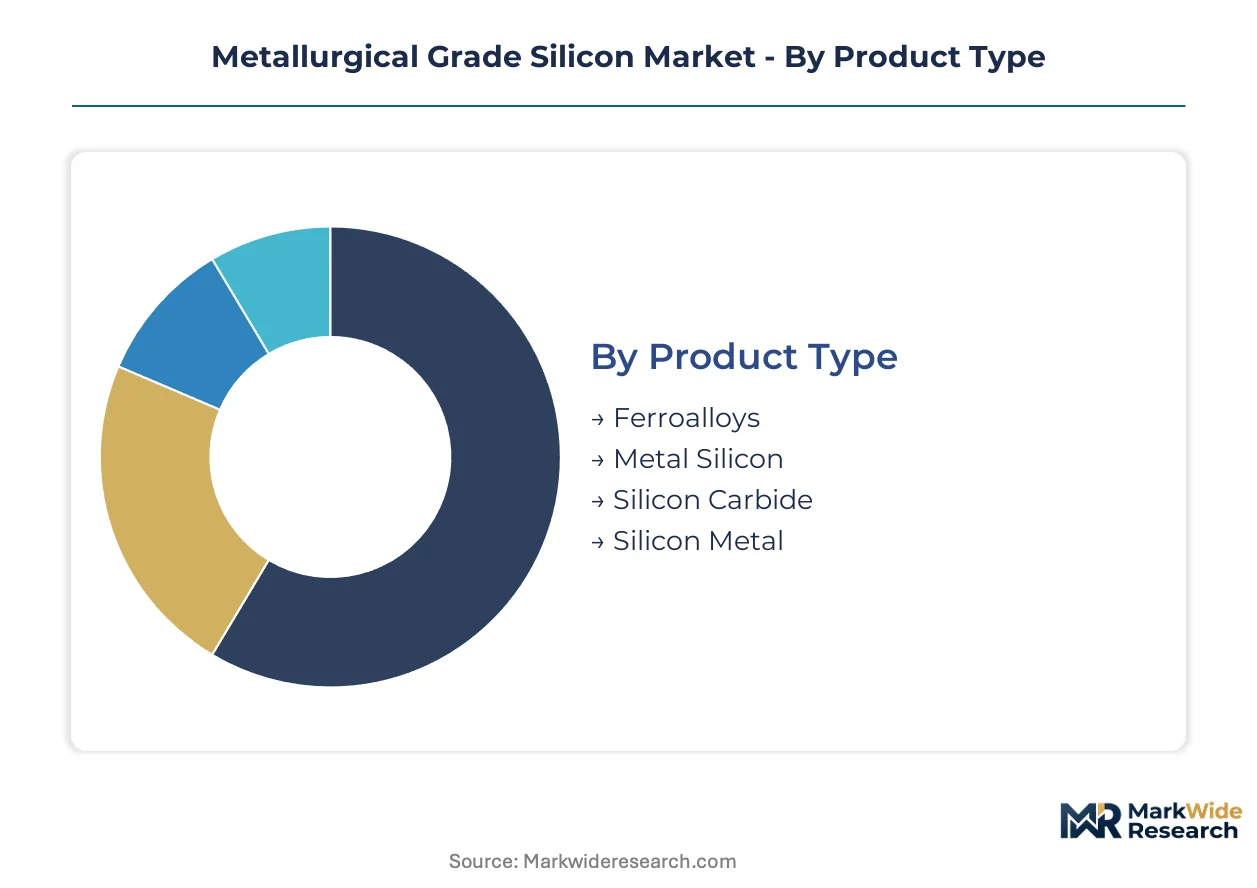
Segmentation in metallurgical grade silicon separates commodity-grade deoxidizers from premium solar and semiconductor feedstocks. Purity tiers, carbon intensity, and end-use specifications now drive pricing spreads wider than historical ferroalloy benchmarks.
Product Type:
Supply concentration in submerged-arc furnace capacity creates tiered access to different product grades, with hydropower-smelted material commanding premium positioning.
- Metal Silicon:Refined silicon metal containing 98-99% elemental silicon serves as the foundational feedstock for polysilicon purification and aluminum alloying. Solar cell manufacturers in China's Xinjiang province pull this grade through expanding metallurgical-to-solar-grade refining capacity.
- Ferroalloys:Silicon-rich alloys combine silicon with iron and other elements for steel deoxidation and sulfur control. Steel mills in Germany and France sustain mature procurement volumes for specialty automotive grades requiring precise oxygen management.
- Silicon Carbide:Compound semiconductor substrate material produced through high-temperature Acheson process reactions. Abrasive and refractory applications in Japanese automotive supply chains anchor baseline demand.
- Silicon Metal:Higher-purity grades above 99% silicon content target chemical and electronics precursors. Norwegian smelters leveraging hydroelectric power capture European premium pools under carbon border adjustment mechanisms.
Today's leader: Metal Silicon. Tomorrow's challenger: Silicon Metal.
End User:
Cost tier stratification separates mass-market construction buyers from specification-driven automotive and electronics procurement.
- Automotive:Aluminum casting operations for electric vehicle structural components require batch-level carbon accounting and tight sulfur specifications. German OEMs now mandate direct offtake relationships with certified low-carbon smelters.
- Electronics:Semiconductor precursor supply chains demand 99.999%+ purity silicon metal for electronic-grade polysilicon production. This segment climbs fastest as chip manufacturers diversify beyond solar feedstock applications.
- Construction:Structural steel deoxidization and concrete admixture applications consume commodity-grade ferrosilicon. Price-sensitive procurement through traditional distributor channels dominates.
- Chemicals:Silicone polymer and fumed silica production requires consistent metallurgical-grade feedstock quality. Integrated chemical majors in the US Gulf Coast maintain captive silicon metal arrangements.
Automotive procurement now leads premium tier pricing. Electronics represents the steepest expansion trajectory.
Application:
Volume concentration in mature steel and aluminum markets contrasts with emerging solar and chemical verticals reshaping capacity allocation.
- Solar Cells:Polysilicon precursor demand pulls higher-purity metallurgical silicon through purification cascades. Chinese producers in Yunnan province scale capacity fastest under MIIT energy efficiency mandates.
- Aluminum Alloys:Silicon additions improve castability and mechanical properties in automotive powertrain and structural components. Aerospace specification tightening sustains deoxidizer demand from specialty mills.
- Steel Production:Ferrosilicon deoxidization removes dissolved oxygen from molten steel in basic oxygen and electric arc furnaces. Mature demand from integrated mills in the US Great Lakes region.
- Chemical Manufacturing:Silicones, silanes, and silica derivatives require consistent feedstock chemistry. European REACH disclosure mandates extend qualification cycles for non-EU refiners serving this segment.
Aluminum Alloys anchor current volume. Solar Cells gain share fastest.
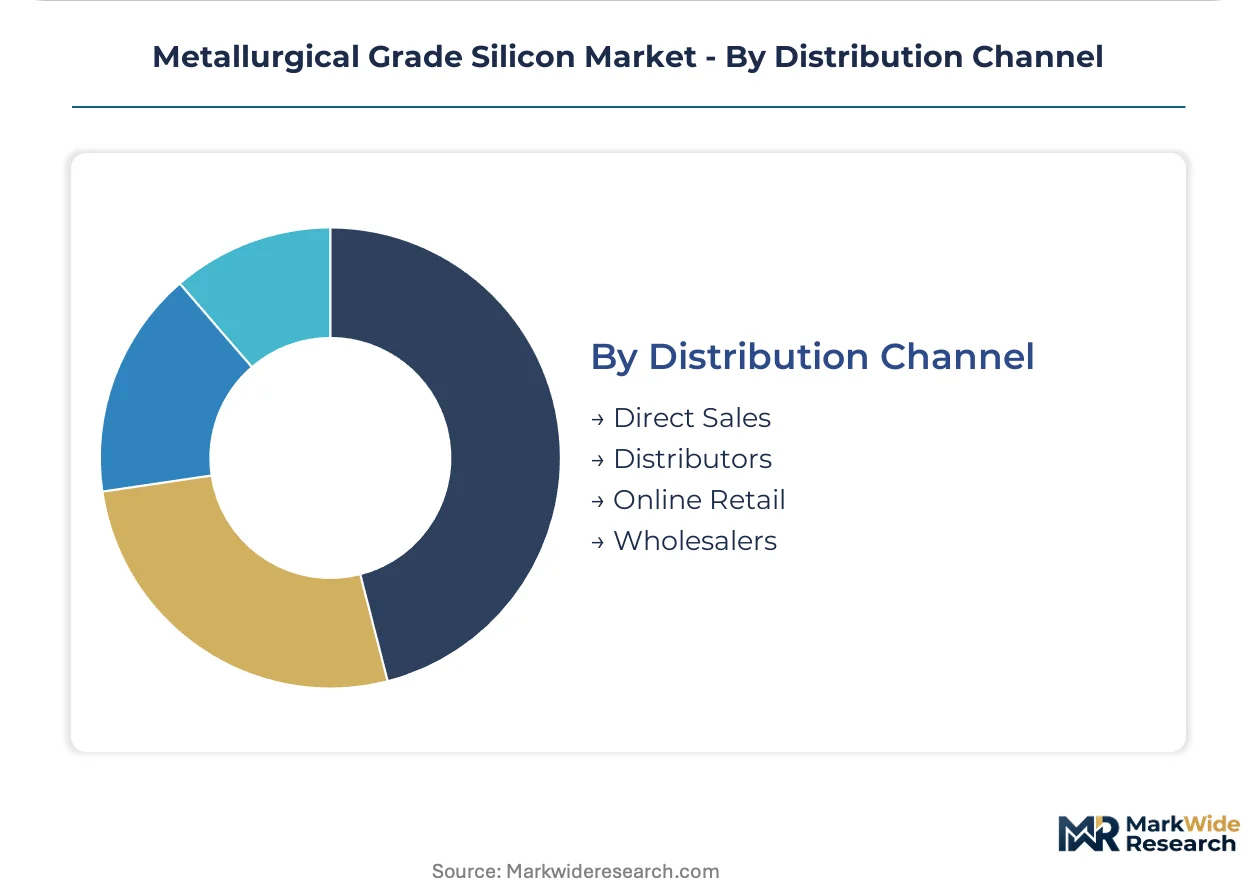
Distribution Channel:
Customer type bifurcation separates direct procurement by carbon-conscious OEMs from traditional trader-mediated spot markets.
- Direct Sales:Long-term offtake agreements between smelters and aluminum casters, polysilicon producers, or steel mills. European automakers with science-based targets now require documented furnace energy sources.
- Distributors:Ferroalloy traders aggregate spot volumes for smaller steel mills and foundries. Margin compression from carbon accounting requirements is displacing undifferentiated intermediaries.
- Wholesalers:Bulk material handlers serving construction and commodity chemical applications. Price-driven procurement with limited purity or certification requirements.
- Online Retail:Digital platforms for specialty silicon metal samples and small-batch procurement. Emerging channel for R&D and prototype casting operations.
Direct Sales commands premium contract structures. Distributors face margin pressure from traceability demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Submerged-arc furnace technology for silicon metal production first achieved industrial scale in Norway during the early twentieth century, leveraging abundant hydroelectric resources that remain a competitive anchor for European producers today.
China
Xinjiang and Yunnan provinces concentrate over half of global metallurgical grade silicon capacity, with polysilicon manufacturers pulling higher-purity feedstock through expanding purification cascades. MIIT enforcement of GB energy consumption standards caps inefficient furnace operations and reshapes provincial production quotas toward hydropower-advantaged southwestern smelters.
Norway
Integrated quartz mining and ferroalloy operations in western Norway supply low-carbon silicon metal to European automotive supply chains facing EU Green Deal carbon border liabilities. Elkem ASA anchors production through captive hydroelectric power, documenting embodied emissions for REACH compliance and science-based target procurement.
United States
Mississippi Silicon LLC operates submerged-arc furnace capacity serving domestic aluminum and chemical manufacturing, though EPA Clean Air Act monitoring of particulate and fluoride emissions raises fixed-cost burdens relative to hydropower competitors. The US Gulf Coast maintains captive silicon metal arrangements for silicone polymer production.
Spain
Ferroglobe leverages Spanish and French furnace assets to supply certified low-carbon silicon metal to German and French automakers with science-based target commitments. Direct offtake relationships now bypass traditional ferroalloy distributors who cannot document batch-level furnace energy sources.
Germany
Automotive aluminum casters in Bavaria and Baden-Württemberg unbundle silicon metal procurement from legacy channels, establishing direct relationships with certified low-carbon smelters. KBA vehicle certification requirements and OEM science-based targets mandate documented embodied carbon in structural casting feedstock.
Metallurgical Grade Silicon Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent cost structures in metallurgical grade silicon. The market consolidates around integrated smelters with captive energy resources and backward-linked quartz mining, while smaller furnace operators face margin compression from carbon accounting requirements. Two strategic archetypes dominate: hydropower-backed European specialists serving premium automotive and solar certification pools, and scale-driven Chinese producers competing on volume in commodity ferroalloy segments. Competitive moves concentrate on furnace automation retrofits and direct offtake partnerships with carbon-conscious OEMs.
Among European integrated producers, Elkem ASA and Ferroglobe exemplify the low-carbon certification archetype, leveraging Nordic and Iberian hydroelectric assets to supply science-based target supply chains. Wacker Chemie AG anchors German chemical-grade silicon metal positioning. At the scale-driven end, Hoshine Silicon Industry Co., Ltd. represents massive Xinjiang-based furnace complexes competing on throughput volume.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| RIMA Group |
| Ferroglobe |
| REC Silicon |
| Mississippi Silicon LLC |
| Elkem ASA |
| Globe Specialty Metals |
| Shin-Etsu Chemical Co. Ltd. |
| Hoshine Silicon Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Submerged-arc furnace engineering talent concentrated in Norway and Spain feeds labor-cost differentials that widen pricing spreads between hydropower-smelted premium grades and commodity ferroalloy tiers. European smelters leverage this scarce expertise to command carbon-certified premiums while Chinese competitors compete on scale-driven unit economics.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between polysilicon producers and smelters, with price differentiation anchored in carbon intensity certification and purity grade. Hydropower-backed material from Norwegian and French furnace assets commands substantial premiums over coal-grid production, while commodity ferrosilicon for steel deoxidization faces acute price sensitivity from integrated mills in the US Great Lakes and Germany's Ruhr region. Cost compression in standard-grade metal silicon intensifies as Xinjiang-based producers automate furnace controls, eroding legacy operator margins.
Supply Chain Analysis
Long-haul freight exposure from quartz concentrate shipments between Australia, Norway, and China elevates landed costs for smelters lacking captive mining assets. The supply chain draws from high-purity quartz deposits in Spruce Pine, North Carolina and Drag, Norway, with electrode graphite sourcing concentrated in China and Mozambique. Single-source vulnerability in semiconductor-grade polysilicon purification creates chokepoint risk for electronics feedstock. Distribution runs through direct sales agreements for certified low-carbon material, while commodity ferroalloy flows via traditional trader networks to smaller steel mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's carbon border adjustment mechanism operates as a regulatory compounder, with the CBAM phase-in timeline forcing immediate procurement reconfiguration across European automotive aluminum supply chains.
For Market Incumbents: Acquire captive hydropower assets or long-term renewable power purchase agreements to defend margin position against CBAM-exposed competitors. Elkem ASA and Ferroglobe demonstrate this model through Norwegian and Iberian hydroelectric integration. Incumbents must simultaneously automate submerged-arc furnace controls to meet China's MIIT energy efficiency benchmarks, capping inefficient capacity before regulatory enforcement accelerates consolidation. For New Entrants and Emerging Players: Enter via semiconductor-grade chemical silicon metal production, where purity-tier arbitrage remains underpenetrated relative to solar feedstock saturation. New entrants should target direct offtake relationships with European Tier-1 automotive casters in Bavaria and Baden-Württemberg, bypassing distributor channels that cannot document batch-level furnace energy sources. A go-to-market angle anchored in REACH-compliant impurity disclosure protocols accelerates qualification cycles. For Investors and Strategic Acquirers: European automotive OEMs with science-based target commitments are the most active acquirer in this space, seeking backward integration into certified low-carbon silicon metal supply. The acquisition target archetype combines integrated quartz mining with hydropower-smelted capacity in Norway, France, or Spain. Investors should monitor CBAM liability calculations as the inflection indicator for premium-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quartz Mining | Captive Spruce Pine or Drag concentrate supply secures feedstock quality against concentrate bottlenecks. |
| Hydropower Certification Program | Documented renewable sourcing unlocks CBAM-compliant premium pools from German and French OEMs. |
| Furnace Automation Retrofit | Real-time electrode positioning cuts per-ton energy consumption to meet MIIT GB standards. |
| Long-term Supply Agreement | Direct polysilicon producer offtake de-risks volume exposure for Yunnan and Xinjiang smelters. |
| REACH Compliance Investment | Full supply chain impurity disclosure extends European chemical manufacturing market access. |
Study Parameters
Bottom-up aluminum casting and polysilicon demand modeling reconciled against top-down submerged-arc furnace capacity tracking forms the analytical core of this study. Primary interviews with plant managers at European ferroalloy operations, procurement leads at German automotive OEMs, technical R&D directors at silicone polymer producers, and channel partners in ferroalloy distribution validated consumption patterns. Secondary sources include SEC 10-K filings from listed producers, customs and trade data from USITC and Eurostat, ECHA REACH registration dossiers, and MIIT GB standard enforcement disclosures.
Historical trendline analysis of capacity utilization, energy consumption per ton, and purity-grade pricing spreads established baseline trajectories across the projection horizon. The forecast framework segments by product purity tier, end-use industry concentration, furnace energy source, and regional regulatory cluster. CAGRs derive from weighted capacity expansion announcements, MIIT quota reshaping effects, and CBAM liability modeling for European import demand. Industry-specific inputs include polysilicon purification capacity buildouts and automotive aluminum content-per-vehicle specifications.
Inputs from ECHA registration databases and MIIT enforcement reports were available through the study window; gaps in real-time Chinese provincial production data introduce uncertainty bands around Xinjiang and Yunnan output estimates. Forecasts reflect assumptions regarding CBAM phase-in stringency, hydropower availability in southwestern China, and furnace engineering talent pipeline constraints. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Encapsulant Market
Semiconductor Material
PV Module Encapsulant Film Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Taiwan Semiconductor Materials Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
Global Strontium Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Silicon Base Paper Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market