
 Middle East Silicon Carbide (Sic) Market | 2026-2036
Middle East Silicon Carbide (Sic) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Silicon Carbide (Sic) Market Foresight
Power utilities are reorganizing procurement priorities around wide-bandgap semiconductors, displacing traditional silicon buyers as the dominant customer archetype in the Middle East. Infineon Technologies AG leverages its vertical integration across substrate and device fabrication to anchor supply security for Gulf grid operators. STMicroelectronics sustains R&D intensity in high-voltage SiC MOSFETs that compete directly with silicon IGBTs in traction inverter applications. Wolfspeed dominates the upstream wafer segment, controlling critical crystal growth capacity that positions the company as a gatekeeper for regional device manufacturers.
Silicon carbide is a compound semiconductor formed from silicon and carbon atoms arranged in a crystalline lattice, typically manufactured through physical vapor transport or chemical vapor deposition methods to achieve purity levels exceeding 99.9995 percent for electronic-grade material. Its wide bandgap of 3.26 electron volts enables operation at temperatures above 200 degrees Celsius with switching losses roughly one-tenth those of conventional silicon, making it indispensable for high-frequency power conversion in electric vehicle drivetrains and renewable energy inverters. Power devices command the largest revenue pool due to their direct substitution of silicon IGBTs in automotive and energy applications, while wafers represent the fastest-growing segment as regional foundries seek backward integration into substrate production. The automotive end-user category absorbs the majority of volume growth, driven by electric vehicle mandates in the UAE and Saudi Arabia that require SiC-based power management systems for onboard chargers and DC-DC converters.
The Saudi Standards, Metrology and Quality Organization and the UAE's Emirates Authority for Standardization and Metrology enforce efficiency benchmarks that effectively mandate SiC adoption in grid-tied inverters above certain power thresholds. The Gulf Cooperation Council's unified technical regulations for electrical equipment create a harmonized compliance pathway that reduces market access friction for qualified suppliers. Stakeholders must monitor how Saudi Arabia's domestic content requirements for NEOM-related procurement reshape supplier qualification criteria and whether the UAE's advanced manufacturing incentives attract wafer fabrication investments that alter regional supply chain topology.
Market Dynamics
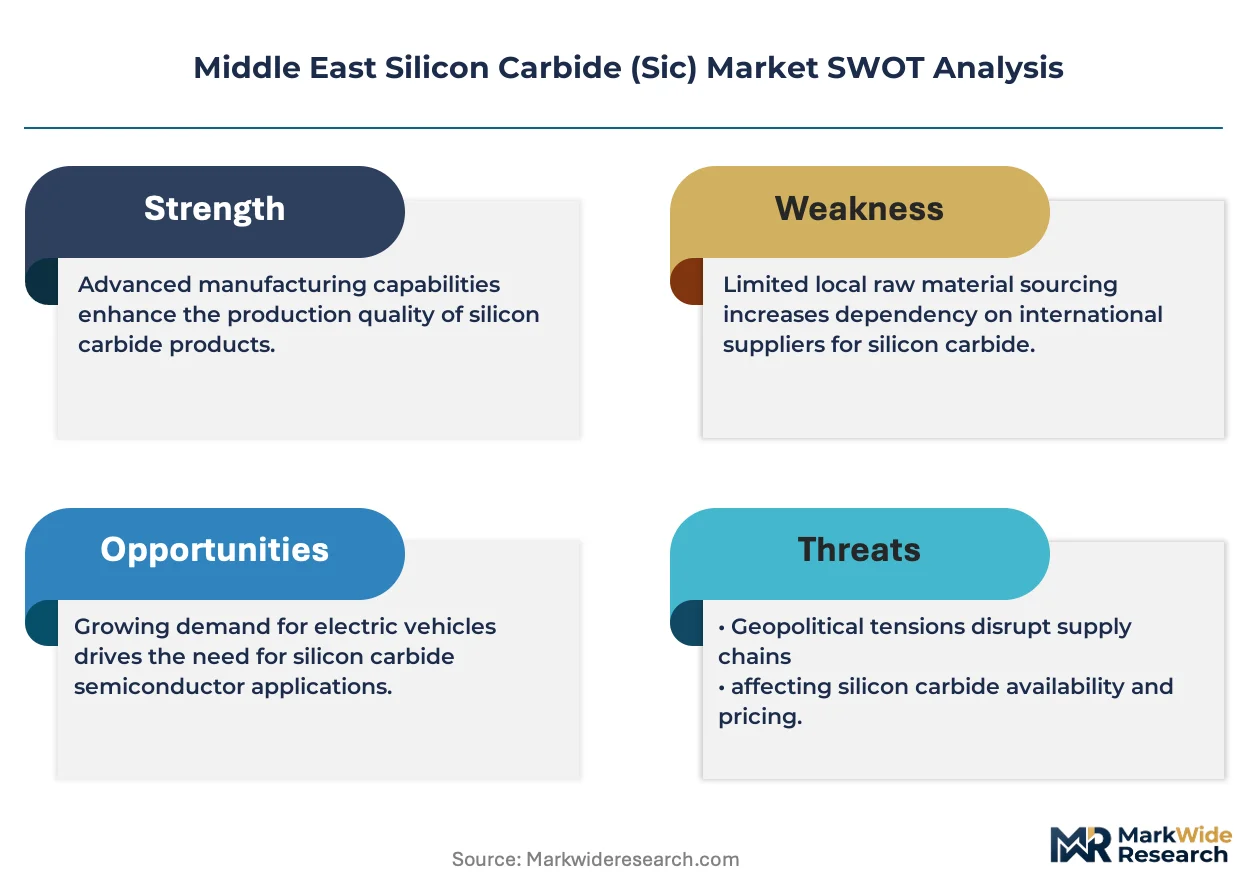
Power utilities across the Gulf Cooperation Council are reorganizing procurement priorities around wide-bandgap semiconductors, displacing traditional silicon buyers as the dominant customer archetype and compressing qualification timelines for SiC device suppliers.
Growth Catalysts
- Saudi Arabia's NEOM industrial zone:Massive renewable energy infrastructure buildout mandates SiC-based inverters and grid-tied power management systems for solar and wind integration.
- UAE renewable energy mandates:Dubai Clean Energy Strategy and Abu Dhabi Economic Vision tighten efficiency standards that effectively require wide-bandgap semiconductors above specified power thresholds.
- Physical vapor transport advances:Improved crystal growth methods are expanding electronic-grade SiC wafer availability for regional foundries seeking backward integration.
Market Restraints
- Upstream wafer concentration:Critical crystal growth capacity concentrates among a handful of specialized suppliers, creating supply security vulnerabilities for regional device manufacturers.
- High-purity silicon feedstock volatility:Electronic-grade silicon and carbon precursor costs fluctuate with energy prices, squeezing margins for substrate producers.
- Gallium nitride substitution threat:GaN devices compete for mid-voltage applications below 650V, limiting SiC addressable market in consumer power adapters and lower-power industrial drives.
Strategic Opportunities
- Egypt's nascent renewable sector:Grid modernization programs and solar auction expansions create first-mover potential for SiC inverter suppliers before domestic content requirements harden.
- Vehicle-to-grid integration:Bidirectional charging infrastructure for electric fleets converges with smart grid architectures, opening high-margin applications for SiC power modules.
- UAE advanced manufacturing incentives:Dubai Silicon Oasis and KIZAD free zone subsidies attract wafer fabrication investments that could alter regional supply chain topology.
Industry Challenges
- Power electronics engineering scarcity:Gulf universities produce limited graduates with compound semiconductor device physics expertise, forcing manufacturers to import talent or fund specialized training programs.
- Dual certification complexity:Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology maintain partially divergent testing protocols, extending product approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Silicon Carbide (Sic) Market |
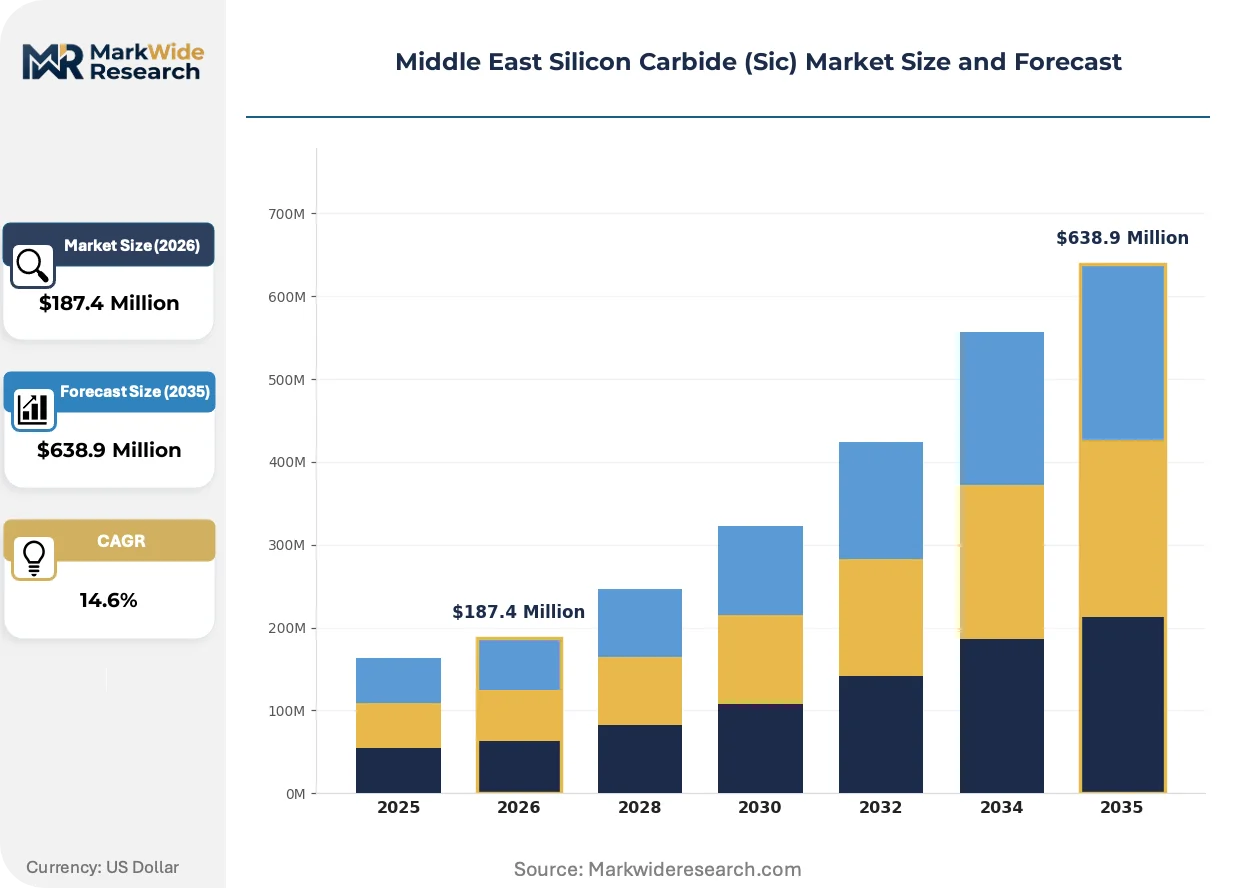
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
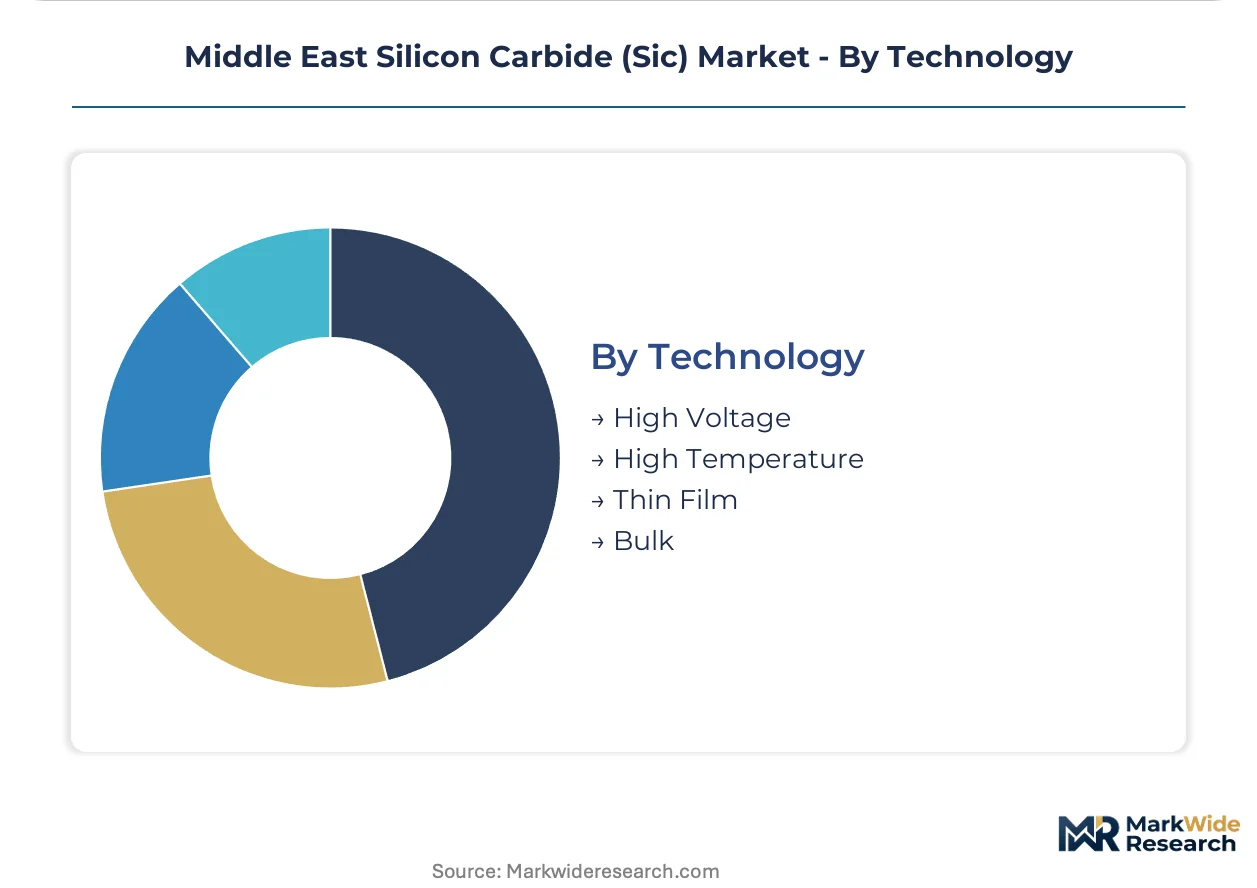
| Segmentation | Product Type: Wafers, Power Devices, Sensors, Substrates End User: Automotive, Energy, Electronics, Aerospace Application: Power Management, RF Devices, Lighting, Electric Vehicles Technology: High Voltage, High Temperature, Thin Film, Bulk |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, ON Semiconductor, Saint-Gobain, Entegris, Washington Mills, ROHM Co. Ltd., Mitsubishi Electric Corporation, Wolfspeed, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Silicon Carbide (Sic) Market Shifts & Advancements
Silicon carbide technology is compressing switching losses and thermal management requirements across Middle East power infrastructure. Three convergent developments are restructuring competitive positioning and procurement patterns.
Trench-gate SiC MOSFET architectures are displacing planar designs in traction inverters and DC-DC converters for electric vehicle drivetrains. Saudi Arabia's Public Investment Fund-backed EV initiatives and UAE fleet electrification mandates are accelerating adoption. This displacement is compressing silicon IGBT market share in automotive power modules and forcing incumbent suppliers to retool fabrication lines.
Saudi Standards, Metrology and Quality Organization efficiency benchmarks for grid-tied inverters above 100kW now effectively mandate wide-bandgap semiconductor adoption. Industrial consequence includes accelerated obsolescence of silicon-based designs in utility-scale solar installations. Grid operators in Riyadh and Jeddah are responding by pre-qualifying only SiC-capable suppliers for renewable procurement tenders.
Long-term power purchase agreements are bundling semiconductor performance guarantees with inverter supply contracts, shifting risk allocation from utilities to device manufacturers. This unbundling of hardware from energy yield assurance is disrupting traditional component vendor relationships. The pattern is most visible in UAE independent power producer auctions where technical evaluation weighting now favors suppliers offering 25-year degradation warranties.
Middle East Silicon Carbide (Sic) Market Segmentation
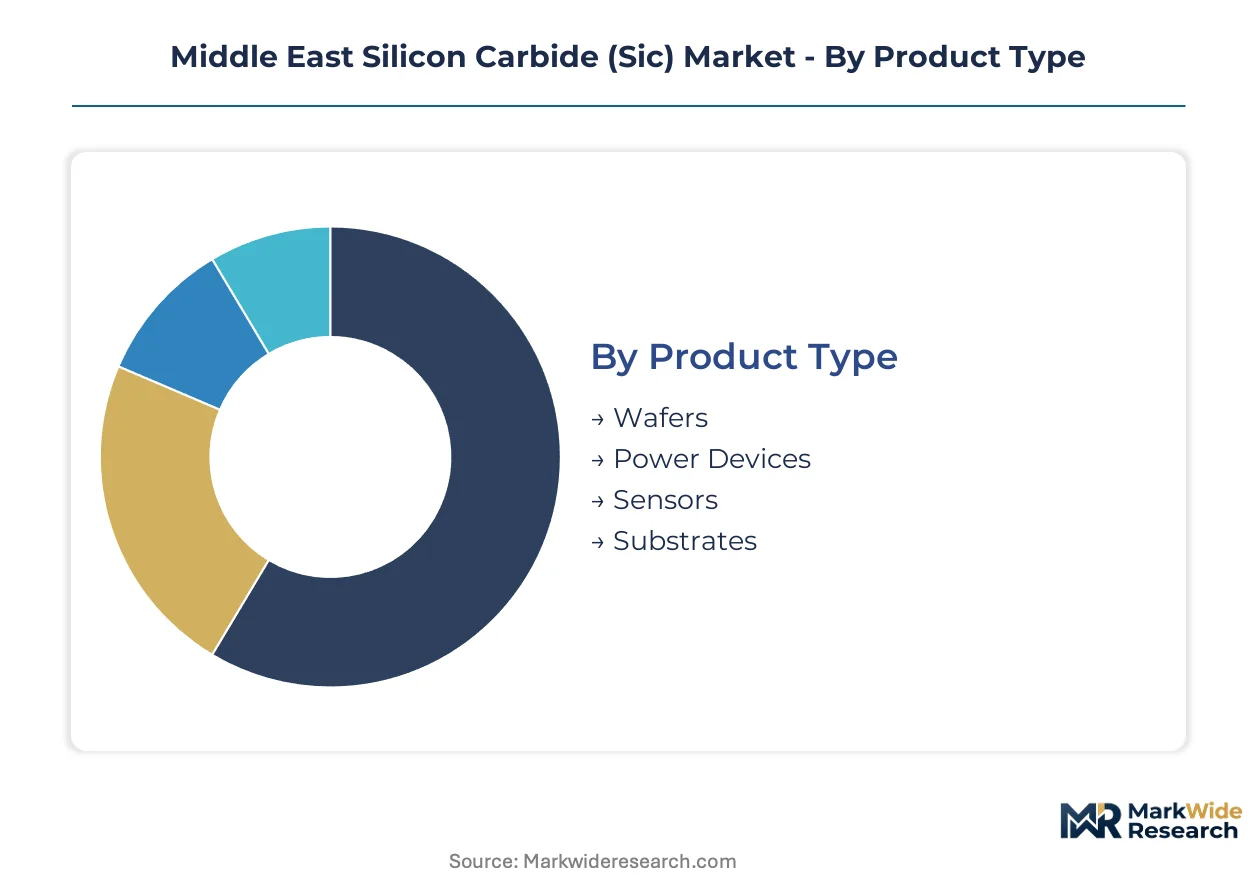
SiC market segmentation in the Middle East reflects competing pressures from gallium nitride substitution, efficiency mandates, and supply chain localization. Understanding how demand fragments across product architectures and end-use applications clarifies where procurement budgets concentrate and where technical specifications diverge most sharply.
Product Type:
Power devices face the most acute substitution threat from silicon IGBTs in cost-sensitive industrial drives below 650V, while wafers enjoy protective scarcity due to crystal growth complexity.
- Power Devices:MOSFETs and Schottky diodes engineered for switching frequencies above 100kHz with thermal tolerance exceeding 200°C. Demand concentrates in Saudi Arabia's NEOM solar inverters and UAE grid-tied storage systems where efficiency mandates from the Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology disqualify silicon alternatives above specified power thresholds.
- Wafers:Electronic-grade substrates manufactured through physical vapor transport achieving 99.9995 percent purity for subsequent device fabrication. Dubai Silicon Oasis and KIZAD free zone incentives are attracting backward integration investments from regional foundries seeking to reduce dependence on Wolfspeed-dominated upstream supply.
- Sensors:High-temperature sensing elements for industrial process monitoring and downhole oilfield applications.
- Substrates:Epitaxy-ready base layers for power module assembly serving automotive and energy customers.
Power devices retain volume leadership; wafers hold the steepest expansion curve.
End User:
Cost tier stratification separates premium efficiency-driven adopters from price-sensitive legacy industrial buyers still evaluating silicon alternatives.
- Automotive:Electric vehicle drivetrain components including traction inverters, onboard chargers, and DC-DC converters. The UAE's Dubai Clean Energy Strategy fleet electrification targets and Saudi Arabia's Public Investment Fund-backed EV manufacturing are compressing qualification timelines for SiC-qualified Tier 1 suppliers.
- Energy:Utility-scale solar inverters, wind turbine converters, and grid stabilization equipment. Procurement from Saudi Arabia's ACWA Power and UAE independent power producers now pre-qualifies only wide-bandgap-capable suppliers for renewable tenders above 100kW.
- Electronics:RF power amplifiers and high-frequency switching supplies for telecommunications infrastructure.
- Aerospace:Satellite power systems and aircraft electrical actuation requiring radiation-hardened wide-bandgap performance.
Energy absorbs the majority of current procurement volume; automotive claims the most aggressive forward growth trajectory.
Application:
Volume concentration in power conversion applications creates margin pressure, while emerging RF and lighting segments offer differentiation opportunities for specialized device architectures.
- Power Management:Grid-tied inverters, motor drives, and uninterruptible power supplies. Gulf Cooperation Council utilities are reorganizing procurement priorities around wide-bandgap semiconductors, displacing traditional silicon buyers as the dominant customer archetype in regional tender processes.
- Electric Vehicles:Traction inverters and charging infrastructure for passenger and commercial fleets. Bidirectional vehicle-to-grid integration requirements in UAE smart city pilots are opening high-margin applications for SiC power modules with extended lifetime guarantees.
- RF Devices:Base station power amplifiers and radar systems leveraging SiC's high electron mobility.
- Lighting:UV-C LED drivers and industrial illumination systems requiring high-temperature operation.
Power management dominates installed base; electric vehicles command the most rapid demand acceleration.
Technology:
Application maturity varies sharply across voltage and temperature ratings, with high-voltage architectures enjoying standardization advantages while thin-film approaches remain development-stage.
- High Voltage:Trench-gate MOSFET designs rated above 1200V for utility-scale renewable integration. Saudi grid operators in Riyadh and Jeddah are responding to efficiency benchmarks by pre-qualifying only SiC-capable suppliers for renewable procurement tenders, accelerating displacement of planar silicon IGBT designs.
- High Temperature:Devices engineered for ambient operation above 175°C without derating. Downhole oilfield applications in Saudi Arabia's Eastern Province and geothermal monitoring in UAE pilot projects concentrate demand for thermally robust packaging.
- Thin Film:Epitaxial layer deposition techniques for RF and sensor applications.
- Bulk:Single-crystal ingot growth methods for substrate production serving regional foundry customers.
High voltage retains technology leadership; high temperature shows the most pronounced adoption slope in industrial process applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC Interconnection Authority's 400kV grid backbone underwrites the Middle East's emergence as a wide-bandgap semiconductor demand center, linking Saudi Arabia's renewable zones with UAE industrial load centers.
Saudi Arabia
NEOM's renewable infrastructure and the Public Investment Fund's EV manufacturing mandates concentrate SiC procurement in the northwest industrial zone. The Saudi Standards, Metrology and Quality Organization enforces efficiency benchmarks above 100kW that disqualify silicon alternatives. Riyadh and Jeddah grid operators now pre-qualify only SiC-capable suppliers for utility tenders.
UAE
Dubai Clean Energy Strategy fleet electrification targets and Abu Dhabi Economic Vision efficiency mandates compress qualification timelines for automotive power module suppliers. The Emirates Authority for Standardization and Metrology regulates grid-tied inverter standards above specified power thresholds. Dubai Silicon Oasis and KIZAD free zones attract backward integration investments from regional foundries seeking substrate production capabilities.
Egypt
Grid modernization programs and solar auction expansions create procurement windows for SiC inverter suppliers before domestic content requirements harden. The Egyptian Electric Utility and Consumer Protection Regulatory Agency oversees renewable integration standards. Cairo and the Suez Canal Economic Zone concentrate early tender activity for utility-scale solar with bundled semiconductor performance guarantees.
Qatar
Utility-scale solar buildouts under the National Renewable Energy Strategy generate demand for high-voltage grid-tied inverters. The Qatar General Electricity and Water Corporation regulates efficiency standards for power conversion equipment. Industrial zones around Doha and Ras Laffan host early pilot deployments of SiC-based power management systems.
Middle East Silicon Carbide (Sic) Market Competitive Landscape
Concentration sits with integrated device manufacturers and specialized substrate producers. The vendor base organizes around three strategic archetypes: European semiconductor conglomerates with captive fabrication, Asian diversified electronics groups, and North American pure-play wafer specialists. Competitive moves center on foundry partnerships for regional device production and long-term supply agreements with Gulf utilities seeking procurement security.
Among European-based integrated suppliers, Infineon Technologies AG and STMicroelectronics exemplify the device-fabrication archetype, anchoring supply relationships with GCC grid operators through established power electronics portfolios. Wolfspeed occupies the upstream substrate tier, representing the crystal-growth specialization that regional foundries must access for backward integration efforts.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| ON Semiconductor |
| Saint-Gobain |
| Entegris |
| Washington Mills |
| ROHM Co. Ltd. |
| Mitsubishi Electric Corporation |
| Wolfspeed |
| Others |
Supply & Pricing Matrix
Silicon IGBT displacement by wide-bandgap alternatives simultaneously redraws procurement geography across the Gulf Cooperation Council and compresses margin structures for device manufacturers serving Saudi Arabia's NEOM zone and the UAE's Dubai Silicon Oasis cluster.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts for SiC power devices in the Middle East, with differentiation driven by wafer grade certification and volume commitment scale. Cost compression in the economy tier is intensifying because regional foundries are qualifying second-source substrate suppliers to reduce dependence on Wolfspeed-dominated upstream supply. Utility buyers in Riyadh and Dubai exhibit the lowest price sensitivity due to efficiency mandates from the Saudi Standards, Metrology and Quality Organization and the Emirates Authority for Standardization and Metrology, while industrial drive manufacturers in Egypt's Suez Canal Economic Zone remain most cost-constrained.
Supply Chain Analysis
The United States and Japan anchor electronic-grade SiC wafer production, while Germany and Italy concentrate device fabrication capacity for automotive and energy applications. Regional supply chains draw from high-purity silicon feedstock, carbon precursor materials, and specialized crystal growth equipment. Single-source vulnerability concentrates in the physical vapor transport ingot segment, where Wolfspeed's dominance creates procurement security risks for Gulf device manufacturers. Distribution runs through authorized distributor networks serving foundries in Dubai Silicon Oasis and direct long-term supply agreements with Saudi Arabia's ACWA Power and UAE independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as power utilities reorganize procurement priorities around wide-bandgap semiconductors, creating specialized niches for substrate suppliers, device fabricators, and system integrators serving divergent efficiency mandates across the Gulf Cooperation Council.
For Market Incumbents: Fortify supply security through captive wafer sourcing agreements or backward integration into substrate production, while accelerating certification investments to meet divergent testing protocols from the Saudi Standards, Metrology and Quality Organization and the Emirates Authority for Standardization and Metrology. Gallium nitride substitution below 650V applications and emerging Chinese device manufacturers present immediate competitive threats requiring defensive patent positioning and foundry capacity reservation in the UAE's KIZAD free zone. For New Entrants and Emerging Players: Lead with vehicle-to-grid integration modules for UAE smart city pilots and Egypt's nascent renewable auction market before domestic content requirements harden. Bidirectional charging infrastructure offers the most penetrable white-space segment, with technical differentiation anchored in 25-year performance guarantees that mirror procurement evaluation criteria in Dubai independent power producer auctions. For Investors and Strategic Acquirers: The market sits at an infrastructure-deployment phase that favors substrate-specialist acquisition targets with physical vapor transport capabilities and established qualification relationships with Gulf grid operators. Long-term viability over a multi-year horizon rests on crystal growth capacity scarcity and regional backward integration momentum. The signal to watch is wafer fabrication investment announcements in Dubai Silicon Oasis or KIZAD that would alter regional supply chain topology and compress margins for pure-play device manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Dubai Silicon Oasis incentives attract foundry investments that reduce Wolfspeed supply dependence for regional device manufacturers. |
| Long-term Supply Agreement with Gulf Utilities | ACWA Power and UAE independent power producers pre-qualify SiC-capable suppliers through bundled performance guarantee contracts. |
| Certification Investment for Dual Market Access | Simultaneous Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology approval accelerates tender participation. |
| Vehicle-to-Grid Module Development | Bidirectional charging requirements in UAE smart city pilots open high-margin applications with extended lifetime guarantees. |
| Regional Foundry Partnership | Joint ventures with Dubai Silicon Oasis cluster participants enable tariff-advantaged production for Gulf Cooperation Council procurement. |
Research Methodology
Desk research of semiconductor trade publications, customs and trade flow databases, and regulatory filing repositories preceded structured interviews with power electronics procurement officers at Gulf utilities, device fabrication executives at European and Asian suppliers, crystal growth specialists at substrate manufacturers, and grid planning engineers at Saudi Arabia's ACWA Power and UAE independent power producers. Secondary validation drew from SEC filings of listed semiconductor companies, International Energy Agency renewable deployment trackers, and Gulf Cooperation Council technical regulation harmonization documents. Bottom-up demand modeling across end-use segments triangulated against top-down market sizing from supply-side capacity assessments.
Variance decomposition across product type, end user, application, and technology segmentation dimensions structured the analytical framework over the projection horizon. CAGRs derived from installed base growth rates, substitution elasticity estimates for silicon IGBT displacement, and efficiency mandate compliance timelines across Saudi Arabia, the UAE, and Egypt. Industry-specific forecast inputs included electric vehicle fleet penetration targets under the Dubai Clean Energy Strategy and NEOM renewable infrastructure buildout schedules.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council grid modernization investment, stable high-purity silicon feedstock pricing, and continued wide-bandgap semiconductor efficiency mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding physical vapor transport capacity expansion, gallium nitride competitive dynamics below 650V, and regional foundry qualification timelines. Recalibration cycles align with material shifts in Saudi Arabia's domestic content requirements, UAE advanced manufacturing incentive revisions, and Egyptian solar auction program expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Semiconductor Grade PTFE Market
Semiconductor Material
India Silicon Carbide (Sic) Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Global Magnesium Oxide Nanopowder Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Sapphire Ingot Market
Semiconductor Material
Electronic-Grade Polysilicon Market