
 Organic Silicon Coating Market | 2026-2036
Organic Silicon Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Silicon Coating Market Analysis
Aftermarket service revenue for protective coating reapplication is reshaping profit distribution across the value chain. Dow leverages backward integration into siloxane feedstocks to secure raw material continuity. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex. Shin-Etsu Chemical dominates high-purity electronics-grade formulations for semiconductor packaging applications.
Organic silicon coatings are polymeric formulations based on siloxane backbones, typically applied at film thicknesses of 25–250 microns to provide thermal stability, moisture resistance, and dielectric protection across substrates ranging from metal to polymer composites. Their primary commercial purpose centers on extending asset life in harsh environments while reducing maintenance frequency. Silicone resins command premium positioning in high-temperature industrial applications where thermal degradation resistance determines specification. Water-based technology segments are gaining formulation share as manufacturers respond to solvent emission restrictions in multiple jurisdictions. UV curing systems occupy specialized niches in electronics assembly where line-speed throughput governs process economics.
EPA regulations on hazardous air pollutants from coating operations constrain solvent-based formulation deployment in the United States. REACH registration requirements and the EU Green Deal's decarbonization targets are redirecting European R&D toward bio-based siloxane precursors. China's MEE enforcement of GB standards on industrial VOC emissions is accelerating water-based technology transitions in manufacturing hubs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and maintain cross-border product registration compliance.
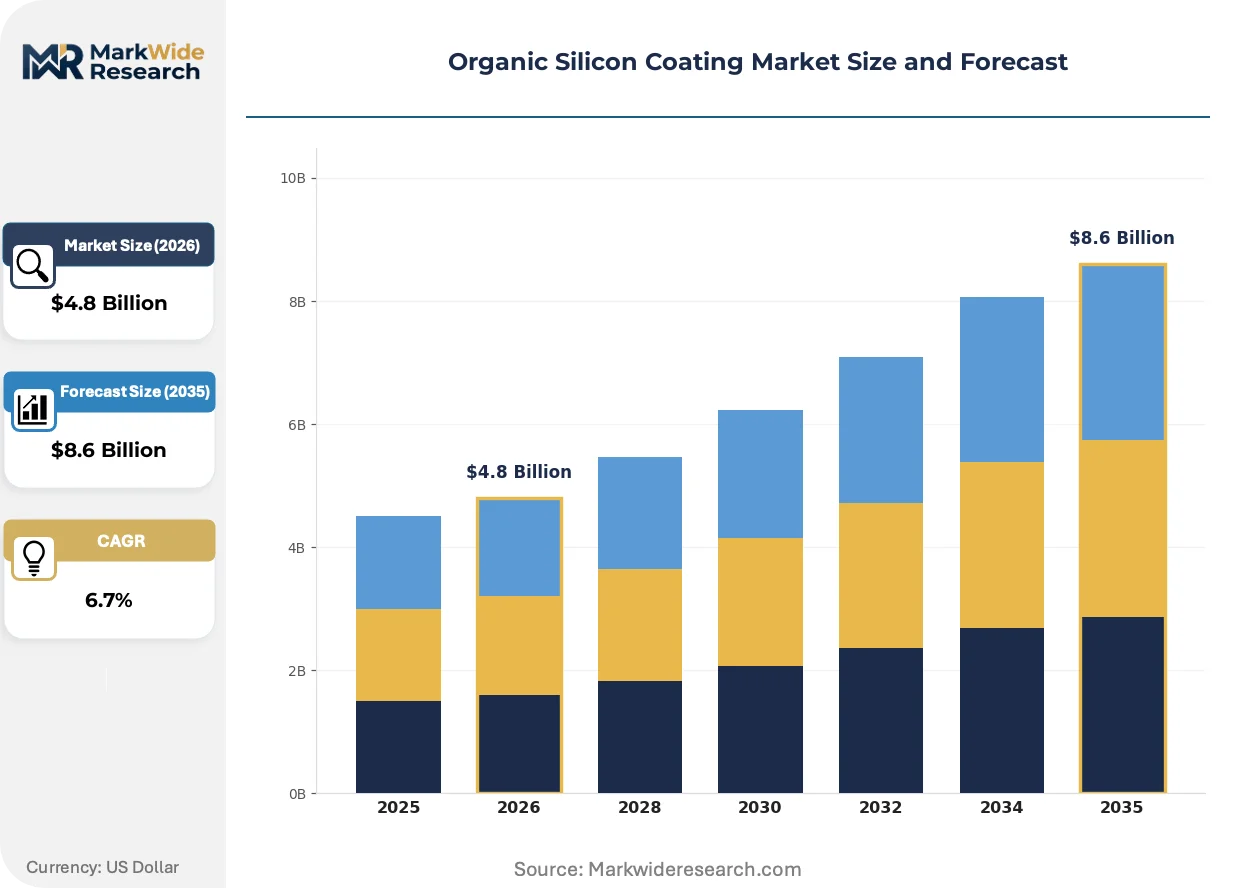
Market Dynamics
Water-based silicone formulations are displacing solvent-borne systems as MEE enforcement of GB standards tightens across Chinese manufacturing zones, compressing traditional formulation margins while rewarding early movers with regulatory compliance advantages.
Growth Catalysts
- Electronics-grade purity requirements:Semiconductor packaging applications in Shenzhen and Seoul metropolitan areas demand ultra-low ionic content silicone coatings, pulling investment toward specialized siloxane purification infrastructure.
- REACH registration completion:Full dossier compliance for siloxane intermediates under ECHA timelines has cleared market access for European formulators serving automotive thermal management segments.
- UV curing line-speed economics:Electronics assembly operations in South Korea are specifying sub-30-second cure cycles, forcing coating suppliers to reformulate photoinitiator packages for throughput parity.
Market Restraints
- Siloxane feedstock concentration:Captive supply chains controlled by integrated petrochemical majors in Germany and Japan limit independent formulator access to high-purity D4-D6 cyclic siloxanes.
- Technical performance ceiling:Water-based silicone resins currently fail to match solvent-borne systems in continuous operating temperatures above 200°C, constraining specification in aerospace engine applications.
- Substitution pressure from fluoropolymers:PTFE and FEP coatings are capturing share in extreme chemical exposure environments where silicone degradation rates exceed asset-life requirements.
Strategic Opportunities
- Underpenetrated Indian electronics assembly:PLI scheme incentives for semiconductor packaging in Gujarat and Tamil Nadu are creating first-mover advantages for coating suppliers establishing local formulation capacity.
- Bio-based siloxane precursors:EU Green Deal R&D funding is accelerating fermentation-derived silicone feedstock development, offering carbon-intensity credentials for premium positioning.
- Convergence of thermal interface and protective coating functions:Single-layer formulations combining dielectric protection with heat dissipation are displacing multi-material stacks in power electronics modules.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in siloxane polymerization kinetics and cure chemistry is concentrated among retiring cohorts in European and Japanese technical centers.
- Dual-registration burden:Separate REACH and China REACH (MEE Order 12) compliance timelines are forcing parallel toxicology studies, stretching SME R&D budgets.
- Legacy equipment retrofit costs:Water-based system transitions require humidity-controlled spray booths and infrared drying arrays, complicating brownfield manufacturing upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Silicon Coating Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Emulsions, Silicone Resins, Silicone Sealants, Silicone Adhesives End User: Construction, Automotive, Electronics, Textiles Technology: Thermal Curing, UV Curing, Solvent-Based, Water-Based Application: Coatings, Adhesives, Sealants, Insulation |
| Companies Covered | Dow, BASF, Evonik Industries, KCC Corporation, Elkem ASA, Shin-Etsu Chemical, Momentive, ChemChina, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Silicon Coating Market Emerging Trajectories
Formulation chemistry is pivoting toward ambient-cure water-based systems as regulatory pressure compounds against high-VOC solvent technologies, reshaping equipment specifications and application training requirements across industrial coating operations.
Nano-silica reinforced silicone hybrids are rendering obsolete conventional unfilled resin systems in high-wear industrial flooring applications. Automotive underhood component suppliers in Germany are specifying these composites for thermal cycling resistance. The technology is compressing maintenance intervals from annual recoating to five-year cycles in heavy equipment fleets.
EPA hazardous air pollutant standards for coating operations are forcing solvent-based formulation withdrawals from US appliance manufacturing. Metal substrate finishing facilities in Ohio and Wisconsin are converting to water-borne silicone systems ahead of compliance deadlines. The regulatory pressure is accelerating capital allocation toward infrared curing infrastructure among mid-tier applicators.
Specification authority is migrating from procurement departments to reliability engineering functions as total-cost-of-ownership modeling penetrates protective coating selection. Electronics OEMs in South Korea are unbundling coating decisions from commodity purchasing categories. The shift is most visible in Shenzhen cluster operations where line-failure cost attribution has elevated technical qualification timelines.
Organic Silicon Coating Market Segmentation
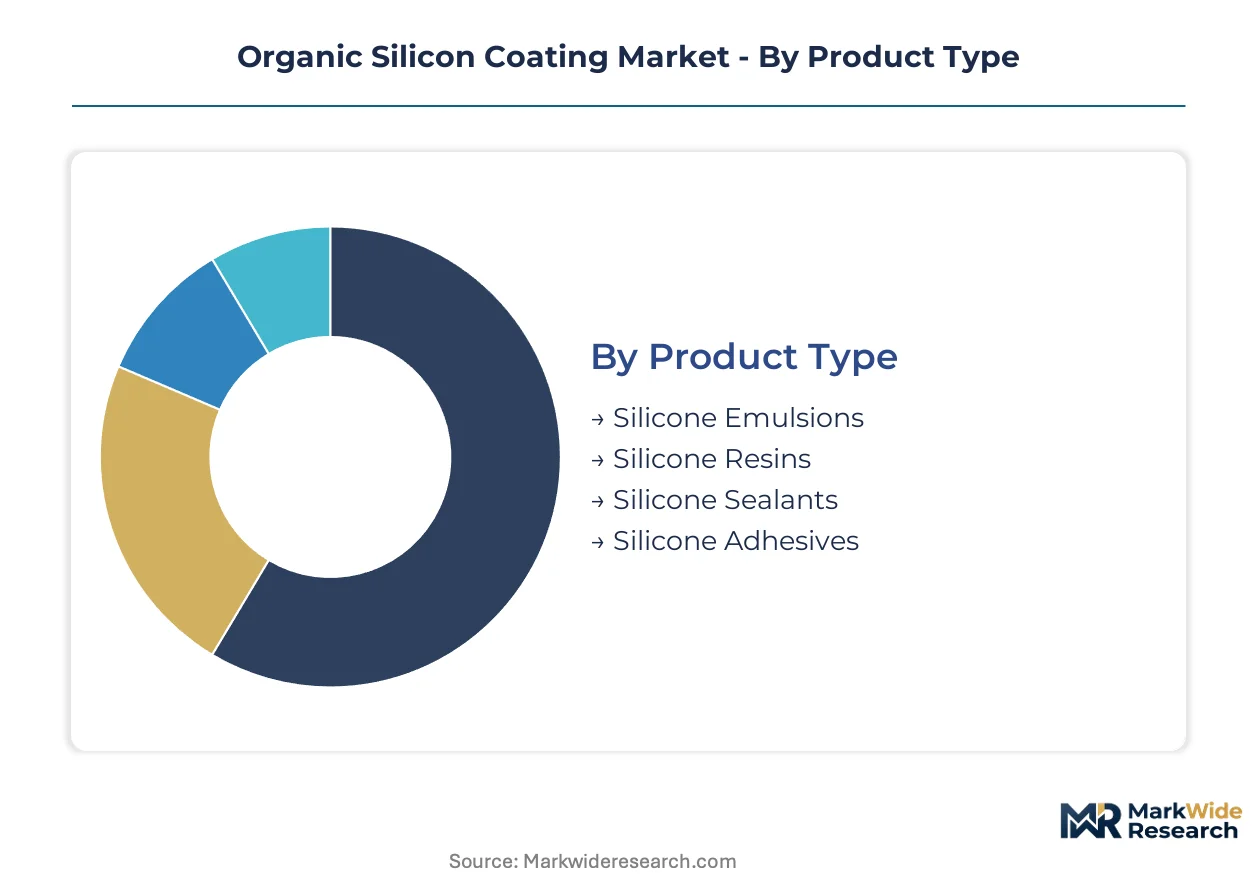
Segmentation in organic silicon coatings reveals divergent margin profiles and specification cycles across formulation chemistries and end-use verticals. Product type and technology choices determine capital intensity and regulatory exposure, while end-user concentration shapes geographic demand clustering.
Product Type:
Cycle times vary sharply: emulsion formulations refresh annually with regulatory shifts, while resin systems lock in specifications across multi-year automotive platform cycles.
- Silicone Resins:These high-molecular-weight siloxane polymers deliver thermal stability exceeding 200°C continuous operation. Automotive underhood component suppliers in Germany specify these for power electronics thermal management modules.
- Silicone Emulsions:Water-dispersed systems with 40-60% solids content dominate textile finishing applications. Chinese textile manufacturers in Zhejiang province are converting from solvent systems to meet MEE VOC enforcement timelines.
- Silicone Sealants:Neutral-cure formulations command construction specification for structural glazing joints.
- Silicone Adhesives:Pressure-sensitive and structural grades serve electronics assembly bonding requirements.
Silicone resins anchor the volume base while silicone emulsions gain share at the steepest rate.
End User:
Margin tiers separate construction commodity applications from electronics-grade purity premiums, with automotive thermal management occupying the mid-tier value position.
- Electronics:Ultra-low ionic content specifications for semiconductor packaging demand specialized siloxane purification. Shenzhen and Seoul metropolitan clusters drive specification intensity for conformal coating applications.
- Automotive:Underhood thermal cycling resistance and battery pack thermal interface requirements pull formulation innovation toward hybrid nano-filled systems.
- Construction:Weatherproofing and structural glazing applications specify neutral-cure sealants across commercial building envelopes.
- Textiles:Soft-hand finishing and water-repellency treatments in apparel manufacturing utilize emulsion-based systems.
Electronics commands the highest specification premiums while automotive expands most quickly on electrification-driven thermal management demand.
Technology:
Application throughput economics and emission compliance trajectories are diverging technology adoption curves across manufacturing jurisdictions.
- Water-Based:Emulsion and dispersion systems with 50-150°C cure profiles serve textile and construction applications. Chinese manufacturing hubs are accelerating conversion ahead of MEE GB standard enforcement deadlines.
- Thermal Curing:Elevated-temperature condensation and addition-cure systems deliver crosslink density for automotive and industrial applications.
- UV Curing:Photoinitiator-activated systems achieve sub-30-second cure cycles. South Korean electronics assembly operations specify these for line-speed parity in high-volume manufacturing.
- Solvent-Based:Hydrocarbon-carried systems retain specification where water-borne performance ceilings constrain adoption.
Thermal curing retains the broadest application base while water-based technology climbs the fastest on regulatory displacement.
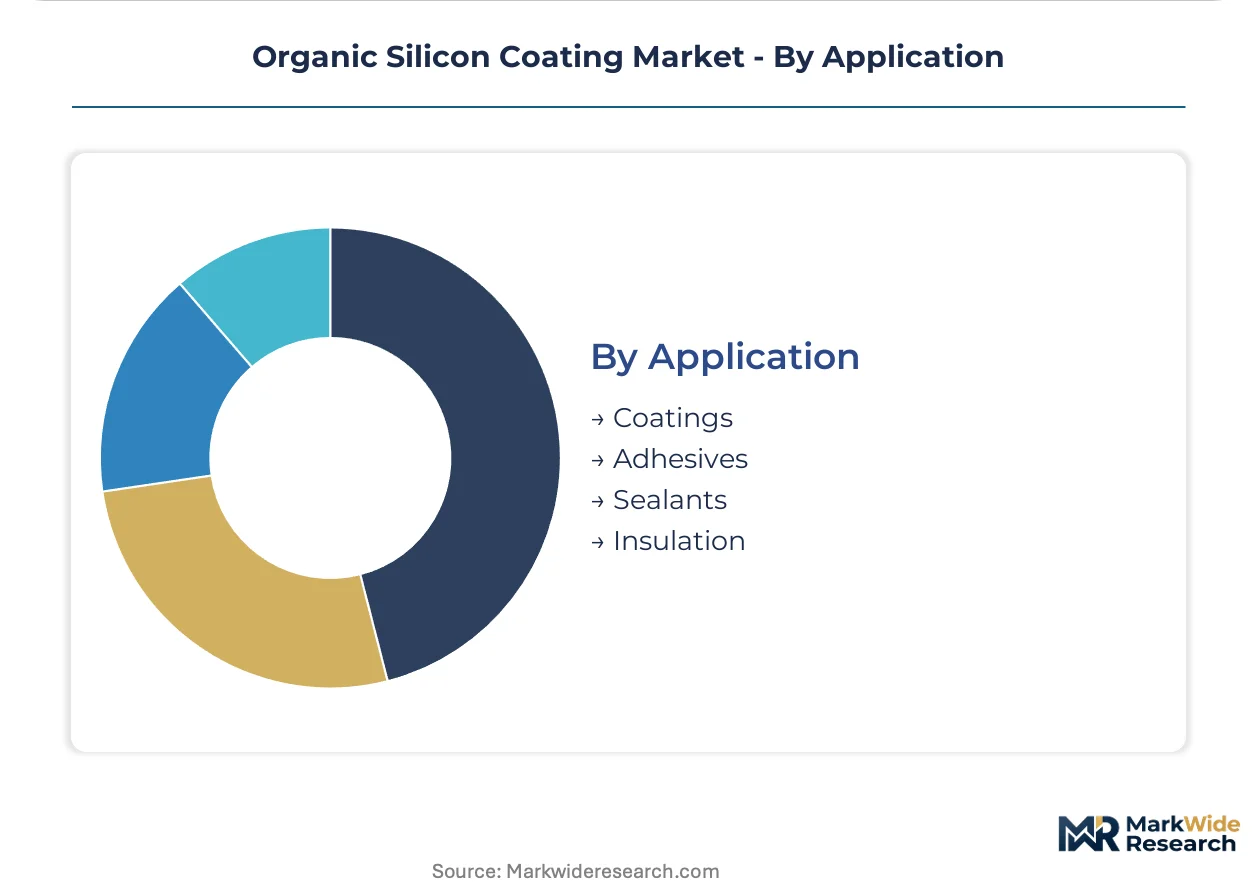
Application:
Functional integration trends are collapsing multi-material stacks into single-layer formulations, reshaping application boundaries across end-use verticals.
- Coatings:Protective films at 25-250 micron thickness deliver dielectric and moisture barrier functions. Electronics-grade coatings in Shenzhen cluster operations specify ionic content below 10ppm for circuit board protection.
- Adhesives:Structural bonding and thermal interface functions converge in power electronics module assembly.
- Sealants:Joint movement accommodation and weatherproofing dominate construction specification.
- Insulation:Dielectric and thermal barrier functions serve wire and cable applications.
Coatings anchor the volume base while adhesive applications gain share fastest on thermal interface functional convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: East Asian electronics clusters prioritize ultra-low ionic purity for semiconductor packaging, while European automotive suppliers emphasize thermal cycling resistance for electrification platforms, and North American industrial users balance emission compliance with high-temperature performance requirements.
China
Electronics manufacturing concentration in Shenzhen and the Pearl River Delta drives conformal coating specification intensity for circuit board protection. MEE enforcement of GB standards on industrial VOC emissions is accelerating water-based formulation transitions across Zhejiang and Jiangsu manufacturing hubs. Shanghai-based textile finishers are converting emulsion systems ahead of regulatory deadlines.
United States
Appliance manufacturers in Ohio and Wisconsin face EPA hazardous air pollutant standards forcing solvent-based formulation withdrawals from metal substrate finishing. Industrial coating operations in the Midwest are retrofitting humidity-controlled spray booths and infrared drying arrays for water-based system compatibility. Ohio facilities are converting ahead of compliance timelines.
Germany
Automotive underhood component suppliers specify silicone resins for power electronics thermal management modules serving electrification platforms. REACH registration requirements under ECHA timelines have cleared market access for siloxane intermediates serving automotive thermal management segments. Burghausen manufacturing complexes anchor European supply continuity.
South Korea
Electronics assembly operations in the Seoul metropolitan area specify UV curing systems with sub-30-second cure cycles for high-volume manufacturing throughput. Semiconductor packaging applications demand ultra-low ionic content formulations, pulling investment toward specialized siloxane purification infrastructure. Busan-Ulsan industrial corridors support coating material distribution.
India
PLI scheme incentives for semiconductor packaging in Gujarat and Tamil Nadu are creating first-mover advantages for coating suppliers establishing local formulation capacity. Electronics assembly expansion in Delhi-NCR and Karnataka is pulling demand for conformal coating materials. BIS standards on industrial chemical emissions are tightening formulation requirements for domestic manufacturers.
Organic Silicon Coating Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors possessing captive siloxane feedstock control; scale advantage sits with diversified chemical conglomerates serving multiple end-use verticals. The market structures around three tiers: backward-integrated siloxane producers, specialized electronics-grade formulators, and regional coating compounders. Dominant competitive moves include capacity expansion in high-purity D4-D6 cyclic siloxanes and geographic partnerships to secure electronics cluster proximity.
Within the integrated producer tier, Dow and Wacker Chemie AG exemplify archetypes combining feedstock security with formulation expertise. Shin-Etsu Chemical occupies a position representing specialized electronics-grade purity capabilities. Among diversified chemical conglomerates, BASF and Evonik Industries sit within portfolios leveraging cross-divisional technology transfer. KCC Corporation and Elkem ASA represent regional specialists with concentrated geographic footprints. Momentive and ChemChina exemplify scale-driven positions serving industrial volume applications.
| Leading Market Players |
|---|
| Dow |
| BASF |
| Evonik Industries |
| KCC Corporation |
| Elkem ASA |
| Shin-Etsu Chemical |
| Momentive |
| ChemChina |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Shanghai-Busan container freight corridors dictate cost absorption patterns across the organic silicon coating value chain, amplifying pricing power for German and Japanese siloxane producers while compressing margins for independent formulators serving Shenzhen electronics clusters.
Pricing Analysis
Long-term offtake contracts anchor volume procurement for automotive thermal management tiers, while spot purchasing dominates electronics-grade specialty formulations where purity specifications command premium positioning. Pricing stratifies across electronics-grade, automotive-standard, and industrial-economy tiers based on ionic content thresholds and certification status. Cost compression in water-based emulsion segments is intensifying as Chinese MEE enforcement accelerates formulation transitions. Electronics OEMs in South Korea exhibit the lowest price sensitivity due to line-failure cost attribution, while textile finishers in Zhejiang province face acute margin pressure from regulatory compliance investments.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculus for European formulators dependent on Burghausen-sourced D4-D6 cyclic siloxanes. Captive production of high-purity siloxane feedstocks concentrates in Germany, Japan, and the United States, drawing from methyl chloride and silicon metal inputs. Single-source vulnerability persists for semiconductor-grade purification equipment tethered to Japanese and Dutch suppliers. Distribution runs through regional compounding hubs in Shenzhen, Seoul, and Burghausen serving downstream electronics and automotive assembly operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among South Korean electronics OEMs and German automotive Tier 1 suppliers, fragmenting procurement leverage for mid-tier formulators and reshaping contract negotiation dynamics across the value chain.
For Market Incumbents: Entrench feedstock security through backward integration into siloxane monomer production or long-term supply agreements with German and Japanese petrochemical majors. Deepen certification investments for REACH and China REACH dual registration to defend specification authority against emerging regional compounders in India and Southeast Asia. For New Entrants and Emerging Players: Establish a beachhead in Gujarat and Tamil Nadu semiconductor packaging corridors where PLI scheme incentives are pulling first-mover formulation capacity. Target UV curing system segments serving South Korean electronics assembly operations, leveraging technical partnerships with local photoinitiator suppliers as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking portfolio rationalization away from industrial coating commodities. Long-term viability centers on electronics-grade purity capabilities and bio-based siloxane precursor development under EU Green Deal funding trajectories. Monitor MEE enforcement intensity in Jiangsu and Zhejiang provinces as the critical inflection signal for water-based technology displacement speed.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstocks | Dow and Wacker Chemie AG secure raw material continuity against D4-D6 supply bottlenecks. |
| Dual REACH Registration Completion | ECHA and MEE Order 12 compliance clears market access for automotive thermal management segments. |
| UV Curing System Reformulation | Sub-30-second cure cycles achieve line-speed parity for Seoul metropolitan electronics assembly operations. |
| Bio-Based Siloxane Precursor Development | Fermentation-derived feedstocks unlock EU Green Deal R&D funding for carbon-intensity positioning. |
| Indian Formulation Capacity Establishment | Gujarat and Tamil Nadu facilities capture PLI scheme semiconductor packaging incentives. |
Methodological Framework
A standing panel of plant managers at siloxane production facilities, procurement leads at electronics OEMs, distribution channel partners in East Asian logistics hubs, and technical R&D directors at formulation houses provided ongoing calibration against operating reality. Primary interview findings triangulated with customs and trade data from Chinese and South Korean port authorities, ACC and Cefic industry association reports, and SEC 10-K disclosures from integrated chemical producers. Bottom-up volume builds across end-use segments reconciled against top-down macroeconomic indicators.
Scenario-bracketing around regulatory enforcement intensity and feedstock supply disruption anchored the analytical framework across the projection horizon. Segmentation modeling incorporated formulation chemistry, cure technology, end-use vertical, and regional manufacturing hub dimensions. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included MEE GB standard implementation timelines and semiconductor capital expenditure cycles.
Sensitivities concentrate around REACH registration timeline delays, MEE enforcement variability across Chinese provincial jurisdictions, and siloxane feedstock supply disruptions from German manufacturing complexes. Forecasts reflect assumptions about regulatory trajectory continuity and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Global Polybutylene Terephthalate (PBT) Market
Semiconductor Material
Yttrium Oxide Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Polycrystalline Silicon Market
Semiconductor Material
Global Gallium Oxide Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Silicon Hydride Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Europium Market
Semiconductor Material
Wet Chemicals for Electronics and Semiconductor Application Market
Semiconductor Material
Polysilicon Market