
 Cadmium Telluride Market | 2026-2036
Cadmium Telluride Market Size, Share, and Industry Trends Forecast 2026-2036
Cadmium Telluride Market Outlook
Chinese polysilicon and tellurium refiners are expanding purification capacity to feed CdTe supply chains. First Solar leverages integrated module manufacturing across Ohio, Alabama, and Louisiana to sustain cost leadership in utility-scale tenders. 5N Plus anchors North American tellurium refining, while II-VI Incorporated competes in substrate and optical materials adjacent to photovoltaic applications.
Cadmium telluride is a II-VI compound semiconductor with a direct bandgap of approximately 1.5 eV, deposited via vapor transport or close-space sublimation onto glass substrates to form p-n heterojunction photovoltaic devices. Its primary commercial purpose is converting sunlight to electricity in thin-film solar configurations that tolerate high temperatures and partial shading better than crystalline silicon alternatives. Thin film solar cells occupy the dominant product position due to decades of manufacturing refinement and bankability among project financiers. The utility end-user segment leads volume absorption, while BIPV technology applications represent an emerging margin pool where building-integrated aesthetics command pricing premiums.
EPA hazardous waste rules govern cadmium handling and end-of-life module recycling obligations in the United States. REACH restrictions in Europe limit cadmium content in electrical equipment, while the EU Green Deal's renewable targets indirectly shape CdTe demand through national solar auctions. Stakeholders must monitor tellurium supply concentration and evolving recycling mandates as these factors determine long-term cost structures and market access conditions.
Market Dynamics
The US Inflation Reduction Act's domestic content bonuses have restructured procurement patterns for thin-film solar modules, concentrating utility-scale demand on American manufacturing footprints while tightening tellurium feedstock competition.
Growth Catalysts
- Grid decarbonization mandates:State-level renewable portfolio standards in California, Texas, and Arizona mandate utility-scale solar additions that favor CdTe's temperature coefficient advantages in desert climates.
- Domestic manufacturing incentives:The IRA's advanced manufacturing production credits reduce effective module costs for thin-film producers operating within US borders.
- Tellurium recovery from copper refining:Anode sludge processing improvements at Canadian and Peruvian smelters are expanding secondary tellurium availability for photovoltaic feedstock.
Market Restraints
- Cadmium toxicity classification:EPA hazardous waste rules impose end-of-life recycling obligations that add compliance costs exceeding crystalline silicon alternatives.
- Tellurium supply concentration:Primary tellurium extraction ties to copper electrorefining in China, Mexico, and Russia, creating geopolitical exposure for North American module producers.
- Efficiency ceiling constraints:Laboratory CdTe cell records near 22.1% lag behind commercial PERC and TOPCon silicon architectures above 24%.
Strategic Opportunities
- Building-integrated photovoltaics:Aesthetic thin-film applications in commercial facades and residential roofing command pricing premiums through architectural specification channels.
- Agrivoltaic dual-use deployments:CdTe's spectral selectivity permits partial light transmission compatible with shade-tolerant crop cultivation beneath elevated arrays.
- Recycling infrastructure buildout:Closed-loop cadmium and tellurium recovery systems align with EU Green Deal circular economy requirements and emerging US state extended producer responsibility frameworks.
Industry Challenges
- Thin-film deposition expertise scarcity:Vapor transport and close-space sublimation process engineering talent concentrates at a handful of legacy manufacturing sites.
- Module certification timelines:IEC 61215 and IEC 61646 testing protocols for new form factors extend product introduction cycles by 12-18 months.
- Bankability requirements for new entrants:Project financiers demand multi-gigawatt operational track records that favor incumbent producers in utility-scale tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cadmium Telluride Market |
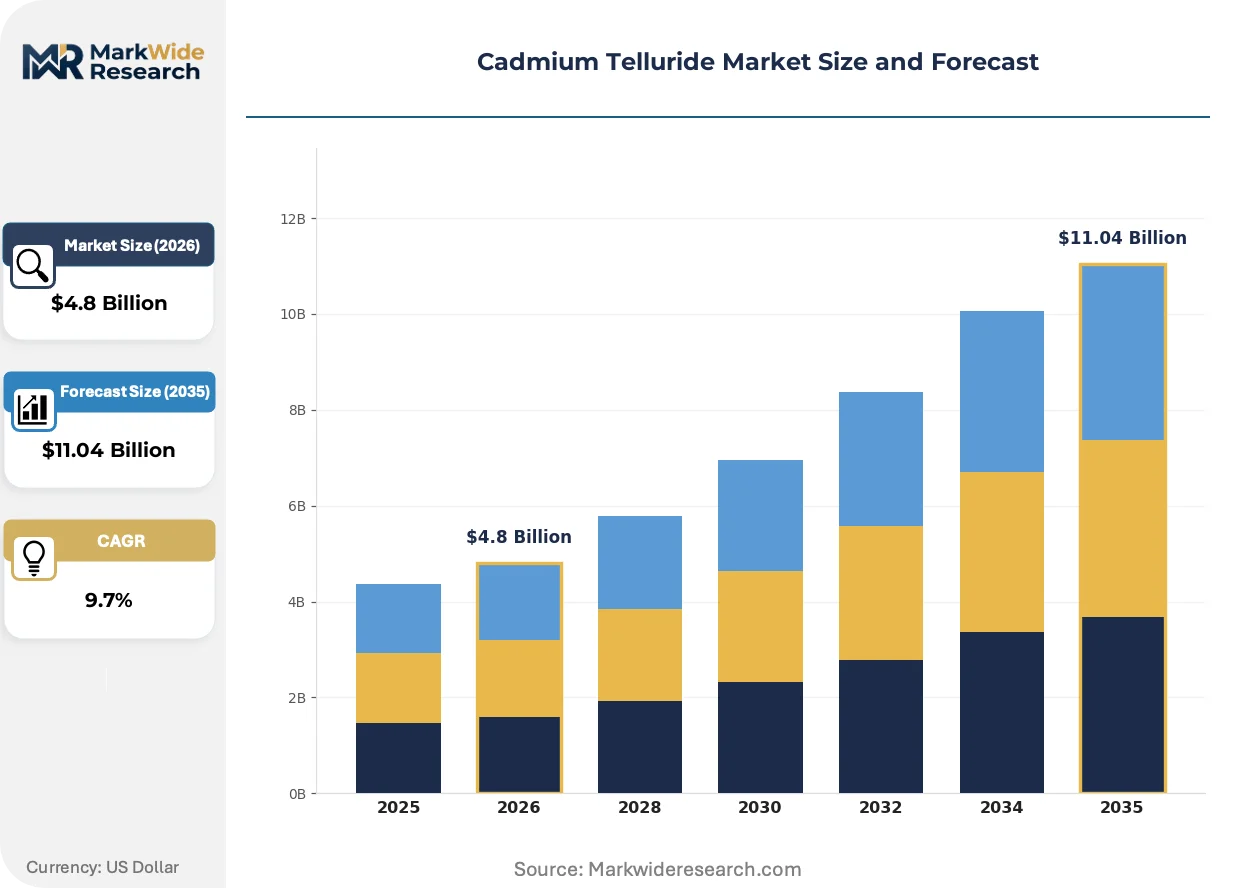
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film Solar Cells, Cadmium Telluride Modules, Thin Film PV, Cadmium Telluride Panels End User: Commercial, Residential, Utility, Industrial Technology: Photovoltaic, Cadmium Telluride Technology, Solar Photovoltaics, BIPV Application: Energy Production, Renewable Energy Projects, Solar Power Generation, Electricity Generation |
| Companies Covered | Advanced Solar Power, Calyxo, First Solar, AVANCIS, CNBM Optoelectronic Materials, 5N Plus, Antec Solar, Global Solar Energy, II-VI Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cadmium Telluride Market Strategic Shifts
Process automation and tellurium recovery technologies are compressing manufacturing cost structures while regulatory frameworks accelerate end-of-life circularity requirements across major photovoltaic demand centers.
Advanced vapor transport deposition systems are automating cadmium telluride layer formation with micron-level thickness uniformity across 3.3-square-meter glass substrates. Utility-scale EPC contractors are specifying these automated lines for gigawatt-scale manufacturing commitments. This automation is compressing labor content per watt and narrowing cost gaps with imported crystalline silicon modules.
The EU's REACH restrictions on cadmium content in electrical equipment have tightened disclosure requirements for photovoltaic imports into European member states. Module suppliers must document recycling arrangements and cadmium containment protocols to maintain market access. BIPV architects in Germany and the Netherlands are responding by specifying thin-film products from manufacturers with pre-certified end-of-life take-back programs.
Utility procurement teams are consolidating module purchasing through multi-year framework agreements rather than project-specific tenders. This concentration is displacing spot-market transactions and favoring manufacturers with demonstrated supply continuity. The southwestern United States exhibits this pattern most acutely, where California and Texas utilities are locking in five-year supply commitments with domestic thin-film producers.
Cadmium Telluride Market Segmentation
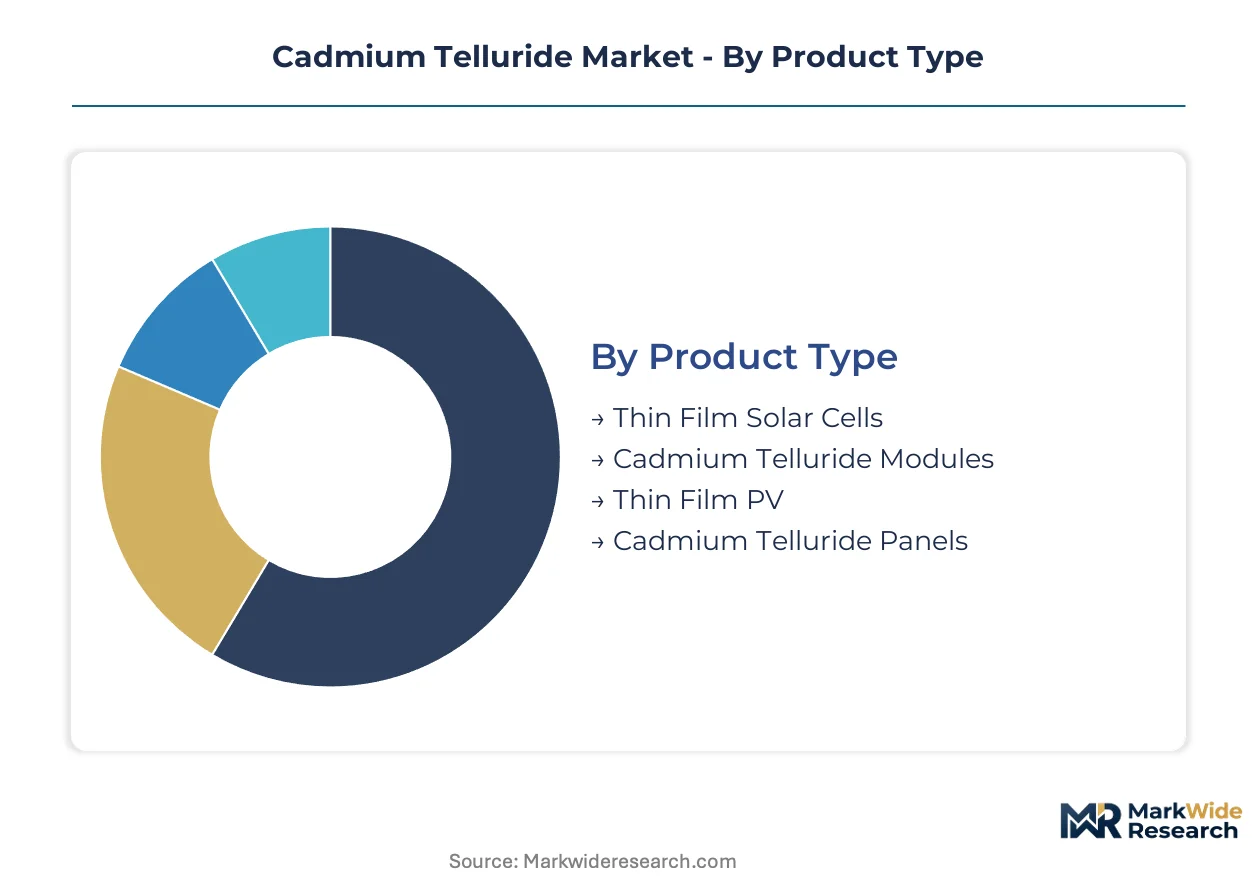
Cadmium telluride market segmentation reveals how manufacturing scale, end-use economics, and regulatory exposure shape procurement decisions. Buyers prioritize bankability, temperature performance, and domestic content compliance when selecting across product configurations.
Product Type:
Cost tier determines procurement channel access, with premium specifications commanding dedicated supply agreements while standard configurations compete in open tenders.
- Thin Film Solar Cells:Individual cell units feature vapor-deposited CdTe absorber layers on glass substrates with micron-level thickness control. Utility-scale developers in Arizona and Texas specify these for high-temperature desert installations where silicon degradation accelerates. IRA domestic content bonuses steer procurement toward American-manufactured thin-film cells.
- Cadmium Telluride Modules:Fully assembled units integrate multiple cells with encapsulation and junction boxes for field deployment. Southwestern US utilities favor these for five-year framework agreements requiring demonstrated supply continuity and end-of-life recycling protocols.
- Thin Film PV:Generic thin-film photovoltaic category encompasses CdTe alongside competing absorber chemistries. Commercial rooftop installers specify these where weight constraints and partial shading tolerance outweigh efficiency premiums.
- Cadmium Telluride Panels:Framed glass-glass assemblies optimized for utility-scale racking systems. EPC contractors in California specify these for agrivoltaic dual-use projects requiring spectral selectivity for crop cultivation beneath arrays.
Volume sits with Cadmium Telluride Modules; growth tilts toward Thin Film Solar Cells as automated deposition expands cell-level supply flexibility.
End User:
Application scale dictates financing structure and technology selection, with gigawatt-scale procurement favoring proven bankability over incremental efficiency gains.
- Utility:Investor-owned utilities and independent power developers dominate volume absorption through multi-gigawatt procurement programs. Texas and California utilities leverage IRA production tax credits and domestic content bonuses to lock in long-term thin-film supply commitments.
- Commercial:Corporate offtakers and commercial real estate developers specify CdTe for behind-the-meter installations where depreciation schedules and renewable energy credits improve project returns. BIPV facades in Germany command pricing premiums through architectural specification channels.
- Residential:Distributed rooftop installations represent smaller unit volumes with higher customer acquisition costs. Efficiency ceilings constrain CdTe competitiveness against crystalline silicon in space-constrained residential applications.
- Industrial:Manufacturing facilities and data centers procure on-site generation to manage electricity costs and sustainability commitments. EPA hazardous waste rules impose recycling obligations that favor suppliers with certified end-of-life programs.
Utility captures dominant share; Commercial expands most quickly as corporate renewable procurement accelerates.
Technology:
Technical maturity separates bankable commercial offerings from emerging configurations still navigating certification timelines.
- Photovoltaic:Broad category encompassing all solar electricity conversion technologies. CdTe occupies a distinct niche within photovoltaic applications where thin-film deposition tolerates high temperatures and partial shading better than crystalline alternatives.
- Cadmium Telluride Technology:Proprietary vapor transport and close-space sublimation processes deposit II-VI compound semiconductor layers with direct bandgap near 1.5 eV. First Solar's integrated manufacturing across Ohio, Alabama, and Louisiana anchors this technology's commercial deployment.
- Solar Photovoltaics:Industry-standard terminology covering all solar-to-electric conversion systems. CdTe modules compete within solar photovoltaics on cost-per-watt and temperature coefficient rather than peak efficiency.
- BIPV:Building-integrated photovoltaics replace conventional building materials with power-generating surfaces. Aesthetic thin-film applications in Dutch and German commercial facades command pricing premiums through architectural channels.
Solar Photovoltaics represents installed base; BIPV gains share fastest as facade-integrated specifications proliferate.
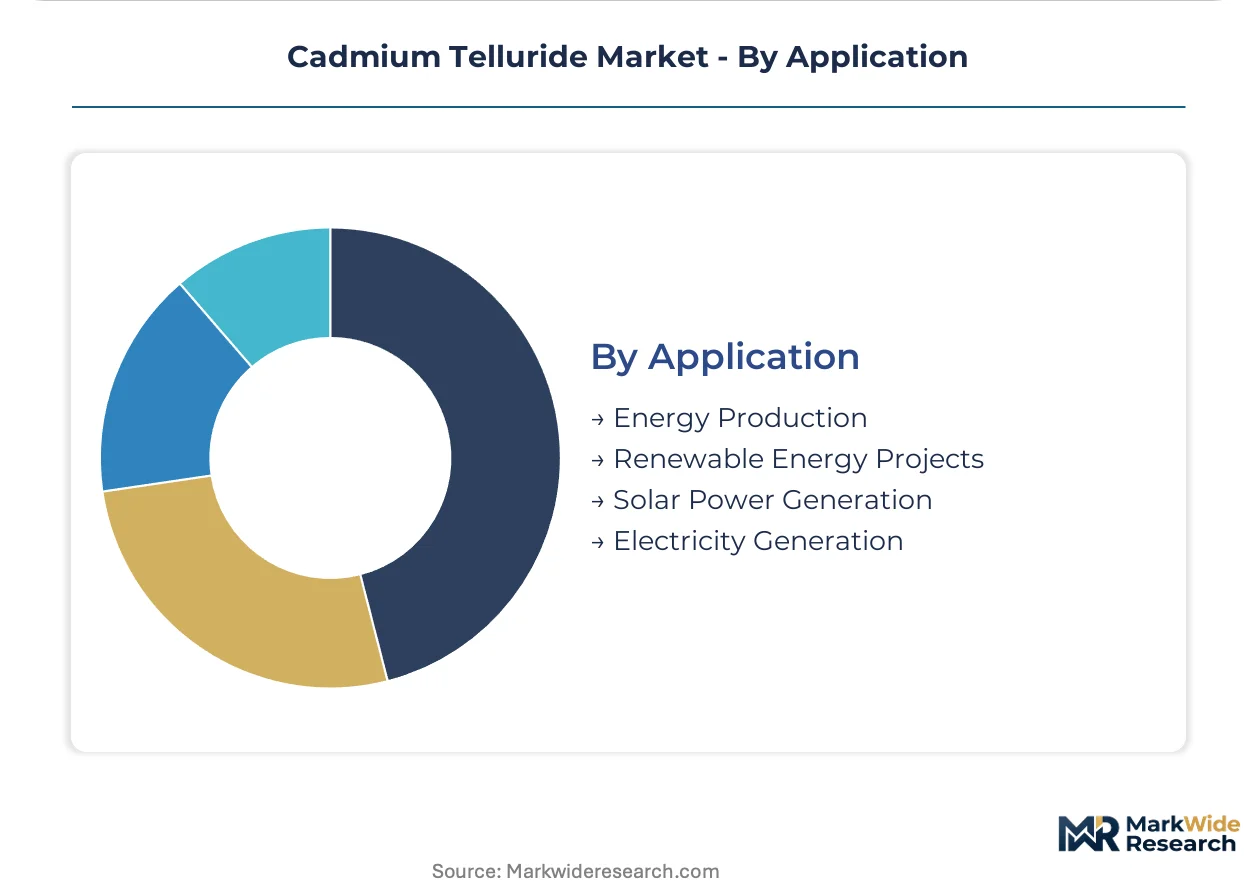
Application:
Project type determines regulatory exposure and revenue structure, with grid-connected generation facing distinct permitting requirements from distributed installations.
- Energy Production:Bulk electricity generation for grid injection or corporate offtake. Utility-scale CdTe deployments in the southwestern United States exploit high insolation and available land for gigawatt-scale solar farms.
- Renewable Energy Projects:Development category encompassing solar, wind, and storage combinations. EU Green Deal renewable targets indirectly shape CdTe demand through national solar auctions with domestic content preferences.
- Solar Power Generation:Technology-specific application category. Cadmium telluride solar power generation benefits from superior temperature coefficients in desert climates where silicon performance degrades.
- Electricity Generation:Universal end-use spanning residential, commercial, and industrial consumption. FERC interconnection rules and state renewable portfolio standards govern electricity generation project economics across US markets.
Electricity Generation holds volume concentration; Renewable Energy Projects show steepest expansion trajectory as hybrid project structures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tellurium refineries in southwestern China and copper smelters in central Mexico anchor raw material flows for cadmium telluride supply chains. Module assembly concentrates in American manufacturing corridors where domestic content bonuses reshape procurement geography.
United States
Utility-scale solar farms in Arizona and Texas absorb the majority of CdTe module volume as grid decarbonization accelerates. The Inflation Reduction Act's domestic content bonuses steer procurement toward American thin-film producers with integrated manufacturing footprints. First Solar operates deposition facilities across Ohio, Alabama, and Louisiana to capture IRA production tax credits.
China
Polysilicon and tellurium refiners in Jiangsu and Henan provinces are expanding purification capacity to feed photovoltaic supply chains. The Ministry of Ecology and Environment enforces cadmium handling standards that govern waste classification for semiconductor manufacturing. Anode sludge processing improvements at copper smelters in Jiangxi are expanding secondary tellurium availability for export markets.
Germany
Building-integrated photovoltaic architects in Munich and Stuttgart specify thin-film products for commercial facade applications. REACH restrictions limit cadmium content in electrical equipment and mandate recycling arrangement documentation for module imports. The EU Green Deal's renewable targets indirectly shape demand through national solar auctions with sustainability criteria.
Canada
Secondary tellurium recovery from copper electrorefining in Quebec and British Columbia supports North American feedstock security. Environment and Climate Change Canada oversees hazardous waste rules that align with cross-border recycling obligations. 5N Plus anchors tellurium refining capacity in Montreal to supply photovoltaic and optical materials markets.
Peru
Copper mining concentration in the Andean region generates anode sludge containing recoverable tellurium for photovoltaic feedstock. The Ministry of Energy and Mines oversees mining waste regulations that influence secondary material extraction economics. Smelter complexes near Lima are upgrading hydrometallurgical circuits to improve tellurium recovery rates for export.
Cadmium Telluride Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and domestic content compliance capabilities. The vendor base stratifies between integrated module producers, specialty material refiners, and deposition equipment specialists. Three archetypes dominate: vertically integrated thin-film manufacturers, tellurium recovery specialists with backward integration into feedstock, and technology licensors with process expertise. Competitive moves center on capacity expansion in IRA-eligible manufacturing zones and strategic partnerships to secure tellurium offtake agreements.
Among integrated thin-film producers, First Solar exemplifies the scale-driven archetype with American manufacturing footprints optimized for utility procurement. Specialty material specialists include 5N Plus, which occupies a position in North American tellurium refining, and II-VI Incorporated, which sits within the optical materials and substrate tier adjacent to photovoltaic applications. These named entities represent distinct competitive vectors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Advanced Solar Power |
| Calyxo |
| First Solar |
| AVANCIS |
| CNBM Optoelectronic Materials |
| 5N Plus |
| Antec Solar |
| Global Solar Energy |
| II-VI Incorporated |
| Others |
Value Chain & Pricing Dynamics
Automated vapor transport deposition systems are compressing labor content per watt while concentrating manufacturing scale among producers with captive tellurium arrangements. This technological transition simultaneously narrows cost gaps with crystalline silicon and reinforces pricing power for integrated producers with IRA-eligible domestic footprints.
Pricing Analysis
Extended warranty and end-of-life recycling bundling separate premium CdTe module tiers from unbundled spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume-scale commitments in utility framework agreements. Cost compression in standard tiers is intensifying because automated deposition lines reduce unit labor costs. Utility procurement teams demonstrate lowest price sensitivity due to IRA production tax credit absorption, while commercial rooftop installers exhibit highest sensitivity to upfront capital costs.
Supply Chain Analysis
The Inflation Reduction Act's domestic content bonuses are reshaping sourcing patterns toward American manufacturing corridors in Ohio, Alabama, and Louisiana. Tellurium feedstock draws from copper electrorefining operations in China, Mexico, and Russia, while cadmium sourcing rests on zinc smelter byproduct recovery. Single-source vulnerability concentrates in Chinese primary tellurium purification capacity. Distribution runs through multi-year framework agreements with southwestern US utilities rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as tellurium feedstock scarcity and bankability requirements force sub-scale deposition specialists toward exit or acquisition.
For Market Incumbents: Anticipate tellurium supply competition intensifying as Chinese refiners expand purification capacity for export markets. Secure long-term offtake agreements with Canadian and Peruvian copper smelters to anchor feedstock security. Invest in closed-loop recycling infrastructure to satisfy emerging EU and US state extended producer responsibility frameworks and differentiate against crystalline silicon alternatives.
For New Entrants and Emerging Players: Digital specification platforms for BIPV architects in Germany and the Netherlands offer route-to-market access without competing for utility-scale bankability. Target agrivoltaic dual-use deployments in California and Texas where spectral selectivity commands technical specification rather than pure cost competition. Partner with established EPC contractors to bypass multi-gigawatt operational track record requirements in project finance.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty material refiners with backward integration into copper smelter feedstock. Long-term viability hinges on circular economy infrastructure buildout and regulatory alignment across major demand centers. Watch EU Green Deal recycling mandate enforcement timelines as inflection indicator for asset valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Tellurium Recovery Partnership | Long-term offtake agreements with Canadian smelters secure feedstock for IRA-compliant production. |
| Closed-Loop Recycling Buildout | End-of-life cadmium recovery infrastructure satisfies EPA hazardous waste rules and EU REACH requirements. |
| Agrivoltaic Specification Channel | Dual-use deployment expertise opens commercial rooftop segments beyond utility-scale competition. |
| BIPV Architectural Certification | Pre-certified facade integration programs unlock premium pricing in German and Dutch specification channels. |
| Automated Deposition Scale-Up | Micron-level thickness uniformity across large-format substrates compresses manufacturing cost structures. |
Study Parameters
Document review covered SEC filings from thin-film manufacturers, EIA electricity generation databases, and EU REACH regulatory filings, complemented by interviews with utility procurement officers, EPC contractors, and copper smelter technical directors. Secondary validation drew from FERC interconnection records, IEA renewable energy reports, and customs trade data for tellurium and cadmium compounds. Bottom-up module deployment estimates triangulated against top-down tellurium consumption figures from copper refining operations.
Historical capacity expansion patterns cross-referenced against expert panel input on IRA domestic content bonus implementation. Segmentation modeling spanned product configuration, end-user scale, application type, and regional regulatory framework across the projection horizon. CAGRs derived from iterative reconciliation of supply-side capacity announcements and demand-side auction pipelines. Key forecast inputs included state renewable portfolio standard trajectories and tellurium recovery rate improvements at copper smelters.
Inputs from utility procurement officers and thin-film manufacturing executives were available through the study window; gaps in proprietary tellurium offtake contract terms introduce uncertainty bands around feedstock cost assumptions. Forecasts reflect documented capacity expansion timelines and regulatory implementation schedules. Technology substitution risk from perovskite and tandem architectures could revise deployment trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Barium Titanate Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Global Inorganic Scintillators Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Fullerene Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Global Semiconductor Gallium Oxide Market