
 Surface Mountable Laser Direct Structuring Antenna (LDS) Market | 2026-2036
Surface Mountable Laser Direct Structuring Antenna (LDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mountable Laser Direct Structuring Antenna (LDS) Market Analytics
Capital-intensity divergence between laser-system owners and pure-play antenna designers is reorganizing competitive tiers in surface mountable LDS supply. LPKF Laser & Electronics leverages its captive laser structuring equipment to dominate high-precision substrate processing. INPAQ Technology Co. Ltd. anchors its position through backward integration into ceramic and polymer substrate manufacturing. TE Connectivity competes across automotive and telecommunications verticals with certified production lines in multiple geographies.
Surface Mountable Laser Direct Structuring Antenna (LDS) refers to three-dimensional conductive traces laser-activated on molded interconnect device (MID) substrates, typically formed on LCP or PBT thermoplastics with copper or silver plating, enabling antenna integration directly onto plastic housing structures. The technology eliminates separate PCB assembly for RF components, reducing device footprint in miniaturized electronics. Embedded Antennas command the largest value pool due to smartphone and wearable penetration, while High-Frequency Antennas represent the fastest-expanding category driven by 5G mmWave and automotive radar applications. Automotive end users are shifting procurement toward conformal designs that integrate radar and V2X antennas into interior trim components.
FCC Part 15 and ETSI EN 301 489 standards govern RF emission compliance for LDS antennas in North America and Europe, while China's MIIT enforces domestic SAR testing protocols that shape product certification timelines. Automotive OEMs now require IATF 16949-aligned production for antenna modules, extending quality system investments across the supplier base. Stakeholders must monitor evolving spectrum allocation decisions for 6-24 GHz automotive radar bands, as these will determine next-generation LDS design rules and substrate material specifications.
Market Dynamics
Automotive OEMs are forcing conformal antenna integration into interior trim components, compressing design cycles and eliminating separate PCB assembly steps entirely. This demand-side pressure is reshaping supplier qualification criteria and substrate material specifications across the value chain.
Growth Catalysts
- 5G mmWave Deployment:Telecommunications infrastructure rollouts require high-frequency LDS antennas for beamforming arrays. Base station manufacturers specify laser-structured substrates for precision RF patterning.
- REACH Compliance Evolution:ECHA substance restrictions on halogenated flame retardants are accelerating qualification of alternative thermoplastic substrates. European automotive suppliers must recertify MID materials by 2027.
- Connected Vehicle Platforms:Radar and V2X module integration into bumper and mirror housings creates dedicated demand streams. Tier-1 automotive electronics suppliers are expanding captive LDS processing capacity.
Market Restraints
- Laser System Capital Intensity:Picosecond and femtosecond laser platforms for high-aspect-ratio structuring require seven-figure equipment investments. Pure-play antenna designers lack balance sheet capacity for captive installation.
- Copper Plating Supply Concentration:Specialty electroless copper chemistry for LDS activation concentrates among German and Japanese chemical suppliers. Geographic concentration creates input cost volatility during currency fluctuations.
- Substrate Material Thermal Limitations:LCP and PBT thermoplastics exhibit dimensional instability above 260°C reflow temperatures. High-temperature automotive underhood applications remain technically inaccessible.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for mobile phone and component production are attracting LDS equipment installation. Domestic substrate molding capacity is scaling in Tamil Nadu and Karnataka clusters.
- Medical Wearable Convergence:Hearing aids and continuous glucose monitors require biocompatible MID substrates with integrated RF. FDA 510(k) pathways for laser-structured polymer devices are clarifying.
- Photovoltaic Microinverter Housing Integration:Solar power electronics manufacturers are specifying LDS antennas for wireless monitoring modules molded directly into enclosure plastics. Distributed generation installations favor this form factor.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:RF-electromagnetic and thermal-mechanical co-simulation for 3D antenna structures requires specialized skill sets. Engineering workforce development lags equipment deployment timelines.
- IATF 16949 Certification Burden:Automotive antenna module suppliers must implement aligned quality systems across multiple production geographies. Audit coordination and documentation requirements extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Mountable Laser Direct Structuring Antenna (LDS) Market |
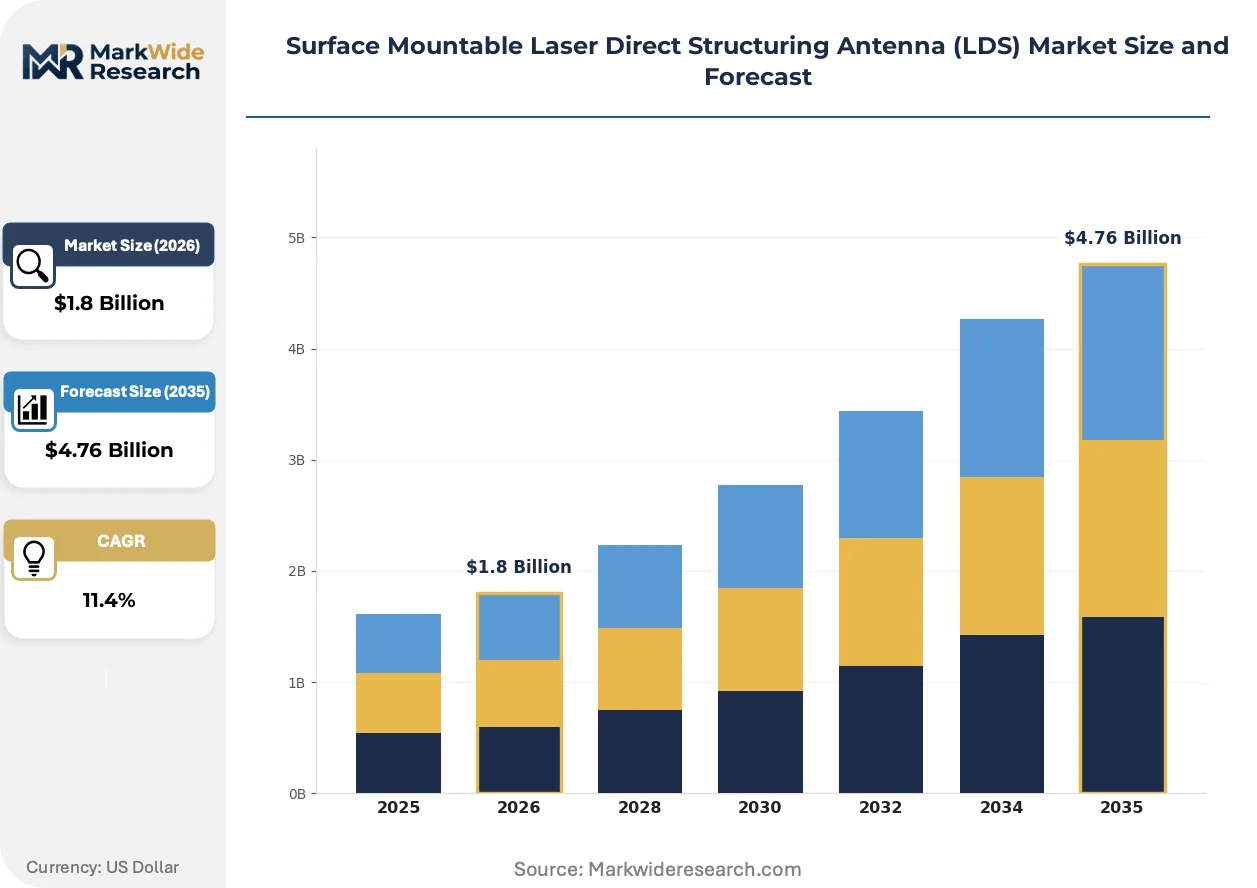
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conformal Antennas, Embedded Antennas, Multi-Layer Antennas, High-Frequency Antennas End User: Telecommunications, Consumer Electronics, Automotive, Medical Devices Technology: Passive Components, Active Components, RF Technology, Microwaves Application: IoT Devices, Wearable Technology, Smart Home, Industrial Automation |
| Companies Covered | Laird Connectivity, INPAQ Technology Co. Ltd., TE Connectivity, Taoglas Limited, Pulse Electronics Corporation, Amphenol Corporation, Tongda Group Holdings Limited, LPKF Laser & Electronics, Molex LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mountable Laser Direct Structuring Antenna (LDS) Market Evolving Landscape
Material science breakthroughs and regulatory harmonization efforts are compressing development timelines while expanding addressable application spaces. Three interconnected developments merit particular attention.
Laser direct structuring on liquid crystal polymer substrates is miniaturizing antenna footprints for smartphone and wearable applications. Consumer electronics OEMs specify sub-millimeter trace widths for 5G sub-6 GHz arrays. This capability is compressing module sizes below discrete component alternatives.
ETSI EN 301 489 emission standards and FCC Part 15 rules are converging on test methodologies for 3D-structured antennas. European and North American certification bodies now accept common RF performance documentation. Automotive radar suppliers in Germany and the United States are consolidating test protocols to accelerate multi-market launches.
Automotive electronics procurement teams are consolidating antenna module sourcing under single-source agreements with full-service MID suppliers. Tier-1 integrators in Stuttgart and Detroit are eliminating multi-vendor assembly steps. This concentration favors suppliers with captive laser structuring, plating, and SMT assembly under one quality system.
Surface Mountable Laser Direct Structuring Antenna (LDS) Market Segmentation
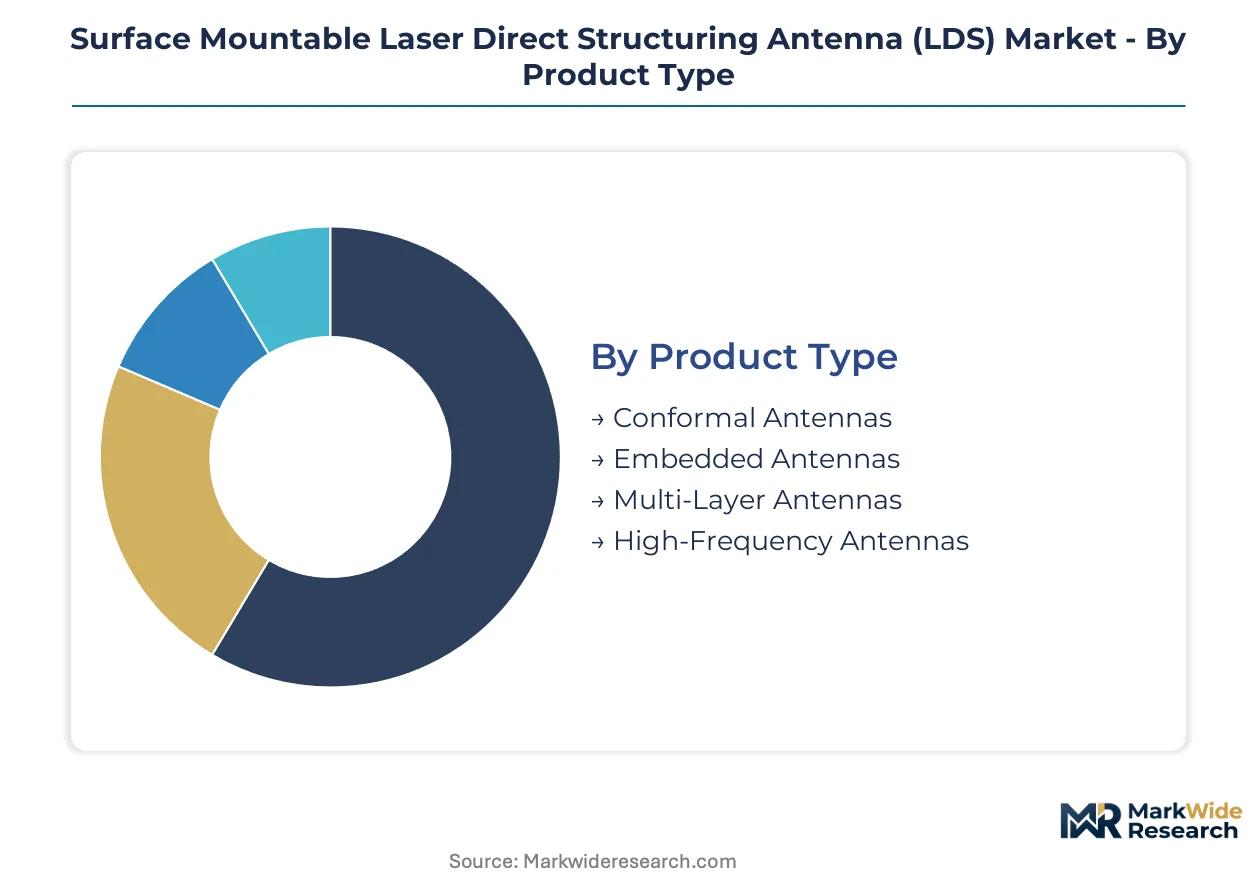
Segmentation in the Surface Mountable Laser Direct Structuring Antenna market reveals how substrate material choices, frequency requirements, and end-use certification burdens fragment both margin capture and supplier qualification pathways. Understanding these divisions exposes where equipment investments and regulatory compliance costs concentrate.
Product Type:
Margin pools concentrate in high-frequency and multi-layer configurations where laser precision requirements and plating chemistry costs elevate pricing power.
- Embedded Antennas:Three-dimensional conductive traces laser-activated directly onto smartphone and wearable housings eliminate separate PCB assembly. Consumer electronics OEMs in South Korea and Taiwan specify sub-millimeter trace widths for 5G sub-6 GHz integration, compressing module sizes below discrete component alternatives.
- High-Frequency Antennas:Precision-structured substrates for mmWave beamforming arrays require picosecond laser platforms and specialized electroless copper activation. Base station manufacturers in Germany and the United States drive qualification timelines for 24-71 GHz automotive radar and telecommunications infrastructure applications.
- Conformal Antennas:Radar and V2X modules integrated into automotive bumper and mirror housings.
- Multi-Layer Antennas:Stacked MID substrates enabling complex RF routing in compact medical device form factors.
The dominant share belongs to Embedded Antennas, while High-Frequency Antennas is closing the gap fastest.
End User:
Procurement patterns diverge sharply between automotive IATF 16949 mandates and consumer electronics volume-scale negotiations.
- Automotive:Conformal radar and V2X integration into interior trim components demands REACH-compliant thermoplastics and aligned quality systems across multiple production geographies. Tier-1 electronics suppliers in Stuttgart and Detroit are consolidating sourcing under single-source agreements with full-service MID suppliers.
- Telecommunications:5G infrastructure rollouts specify laser-structured substrates for base station beamforming arrays. FCC Part 15 and ETSI EN 301 489 convergence on test methodologies is accelerating multi-market launch timelines for equipment vendors.
- Consumer Electronics:Smartphone and wearable penetration drives volume but compresses margins through discrete component competition.
- Medical Devices:Hearing aids and continuous glucose monitors require biocompatible polymer substrates with FDA 510(k) pathway navigation.
Automotive commands premium pricing through certification burdens, though Telecommunications is expanding most quickly through infrastructure deployment cycles.
Technology:
Cost tier separation reflects whether laser structuring serves passive interconnect or active RF amplification functions.
- RF Technology:Integrated matching networks and filtering structures laser-activated directly onto three-dimensional substrates. Telecommunications base station and automotive radar module manufacturers specify these configurations for impedance control without additional assembly steps.
- Microwaves:Millimeter-wave frequency operation demands substrate dielectric stability and trace geometry precision that elevate equipment and chemistry costs. 5G mmWave and automotive radar applications in Japan and Germany drive specification evolution.
- Passive Components:Inductor and capacitor structures embedded in MID substrates for compact IoT device integration.
- Active Components:Amplifier and switch integration requiring thermal management solutions for higher power dissipation.
RF Technology holds the installed base advantage, while Microwaves shows the steepest expansion trajectory.
Application:
Volume concentration varies dramatically between consumer-facing device integration and industrial equipment retrofit cycles.
- IoT Devices:Wireless sensor networks and smart meter modules leverage LDS for antenna integration into compact plastic enclosures. India's PLI scheme incentives for electronics manufacturing are attracting LDS equipment installation in Tamil Nadu and Karnataka clusters.
- Wearable Technology:Continuous health monitoring devices require biocompatible substrates with integrated RF connectivity. FDA 510(k) pathway clarification is reducing commercialization uncertainty for polymer-based medical devices.
- Smart Home:Distributed speaker and security device antennas molded into aesthetic housing components.
- Industrial Automation:Wireless monitoring modules for predictive maintenance in manufacturing environments.
IoT Devices leads current volume, with Wearable Technology gaining share fastest through medical device convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications infrastructure buyers in Germany tolerate premium pricing for certified precision, while Indian smartphone assemblers squeeze margins through volume procurement. This elasticity gap fragments supplier strategies across geographies.
Germany
Automotive radar and 5G base station manufacturers drive demand for REACH-compliant LCP substrates with sub-millimeter trace precision. ECHA substance restrictions on halogenated flame retardants force material recertification by 2027. Stuttgart's Tier-1 electronics cluster concentrates conformal antenna integration for bumper and mirror housings.
China
MIIT enforces domestic SAR testing protocols that compress product certification timelines for smartphone OEMs. SAMR oversight of GB standards shapes substrate material specifications for wearable devices. The Yangtze River Delta dominates manufacturing concentration for picosecond laser structuring equipment and electroless copper chemistry supply.
United States
FCC Part 15 governs RF emission compliance for automotive V2X and telecommunications infrastructure deployments. NHTSA safety mandates accelerate radar module integration into interior trim components. Detroit's automotive electronics procurement teams consolidate sourcing under single-source agreements with full-service MID suppliers.
India
PLI scheme incentives for mobile phone and component production attract LDS equipment installation at scale. TRAI spectrum allocation decisions for 5G sub-6 GHz bands determine antenna design specifications. Tamil Nadu and Karnataka clusters scale domestic substrate molding capacity for IoT device manufacturers.
Japan
METI industrial policy supports millimeter-wave antenna development for automotive radar and telecommunications infrastructure. JIS standards govern substrate dielectric stability for high-frequency applications. Nagoya's automotive electronics corridor integrates LDS antennas into advanced driver-assistance systems.
Surface Mountable Laser Direct Structuring Antenna (LDS) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Laser equipment manufacturers with captive structuring capabilities command premium positioning in high-precision segments, while substrate specialists compete on material cost and molding scale. Three archetypes dominate: integrated equipment-substrate providers, pure-play antenna designers, and full-service MID assemblers. Consolidation through strategic partnerships and geographic expansion represents the primary competitive vector, with secondary emphasis on backward integration into polymer chemistry.
Among equipment-integrated fabricators, LPKF Laser & Electronics and INPAQ Technology Co. Ltd. occupy distinct positions within the technology-tier hierarchy. TE Connectivity exemplifies the diversified industrial conglomerate archetype with certified production footprints spanning multiple geographies. These three anchors illustrate how capital intensity in laser platforms separates competitors into defendable capability tiers rather than direct price competition.
| Leading Market Players |
|---|
| Laird Connectivity |
| INPAQ Technology Co. Ltd. |
| TE Connectivity |
| Taoglas Limited |
| Pulse Electronics Corporation |
| Amphenol Corporation |
| Tongda Group Holdings Limited |
| LPKF Laser & Electronics |
| Molex LLC |
| Others |
Value Network & Pricing Analysis
Picosecond laser platform utilization rates above 80% in Germany and China compress unit processing costs while creating entry barriers for smaller antenna designers. This scale concentration elevates price floors for high-frequency substrates while volume buyers in consumer electronics extract concessions through multi-year offtake commitments.
Pricing Analysis
After-sales service contracts for laser equipment maintenance and plating chemistry replenishment generate 35-45% of lifetime supplier revenue in the LDS antenna market. Three-tier pricing structure across automotive-certified, telecommunications-grade, and consumer electronics economy levels reflects IATF 16949 audit burdens and REACH compliance costs. Pricing pressure stems from smartphone OEM procurement consolidation in Taiwan and South Korea, where volume scale negotiations compress margins on embedded antenna modules. Tier-1 automotive electronics buyers exhibit lowest price sensitivity due to single-source qualification requirements and liability exposure.
Supply Chain Analysis
Germany and Japan anchor specialty electroless copper chemistry production for LDS activation, while China dominates picosecond laser structuring equipment manufacturing. Raw material dependencies include LCP and PBT thermoplastic resins, high-purity copper salts, and rare-earth-doped laser gain media. Single-source vulnerability concentrates in German chemical suppliers for electroless plating baths, creating input cost volatility during euro-yen fluctuations. Distribution runs through full-service MID assemblers with captive laser, plating, and SMT capabilities rather than fragmented component merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as automotive OEMs disaggregate radar and V2X antenna procurement from traditional PCB assembly suppliers, creating dedicated slots for LDS specialists.
For Market Incumbents: Fortify captive laser structuring capacity through equipment fleet expansion in Stuttgart and Detroit automotive corridors. Backward integration into REACH-compliant thermoplastic compounding secures material allocation priority ahead of 2027 ECHA recertification deadlines. Defensive positioning requires blocking emerging Chinese equipment vendors from qualifying with European Tier-1 electronics suppliers through early joint development agreements on next-generation conformal antenna platforms. For New Entrants and Emerging Players: Lead with medical wearable applications where FDA 510(k) pathway clarification reduces regulatory uncertainty and incumbent penetration remains shallow. India's PLI scheme-attracted smartphone assembly clusters in Tamil Nadu offer the most penetrable geography for greenfield LDS equipment installation. Go-to-market execution should emphasize biocompatible polymer substrate expertise to differentiate from established automotive and telecommunications suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors full-service MID assemblers with integrated laser, plating, and SMT capabilities over pure-play antenna designers lacking balance sheet depth for equipment ownership. Long-term viability hinges on 5G mmWave and automotive radar frequency expansion sustaining premium pricing for high-aspect-ratio structuring. Acquisition targets should demonstrate IATF 16949 alignment across multiple geographies. The signal to watch is MIIT spectrum allocation decisions for 6-24 GHz automotive radar bands, which would trigger accelerated capacity deployment among qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH-compliant LCP substrate control secures allocation priority for European automotive qualification cycles. |
| Joint Development with Tier-1 Automotive Electronics | Single-source agreements with Stuttgart and Detroit integrators lock out competing LDS suppliers from platform access. |
| Medical Device FDA 510(k) Pathway Navigation | Biocompatible MID substrate certification opens hearing aid and glucose monitor revenue streams. |
| India PLI Scheme Equipment Installation | Tamil Nadu and Karnataka cluster proximity reduces logistics costs for smartphone OEM volume contracts. |
| Multi-Geography IATF 16949 Certification | Aligned quality systems across Germany, United States, and China accelerate automotive radar module commercialization. |
Research Methodology
Operator-level perspectives from laser equipment engineers, electroless plating chemists, Tier-1 automotive electronics procurement managers, and telecommunications base station RF architects anchored the qualitative base. Primary interviews combined with secondary validation against SEC filings from LPKF Laser & Electronics and TE Connectivity, MIIT SAR testing protocol documentation, and ECHA REACH substance restriction updates. Customs data for LCP resin imports and laser structuring equipment trade flows provided demand-side triangulation. Bottom-up antenna module shipment estimates and top-down OEM procurement budget analysis were cross-referenced for convergence.
Sensitivity analysis examined substrate material cost volatility, laser equipment depreciation schedules, and automotive qualification timeline compression across the projection horizon. Segmentation dimensions modeled include product type, end user vertical, frequency band, and regional regulatory cluster. CAGRs were derived from installed base expansion rates and replacement cycle analysis. Industry-specific forecast inputs incorporated 5G base station deployment schedules and automotive radar content-per-vehicle trajectories.
Forecasts assume regulatory continuity in FCC Part 15, ETSI EN 301 489, and MIIT SAR testing regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include ECHA acceleration of halogenated flame retardant bans, NHTSA V2X mandate timing changes, and currency-driven electroless copper chemistry cost spikes. Recalibration cycles align with material shifts in spectrum allocation decisions and automotive platform electrification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Global Ethernet Controller Market
Electronic Components
Bonding Wires and Ribbons Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Digital Isolator Market
Electronic Components
DVB/SAT Remote Controls Market
Electronic Components
Efuse Market
Electronic Components
Passive Attenuator Market
Electronic Components
Operational Amplifier Market
Electronic Components
Screw Washer Market
Electronic Components
Global Capacitive Stylus Market
Electronic Components
Motherboard Battery Market
Electronic Components
Class D Audio Amplifier Market
Electronic Components
Ceramic Disc Capacitor Market
Electronic Components
China Data Converter Market
Electronic Components
Motherboard Market
Electronic Components
Global Waveguide Components and Assemblies Market