
 Chromium Oxide Market | 2026-2036
Chromium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Chromium Oxide Market Intelligence
The capability gap between large-scale, low-cost producers and suppliers of high-purity specialty grades is unwinding the market's traditional structure. This shift separates producers focused on volume from those pursuing value-added applications. LANXESS leverages its extensive production scale to serve high-volume segments like metallurgy and refractories. In contrast, American Elements specializes in high-purity compounds for advanced electronics and research. Elementis differentiates through its portfolio of specialty pigments and additives for the coatings sector.
Chromium oxide is an inorganic compound with the formula Cr2O3, characterized by its exceptional hardness, thermal stability, and deep green coloration. Its primary industrial purpose is as a pigment in paints, plastics, and ceramics, and as an abrasive for polishing applications. While Cr2O3 Powder and Chromium Oxide Pigments constitute the bulk of production volume, the fastest growth is in refined grades for specialized applications. The ceramics and coatings applications remain the largest end-use segments, commanding significant material consumption for coloration and surface protection.
Regulatory oversight from bodies like the European Chemicals Agency (ECHA) under REACH and the United States Environmental Protection Agency (EPA) heavily influences production. These regulations target the management of hexavalent chromium, a precursor, pushing manufacturers toward safer and more sustainable processes. Consequently, navigating market access depends on compliance with stringent substance registration and environmental standards in key markets like Germany, the United States, and Japan. Stakeholders must decide whether to compete on cost in the commoditized industrial grade or invest in technology for higher-margin cosmetic and reagent grades.
Market Dynamics
The central force shaping the chromium oxide market is the regulatory pressure to mitigate the risks associated with hexavalent chromium, a common precursor. This pressure from bodies like the EPA and ECHA is bifurcating the industry's production logic.
Growth Catalysts
- High-Performance Coatings:Demand from the industrial coatings sector for corrosion resistance and durable coloration in automotive and construction applications provides a consistent volume driver.
- Chinese Industrial Demand:China's expansive manufacturing base, particularly in chemicals, metallurgy, and ceramics, consumes significant quantities of industrial-grade chromium oxide for pigments and refractory materials.
- Advanced Electronics:The growing requirement for high-purity chromium oxide in the manufacturing of semiconductors and electronic components creates a high-value, albeit smaller, market segment.
Market Restraints
- Regulatory Scrutiny:Strict regulations governing hexavalent chromium, such as the EU's REACH directive and EPA standards in the United States, increase compliance costs and operational complexity.
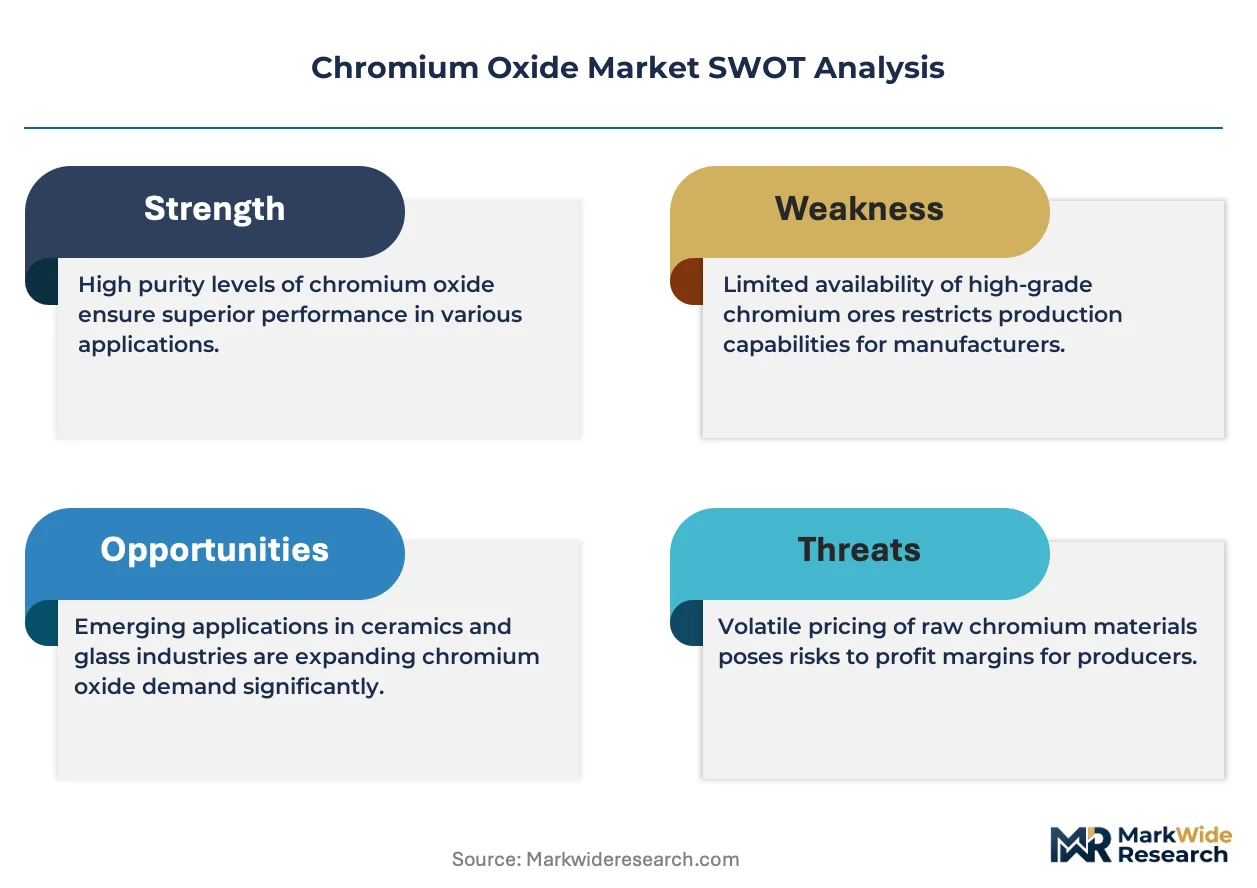
- Raw Material Volatility:The price and availability of chromite ore, the primary raw material, are subject to geopolitical factors and mining disruptions, creating cost instability for producers.
- Substitution in Low-End Applications:In less demanding colorant applications, organic pigments and other inorganic compounds can serve as lower-cost substitutes, capping price ceilings for standard-grade chromium oxide.
Strategic Opportunities
- Green Synthesis Processes:Developing and patenting novel production methods that bypass or minimize the use of hexavalent chromium intermediates offers a significant competitive advantage and regulatory safe harbor.
- Medical and Cosmetic Grades:Untapped potential exists in formulating ultra-high-purity, biocompatible chromium oxide grades for use as pigments in cosmetics and certain medical device coatings.
- Indian Manufacturing Sector:As India's industrial and infrastructure development accelerates under policies like the PLI scheme, demand for pigments, refractories, and coatings will present new growth avenues.
Industry Challenges
- Capital Investment for Compliance:Upgrading or building new production facilities to meet stringent environmental standards for chromium handling and waste disposal requires substantial capital expenditure, creating high barriers to entry.
- Complex Substance Registration:Navigating the detailed and lengthy substance approval processes mandated by regulatory bodies like ECHA can significantly delay market access for new products or producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromium Oxide Market |
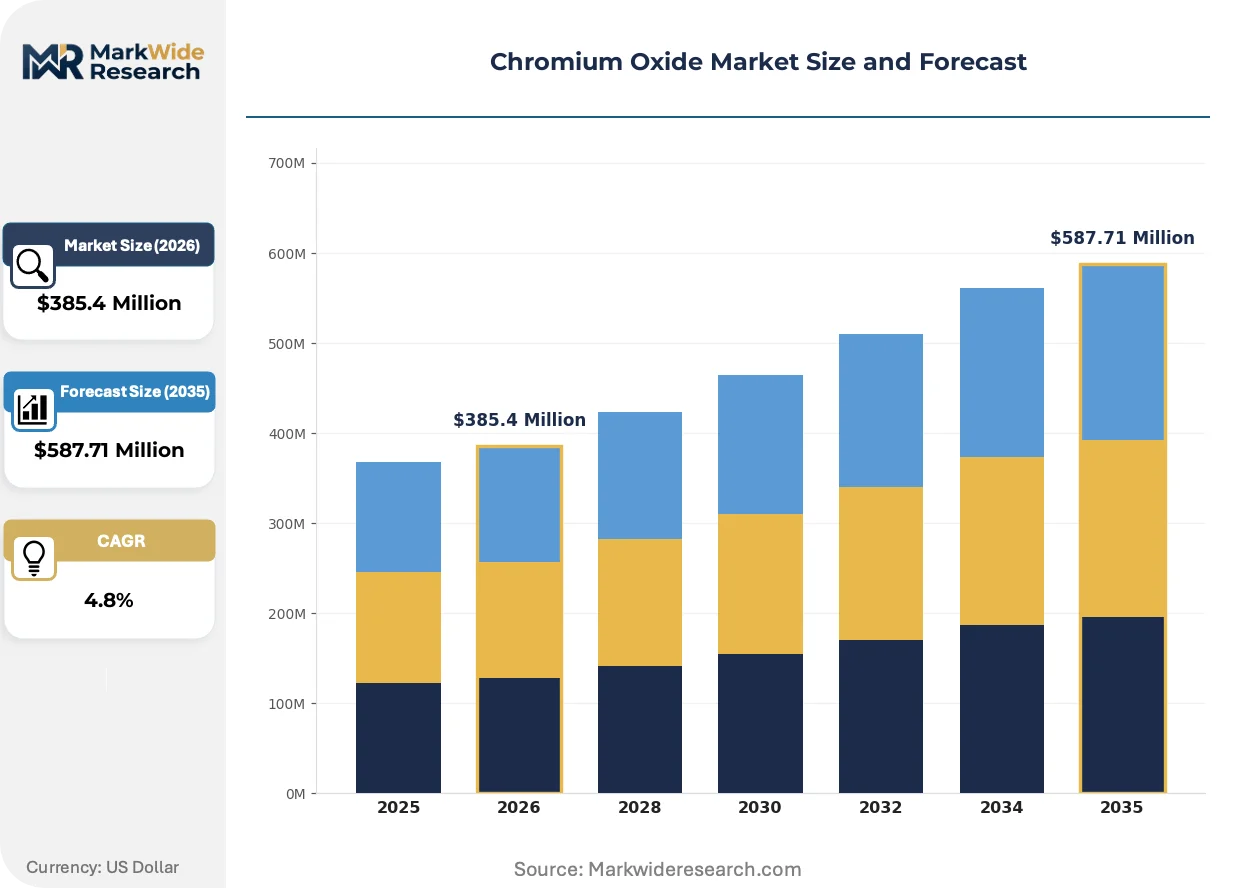
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cr2O3 Powder, Precipitated Chromium Oxide, Chromium Oxide Pigments, Sintered Chromium Oxide, Others Grade: Industrial, Reagent, Cosmetic, Pharmaceutical, Food Grade Application: Ceramics, Coating, Paints, Polishing, Glass Manufacturing, Abrasives End User: Chemical Manufacturers, Glass Producers, Cosmetic Brands, Metal Finishers, Abrasive Suppliers |
| Companies Covered | Venator Materials PLC, Hunter Chemical, LANXESS, Huangshi Zhenhua Chemical, Hebei Chromate Chemical, Elementis, American Elements, Reade International Corp, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromium Oxide Market Strategic Shifts & Innovations
The market's evolution is defined by a divergence between volume-centric industrial grades and value-driven specialty grades. This split is driven by technology enabling new material properties and regulations mandating cleaner production pathways, forcing producers to choose a strategic direction.
Nanoscale chromium oxide is a key material innovation valued for its enhanced catalytic and abrasive properties. The electronics industry is adopting these nanoparticles for chemical mechanical planarization slurries used in semiconductor polishing. This advancement is miniaturizing the particle size required for high-precision surface finishing, creating a distinct market for ultra-fine materials beyond traditional pigment applications.
Regulatory frameworks, particularly the EU Green Deal and its chemical strategy for sustainability, are accelerating the shift toward safer production. This forces manufacturers to re-evaluate processes that use or generate hazardous intermediates, most notably hexavalent chromium. The industrial pigments and metallurgy segments are most affected, facing pressure to invest in alternative synthesis routes or risk losing market access in Europe.
A notable behavioral shift is occurring in how industrial buyers select suppliers, with an emphasis on supply chain transparency. Procurement decisions increasingly incorporate criteria beyond price, favoring producers who can provide documented evidence of sustainable sourcing and compliance with environmental management standards like ISO 14001. This trend is most pronounced among coatings and ceramics manufacturers in North America and Europe.
Chromium Oxide Market Segmentation
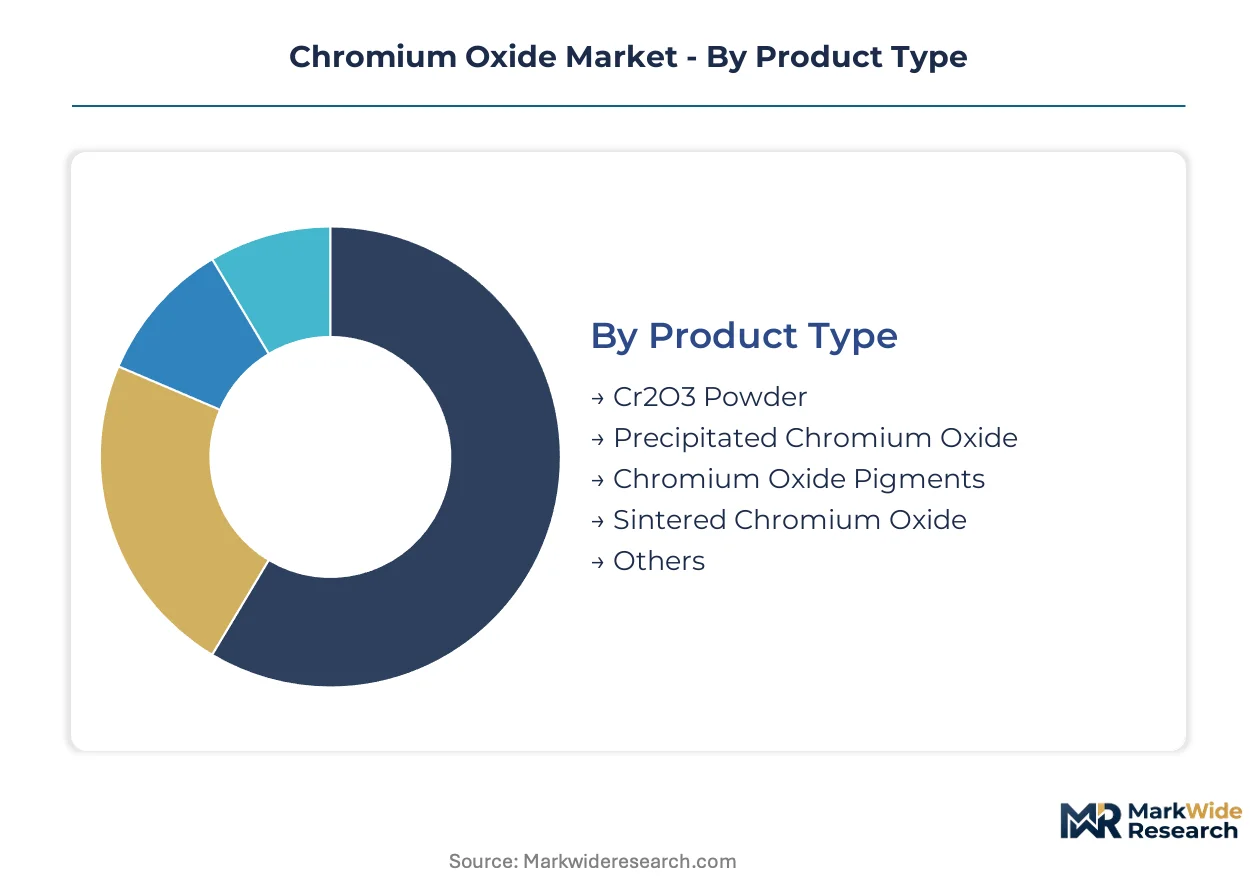
The Chromium Oxide market's segmentation reveals distinct value propositions and demand drivers across its diverse product forms and end-use sectors. Understanding these segments helps stakeholders identify specific growth pockets and tailor product development strategies. This granular view highlights where regulatory pressures and technological advancements are most impactful.
Product Type:
The geographic spread of chromium oxide product types often dictates supply chain logistics, with some forms primarily serving domestic industrial bases while others are export-led for specialized applications.
- Cr2O3 Powder:This fundamental form of chromium oxide is characterized by its fine particle size and high purity, serving as a versatile base material. Demand concentrates in metallurgy and refractory applications within China, where it is used for its heat resistance and chemical stability.
- Chromium Oxide Pigments:These compounds provide exceptional green coloration, UV stability, and chemical inertness for various applications. The coatings and ceramics sectors in Europe drive significant demand for these pigments due to their durability and aesthetic qualities.
- Precipitated Chromium Oxide:This type is produced through a precipitation process, often yielding a finer and more reactive powder suitable for catalyst precursors.
- Sintered Chromium Oxide:Characterized by its high density and enhanced hardness, sintered chromium oxide finds use in specialized abrasive and wear-resistant applications.
- Others:This category encompasses less common or emerging chromium oxide forms tailored for niche applications, including experimental materials.
Cr2O3 Powder holds the largest share; momentum sits with Sintered Chromium Oxide.
Grade:
Different chromium oxide grades command varying price points, reflecting their purity levels, processing complexity, and suitability for high-value applications.
- Industrial:This grade represents the bulk of chromium oxide production, featuring standard purity and cost-effectiveness for large-scale manufacturing processes. Chinese chemical manufacturing and construction sectors are major consumers, utilizing it in pigments and refractory linings.
- Cosmetic:Requiring ultra-high purity and rigorous testing for biocompatibility and trace element control, this grade is specifically formulated for personal care products. European and North American personal care product formulators drive demand for its safe and stable green pigmentation.
- Reagent:Reagent grade chromium oxide meets specific laboratory standards for analytical and research purposes, demanding precise chemical composition.
- Pharmaceutical:This grade adheres to stringent purity and safety standards for potential use in medical device coatings or specialized pharmaceutical formulations.
- Food Grade:Food grade chromium oxide is produced under strict controls to ensure safety for applications requiring contact with food products, though its use is highly regulated.
The Industrial grade remains the volume leader, while the Cosmetic grade is rapidly expanding.
Application:
The volume consumption across chromium oxide applications varies significantly, with some sectors requiring vast quantities for foundational processes and others demanding smaller, specialized volumes.
- Ceramics:Chromium oxide provides heat resistance, vibrant green color, and chemical inertness to ceramic products, enhancing their durability and aesthetic appeal. European and Japanese tile and sanitaryware production consume substantial volumes for coloration and glaze formulation.
- Coating:In coatings, chromium oxide offers superior corrosion protection, weather resistance, and color stability, making it ideal for demanding environments. The automotive and construction industries in Germany and the United States utilize it extensively for high-performance surface protection.
- Paints:Chromium oxide serves as a durable green pigment in various paint formulations, valued for its lightfastness and chemical resistance in architectural and industrial coatings.
- Polishing:Its abrasive properties make chromium oxide an effective polishing agent for precision finishing of metals, ceramics, and optical components.
- Glass Manufacturing:Chromium oxide is incorporated into glass batches to impart green coloration, particularly for architectural glass and specialized optical filters.
- Abrasives:Utilized in abrasive tools and compounds, chromium oxide contributes to the hardness and cutting efficiency required for grinding and lapping operations.
Ceramics applications consume the most material, with Polishing applications seeing accelerated demand.
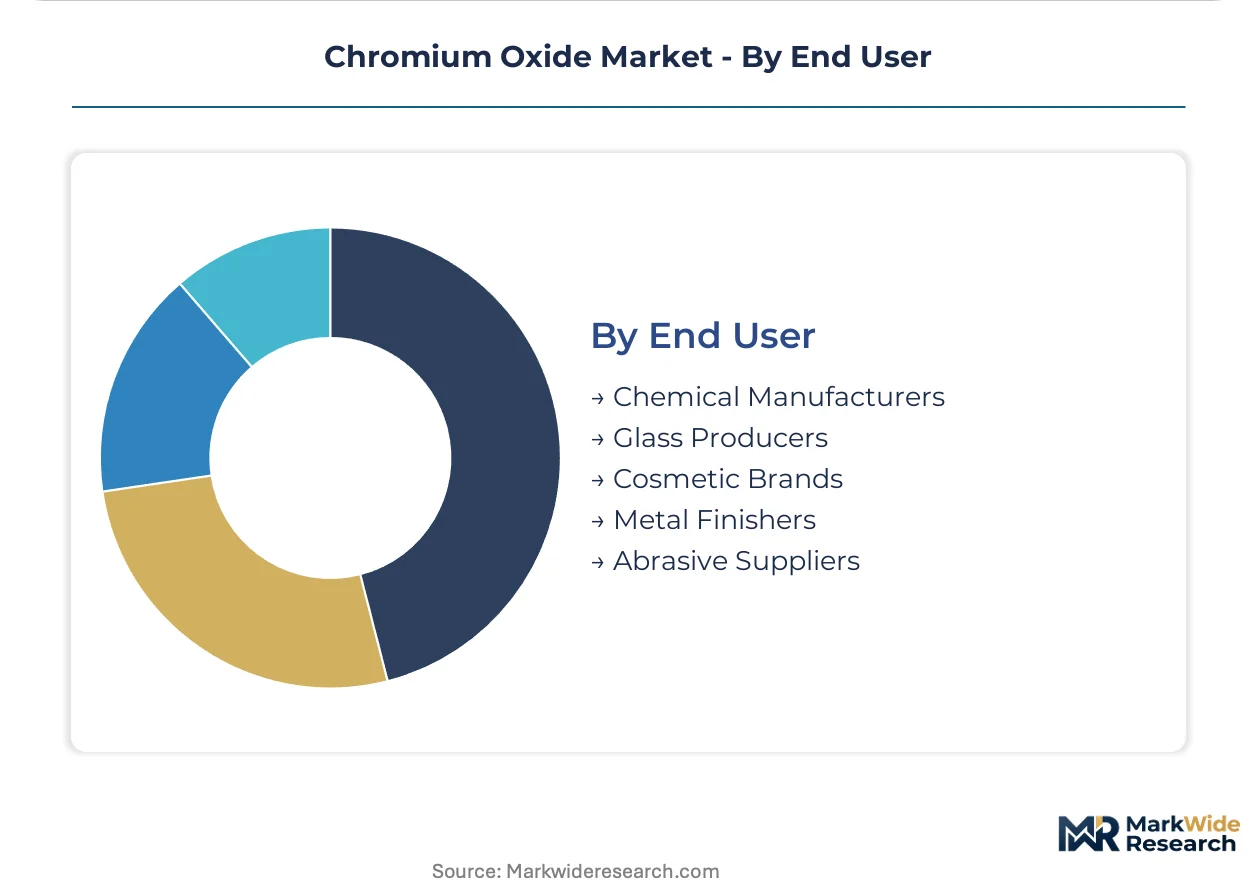
End User:
Chromium oxide end-users represent diverse customer types, ranging from large-scale industrial manufacturers to specialized niche producers with distinct procurement requirements.
- Chemical Manufacturers:These entities utilize chromium oxide as a critical precursor for synthesizing other chromium compounds, including catalysts and specialized chemicals. Integrated chemical complexes in China and India are significant consumers, driving demand for industrial-grade material.
- Cosmetic Brands:Cosmetic brands incorporate high-purity chromium oxide as a safe and stable green pigment in various color cosmetics, including eyeshadows and eyeliners. Premium cosmetic formulators in France and the United States prioritize suppliers meeting stringent regulatory and quality standards.
- Glass Producers:Companies manufacturing glass products use chromium oxide to achieve specific green hues in their output, serving architectural, automotive, and decorative glass markets.
- Metal Finishers:Firms specializing in surface treatment and finishing of metal parts employ chromium oxide for polishing and abrasive applications, enhancing product aesthetics and performance.
- Abrasive Suppliers:These suppliers provide chromium oxide to various industries for use in grinding wheels, polishing compounds, and other abrasive tools due to its exceptional hardness.
Chemical Manufacturers represent the largest consumer base, with Cosmetic Brands showing strong growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry between China and Germany influences global chromium oxide trade dynamics. China's cost-efficient volume production contrasts with Germany's focus on high-purity, value-added grades. This divergence shapes procurement strategies and supply chain resilience across continents.
China
Expansive industrial demand from chemicals, metallurgy, and ceramics drives significant chromium oxide consumption in China. The Ministry of Ecology and Environment (MEE) regulations push manufacturers towards more sustainable production practices. Industrial clusters in the Yangtze River Delta continue to expand, increasing demand for pigments and refractory materials.
Germany
High-performance coatings and specialty ceramics applications underpin robust demand for chromium oxide in Germany. The European Chemicals Agency (ECHA) and REACH directive strictly regulate the production and use of chromium compounds. Automotive and construction sectors in Bavaria and North Rhine-Westphalia prioritize suppliers demonstrating compliance and product quality.
United States
Advanced electronics and high-durability coatings sectors require specialized grades of chromium oxide across the United States. The Environmental Protection Agency (EPA) sets stringent standards for chromium emissions and waste management. Manufacturers in California and Texas are investing in cleaner production technologies to meet evolving regulatory requirements.
Japan
Precision polishing and high-tech ceramics applications generate demand for refined chromium oxide grades in Japan. The Ministry of Economy, Trade and Industry (METI) promotes innovation in materials science, supporting advanced manufacturing. Companies in the Kanto region are developing nanoscale chromium oxide for semiconductor fabrication processes.
India
India's accelerating infrastructure development and chemical manufacturing expansion drive demand for industrial-grade chromium oxide. The Production Linked Incentive (PLI) scheme encourages domestic manufacturing, including pigments and refractories. Chemical complexes in Gujarat and Maharashtra are increasing their capacity to serve the growing domestic market.
Chromium Oxide Market Key Industry Players
Concentration sits with large-scale chemical conglomerates dominating industrial-grade chromium oxide production. The market structure exhibits a tiered approach, with a few global players controlling significant volume and numerous smaller entities specializing in niche, high-purity applications. Strategic archetypes include integrated commodity producers, specialty chemical suppliers, and advanced materials innovators. Capacity expansion and portfolio diversification are dominant competitive moves among market participants.
Within the specialty chemicals sector, LANXESS, a German-based company, represents producers leveraging extensive production scale for high-volume segments. American Elements exemplifies suppliers focused on high-purity compounds for advanced electronics and research. Elementis, a UK-headquartered firm, occupies a position specializing in pigments and additives for the coatings sector.
| Leading Market Players |
|---|
| Venator Materials PLC |
| Hunter Chemical |
| LANXESS |
| Huangshi Zhenhua Chemical |
| Hebei Chromate Chemical |
| Elementis |
| American Elements |
| Reade International Corp |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for industrial-grade chromium oxide lock in predictable supply access and price visibility for large chemical manufacturers. This contrasts with more volatile spot pricing for raw chromite ore, impacting overall market stability.
Pricing Analysis
Configured-to-order pricing for cosmetic and reagent grades commands a significant premium over standard industrial-grade chromium oxide. Price differentiation stems from ultra-high purity requirements and stringent certification levels, such as those for personal care products. Pricing pressure affects industrial grades due to competition from lower-cost substitutes in less demanding applications. Cosmetic brands exhibit lower price sensitivity compared to high-volume chemical manufacturers.
Supply Chain Analysis
Strategic-stockpile preferences are evident among large-scale industrial consumers for critical chromium oxide supplies, balancing against just-in-time practices for specialty grades. Geographic supply concentrates heavily in China for industrial volumes, while raw material sourcing relies on chromite ore from various global mines. Single-source vulnerability for specific high-purity precursors poses a structural risk. Distribution runs through a mix of direct sales channels for major industrial buyers and specialized chemical distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chromium oxide market is undergoing high-growth disruption, driven by the technological inflection of nanoscale materials and stringent regulatory shifts in hexavalent chromium management.
For Market Incumbents:Compound investments in green synthesis processes to mitigate regulatory exposure from hexavalent chromium. Consolidate production capabilities in regions with favorable environmental standards to maintain market access, particularly in Europe. Focus research and development on high-purity applications, leveraging existing scale to counter emerging specialty producers. Capacity additions in India can serve its accelerating industrial demand.
For New Entrants and Emerging Players:Anchor in unmet demand for ultra-high purity grades required by the advanced electronics and medical sectors. Target the underpenetrated cosmetic and pharmaceutical segments with biocompatible chromium oxide formulations. A go-to-market angle emphasizing transparent, sustainable production verified by ISO 14001 certification can differentiate offerings. Focus on niche applications where established players lack specific technical expertise.
For Investors and Strategic Acquirers:Capital is best deployed toward integrated specialty chemical suppliers possessing proprietary green synthesis technologies and strong intellectual property in high-purity chromium oxide. Long-term viability over a 5-10 year window rests on capturing value in advanced applications rather than competing on industrial volume. An acquisition target archetype includes firms with strong R&D capabilities in nanoscale materials. The signal to watch is the increasing market penetration of hexavalent chromium-free production routes.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Supports India's accelerating industrial development and PLI scheme objectives. |
| Green Manufacturing Transition | Addresses ECHA and EPA regulatory pressures regarding hexavalent chromium. |
| Long-term Supply Agreement | Secures stable chromite ore supply amidst raw material volatility. |
| Joint Venture for Nanoscale Materials | Accelerates development of advanced electronics applications in Japan. |
| Certification Investment (ISO 14001) | Enhances supply chain transparency for coatings and ceramics manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with R&D directors, procurement leads, plant managers, and regulatory compliance officers. This primary fieldwork was triangulated with secondary validation from ECHA dossiers, EPA reports, national trade statistics, and company annual reports. Both bottom-up and top-down approaches ensured comprehensive data integration.
Forecasting across the analysis window utilized a robust analytical framework. Segmentation dimensions modeled include product type, grade, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived through regression analysis, informed by expert consensus. Key industry-specific inputs included chromite ore price trends and hexavalent chromium regulation timelines.
Decision-makers should treat outputs as directional under current base assumptions regarding regulatory stability and raw material availability; material deviation would warrant model refresh. Forecasts reflect these assumptions concerning market dynamics and technological progress. Revision becomes warranted when significant geopolitical events impact chromite ore supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Vietnam Semiconductor Materials Market
Semiconductor Material
Semiconductor Fabrication Material Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
Global Semiconductor Microelectronics Materials Market
Semiconductor Material
Electronic-Grade Polysilicon Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Ultra High Purity Silicon Carbide Market
Semiconductor Material
Sapphire Substrate Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Liquid Film Photoresist Market
Semiconductor Material
Synthetic Sapphire Market
Semiconductor Material
Semiconductor Grade Neon Gas Market