
 SDI Camera Market | 2026-2036
SDI Camera Market Size, Share, and Industry Trends Forecast 2026-2036
SDI Camera Market Insights
The migration from copper-based SDI cabling to fiber-integrated 12G-SDI transmission is narrowing the performance gap between traditional broadcast infrastructure and IP-based alternatives. Panasonic leverages its vertical manufacturing scale to control sensor-to-output pipeline costs across professional broadcast tiers. Marshall Electronics anchors its position through compact POV camera designs purpose-built for live sports and house-of-worship installations. PTZ Optics specializes in robotic pan-tilt-zoom SDI units that serve corporate video conferencing and streaming workflows.
Serial Digital Interface cameras transmit uncompressed digital video signals through coaxial or fiber connections using standardized formats from 270 Mbps SD-SDI through 12 Gbps 12G-SDI, with 3G-SDI supporting 1080p at 60 frames per second as the current broadcast baseline. These devices serve professional environments where latency, signal integrity, and color fidelity exceed consumer-grade HDMI or compressed IP alternatives. High Definition product types still generate the majority of unit shipments, though 4K and Ultra High Definition segments are capturing an expanding share of value as production houses upgrade master control rooms. 12G-SDI technology leads in greenfield broadcast installations, while 3G-SDI persists in budget-constrained educational and corporate settings where infrastructure replacement cycles run longer.
The FCC governs equipment authorization and electromagnetic emissions for SDI cameras sold in the United States, while the EU's CE marking and RoHS directives restrict hazardous substances in electronic components and mandate conformity assessment for market access. Japan's METI promotes domestic broadcast technology standards through NHK's 8K Super Hi-Vision roadmap, which extends SDI bandwidth requirements toward 24G-SDI and beyond. Stakeholders must weigh the pace of IP transition against the installed base of SDI routers, monitors, and switchers that still define operational reliability in live production environments.
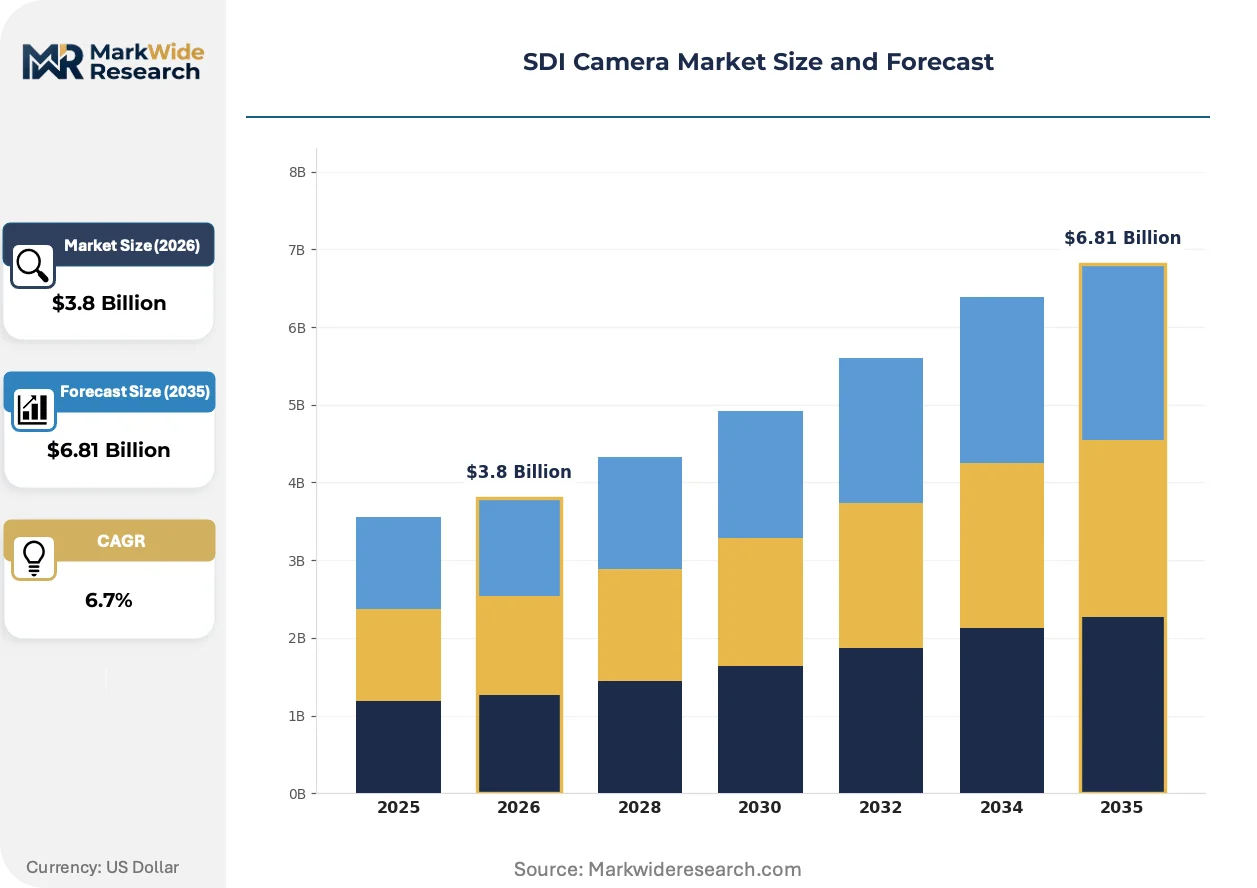
Market Dynamics
The broadcast infrastructure sector faces a forced equipment refresh as 12G-SDI bandwidth requirements collide with FCC spectrum reallocation deadlines and EU Ecodesign mandates under the Green Deal.
Growth Catalysts
- FCC spectrum reallocation:North American broadcasters must vacate C-band frequencies by 2025, compelling studios in Los Angeles and New York to replace aging HD-SDI infrastructure with 12G-SDI capable equipment.
- Live sports production:Premium broadcasters demand uncompressed 4K at 60fps for instant replay systems, driving 12G-SDI adoption in stadium installations across Germany and the United States.
- Fiber-integrated transmission:Hybrid copper-fiber cabling extends SDI reach beyond 100 meters without signal degradation, enabling remote camera positions in large venue productions.
Market Restraints
- Copper commodity volatility:SDI coaxial cable production depends on copper pricing, with mining supply concentrated in Chile and Peru creating input cost instability for cable manufacturers.
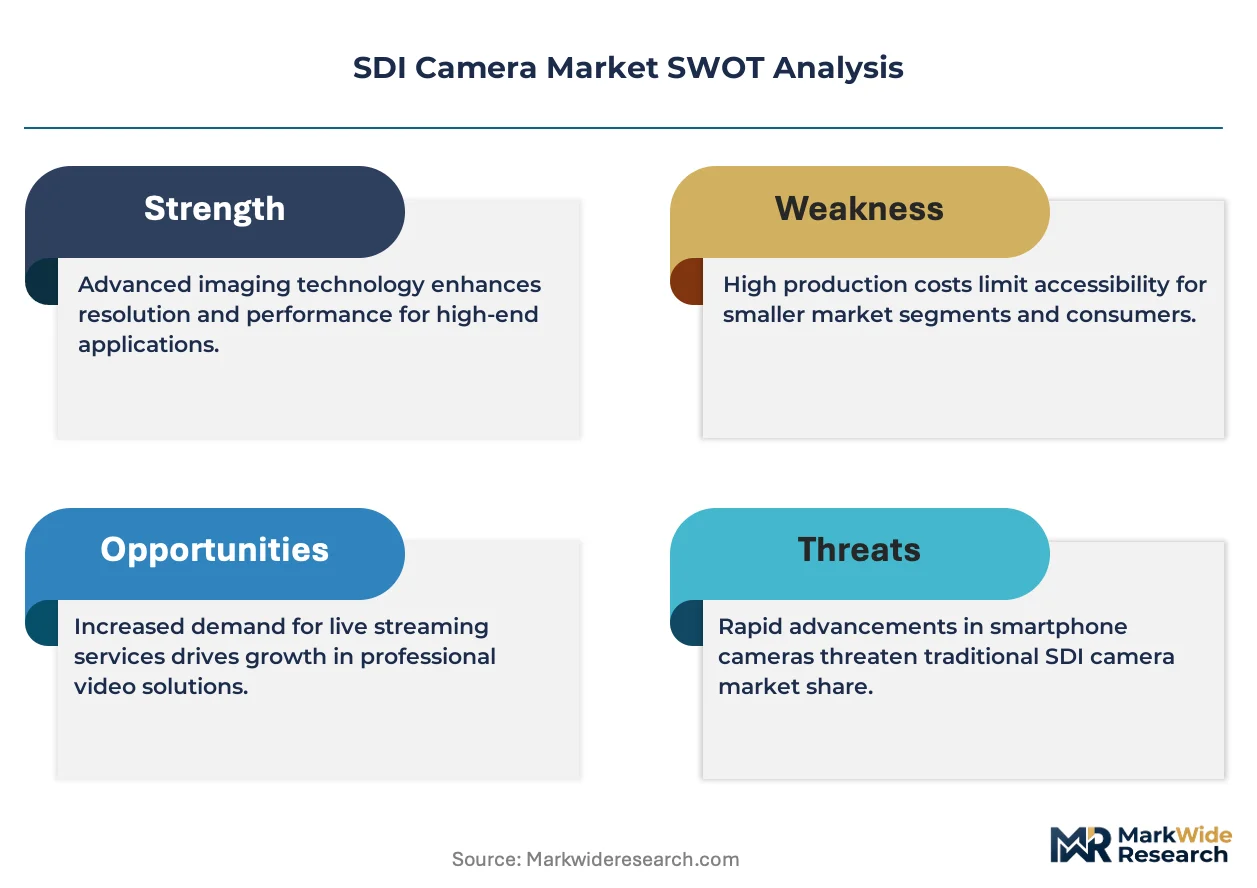
- IP substitution threat:SMPTE ST 2110 uncompressed IP workflows offer software-defined routing flexibility that 12G-SDI hardware cannot match, pressuring greenfield investment decisions.
- Long replacement cycles:Educational institutions and corporate video departments operate 3G-SDI equipment for 10-15 year lifespans, delaying volume upgrades to 4K-capable systems.
Strategic Opportunities
- House-of-worship segment:Religious institutions in the United States are upgrading streaming capabilities, creating demand for compact POV cameras with SDI outputs for multi-camera live production.
- EU Green Deal alignment:Ecodesign requirements for energy-efficient broadcast equipment incentivize replacement of legacy power-hungry HD infrastructure with modern 12G-SDI systems.
- Remote production convergence:Integration of 12G-SDI with bonded cellular transmission enables at-home production models that reduce crew travel for regional sports broadcasts.
Industry Challenges
- 12G-SDI signal integrity:Higher bandwidth coaxial transmission requires precise impedance matching and cable quality control, demanding specialized installation expertise that broadcast engineering departments struggle to source.
- Hybrid workflow complexity:Production facilities must maintain parallel SDI and IP infrastructure during transition periods, doubling monitoring, patching, and troubleshooting overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SDI Camera Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Definition, High Definition, Ultra High Definition, 4K Technology: 3G-SDI, 6G-SDI, 12G-SDI, Quad Link Application: Broadcast, Live Streaming, Film Production, Video Conferencing End User: Media Houses, Event Organizers, Corporate Entities, Educational Institutions |
| Companies Covered | SECU-VISION, Marshall Electronics, Panasonic, Active Silicon, PTZ Optics, Imperx, KT&C, Soncci, ARTRAY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SDI Camera Market Trends and Innovations
Broadcast camera technology is pivoting toward bandwidth consolidation as single-cable 12G-SDI replaces multi-link 3G-SDI configurations, while regulatory pressure accelerates hardware replacement timelines beyond traditional depreciation schedules.
12G-SDI transmission is migrating from copper coaxial cabling to fiber-optic integration for distances exceeding 100 meters. Sports stadiums and large entertainment venues in the United States are adopting hybrid fiber-SDI cameras to position remote units at field level and concourse positions. This migration from copper-dominant infrastructure is compressing the installed base of legacy 3G-SDI routers and forcing synchronous upgrades across camera, routing, and monitoring subsystems.
The EU Ecodesign requirements under the Green Deal mandate standby power limits and energy efficiency labels for professional broadcast equipment. Manufacturers must redesign power supplies and thermal management systems to achieve CE marking compliance. Studio camera systems sold into Germany, France, and the Netherlands face the most stringent enforcement, with national market surveillance authorities conducting port-of-entry inspections.
Rental and lease-to-own procurement models are displacing outright capital purchase for broadcast camera fleets. Regional sports networks and independent production houses in the United Kingdom favor operational expenditure structures that preserve balance sheet flexibility. This shift concentrates fleet ownership with specialized broadcast equipment lessors who negotiate volume purchasing agreements directly with manufacturers.
SDI Camera Market Segmentation
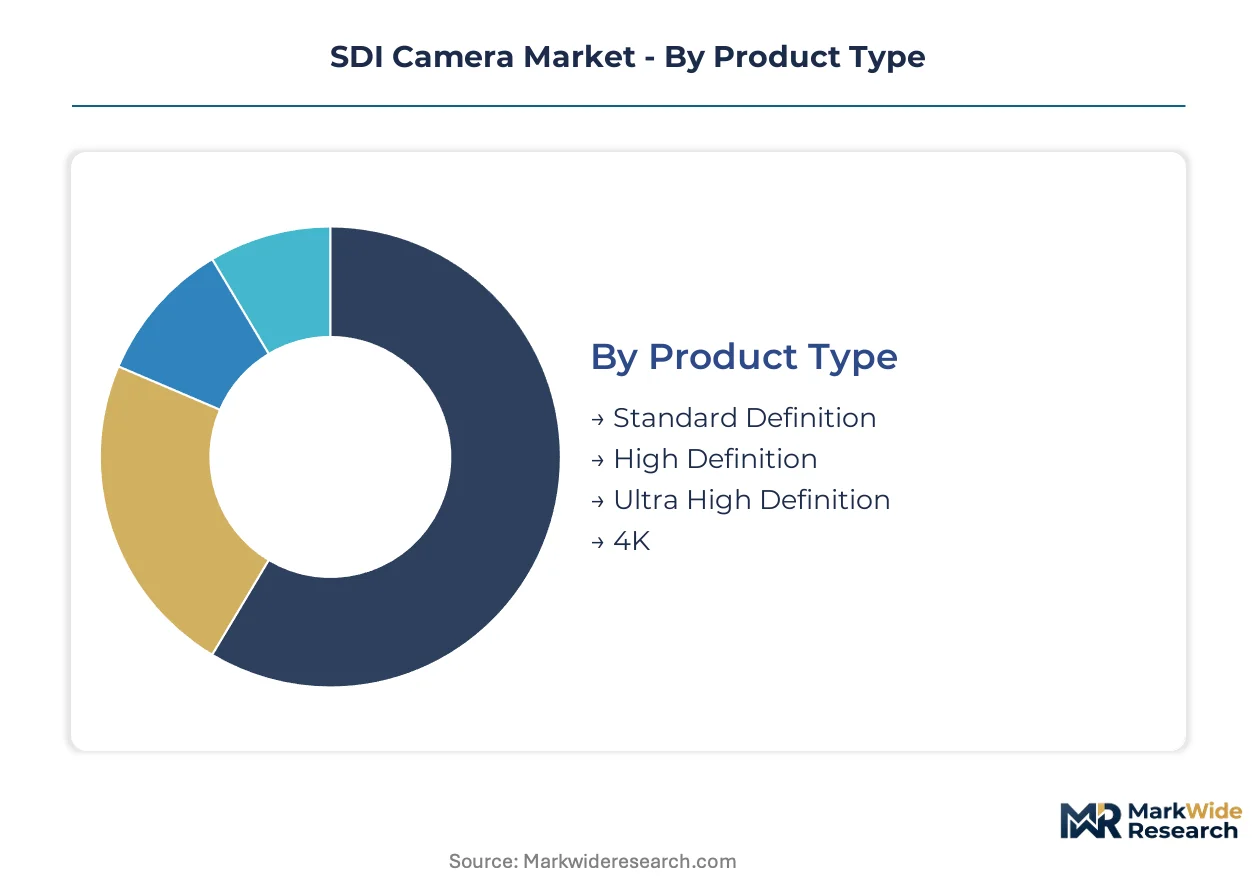
SDI camera procurement patterns diverge sharply across resolution tiers, bandwidth standards, and operational environments. Understanding these fault lines reveals where infrastructure investment concentrates and where legacy equipment persists.
Product Type:
Resolution tiers segment the market by production pipeline requirements and infrastructure replacement cycles.
- High Definition:1080p formats at 60 frames per second remain the broadcast baseline, dominating live news workflows in London and Mumbai where 3G-SDI infrastructure depreciation cycles extend past twelve years. HD commands volume shipments but faces compression from 4K upgrade mandates in premium sports production.
- 4K:Uncompressed 2160p output through single-cable 12G-SDI is displacing Quad Link configurations in greenfield broadcast installations across Los Angeles and New York. Stadium camera positions in Germany and the United States specify 4K for instant replay systems.
- Ultra High Definition:8K-ready sensors with 12G-SDI output serve experimental production pipelines and future-proofed master control investments.
- Standard Definition:480i/576i legacy formats persist in budget-constrained security and monitoring applications with minimal resolution requirements.
High Definition commands the established base. The steepest expansion runs through 4K.
Technology:
Bandwidth specifications determine signal integrity, cable reach, and backward compatibility with installed router infrastructure.
- 12G-SDI:Single-cable 12 Gbps transmission handles uncompressed 4K at 60fps, eliminating multi-link complexity in new broadcast builds across Germany and the United States. FCC spectrum reallocation deadlines in North America accelerate 12G-SDI router and camera procurement ahead of traditional replacement schedules.
- 3G-SDI:2.97 Gbps bandwidth supports 1080p workflows and dominates educational institutions and corporate video departments where capital budgets refresh every ten to fifteen years. Copper coaxial infrastructure for 3G-SDI remains serviceable without fiber conversion costs.
- 6G-SDI:Intermediate bandwidth tier bridges 3G-SDI legacy and 12G-SDI requirements for 4K at 30fps applications.
- Quad Link:Four-channel 3G-SDI bonding enables 4K transmission over existing copper infrastructure, persisting in rental fleets and staged upgrade scenarios.
3G-SDI anchors installed capacity. 12G-SDI is climbing the fastest as broadcasters confront bandwidth and regulatory deadlines simultaneously.
Application:
Operational use cases dictate latency tolerance, mobility requirements, and integration with production switchers.
- Broadcast:National networks and regional affiliates in the United States, United Kingdom, and India require frame-accurate genlock synchronization and tally integration for multi-camera live production. 12G-SDI dominates new studio builds while hybrid SDI-IP workflows manage transition complexity.
- Live Streaming:Houses of worship and regional sports networks demand compact POV cameras with SDI output for multi-camera streaming setups. Bonded cellular backhaul from 12G-SDI camera positions enables at-home production models reducing crew travel.
- Film Production:Cinema camera operators favor SDI for uncompressed monitoring on set, though RAW recording workflows increasingly bypass SDI for direct storage.
- Video Conferencing:Corporate and government installations specify PTZ cameras with 3G-SDI output for integration with legacy AV infrastructure in council chambers and boardrooms.
Broadcast retains volume concentration. Live Streaming is gaining share fastest as streaming infrastructure investment outpaces traditional broadcast capital expenditure.
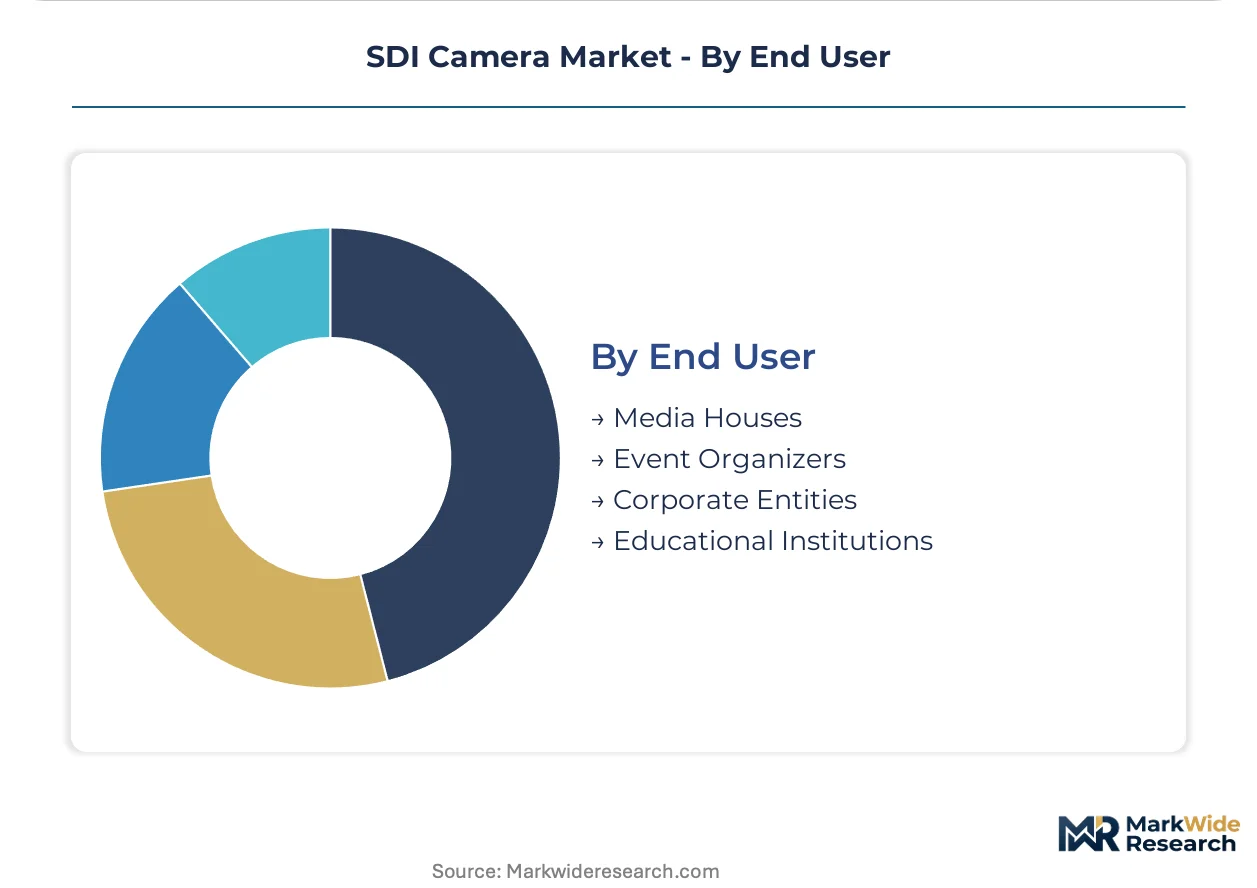
End User:
Customer type determines procurement modality, replacement urgency, and sensitivity to operational expenditure structures.
- Media Houses:Broadcast networks and production companies in Los Angeles, London, and Mumbai face FCC and EU Ecodesign mandates compressing depreciation schedules. Rental and lease-to-own procurement is displacing outright purchase to preserve balance sheet flexibility.
- Corporate Entities:Enterprise video departments in the United States upgrade streaming capabilities for internal communications and investor relations, favoring compact SDI cameras with HDMI bridging for mixed infrastructure.
- Event Organizers:Rental-dependent producers serving touring productions and corporate events prioritize camera fleet interoperability across 3G-SDI and 12G-SDI client specifications.
- Educational Institutions:Universities and K-12 districts operate extended replacement cycles, maintaining 3G-SDI equipment for student training and internal broadcast where 4K offers marginal pedagogical value.
Media Houses drive premium segment value. Corporate Entities represent the most rapid procurement expansion as streaming investment accelerates outside traditional broadcast.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export 12G-SDI broadcast equipment to production hubs in the United States and India, while Japanese component suppliers feed sensor modules into camera assembly lines across Asia-Pacific.
United States
FCC spectrum reallocation deadlines compel Los Angeles and New York broadcasters to replace HD-SDI infrastructure before 2025. The FCC governs equipment authorization and electromagnetic emissions for all SDI cameras sold domestically. Stadium camera deployments in Texas and Florida specify 12G-SDI for instant replay systems in professional sports venues.
Germany
EU Ecodesign requirements under the Green Deal accelerate replacement of power-hungry legacy broadcast equipment in Berlin and Munich studios. CE marking and RoHS directives restrict hazardous substances in electronic components and mandate conformity assessment. North Rhine-Westphalia hosts broadcast technology clusters serving RTL Group and ProSiebenSat.1 production facilities.
India
TRAI broadcast infrastructure guidelines support studio modernization in Mumbai and Delhi as streaming platforms expand original content production. The Central Electricity Authority enforces standby power regulations for professional equipment imports. Media city developments in Hyderabad and Bengaluru concentrate multi-camera live production demand for regional language programming.
Japan
METI promotes domestic broadcast technology standards through NHK's 8K Super Hi-Vision roadmap, extending SDI bandwidth requirements toward 24G-SDI. JIS standards govern professional video equipment interoperability. Nagoya and Osaka manufacturing corridors supply precision optical components for broadcast camera modules.
United Kingdom
Regional sports networks and independent production houses in London favor rental and lease-to-own procurement models that preserve balance sheet flexibility. Ofcom broadcast licensing frameworks influence equipment refresh cycles for BBC and ITV facilities. Manchester and Birmingham post-production clusters drive demand for 4K-capable SDI monitoring infrastructure.
SDI Camera Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with broadcast divisions, compact camera specialists serving niche installation verticals, and component-integrated module suppliers. Consolidation pressure runs through technology licensing agreements and strategic partnerships as 12G-SDI standardization eliminates proprietary differentiation.
Among diversified electronics manufacturers, Panasonic occupies a position exemplifying vertical manufacturing scale across professional broadcast tiers. Marshall Electronics represents the compact POV camera specialist archetype purpose-built for live sports and house-of-worship installations. PTZ Optics anchors the robotic pan-tilt-zoom segment serving corporate video conferencing and streaming workflows.
| Leading Market Players |
|---|
| SECU-VISION |
| Marshall Electronics |
| Panasonic |
| Active Silicon |
| PTZ Optics |
| Imperx |
| KT&C |
| Soncci |
| ARTRAY |
| Others |
Pricing and Supply Chain Analysis
Nagoya and Osaka manufacturing corridors supply precision optical components that feed camera module assembly across Japan, China, and South Korea, concentrating upstream pricing power with sensor and lens suppliers while downstream broadcast equipment vendors compete on integration efficiency and service bundling.
Pricing Analysis
The 12G-SDI to 3G-SDI pricing gap spans roughly three-to-one for comparable camera bodies, with 4K-capable units commanding premiums over HD baselines and 8K-ready sensors occupying a thin premium tier. Three-tier pricing structure across premium broadcast, standard corporate, and economy education levels reflects certification grade differentiation and volume scale. Cost compression in the HD tier is intensifying because copper commodity volatility and extended replacement cycles in institutional buyers compress margins. Educational institutions exhibit highest price sensitivity due to decade-long depreciation schedules, while national broadcast networks in Los Angeles and London prioritize signal integrity over unit cost.
Supply Chain Analysis
Hon Hai Precision Industry and Jabil Electronics hold contract manufacturing capacity for broadcast camera assembly, with additional foundry concentration in Taiwan and South Korea for image sensor fabrication. Camera production draws from copper coaxial cabling, precision optical glass, and broadcast-grade FPGA processors as core inputs. Single-source vulnerability concentrates in high-bandwidth SerDes chipsets from limited qualified suppliers. Distribution runs through specialized broadcast equipment lessors who negotiate volume purchasing agreements directly with manufacturers, displacing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SDI camera incumbents face a substitution defense against SMPTE ST 2110 uncompressed IP workflows that threaten hardware-centric business models with software-defined routing flexibility.
For Market Incumbents: Build switching cost moats through 12G-SDI router and monitor ecosystem bundling that raises replacement barriers for installed broadcast facilities. Panasonic leverages captive sensor production to compress bill-of-materials costs and defend margin position against modular competitors. Incumbents should deepen backward integration into fiber-optic transmission modules to capture hybrid copper-fiber upgrade cycles.
For New Entrants and Emerging Players: Pursue house-of-worship and regional sports network segments where streaming infrastructure investment outpaces traditional broadcast capital expenditure and procurement favors operational expenditure structures. The United States religious institution vertical presents penetrable white space with limited incumbent specialization. A lease-to-own go-to-market angle aligns with balance sheet flexibility priorities among independent production houses.
For Investors and Strategic Acquirers: Long-term, this sits as a transition-arbitrage play because the IP migration timeline remains uncertain and SDI infrastructure retains operational reliability premiums in live production environments. Acquisition targets should display component-integrated module capabilities or specialized vertical positioning in compact POV or robotic PTZ segments. The signal to watch is bonded cellular backhaul adoption rates in regional sports broadcasts as an indicator of at-home production model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| 12G-SDI Product Launch | Single-cable 4K transmission eliminates multi-link complexity in FCC-mandated infrastructure refreshes. |
| Fiber-Optic Integration Partnership | Hybrid copper-fiber cabling extends camera positioning range beyond 100 meters in stadium installations. |
| EU Ecodesign Compliance Program | CE marking alignment unlocks German and French studio procurement under Green Deal mandates. |
| Lease-to-Own Fleet Model | Operational expenditure structures attract UK independent production houses preserving balance sheet flexibility. |
| House-of-Worship Vertical Expansion | Compact POV camera demand accelerates as US religious institutions upgrade multi-camera streaming capabilities. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with broadcast engineering directors, procurement leads at regional sports networks, house-of-worship technical directors, and broadcast equipment lessors; and secondary validation through FCC equipment authorization filings, EU Ecodesign compliance registries, TRAI infrastructure guidelines, and customs trade records for broadcast camera imports. Bottom-up unit shipment estimates triangulated against top-down infrastructure replacement cycle analysis across the analysis window.
Forecast inputs incorporated resolution tier migration curves, bandwidth standard adoption rates, and regional regulatory deadline clustering. Segmentation modeling spanned product type, technology generation, application environment, and end-user procurement modality. CAGRs derived from slope analysis of replacement cycle compression against greenfield installation growth across the projection horizon. Industry-specific inputs included copper commodity price trajectories and bonded cellular backhaul penetration rates.
Sensitivities concentrate around FCC spectrum reallocation timeline adjustments, EU Green Deal enforcement variance across member states, and IP substitution acceleration in premium broadcast segments. Forecasts reflect documented assumptions regarding infrastructure depreciation schedules and regulatory compliance cost pass-through. Quarterly review of 12G-SDI router procurement volumes and regional sports network at-home production adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Industrial Machine Vision Market
Imaging
Camera Technology Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Europe CT Market
Imaging
Global Microscopy Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Global Trail Camera Market
Imaging
PET Scanners Market
Imaging
X-Ray Market
Imaging
Holographic Imaging Market
Imaging
Global Digital Photo Frame Market
Imaging
Video Microscopes Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Global Mobile Image Sensor Market
Imaging
Photo Kiosk Market
Imaging
Machine Vision System and Services Market