
 Global Strontium Market | 2026-2036
Global Strontium Market Size, Share, and Industry Trends Forecast 2026-2036
Global Strontium Market Foresight
Long-term supply contracts for strontium carbonate is rebalancing how producers capture value across the value chain. Solvay S.A. leverages its integrated rare earths platform to secure feedstock priority in European markets. Tateho Chemical Industries Co., Ltd. anchors Japanese supply through captive magnesite-strontium co-production. Hebei Xinji Chemical Group Co., Ltd. dominates volume output from its Shandong processing complex.
Strontium is an alkaline earth metal with atomic number 38, occurring naturally as celestite (strontium sulfate) and strontianite (strontium carbonate), with commercial grades requiring 98.5% purity for pyrotechnic and ceramic applications. Its primary industrial purpose centers on flame coloration, ferrite magnet production, and glass modification for cathode-ray and specialty optical applications. Strontium carbonate leads product-type revenue due to ferrite magnet binder demand, while strontium nitrate in fireworks applications shows the fastest volume trajectory. Electronics manufacturing as an end-user industry commands premium pricing through high-purity specifications, whereas construction materials remains a mature, price-sensitive outlet.
China's MEE enforces wastewater discharge limits on strontium refining that elevate compliance costs for sulfate-to-carbonate conversion. REACH in Europe mandates registration and hazard communication for strontium compounds imported above one-tonne thresholds. Stakeholders must monitor how China's GB standards evolution and the EU Green Deal's critical raw materials list reshape supply qualification requirements and regional sourcing strategies.
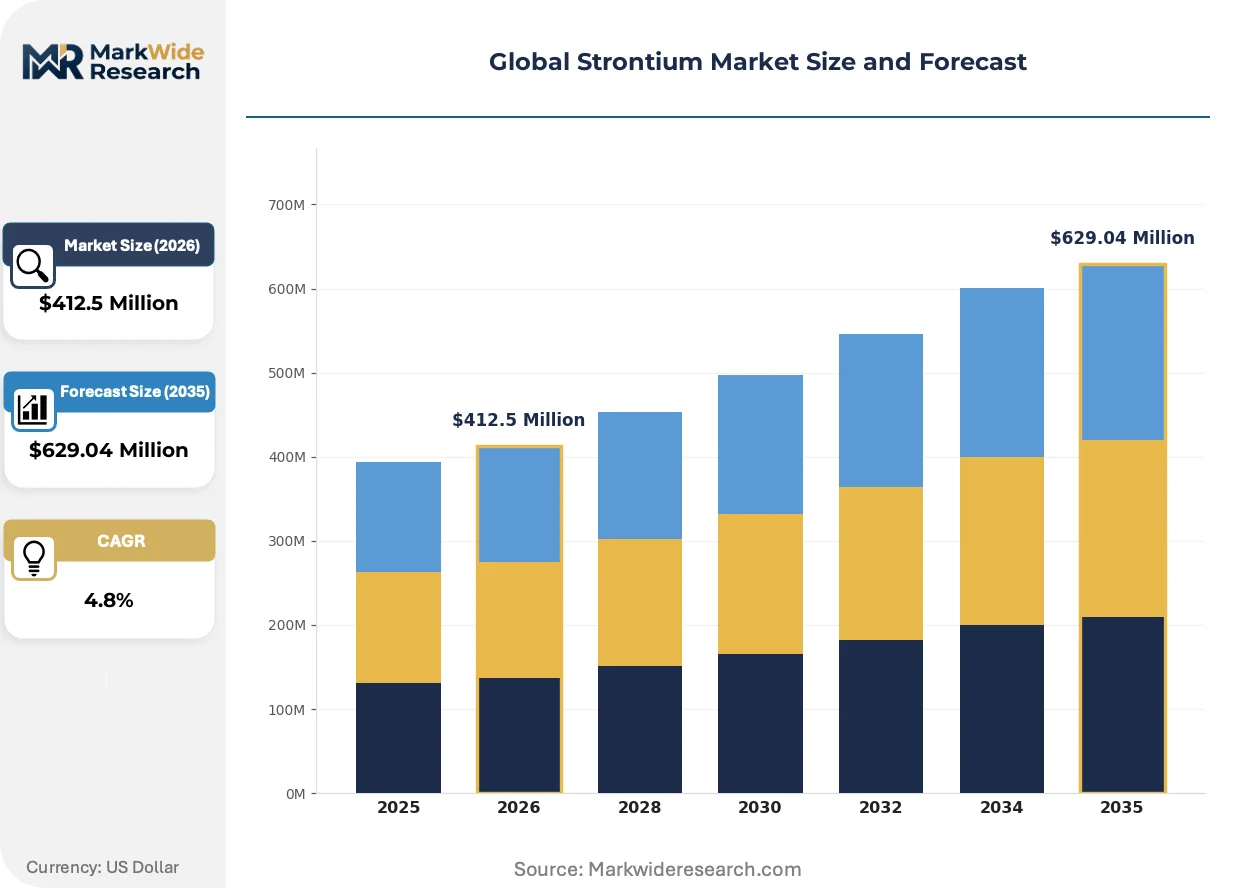
Market Dynamics
China's dual carbon goals are compressing sulfate-to-carbonate conversion capacity while pyrotechnic demand in Asia-Pacific pulls strontium nitrate volumes upward, creating a structural tension between emission compliance and raw material throughput.
Growth Catalysts
- Ferrite magnet binder demand:Strontium carbonate serves as the primary grain-growth inhibitor in sintered ferrite production for automotive sensors and consumer electronics, with magnet manufacturers in Japan and South Korea expanding offtake commitments.
- MEE wastewater discharge limits:China's Ministry of Ecology and Environment enforcement is paradoxically consolidating compliant capacity, rewarding refiners with advanced effluent systems and locking in supply relationships with certified buyers.
- Pyrotechnic flame coloration:Strontium nitrate delivers the specific 620-750 nanometer red emission required for professional fireworks displays, with display companies in Germany and the United States substituting barium alternatives for strontium in premium formulations.
Market Restraints
- Celestite ore concentration:Mineable strontium sulfate deposits cluster in Sichuan and Qinghai provinces, exposing processors to single-region logistics disruptions and provincial environmental shutdowns.
- Carbonate-to-hydroxide conversion cost:High-temperature calcination of strontianite requires metallurgical-grade coke inputs that track volatile coking coal indices, compressing margins for non-integrated refiners.
- Calcium-strontium substitution in glass:Specialty optical manufacturers in Schott AG's supply chain are qualifying calcium-barium formulations for cathode-ray tube faceplates, threatening long-term carbonate offtake.
Strategic Opportunities
- India's PLI scheme for magnets:Production-linked incentives for rare earth permanent magnet manufacturing are attracting ferrite precursor investments in Tamil Nadu and Gujarat, creating import substitution demand for carbonate feedstock.
- EU Green Deal critical raw materials list:Strontium's inclusion is triggering strategic stockpiling mandates and offtake guarantees for domestic magnet recyclers and ceramic additive producers.
- Battery electrolyte additive convergence:Strontium titanate and related perovskite structures are emerging as solid-state electrolyte interface stabilizers, with South Korean battery researchers filing patent applications at accelerating rates.
Industry Challenges
- RoHS compliance certification timelines:Electronics manufacturers require third-party verification of strontium compound purity thresholds below 100 ppm barium contamination, with testing backlogs at accredited laboratories extending qualification cycles.
- Sulfate process legacy asset stranding:European carbonate producers face retrofit costs for direct conversion furnaces to meet REACH SVHC documentation requirements, with engineering procurement construction contracts delayed by specialized refractory sourcing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Strontium Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strontium Carbonate, Strontium Nitrate, Strontium Chloride, Strontium Hydroxide, Strontium Sulfate Application: Fireworks, Ceramics, Glass Manufacturing, Electronics, Radiology End User Industry: Chemicals, Electronics Manufacturing, Construction Materials, Medical Devices, Automotive Components Form: Powder, Granules, Pellets, Solution |
| Companies Covered | Alfa Aesar, Noah Technologies Corporation, Solvay S.A., Tateho Chemical Industries Co., Ltd., ProChem, Inc., Sakai Chemical Industry Co., Ltd., Merck KGaA, Hebei Xinji Chemical Group Co., Ltd., American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Strontium Market Shifts & Advancements
Process intensification in strontium refining and downstream formulation chemistry are compressing cost curves while regulatory hazard communication mandates reshape qualification protocols across electronics and pyrotechnic supply chains.
High-purity strontium carbonate synthesized via hydrometallurgical precipitation is expanding into thin-film deposition applications for piezoelectric sensors. MEMS manufacturers in Germany and Japan are qualifying sub-micron grades for acoustic filter substrates, displacing conventionally calcined material in frequency-control devices. This purity tier is expanding into medical imaging scintillator arrays where barium elimination below 50 ppm is non-negotiable.
REACH Annex XVII restrictions on strontium chromate pigments are forcing reformulation across European aerospace coating supply chains. ECHA's sunset date enforcement is accelerating substitution toward strontium molybdate and phosphate corrosion inhibitors, with Tier-1 suppliers in Toulouse and Hamburg requalifying primer systems ahead of 2026 authorization deadlines. The regulatory pressure is concentrating purchasing power among registrants with full substance dossiers.
Magnet procurement contracts are compressing from annual to quarterly price reviews with pass-through clauses for celestite ore indices. Tier-1 automotive sensor manufacturers in Detroit and Stuttgart are unbundling ferrite core supply from magnet assembly, forcing carbonate refiners to assume inventory risk previously held by Japanese trading houses. This disintermediation is most visible in just-in-time delivery mandates from South Korean motor suppliers.
Global Strontium Market Segmentation
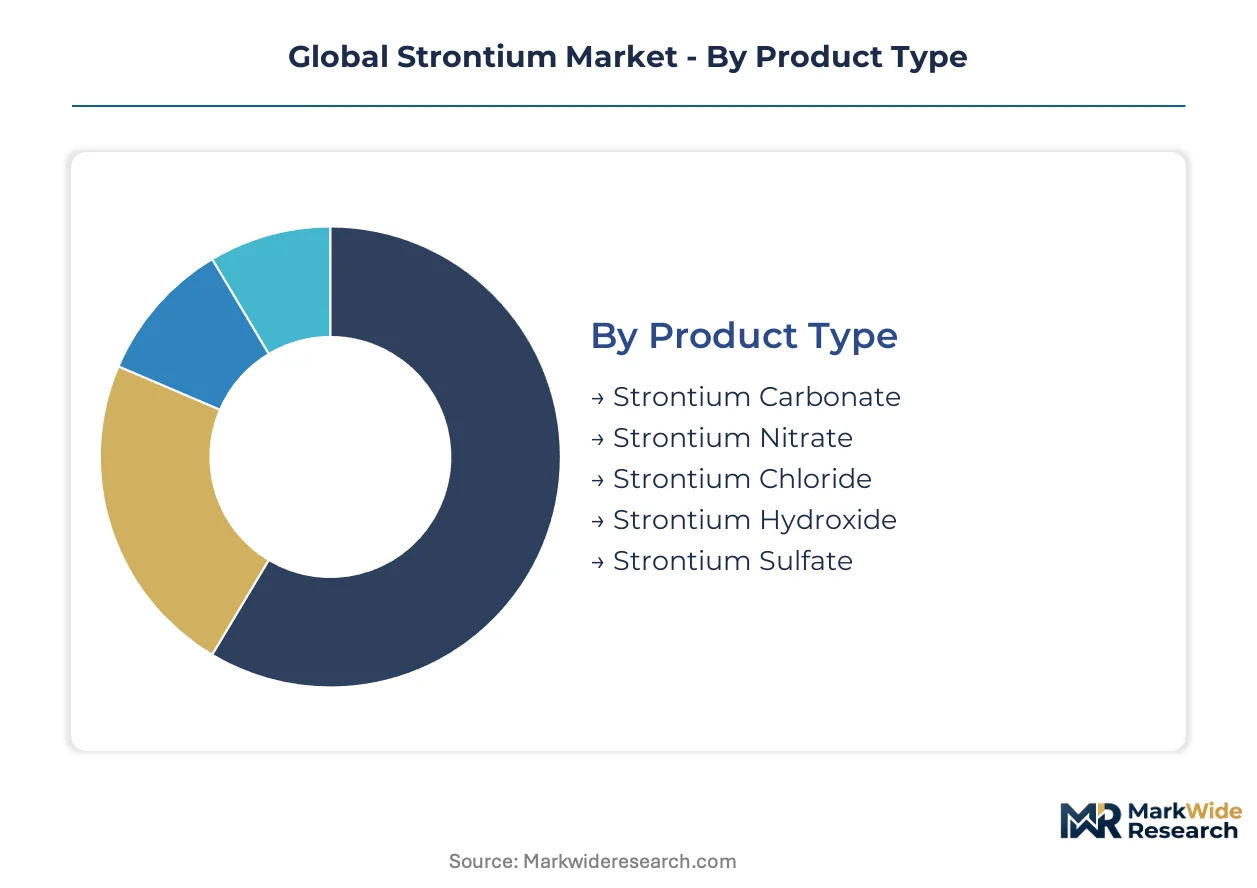
Strontium's industrial utility fragments across purity grades, chemical forms, and end-use specifications that reshape procurement priorities. Supply chain configuration varies sharply by segment, with carbonate and nitrate channels operating on fundamentally different logistics and qualification timelines.
Product Type:
Shandong Province refiners concentrate capacity around carbonate and nitrate outputs, creating divergent availability profiles across the five commercial grades.
- Strontium Carbonate:Synthesized via celestite calcination or black ash reduction, this grade demands 98.5% minimum purity for ferrite magnet binder applications. Magnet manufacturers in Japan and South Korea anchor offtake through long-term contracts with Shandong processors, though MEE wastewater enforcement is consolidating compliant supply among integrated refiners.
- Strontium Nitrate:Produced through nitric acid digestion of carbonate or direct celestite conversion, this oxidizer delivers the 620-750 nanometer red emission critical for professional pyrotechnics. Display companies in Germany and the United States are substituting barium alternatives with strontium in premium formulations, pulling volumes upward even as Chinese emission controls compress conversion capacity.
- Strontium Chloride:Metallurgical-grade material serves electrolytic refining and flux applications in aluminum smelting circuits.
- Strontium Hydroxide:Specialty grade targets grease manufacturing and sugar refining with strict calcium contamination limits.
- Strontium Sulfate:Direct-milled celestite finds limited markets in drilling fluids and paint fillers where purity requirements remain relaxed.
Today's leader: Strontium Carbonate. Tomorrow's challenger: Strontium Nitrate.
Application:
End-use specifications create tiered pricing structures, with electronics and radiology commanding purity premiums that fireworks and construction materials cannot support.
- Fireworks:Professional display operators require strontium nitrate with sub-100 ppm barium contamination for consistent red flame coloration. German and U.S. pyrotechnic formulators are locking in certified supply chains ahead of REACH authorization deadlines.
- Electronics:Ferrite core manufacturers demand carbonate with particle size distributions below 5 microns for high-frequency magnet applications. Japanese MEMS producers are qualifying sub-micron grades for piezoelectric sensor substrates, displacing conventional material in acoustic filter devices.
- Glass Manufacturing:Cathode-ray tube faceplate production is contracting as Schott AG's supply chain qualifies calcium-barium substitutes, threatening long-term carbonate offtake from specialty optical producers.
- Ceramics:Tile glazes and electrical insulators consume standard-grade carbonate with tolerance for modest iron contamination.
- Radiology:Scintillator arrays for CT imaging require barium elimination below 50 ppm, restricting qualified supply to hydrometallurgical precipitation routes.
Electronics and radiology capture margin premiums; fireworks drives volume velocity.
End User Industry:
Procurement sophistication varies by sector, with automotive and medical device buyers imposing qualification protocols that chemical and construction purchasers rarely match.
- Electronics Manufacturing:RoHS compliance mandates third-party verification of strontium compound purity thresholds, with testing backlogs at accredited laboratories extending qualification cycles for new suppliers.
- Automotive Components:Tier-1 sensor manufacturers in Detroit and Stuttgart are compressing magnet procurement contracts to quarterly price reviews with celestite ore pass-through clauses, forcing carbonate refiners to assume inventory risk.
- Medical Devices:Imaging equipment OEMs require full REACH substance dossiers for scintillator feedstock, concentrating purchasing power among registrants with complete hazard communication documentation.
- Chemicals:Commodity purchasers prioritize volume scale over certification granularity, sourcing standard-grade material through trading houses.
- Construction Materials:Price-sensitive buyers in mature markets accept broader specification ranges for tile and glaze applications.
Electronics Manufacturing commands the strictest qualification barriers; Chemicals offers the deepest volume pool.
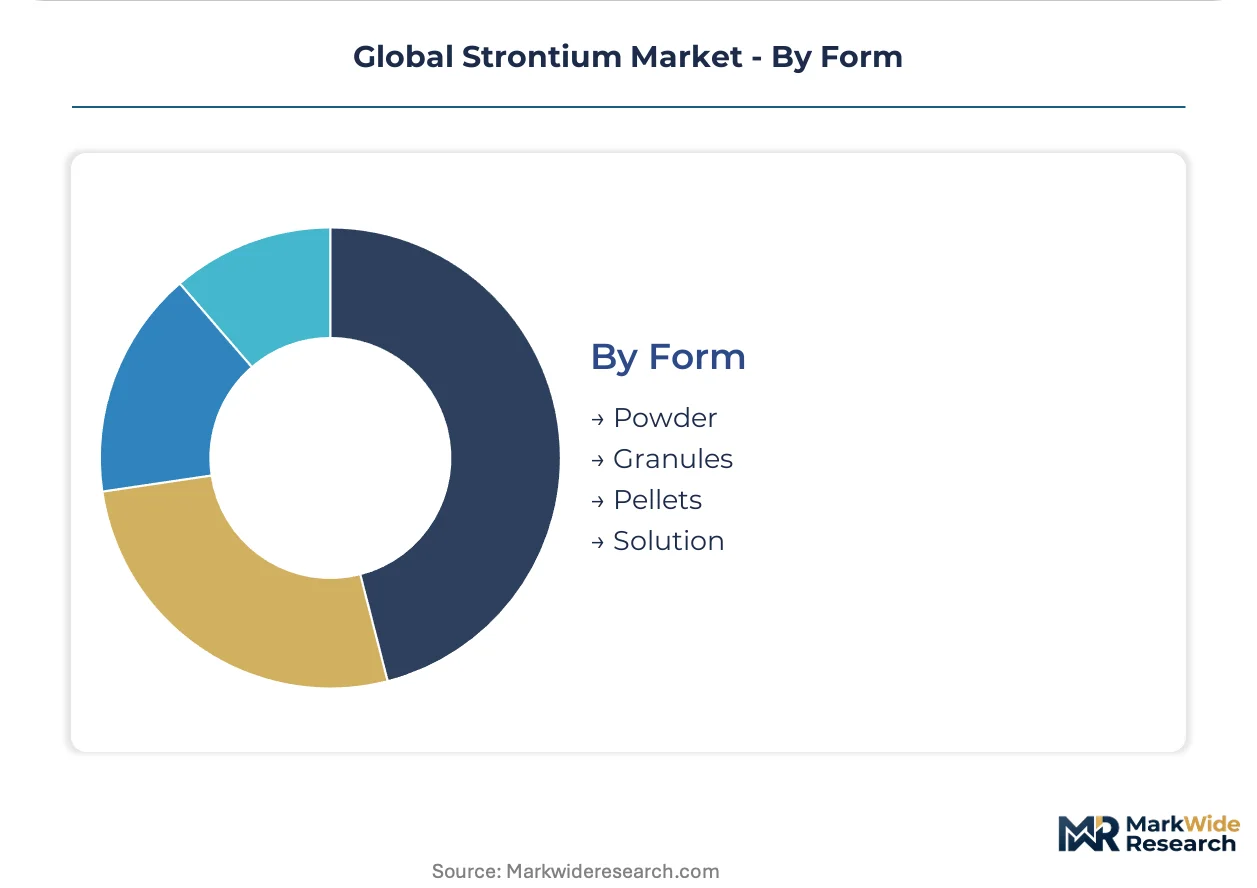
Form:
Physical presentation determines handling economics and dissolution kinetics, with powder and granule formats dominating industrial uptake while pellets and solutions serve niche process integration.
- Powder:Fine-ground carbonate and nitrate enable rapid dissolution in pyrotechnic mixing and ferrite slurry preparation, though dust containment elevates handling costs for high-volume consumers.
- Granules:Agglomerated material reduces airborne exposure during pneumatic conveying and supports controlled dissolution rates in continuous glass melting furnaces.
- Pellets:Briquetted sulfate serves drilling mud applications where density and flow properties outweigh dissolution speed requirements.
- Solution:Pre-dissolved chloride and nitrate formats eliminate solid handling for electroplating and chemical synthesis customers with batch process integration.
Powder and granules divide the industrial mass; solution formats gain share in automated process lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands strontium carbonate refining capacity while Germany's pyrotechnic formulators drive premium-grade nitrate demand, creating divergent procurement patterns across the value chain.
China
Shandong Province hosts the country's largest strontium carbonate refineries, supplying ferrite magnet manufacturers in Japan and South Korea. MEE wastewater discharge limits are consolidating compliant capacity among integrated operators with advanced effluent systems. Qinghai and Sichuan provinces contain mineable celestite ore deposits, exposing processors to single-region logistics disruptions during provincial environmental shutdowns.
Germany
Professional fireworks display operators in Germany require strontium nitrate with sub-100 ppm barium contamination for consistent red flame coloration. ECHA's REACH Annex XVII restrictions on strontium chromate pigments are forcing aerospace coating reformulation toward molybdate alternatives ahead of 2026 authorization deadlines. Hamburg and Toulouse host Tier-1 suppliers requalifying primer systems under accelerated compliance timelines.
United States
Pyrotechnic formulators in the United States are substituting barium alternatives with strontium in premium display formulations, pulling nitrate volumes upward. EPA enforcement of TSCA Section 5 notification requirements is extending qualification cycles for imported strontium compounds. Detroit-based Tier-1 automotive sensor manufacturers are compressing magnet procurement contracts to quarterly price reviews with celestite ore pass-through clauses.
Japan
MEMS producers in Japan are qualifying sub-micron strontium carbonate grades for piezoelectric sensor substrates, displacing conventional material in acoustic filter devices. METI's critical minerals strategy is prioritizing supply chain resilience for ferrite magnet precursors. Osaka and Nagoya anchor magnet manufacturing clusters expanding offtake commitments through long-term carbonate contracts.
India
Production-linked incentives for rare earth permanent magnet manufacturing under India's PLI scheme are attracting ferrite precursor investments in Tamil Nadu and Gujarat. BIS certification requirements for electronic-grade strontium compounds are creating import substitution demand for carbonate feedstock. Domestic refiners are positioning to capture volume previously sourced from Shandong processors.
Global Strontium Market Competitive Landscape
Top-tier vendors anchor carbonate and nitrate supply through integrated refining platforms, while mid-scale specialists concentrate on high-purity grades for electronics and radiology applications. The vendor base separates into three strategic archetypes: integrated rare earths processors with captive ore access, hydrometallurgical precipitation specialists serving medical imaging, and trading houses managing spot-market logistics for construction-grade material. Dominant competitive moves include backward integration into celestite mining concessions and technology licensing for sulfate-to-carbonate conversion efficiency.
Among European-based chemical conglomerates, Solvay S.A. exemplifies the integrated rare earths processor archetype leveraging platform synergies for feedstock priority. Japanese specialists Tateho Chemical Industries Co., Ltd. and Sakai Chemical Industry Co., Ltd. occupy positions within the high-purity precipitation tier, serving MEMS and scintillator array manufacturers with sub-micron grade capabilities. Hebei Xinji Chemical Group Co., Ltd. represents the volume-driven Shandong refining cluster, anchoring carbonate output for ferrite magnet supply chains across Northeast Asia.
| Leading Market Players |
|---|
| Alfa Aesar |
| Noah Technologies Corporation |
| Solvay S.A. |
| Tateho Chemical Industries Co., Ltd. |
| ProChem, Inc. |
| Sakai Chemical Industry Co., Ltd. |
| Merck KGaA |
| Hebei Xinji Chemical Group Co., Ltd. |
| American Elements |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between electronics-grade carbonate and construction-grade material manifests in pricing spreads exceeding threefold, with Shandong refiners commanding premium terms for RoHS-compliant batches while commodity buyers in mature markets absorb standardized output through trading houses. This bifurcation concentrates pricing power among integrated operators with captive effluent systems, leaving non-compliant processors to compete on volume terms in price-sensitive ceramic and glass channels.
Pricing Analysis
Capacity additions in Qinghai are reshaping price floors for standard-grade carbonate as new celestite-to-carbonate conversion lines absorb metallurgical coke volatility through backward integration into ore concessions. Three-tier pricing structure across premium, standard, and economy levels tracks barium contamination thresholds, with sub-50 ppm radiology grades capturing the widest margins. Cost compression in commodity carbonate intensifies because MEE enforcement is consolidating compliant supply among integrated Shandong operators. Chemical and construction purchasers exhibit highest price sensitivity, while medical device OEMs tolerate premium terms for full REACH dossier documentation.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for ferrite magnet precursors, with Tamil Nadu and Gujarat refiners qualifying BIS-certified carbonate to displace Shandong imports. Raw material flows draw from celestite deposits in Sichuan and Qinghai provinces, metallurgical coke indices tracking coking coal volatility, and nitric acid supply from integrated chemical complexes. Single-region vulnerability concentrates in Sichuan-Qinghai logistics corridors exposed to provincial environmental shutdowns. Distribution runs through Japanese trading houses for Northeast Asian magnet manufacturers, direct mill-to-plant contracts for European pyrotechnic formulators, and spot-market intermediaries for construction-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between China's tightening MEE compliance costs and India's PLI-subsidized capacity buildout, with cost differentials exceeding normalized logistics premiums for carbonate feedstock.
For Market Incumbents: Lock in long-term offtake agreements with Japanese and South Korean magnet manufacturers before India's PLI-qualified capacity reaches commercial scale. Secure captive celestite mining concessions in Qinghai to insulate against metallurgical coke volatility and provincial logistics disruptions. Priority investment targets advanced effluent systems that satisfy MEE wastewater thresholds, consolidating compliant supply relationships ahead of further environmental enforcement.
For New Entrants and Emerging Players: The premium-to-economy price gap in pyrotechnic-grade nitrate offers white-space entry for hydrometallurgical precipitation specialists capable of sub-100 ppm barium certification. Target German and U.S. display operators requalifying supply chains ahead of REACH authorization deadlines. Go-to-market leverage rests on accelerated third-party RoHS verification to bypass testing backlogs at accredited laboratories.
For Investors and Strategic Acquirers: Asymmetric upside sits with hydrometallurgical precipitation specialists serving medical imaging scintillator arrays, where barium elimination below 50 ppm restricts qualified supply. Long-term viability favors operators with integrated rare earths platforms and captive ore access over trading-dependent volume players. Signal to monitor: acceleration in South Korean battery electrolyte additive patent filings indicating solid-state strontium titanate demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Celestite Mining | Qinghai concessions insulate Shandong refiners from metallurgical coke volatility and single-region logistics exposure. |
| MEE-Compliant Effluent System Upgrade | Advanced wastewater treatment locks in supply relationships with certified Japanese and South Korean magnet buyers. |
| Sub-Micron Grade Qualification for MEMS | German and Japanese acoustic filter substrate manufacturers displace conventional carbonate with hydrometallurgical precipitation output. |
| REACH Full Substance Dossier Registration | Complete hazard documentation concentrates purchasing power among registrants serving European aerospace coating reformulation. |
| India PLI-Aligned Capacity Buildout | Tamil Nadu and Gujarat refiners capture import substitution demand from BIS-certified electronics-grade carbonate requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with carbonate refinery plant managers, procurement leads at Japanese ferrite magnet OEMs, pyrotechnic formulator technical directors, and distribution channel partners in Shandong and Hamburg with secondary validation through Chinese customs data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed materials companies, and ECHA REACH registration databases. Bottom-up volume modeling across product grades triangulated against top-down macroeconomic indicators.
Segment-weighting approaches applied discrete growth assumptions across purity tiers, end-use industries, and regional production clusters throughout the forecast period. Chemical form segmentation by carbonate, nitrate, chloride, hydroxide, and sulfate grades combined with application splits across fireworks, electronics, glass, ceramics, and radiology to generate volume and value outputs. CAGRs derived from regression analysis against historical celestite ore indices, coking coal price volatility, and magnet manufacturing capacity expansion announcements.
Caveats apply where China's GB standards evolution, EU Green Deal critical raw materials list revisions, or breakthrough calcium-barium substitution in specialty optical glass could materially shift the outlook. Forecasts embed assumptions regarding MEE enforcement continuity, PLI scheme disbursement timelines, and REACH authorization deadline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Silicon Carbide Ceramics Market
Semiconductor Material
Silicon Carbide (Sic) Coating Market
Semiconductor Material
Fullerene Market
Semiconductor Material
Asia-Pacific Transparent Conductive Films Market
Semiconductor Material
North America Silicone Market
Semiconductor Material
Europe Silicon Carbide Market
Semiconductor Material
Gallium Market
Semiconductor Material
Indium Gallium Zinc Oxide Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
India Liquid Silicon Rubber Market