
 Self-Heating Food Packaging Market | 2026-2036
Self-Heating Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Heating Food Packaging Market Intelligence
The EU Green Deal is repositioning material specifications across European supply chains, forcing converters toward recyclable substrates and reduced aluminum content. Luxfer Magtech leverages its magnesium-based heating chemistry to sustain dominance in military-grade flameless heaters across NATO procurement channels. Tempra Technology specializes in consumer-facing beverage warming systems, while HeatGen LLC anchors its position through captive production of iron-oxide exothermic blends.
Self-heating food packaging denotes engineered containers that generate controlled thermal energy through chemical or electrochemical reactions without external power, typically achieving temperatures of 60°C to 100°C within three to ten minutes for field-consumption scenarios. Exothermic reaction technology leads unit shipments due to its reliability in austere environments, though microwave heating formats are gaining traction among food delivery platforms seeking consumer familiarity. Pouch configurations dominate military and outdoor segments for their weight efficiency, while bowl formats capture premium positioning in Asian retail chains where hot noodle and rice dishes command higher margins.
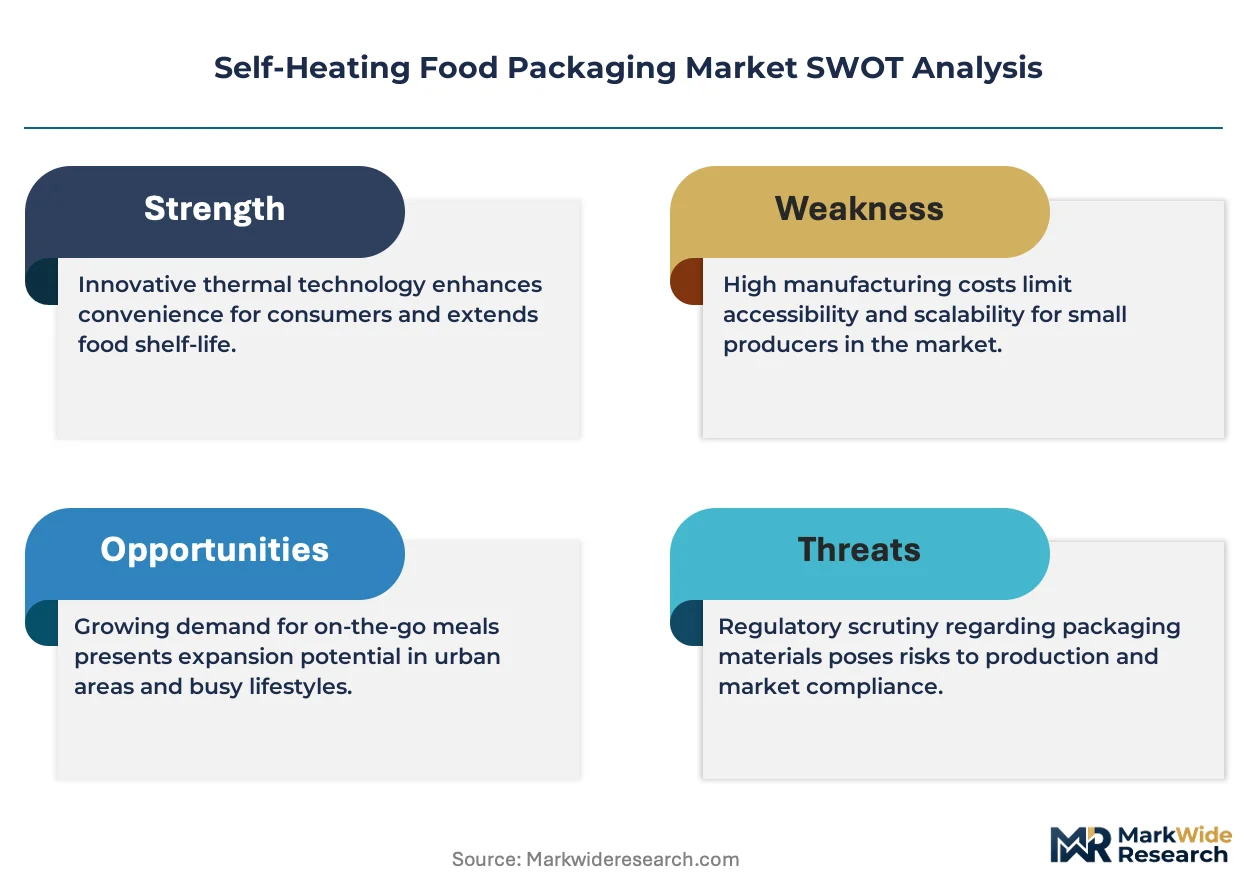
The US FDA governs indirect food contact substances for self-heating components under 21 CFR, while the EPA monitors disposal pathways for spent chemical heaters under RCRA hazardous waste criteria. REACH compliance in Europe constrains certain exothermic salt formulations, redirecting R&D toward calcium oxide and magnesium iron oxide chemistries. Stakeholders must monitor evolving extended producer responsibility schemes and decide whether to absorb compliance costs or pass them through premium positioning before regulatory thresholds harden.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign material stacks, eliminating multi-layer laminates that previously locked in aluminum barrier films and exothermic salt pouches.
Growth Catalysts
- Military procurement expansion:NATO member states are standardizing flameless ration heater specifications across expeditionary forces, creating volume commitments that stabilize manufacturing economics for magnesium-based chemistry suppliers.
- REACH compliance redirection:The European Chemicals Agency's restrictions on certain exothermic salt formulations are accelerating R&D investment into calcium oxide and magnesium iron oxide alternatives that maintain thermal output.
- Outdoor recreation demand:United States camping and overlanding communities are absorbing premium-priced self-heating meal formats through specialty retail channels and direct-to-consumer subscription services.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with energy input prices, squeezing converter margins on foil-based pouch substrates that form the barrier layer in most military-grade formats.
- Single-supplier chemistry concentration:Magnesium iron oxide precursor production concentrates in Chinese industrial zones, exposing NATO procurement channels to geopolitical supply interruption risks.
- End-of-life disposal friction:The EPA's RCRA hazardous waste criteria classify spent iron-oxide heaters as regulated materials, imposing collection and disposal costs that erode consumer value propositions in civilian markets.
Strategic Opportunities
- Indian food delivery penetration:Quick-commerce platforms in Mumbai and Bangalore are piloting self-heating bowl formats for biryani and curry segments where temperature maintenance drives repeat purchase rates.
- EU Green Deal material subsidies:The European Commission's innovation procurement programs offer preferential tender access to packaging converters demonstrating verified recyclable substrate performance.
- Electrochemical-microwave convergence:Hybrid heating systems combining thin-film battery elements with susceptor materials are opening premium positioning in Asian convenience retail chains.
Industry Challenges
- Thermal engineering talent scarcity:The intersection of food science, materials chemistry, and packaging engineering requires specialized expertise that outpaces university program output in North America and Europe.
- Extended producer responsibility compliance:France's AGEC law and Germany's VerpackG impose registration, reporting, and fee obligations that fragment operational attention across divergent national implementation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Heating Food Packaging Market |
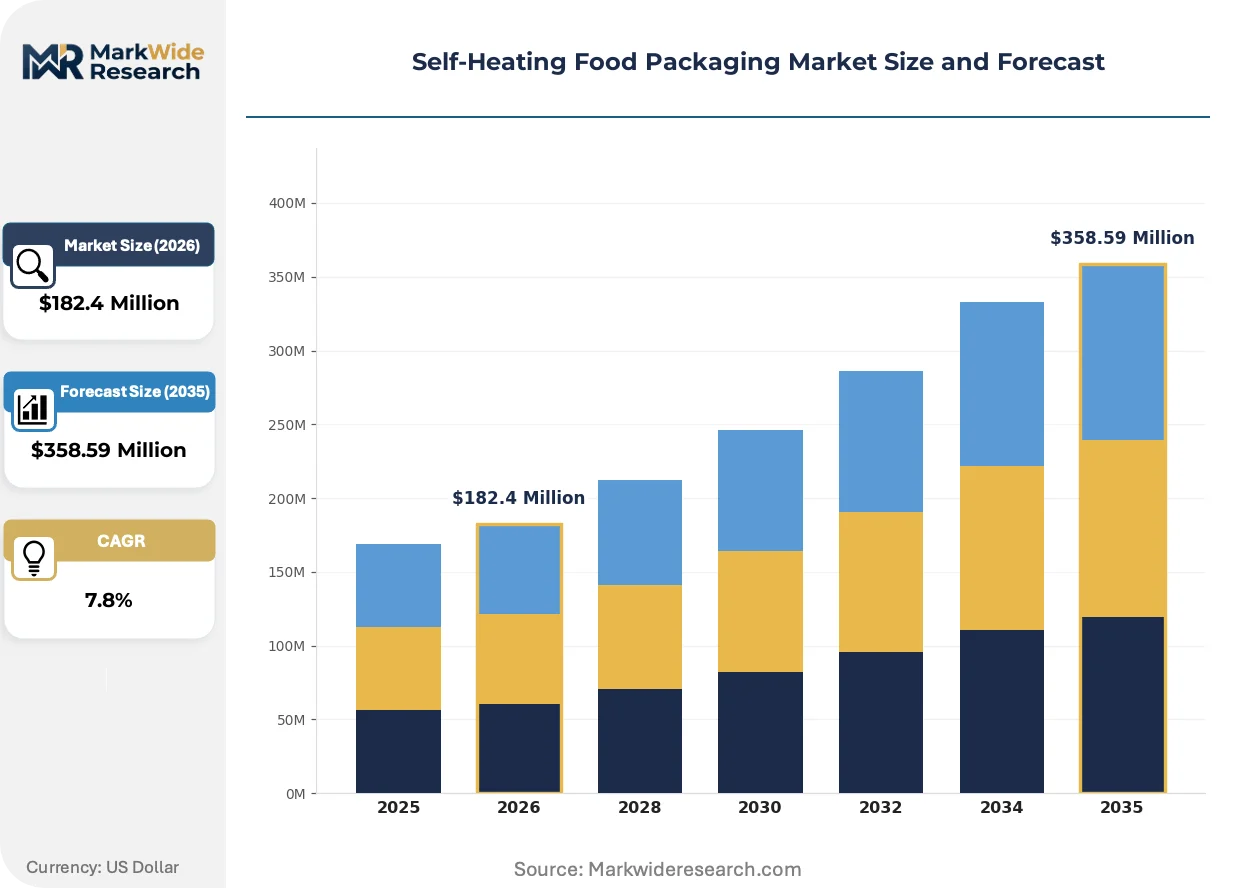
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $358.59 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Container, Tray, Bowl, Pouch Technology: Exothermic Reaction, Chemical Heating, Microwave Heating, Thermal Pouch End User: Restaurants, Catering Services, Retail Chains, Food Delivery Material: Cardboard, Plastic, Composite, Metal |
| Companies Covered | Luxfer Magtech Inc., ScaldoPack, Tempra Technology, Kemira, Heat Food & Drink Ltd, HeatGen LLC, LMK Thermosafe, Com-Pac International, The 42 Degrees Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Heating Food Packaging Market Strategic Shifts & Innovations
Active redesign of heating chemistry and substrate architecture is compressing development cycles as converters race to meet simultaneous demands for thermal performance, regulatory compliance, and circular material flows.
Smart susceptor technology is automating temperature control in self-heating beverage applications. Nestlé and Coca-Cola system partners are deploying these films in premium coffee and hot chocolate formats across Japanese convenience retail. The technology is automating quality consistency that previously required manual shaking or timing judgment from consumers.
REACH Annex XVII restrictions on perfluorinated compounds are eliminating legacy grease-resistant coatings from self-heating pouch interiors. German converters are accelerating migration to silicone-based and bio-wax barrier alternatives that satisfy ECHA compliance windows. Military specification holders face reformulation timelines that compress against NATO tender renewal cycles.
Direct-to-consumer subscription models are fragmenting traditional retail concentration for outdoor recreation self-heating meals. REI and Backcountry.com are absorbing share from supermarket ambient aisles through curated meal kits targeting ultralight backpackers. This channel rotation is most visible in Colorado and Pacific Northwest metropolitan markets where outdoor participation rates exceed national baselines.
Self-Heating Food Packaging Market Segmentation
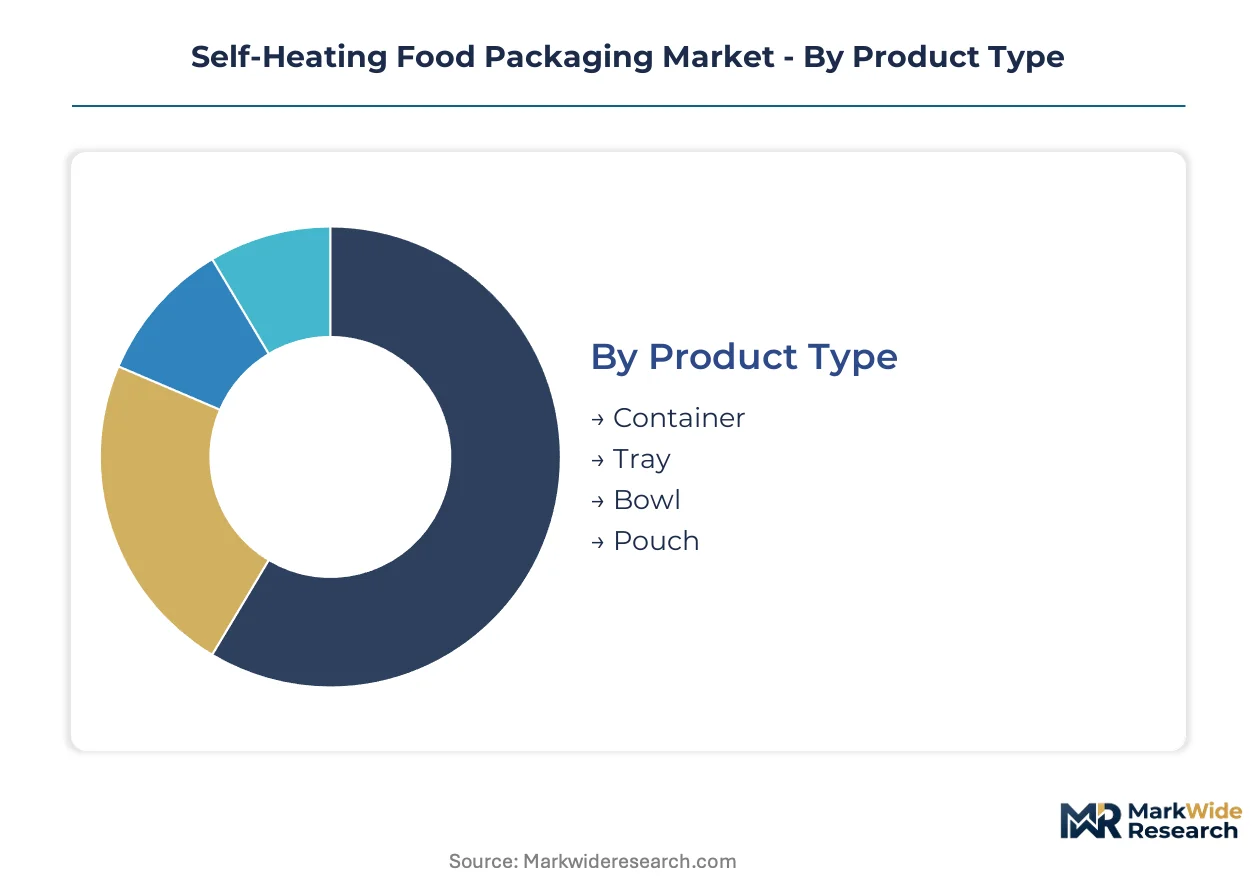
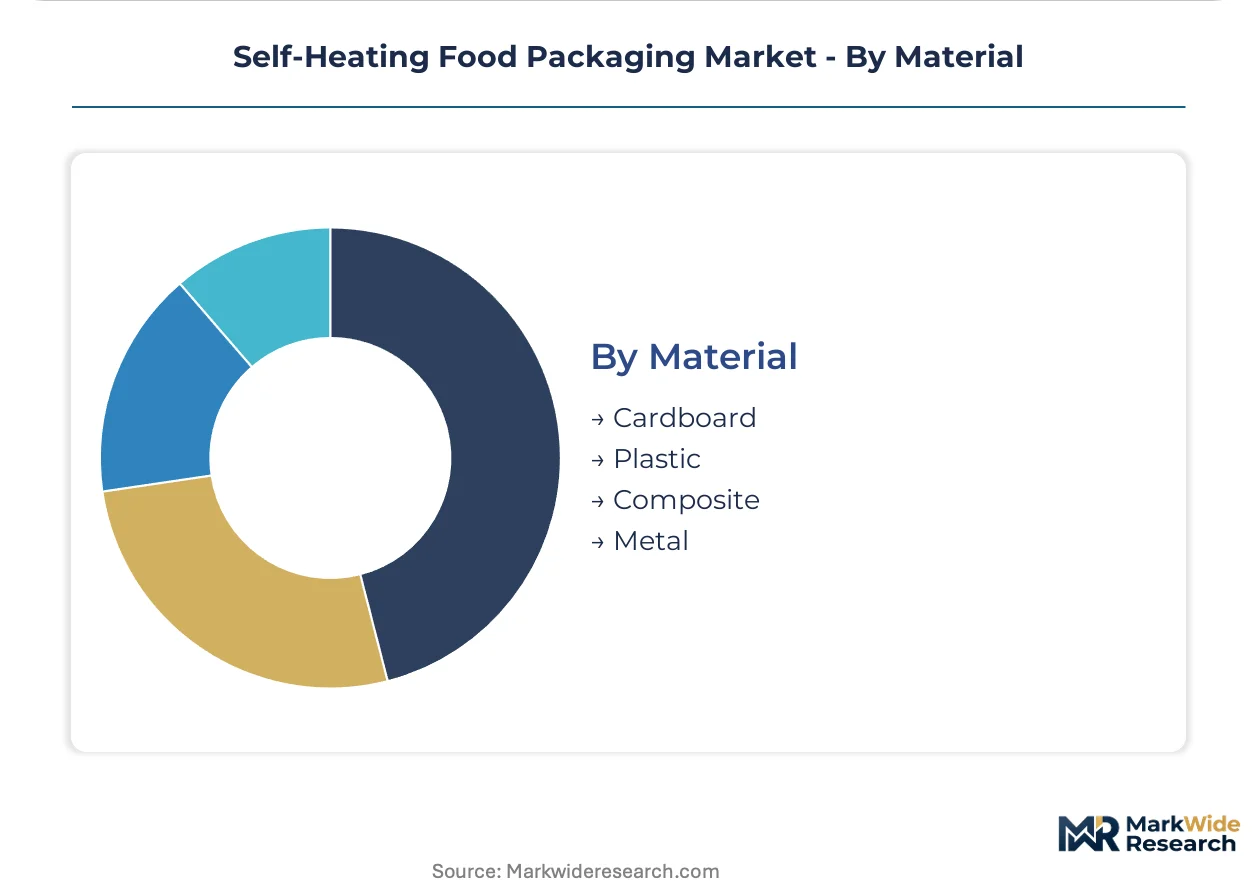
Self-heating food packaging segments diverge sharply across military procurement specifications and consumer convenience expectations. Material chemistry and form factor decisions cascade through regulatory compliance pathways and end-of-life disposal economics.
Product Type:
Form factor selection hinges on thermal retention duration and field-portability requirements across expeditionary and civilian use cases.
- Pouch:Lightweight multi-layer laminates with aluminum barrier films dominate military flameless ration heaters. NATO standardization programs stabilize volume commitments for magnesium-based chemistry integration in pouch formats.
- Bowl:Rigid structures with insulated bases capture premium positioning in Asian retail chains where hot noodle and rice dishes command higher margins. Quick-commerce pilots in Mumbai and Bangalore favor bowl configurations for biryani and curry temperature maintenance.
- Container:Modular designs with snap-fit heating elements serve institutional catering contracts requiring batch thermal management.
- Tray:Compartmentalized formats align with airline and rail meal service specifications where space efficiency constrains form factor.
Pouch leads on scale; Bowl leads on momentum.
Technology:
Heating mechanism selection trades reliability in austere environments against consumer familiarity and disposal friction.
- Exothermic Reaction:Iron-oxide and magnesium-based chemistries generate controlled thermal energy without external power, achieving 60°C to 100°C within three to ten minutes. Military and emergency relief agencies drive procurement volume for flameless ration heaters where electrical infrastructure is absent.
- Microwave Heating:Susceptor-enabled formats leverage consumer familiarity with domestic microwave penetration. Food delivery platforms in developed markets adopt this technology to reduce consumer education costs and disposal classification complexity.
- Chemical Heating:Calcium oxide and magnesium iron oxide alternatives are gaining share as REACH Annex XVII restrictions eliminate legacy salt formulations from European supply chains.
- Thermal Pouch:Phase-change material inserts extend temperature maintenance duration for last-mile delivery applications where transit time variability threatens food safety thresholds.
Exothermic Reaction leads on scale; Microwave Heating climbs the fastest.
End User:
Channel-specific requirements fragment demand across institutional procurement cycles and direct-to-consumer subscription models.
- Food Delivery:Platform economics prioritize disposal-friendly formats that avoid EPA RCRA hazardous waste classification. Smart susceptor deployment in premium coffee and hot chocolate segments automates temperature consistency.
- Retail Chains:Asian convenience stores absorb hybrid electrochemical-microwave systems for premium hot beverage positioning. Shelf-space constraints favor compact footprint designs.
- Restaurants:Ghost kitchen operators experiment with self-heating formats to extend delivery radius without quality degradation.
- Catering Services:Event and institutional contracts demand batch-scale thermal management with standardized holding temperatures.
Food Delivery leads on scale; Retail Chains gain share fastest.
Material:
Substrate architecture faces simultaneous pressure from thermal performance requirements and circular material flow mandates.
- Composite:Multi-layer structures combining barrier films with structural substrates dominate military specifications. EU Packaging and Packaging Waste Regulation timelines are forcing redesign to eliminate non-recyclable laminate lock-in.
- Metal:Aluminum foil barrier layers face price volatility tied to energy input costs, squeezing converter margins on military-grade formats.
- Cardboard:Fiber-based structures with bio-wax barrier coatings are advancing as German converters migrate from perfluorinated compound formulations under ECHA compliance windows.
- Plastic:Mono-material designs are emerging to satisfy extended producer responsibility schemes in France and Germany, though thermal conductivity limitations constrain heating element integration.
Composite leads on scale; Cardboard climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Military procurement standardization in the United States established the technical foundation for self-heating food packaging during the 1990s, with NATO adoption spreading manufacturing know-how across allied industrial bases.
United States
Outdoor recreation subscription services and ready-to-eal meal delivery platforms absorb premium self-heating formats through REI, Backcountry.com, and direct-to-consumer channels. The EPA's RCRA hazardous waste criteria classify spent iron-oxide heaters as regulated materials, imposing collection costs that erode civilian market value propositions. Colorado and Pacific Northwest metropolitan markets exhibit outdoor participation rates exceeding national baselines, concentrating demand for ultralight backpacking meal kits.
Germany
Converters are accelerating migration to silicone-based and bio-wax barrier alternatives as REACH Annex XVII restrictions eliminate perfluorinated compounds from pouch interiors. The country's national packaging regulator enforces extended producer responsibility schemes under the VerpackG law, fragmenting operational attention across registration and fee obligations. Industrial clusters in Bavaria and North Rhine-Westphalia host specialized laminators redesigning material stacks to eliminate multi-layer non-recyclable structures.
China
Magnesium iron oxide precursor production concentrates in eastern industrial zones, exposing international procurement channels to geopolitical supply interruption risks. The Ministry of Ecology and Environment monitors dual carbon goals that constrain energy-intensive aluminum smelting operations critical to barrier film substrates. Yangtze River Delta manufacturing hubs supply precursor chemicals to NATO specification holders facing compressed reformulation timelines.
India
Quick-commerce platforms in Mumbai and Bangalore pilot self-heating bowl formats for biryani and curry segments where temperature maintenance drives repeat purchase rates. The Food Safety and Standards Authority of India governs indirect food contact substances for self-heating components under evolving notification protocols. Maharashtra and Karnataka industrial corridors attract converters serving domestic food delivery expansion and export-oriented military specification contracts.
Japan
Smart susceptor technology deployment in premium coffee and hot chocolate formats leverages automated temperature control across convenience retail chains. The Ministry of Economy, Trade and Industry oversees JIS standards alignment for electrochemical-microwave hybrid systems entering premium positioning. Kanto and Kansai metropolitan markets absorb hybrid heating technologies combining thin-film battery elements with susceptor materials.
Self-Heating Food Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across chemistry specialization and military certification depth. The vendor base clusters around three strategic archetypes: magnesium-based chemistry specialists serving NATO procurement channels, consumer-facing beverage warming system developers, and captive producers of iron-oxide exothermic blends. Consolidation pressure concentrates among military specification holders facing simultaneous REACH compliance deadlines and aluminum price volatility. Dominant competitive moves include strategic partnerships with quick-commerce platforms and technology licensing for hybrid electrochemical formats.
Within the chemistry-specialist tier, Luxfer Magtech Inc. and HeatGen LLC exemplify divergent approaches to thermal energy generation. Luxfer Magtech anchors military-grade positioning through magnesium-based formulations, while HeatGen occupies a position tied to iron-oxide exothermic blend production. Tempra Technology represents the consumer-facing archetype with beverage warming specialization. These three entities collectively illustrate how regulatory compliance pressure and end-market fragmentation are reshaping competitive boundaries across the analysis window.
| Leading Market Players |
|---|
| Luxfer Magtech Inc. |
| ScaldoPack |
| Tempra Technology |
| Kemira |
| Heat Food & Drink Ltd |
| HeatGen LLC |
| LMK Thermosafe |
| Com-Pac International |
| The 42 Degrees Company |
| Others |
Cost & Logistics Intelligence
Captive production of iron-oxide exothermic blends by HeatGen LLC and other integrated chemistry specialists anchors both supply security and pricing power across NATO procurement channels, insulating military-grade formats from aluminum price volatility that squeezes converter margins on civilian-facing pouch substrates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates magnesium-based military specification heaters from iron-oxide consumer formats and commodity susceptor-enabled microwave products. Price differentiation rests on certification depth and volume scale, with NATO tender holders commanding premium positioning while quick-commerce platforms absorb standard-tier bowl formats. Cost compression in aluminum-dependent laminates is intensifying because energy input prices fluctuate with European gas markets. Food delivery platforms exhibit highest price sensitivity due to disposal cost pass-through requirements, whereas military procurement channels show lowest sensitivity given mission-critical thermal reliability mandates.
Supply Chain Analysis
Single-source vulnerability sits with magnesium iron oxide precursor production concentrated in China's Yangtze River Delta industrial zones. Raw material dependencies draw from bauxite refining for aluminum barrier films, magnesium ore processing for military-grade heating chemistry, and iron oxide sourcing for civilian exothermic blends. Tariff exposure threatens NATO specification holders facing compressed reformulation timelines against REACH compliance deadlines. Distribution runs through specialty laminators in Bavaria and North Rhine-Westphalia for European military contracts, direct-to-consumer subscription channels for US outdoor recreation segments, and quick-commerce platform partnerships for Indian food delivery pilots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal material subsidies in Germany and France attract converters fleeing higher extended producer responsibility compliance costs in jurisdictions with fragmented national implementation schedules.
For Market Incumbents: Anticipate REACH Annex XVII expansion eliminating additional perfluorinated compound formulations by accelerating silicone-based barrier coating R&D partnerships with German industrial clusters. Deepen backward integration into magnesium precursor supply through joint development agreements with Yangtze River Delta producers to offset geopolitical interruption exposure. Certification investment in recyclable substrate performance verification secures preferential tender access under European Commission innovation procurement programs. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer lowest competitive density for ultralight backpacking meal kits targeting Colorado and Pacific Northwest metropolitan markets with outdoor participation rates exceeding national baselines. Quick-commerce platform pilots in Mumbai and Bangalore represent the most penetrable geography for self-heating bowl formats serving biryani and curry temperature maintenance requirements. Go-to-market execution should prioritize ghost kitchen operator partnerships enabling delivery radius extension without quality degradation. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap chemistry specialists because NATO standardization programs consolidate procurement volume around fewer certified suppliers over the projection horizon. Long-term viability favors platforms combining magnesium-based military certification with consumer-facing beverage warming system development. Watch for ECHA restriction expansion on additional exothermic salt formulations as the inflection indicator triggering accelerated consolidation among specification holders facing simultaneous compliance deadlines and aluminum price volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive magnesium iron oxide production insulates NATO suppliers from Yangtze River Delta geopolitical exposure. |
| Recyclable Substrate Redesign | Eliminating multi-layer laminates satisfies EU Packaging and Packaging Waste Regulation material recovery timelines. |
| Quick-Commerce Platform Partnership | Bowl format pilots with Mumbai and Bangalore platforms capture biryani and curry temperature maintenance demand. |
| Smart Susceptor Technology Licensing | Automated temperature control deployment across Japanese convenience retail chains opens premium beverage positioning. |
| Direct-to-Consumer Subscription Launch | Ultralight backpacking meal kits through REI and Backcountry.com absorb share from supermarket ambient aisles. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging converters, military procurement officers, food delivery platform operators, and outdoor recreation retail buyers with secondary validation from FDA 21 CFR filings, ECHA REACH restriction updates, EPA RCRA hazardous waste classification documents, and NATO standardization tender databases. Bottom-up shipment estimates by chemistry type and form factor triangulated against top-down market value reconstruction across the analysis window.
Historical reference periods anchored volume and value outputs to established military procurement cycles and consumer adoption curves, with segmentation modeling across technology mechanism, product configuration, end-use channel, and material substrate dimensions. CAGRs derived from slope analysis of chemistry-specific cost curves and regulatory compliance timeline impacts, incorporating aluminum price volatility indices and extended producer responsibility fee schedules as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electrochemical-microwave hybrid systems would alter the outlook if thin-film battery cost reduction accelerates beyond projected trajectories. Forecasts reflect assumptions regarding REACH restriction expansion scope and NATO tender renewal timing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Probiotics Packaging Market