
 Middle East and Africa Canned Food Packaging Market | 2026-2036
Middle East and Africa Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Canned Food Packaging Market Insights
The capital-intensity divergence between multinational can makers and regional metal-forming specialists is unwinding competitive dynamics across the Middle East and Africa. Crown Holdings leverages integrated steel-sourcing networks to sustain margin stability in North African production zones. Nampak Limited anchors its position through beverage-can specialization while competing for processed food contracts in Southern Africa. Middle East Metal Can LLC differentiates via proximity to Saudi Arabia's food processing clusters.
Canned food packaging denotes hermetically sealed containers—typically fabricated from tinplate steel or aluminum alloy with internal lacquer systems—that preserve sterility and extend shelf life through thermal processing. Wall thickness, seam geometry, and coating chemistry determine compatibility with acidic, saline, or fatty food matrices while preventing metal-ion migration. Metal Cans retain dominance across the Middle East and Africa due to established recycling infrastructure and compatibility with retort temperatures exceeding 121°C. Flexible Pouches represent the fastest-expanding packaging type as hot-fill and aseptic technologies reduce material intensity for ready-to-eat stews and legume products. Vacuum Packing technology concentrates margin pools in premium seafood and halal meat segments where oxygen exclusion preserves sensory quality.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce coating-safety and labeling standards that elevate compliance costs for imported can stock. South Africa's National Regulator for Compulsory Specifications mandates dimensional and coating-performance benchmarks that shape regional procurement specifications. Stakeholders must monitor evolving extended producer responsibility frameworks across Gulf states and assess localized coil-coating capacity before committing to greenfield can-manufacturing investments.
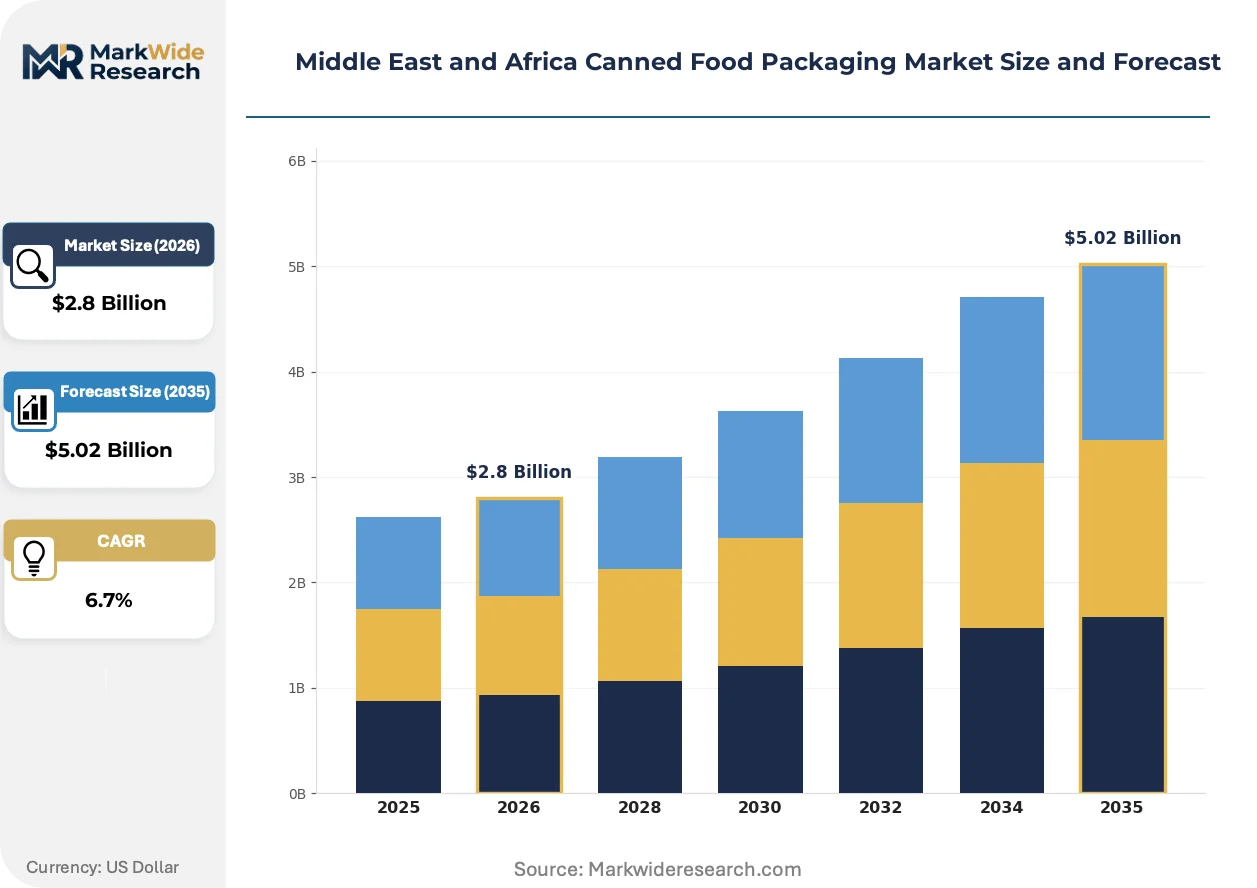
Market Dynamics
Foodservice procurement consolidation across Gulf Cooperation Council states is compressing supplier margins while forcing can manufacturers to absorb coating-cost volatility from European steel mills.
Growth Catalysts
- SFDA coating-safety mandates:Saudi Food and Drug Authority enforcement of epoxy migration limits is accelerating domestic coil-coating capacity investments by regional can makers seeking import substitution.
- Hot-fill flexible pouch adoption:Ready-to-eat stew processors in Nigeria's Lagos-Abuja corridor are converting retort lines to accommodate lighter-weight barrier laminates for legume products.
- Halal certification premiums:Oxygen-exclusion vacuum packing technology commands price premiums in Saudi Arabia's premium seafood segment where ESMA labeling requirements elevate compliance barriers for imports.
Market Restraints
- Tinplate price volatility:European steel mill supply concentration exposes North African can manufacturers to coil-coating input cost swings that erode fixed-contract margins.
- Retort temperature compatibility:Flexible pouch materials face technical ceiling at 121°C thermal processing thresholds required for low-acid canned proteins, limiting penetration in institutional foodservice.
- South African dimensional mandates:National Regulator for Compulsory Specifications enforcement of seam-geometry benchmarks creates compliance friction for imported can stock from Asian suppliers.
Strategic Opportunities
- Ethiopian modern retail expansion:Addis Ababa supermarket chain growth creates first-mover advantage for shelf-stable protein formats previously distributed through informal channels.
- Extended producer responsibility frameworks:Dubai's impending packaging-waste regulations will mandate aluminum recycling quotas that favor local can-manufacturing investments over imports.
- Aseptic-legume convergence:Hot-fill barrier technology combined with pulse-protein formulation innovation opens ready-to-eat segments beyond traditional meat and fish canning.
Industry Challenges
- Migration testing capacity:Epoxy coating chemistry validation requires laboratory infrastructure scarce outside South Africa and Saudi Arabia, extending product launch timelines.
- Retort operator certification:Thermal processing safety credentials for 121°C sterilization protocols face training pipeline constraints across West African food processing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Canned Food Packaging Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Metal Cans, Glass Jars, Flexible Pouches, Plastic Containers Material: Aluminum, Steel, Glass, Plastic Canning Technology: Cold Filling, Hot Filling, Aseptic Filling, Vacuum Packing Distribution Channel: Retail Stores, Online Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Ball Corporation, Crown Holdings, Can-Pack SA, Graham Packaging, Amcor PLC, SAPIN Saudi Arabian Packaging Industry Co. Ltd., Middle East Metal Can LLC, Nampak Limited, Ardagh Group S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Canned Food Packaging Market Trends and Innovations
Coating chemistry evolution and thermal processing technology are compressing material intensity while regulatory migration limits force reformulation investments across the value chain.
Water-based internal lacquer systems are fragmenting epoxy-dominated can-coating conventions. Nigerian tomato paste processors and Saudi halal meat canneries are piloting acrylic-phenolic hybrids at commercial scale. This substitution is fragmenting established supplier relationships with European specialty chemical houses while creating openings for regional coating compounders.
ESMA's 2024 coating-safety amendments tightened bisphenol-A migration thresholds for aluminum beverage cans retooled for food contact. Gulf can manufacturers now face reformulation deadlines that compress R&D timelines. Saudi Arabia's food processing clusters are responding by consolidating procurement specifications to reduce coating SKU complexity.
Foodservice distributors across the United Arab Emirates are unbundling can-size assortments previously sold as fixed pallets. Quick-service chains now specify mixed-format shipments combining single-serve tuna with institutional-size legume containers. This pattern concentrates most visibly in Dubai's central kitchen facilities serving airport and hospital captive feeding operations.
Middle East and Africa Canned Food Packaging Market Segmentation
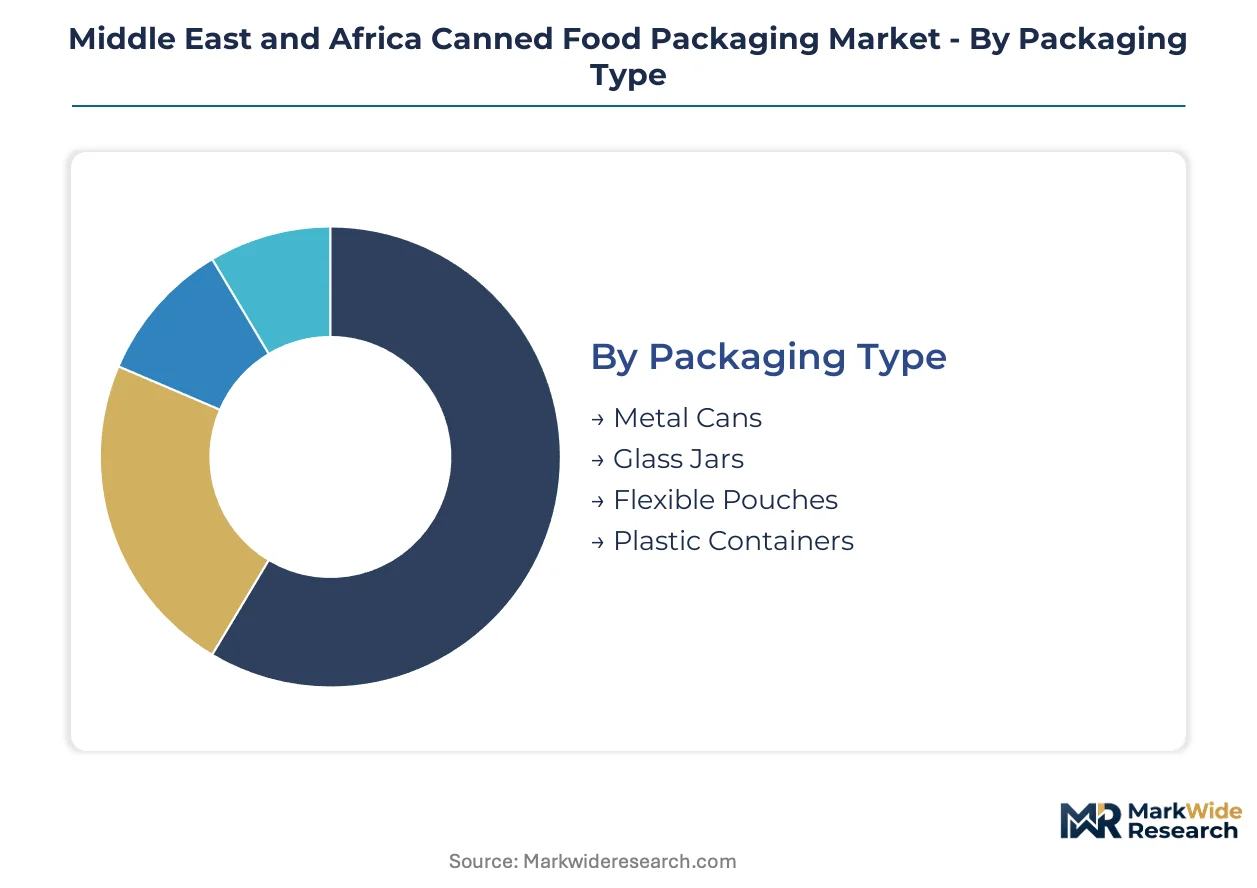
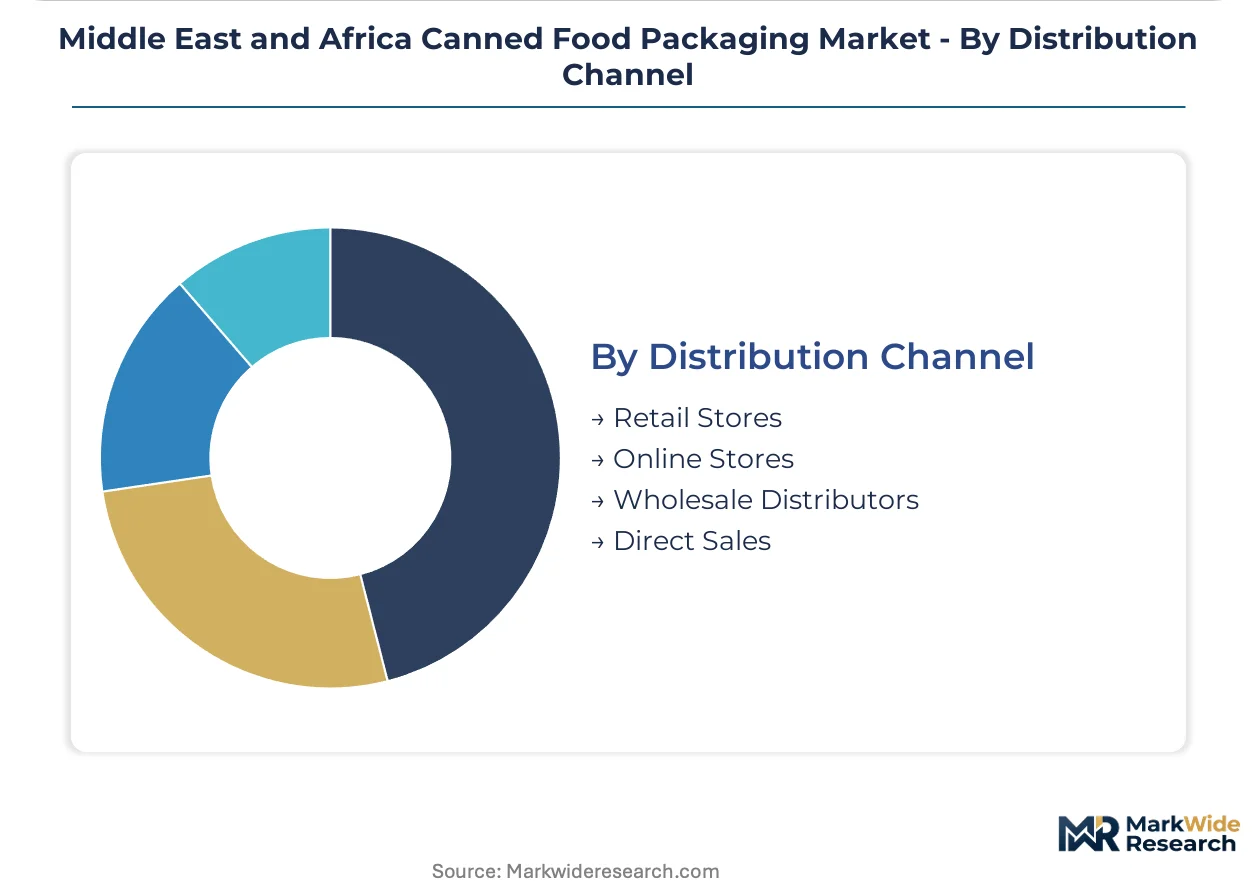
Packaging format selection across the Middle East and Africa hinges on thermal processing requirements, recycling infrastructure availability, and regulatory migration limits. Channel mix varies sharply between Gulf foodservice consolidation and West African informal retail penetration.
Packaging Type:
Retail and foodservice channels split sharply by packaging rigidity, with institutional procurement favoring formats that withstand 121°C retort cycles.
- Metal Cans:Hermetically sealed tinplate or aluminum containers with internal lacquer systems prevent metal-ion migration into acidic food matrices. Demand clusters in Saudi Arabia's food processing zones where SFDA coating-safety mandates favor established steel-recycling infrastructure.
- Flexible Pouches:Multi-layer barrier laminates enable hot-fill processing for ready-to-eat stews at reduced material intensity. Nigerian processors in the Lagos-Abuja corridor are converting retort lines to accommodate these formats for legume products.
- Glass Jars:Transparent silica-based containers suit premium condiment segments where shelf visibility drives purchase decisions in South African supermarket chains.
- Plastic Containers:Polypropylene and PET formats serve short-shelf-life prepared foods in Ethiopian modern retail expansion zones where cold chain reliability remains uneven.
Metal Cans dominates installed base. Flexible Pouches is where expansion concentrates.
Material:
Cost tiers separate premium coil-coated aluminum from commodity steel procurement, with geographic proximity to Gulf smelters reshaping margin structures.
- Aluminum:Lightweight alloy with superior thermal conductivity enables faster retort cycle times. Dubai's impending packaging-waste regulations will mandate aluminum recycling quotas that favor local can-manufacturing investments over imports.
- Steel:Tinplate and chromium-coated substrates retain dominance in North African production zones where Crown Holdings leverages integrated steel-sourcing networks. European mill supply concentration exposes manufacturers to input cost volatility.
- Glass:Silicate-based containers command premium positioning in halal-certified seafood segments where oxygen exclusion preserves sensory quality.
- Plastic:Polymer substrates face technical ceilings at high-temperature sterilization thresholds required for low-acid canned proteins.
Steel commands volume leadership. Aluminum is climbing the fastest.
Canning Technology:
Application requirements dictate thermal processing intensity, with protein sterilization demanding the most rigorous protocols.
- Hot Filling:Elevated-temperature product deposition into pre-sterilized containers suits high-acid foods. Nigerian tomato paste processors are piloting acrylic-phenolic coating hybrids at commercial scale to accommodate these lines.
- Aseptic Filling:Separate sterilization of product and package enables extended shelf life without retort intensity. Pulse-protein formulation innovation is opening ready-to-eat segments beyond traditional meat and fish canning.
- Cold Filling:Ambient-temperature processing preserves heat-sensitive nutrients in premium juice and dairy applications.
- Vacuum Packing:Oxygen-exclusion technology concentrates margin pools in Saudi Arabia's premium seafood segment where ESMA labeling requirements elevate compliance barriers for imports.
Hot Filling anchors current capacity. Aseptic Filling is gaining share fastest.
Distribution Channel:
Customer type separates fragmented wholesale networks from consolidated foodservice procurement that is compressing supplier margins.
- Wholesale Distributors:Aggregated procurement through informal channels still dominates Nigerian and Ethiopian market penetration. Addis Ababa supermarket chain growth creates first-mover advantage for shelf-stable protein formats previously distributed through these networks.
- Retail Stores:Modern grocery infrastructure expansion in the Lagos-Abuja corridor concentrates demand for standardized pack sizes. South Africa's National Regulator for Compulsory Specifications enforces dimensional benchmarks that shape regional procurement specifications.
- Direct Sales:Foodservice operators across Gulf Cooperation Council states are expanding procurement of shelf-stable protein formats through centralized purchasing.
- Online Stores:E-commerce penetration remains nascent for bulk canned goods due to last-mile cost structures in dispersed African markets.
Wholesale Distributors retains volume dominance. Retail Stores shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Middle East and Africa diverge sharply between Gulf foodservice consolidation and West African informal retail penetration, with procurement specifications reflecting these structural differences.
Saudi Arabia
SFDA coating-safety mandates on epoxy migration limits are accelerating domestic coil-coating capacity investments by regional can makers. The Saudi Food and Drug Authority enforces strict labeling standards that elevate compliance costs for imported can stock. Jeddah's food processing clusters are consolidating procurement specifications to reduce coating SKU complexity amid reformulation deadlines.
United Arab Emirates
ESMA's 2024 coating-safety amendments tightened bisphenol-A migration thresholds for aluminum beverage cans retooled for food contact. Dubai's impending packaging-waste regulations will mandate aluminum recycling quotas that favor local can-manufacturing investments over imports. Quick-service chains in Dubai's central kitchen facilities now specify mixed-format shipments combining single-serve tuna with institutional-size legume containers.
Nigeria
Ready-to-eat stew processors in the Lagos-Abuja corridor are converting retort lines to accommodate lighter-weight barrier laminates for legume products. Modern retail infrastructure expansion concentrates demand for standardized pack sizes. Lagos-based tomato paste processors are piloting acrylic-phenolic coating hybrids at commercial scale to accommodate hot-fill processing lines.
South Africa
The National Regulator for Compulsory Specifications enforces dimensional and coating-performance benchmarks that shape regional procurement specifications. Migration testing capacity for epoxy coating chemistry validation requires laboratory infrastructure scarce outside Johannesburg and Cape Town. Cape Town's beverage-can specialization anchors Nampak Limited's position while competing for processed food contracts across Southern Africa.
Ethiopia
Addis Ababa supermarket chain growth creates first-mover advantage for shelf-stable protein formats previously distributed through informal wholesale channels. Cold chain reliability remains uneven, driving demand for polypropylene and PET formats serving short-shelf-life prepared foods. Ethiopian modern retail expansion opens ready-to-eat segments beyond traditional meat and fish canning through pulse-protein formulation innovation.
Middle East and Africa Canned Food Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational can makers leveraging steel-sourcing networks against regional metal-forming specialists competing on proximity to food processing clusters. Crown Holdings anchors the integrated tier through captive supply relationships, while Nampak Limited and Middle East Metal Can LLC occupy specialist positions defined by beverage-can focus and Saudi cluster adjacency respectively. Capacity expansion and coating reformulation partnerships constitute the dominant competitive moves as SFDA and ESMA deadlines compress R&D timelines.
Among North American-based fabricators, Ball Corporation and Crown Holdings exemplify the integrated archetype through upstream control over coil-coating supply chains. Crown Holdings leverages these networks to sustain margin stability in North African production zones. Within the regional specialist tier, Nampak Limited anchors its position through beverage-can specialization while competing for processed food contracts in Southern Africa, and Middle East Metal Can LLC differentiates via proximity to Saudi Arabia's food processing clusters. SAPIN Saudi Arabian Packaging Industry Co. Ltd. occupies a position within the Gulf-based fabrication segment serving domestic food processors.
| Leading Market Players |
|---|
| Ball Corporation |
| Crown Holdings |
| Can-Pack SA |
| Graham Packaging |
| Amcor PLC |
| SAPIN Saudi Arabian Packaging Industry Co. Ltd. |
| Middle East Metal Can LLC |
| Nampak Limited |
| Ardagh Group S.A. |
| Others |
Pricing and Supply Chain Analysis
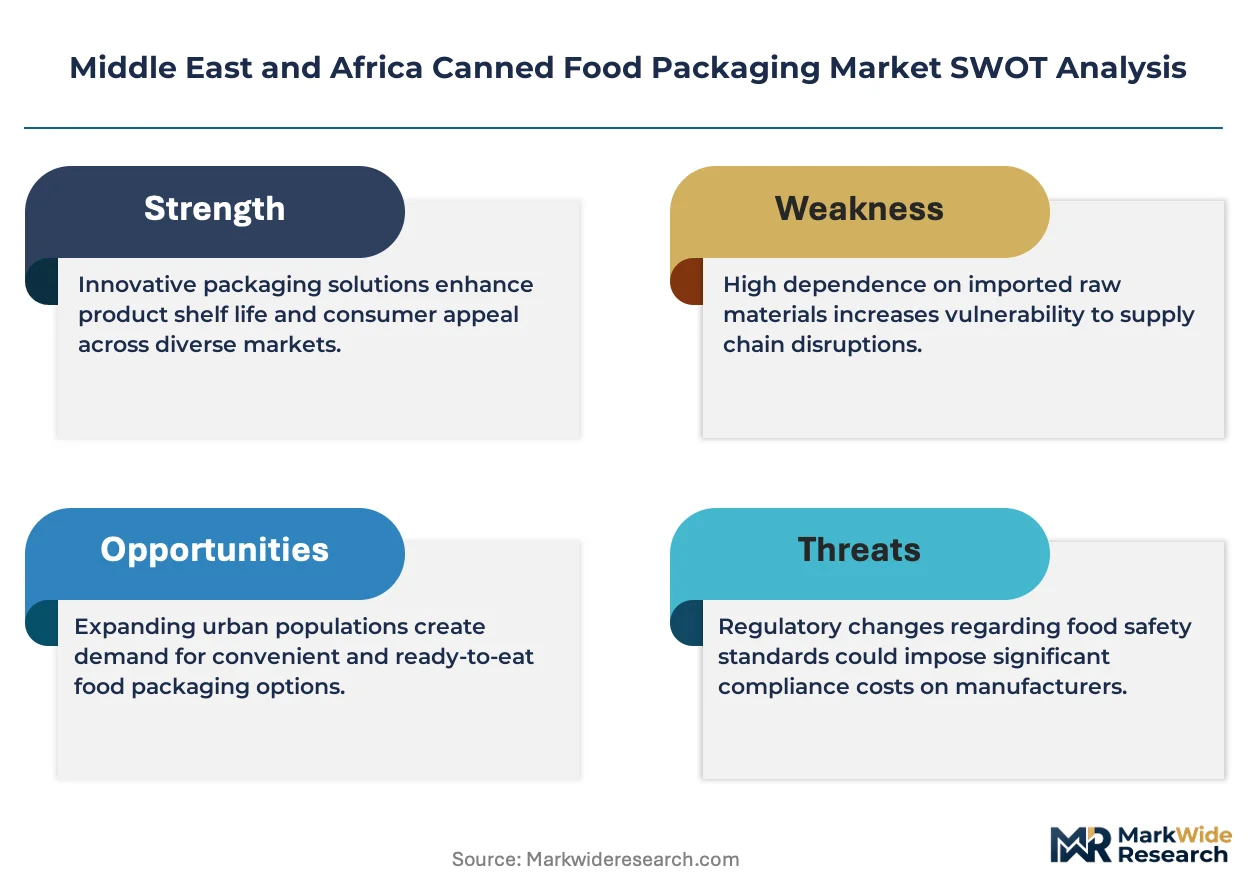
SFDA coating-safety mandates on epoxy migration limits gate both supplier qualification and price differentiation across Saudi Arabia's food processing clusters, compressing margins for importers while rewarding domestic coil-coating investments with procurement preference.
Pricing Analysis
Long-term offtake contracts dominate procurement between Gulf foodservice operators and can manufacturers, though spot purchases persist for coating chemical inputs subject to European steel mill volatility. Three-tier pricing structure across premium, standard, and economy levels separates halal-certified vacuum-packed seafood from commodity tomato paste and institutional legume formats. Cost compression in standard-tier metal cans is intensifying because foodservice distributors are unbundling fixed-pallet assortments into mixed-format shipments. Quick-service chains exhibit the highest price sensitivity, while premium seafood processors absorb certification-driven premiums with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of tinplate coil predominates among North African manufacturers buffering European mill supply disruptions, whereas Gulf can makers favor just-in-time aluminum sourcing from regional smelters. Raw material flows draw from Saudi Arabia's food processing clusters, Nigeria's Lagos-Abuja corridor, and South Africa's Cape Town-Johannesburg axis. Critical dependencies include epoxy coating compounds, tinplate steel substrate, and barrier laminate films. Single-source vulnerability concentrates in European specialty chemical houses supplying coil-coating formulations. Distribution runs through Dubai's central kitchen facilities serving airport and hospital captive feeding operations, with wholesale networks penetrating West African informal retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hot-fill flexible pouch adoption is reshaping competitive positioning in Nigeria's ready-to-eat segment, creating first-mover advantage for processors converting retort lines to lighter-weight barrier laminates.
For Market Incumbents: Secure backward integration into domestic coil-coating capacity before SFDA reformulation deadlines compress R&D timelines for epoxy substitution. Anchor position through beverage-can specialization while competing for processed food contracts, as Nampak Limited demonstrates in Southern Africa. Absorb coating-cost volatility through captive steel-sourcing networks rather than fixed-contract exposure to European mill pricing swings. For New Entrants and Emerging Players: Aseptic legume processing gaps in Ethiopia's modern retail expansion offer white-space entry where cold chain reliability remains uneven and pulse-protein formulation innovation opens ready-to-eat segments beyond traditional meat canning. Target Addis Ababa supermarket chains with polypropylene formats for short-shelf-life prepared foods. Pursue coating compounding partnerships with regional chemical houses to circumvent established European supplier relationships. For Investors and Strategic Acquirers: ESMA's 2024 bisphenol-A migration threshold amendments reshape the acquisition landscape by elevating compliance barriers for imported can stock and favoring local manufacturing investments with laboratory infrastructure. Five-to-ten-year viability hinges on extended producer responsibility framework positioning across Gulf states. Prioritize coil-coating compounders with acrylic-phenolic hybrid commercialization progress. Revision becomes warranted when aluminum recycling quota mandates in Dubai cross implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Coil-Coating Capacity Investment | SFDA enforcement accelerates import substitution for epoxy migration-compliant can stock. |
| Retort Line Conversion to Flexible Pouch | Nigerian processors in Lagos-Abuja corridor reduce material intensity for legume products. |
| Halal Certification Premium Positioning | Oxygen-exclusion vacuum packing commands price premiums in Saudi seafood segments. |
| Extended Producer Responsibility Compliance | Dubai's aluminum recycling quotas favor local can-manufacturing over imports. |
| Aseptic Filling Technology Adoption | Pulse-protein formulation innovation opens ready-to-eat segments beyond traditional canning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, ESMA standard amendments, and South African National Regulator for Compulsory Specifications benchmarks. Primary interviews engaged can manufacturing plant managers, coating compound procurement leads at food processors, distribution channel partners in Gulf central kitchen facilities, and technical R&D directors at regional metal-forming specialists. Secondary validation drew from customs and trade data, steel mill supply disclosures, and extended producer responsibility framework drafts. Bottom-up volume builds triangulated against top-down value assessments across packaging type, material substrate, and canning technology segments.
Segmentation dimensions modeled include packaging format rigidity, thermal processing intensity, and regional regulatory cluster. Value projections across the analysis window incorporate coil-coating capacity utilization rates, foodservice procurement consolidation patterns, and modern retail infrastructure expansion trajectories. CAGRs derive from regression analysis of historical volume trends adjusted for regulatory inflection timing and technology substitution elasticities.
Forecasts assume regulatory continuity in SFDA, ESMA, and South African National Regulator regimes; material policy shifts would require re-modeling. Specific risks include epoxy coating chemistry validation pipeline constraints, retort operator certification scarcity across West African zones, and European steel mill supply disruption frequency. Revision becomes warranted when flexible pouch thermal processing ceiling breakthroughs cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
North America Food Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Chilled Food Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Burger Boxes Market
Food Packaging
Seafood Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Disposable Food Containers Market