
 Europe Frozen Food Packaging Market | 2026-2036
Europe Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Food Packaging Market Foresight
Market Context
The capability gap between capital-intensive film extruders and mid-tier converters is reorganizing competitive tiers across Europe. Amcor plc leverages integrated resin-to-pouch operations to sustain margin control in barrier films for frozen vegetables and seafood. Mondi plc anchors its position through kraft-paper-based frozen food solutions that compete with conventional plastic trays in Nordic retail channels. Huhtamäki Oyj differentiates via molded fiber technology leadership, occupying the premium sustainable packaging tier for private-label frozen meals.
Technical Definition and Structural Segments
Europe frozen food packaging encompasses engineered materials and container systems designed to maintain product integrity at temperatures of minus 18 degrees Celsius or below, employing multi-layer barrier films, vacuum-insulated panels, or modified-atmosphere structures to prevent freezer burn and moisture loss across extended retail and food-service distribution cycles. The packaging form dimension shows trays dominating retail frozen pizza and ready-meal segments while pouches represent the fastest-expanding category for single-serve ethnic food and plant-based protein offerings. Plastic retains volume leadership across material type segments, though paper-based alternatives are capturing margin pools in premium organic and carbon-labeled product lines where brand owners fund packaging cost premiums.
Regulatory Framework and Outlook
The EU Green Deal, F-Gas Regulation, and REACH compliance framework collectively mandate reduced fluorinated gas content in insulated transport packaging and full material traceability for food-contact substances entering European frozen food supply chains. EFSA review protocols for recycled content in food-contact plastics are reshaping R&D investment priorities among compounders serving the frozen sector. Stakeholders must monitor the evolving interface between national extended producer responsibility schemes and the EU Packaging and Packaging Waste Regulation to anticipate compliance cost redistribution across material and form choices.
Market Dynamics
EU Green Deal compliance deadlines are forcing a wholesale reconstitution of cold-chain material specifications across European frozen food packaging, compressing converter margins while rewarding early movers in bio-based barrier films.
Growth Catalysts
- F-Gas Regulation phase-down:The EU F-Gas Regulation is accelerating demand for vacuum-insulated panel alternatives in temperature-controlled logistics, pulling investment into fiber-based thermal protection systems.
- Plant-based protein surge:Frozen plant-meat processors in Germany and the Netherlands are expanding pouch-format procurement for single-serve portions, creating volume pull for high-barrier coextruded films.
- Retail consolidation:Aldi and Lidl's private-label expansion across Central Europe is concentrating specification power with a handful of buying desks, streamlining approval pathways for qualified converters.
Market Restraints
- Resin supply concentration:Polyamide and EVOH supply for multi-layer frozen films clusters with German and Belgian petrochemical complexes, exposing converters to input volatility and force majeure risk.
- Recycled-content technical ceiling:EFSA food-contact approval protocols currently cap post-consumer recycled content in frozen food layers at sub-threshold levels, blocking circular material claims.
- Paper barrier performance gap:Kraft-based alternatives to plastic trays exhibit moisture sensitivity in extended frozen storage, limiting substitution in seafood and ice cream applications.
Strategic Opportunities
- Polish and Romanian retail modernization:Discount channel expansion in these markets is creating first-mover advantage for packaging suppliers offering localized technical service and shorter lead times.
- Smart packaging convergence:Integration of time-temperature indicators with RFID-enabled logistics tracking is opening premium pricing tiers for cold-chain accountability in food-service channels.
- Extended Producer Responsibility alignment:France's national EPR scheme for packaging is rewarding mono-material frozen tray designs with fee reductions, incentivizing format simplification investments.
Industry Challenges
- Multilayer film delamination expertise:Separating incompatible polymer layers for chemical recycling requires specialized mechanical engineering talent that remains scarce across converter engineering departments.
- REACH SVHC testing backlog:Substance of Very High Concern screening delays for novel bio-based additives are extending new product qualification timelines beyond frozen food brand owner launch windows.
- Legacy thermoforming asset stranding:Converters with sunk capital in PS and PET tray lines face write-down pressure as retailer specifications pivot toward fiber-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Food Packaging Market |
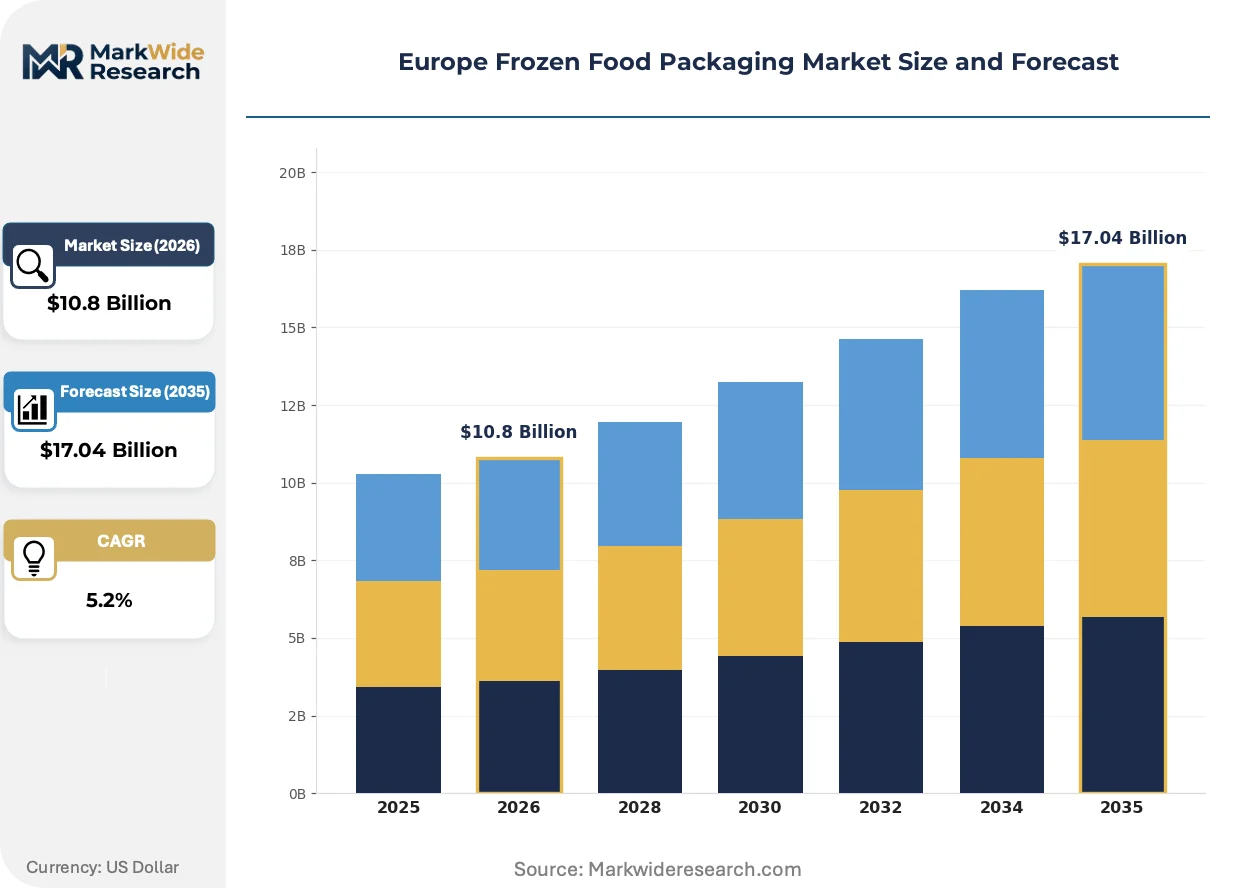
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.04 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Aluminum, Glass Closure Type: Screw Cap, Zipper, Heat Seal, Cardboard Lid Packaging Form: Tray, Bag, Box, Pouch End User: Retail, Food Service, Household, Institutional |
| Companies Covered | Owens-Illinois, Ball Corporation, WestRock Company, Crown Holdings, Sealed Air, Amcor plc, Mondi plc, Huhtamäki Oyj, Tetra Pak International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Food Packaging Market Shifts & Advancements
Active and intelligent packaging systems are penetrating European frozen food logistics, while material science breakthroughs in cellulose barriers and regulatory pressure on fluorinated chemistry reshape competitive positioning.
High-barrier cellulose nanofiber films are decomposing the traditional plastic monopoly in frozen vegetable and ready-meal applications. Nordic retail chains are piloting these materials for private-label lines with carbon-labeled positioning. The technology is decomposing incumbent converter relationships as paper specialists capture specification authority previously held by film extruders.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from frozen bakery packaging. The European Chemicals Agency's 2023 restriction proposal is forcing reformulation of microwaveable crisping sleeves and pizza box liners. Frozen pizza manufacturers in Italy and Spain are accelerating testing of silicone-based and bio-wax alternatives to maintain product performance.
Direct-to-freezer e-commerce fulfillment is fragmenting traditional case-pack specifications. Frozen meal subscription services in the United Kingdom and France are demanding individual-portion pouches with ship-ready thermal protection, bypassing retail display requirements. This channel evolution is compressing minimum order quantities and rewarding digital-native converters with agile make-to-order capabilities.
Europe Frozen Food Packaging Market Segmentation
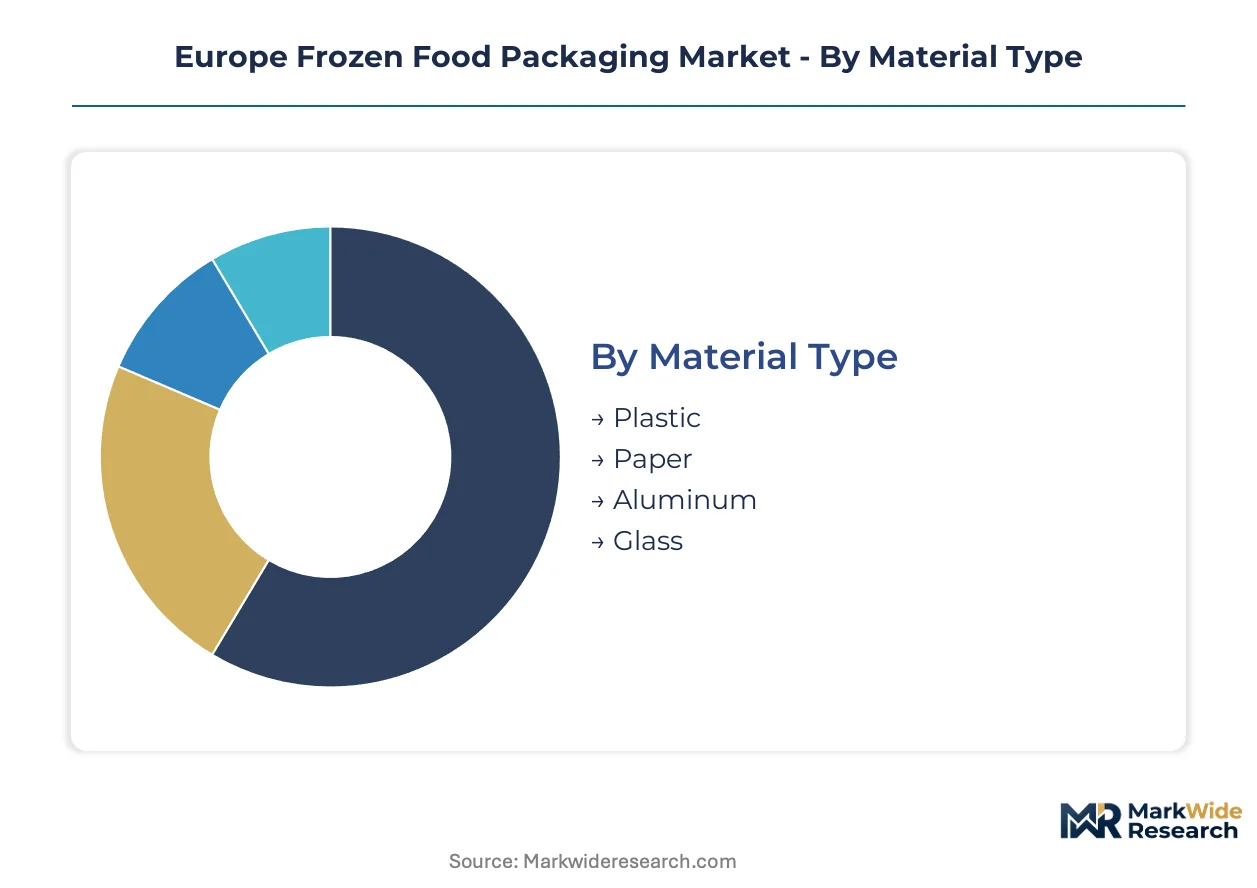
Segmentation in Europe frozen food packaging reveals how material choices and format specifications diverge across retail, food-service, and institutional channels. Understanding these splits exposes where compliance costs concentrate and which specifications reward premium positioning.
Material Type:
Retail frozen pizza and ready-meal shelves favor plastic and paper for display visibility, while food-service bulk formats lean on aluminum for thermal performance in transport.
- Plastic:Multi-layer barrier films combining polyethylene, polyamide, and EVOH dominate frozen vegetable and seafood applications across German and French retail. EFSA food-contact approval protocols cap post-consumer recycled content, forcing virgin resin dependence in high-barrier coextrusions.
- Paper:Kraft-paper-based solutions with bio-wax or cellulose nanofiber barriers capture specification authority in Nordic organic private-label lines. Moisture sensitivity in extended frozen storage limits substitution in ice cream and premium seafood.
- Aluminum:Rolled foil and semi-rigid trays serve food-service bulk portions and institutional feeding programs requiring rapid heat transfer.
- Glass:Premium frozen dessert and specialty sauce segments in Italian and Spanish retail use glass for premium shelf differentiation despite weight and breakage constraints.
Plastic dominates installed base. Paper is where expansion concentrates.
Closure Type:
Closure selection tracks format sophistication and resealability demands across retail versus food-service splits.
- Zipper:Press-to-close interlocking strips enable portion control in single-serve ethnic meals and plant-based protein pouches. German and Dutch processors specify these for direct-to-freezer e-commerce fulfillment.
- Heat Seal:Peelable lidding films with controlled-seal strength dominate trayed ready-meals across UK and French retail, where tamper evidence and extended shelf life compete.
- Screw Cap:Rigid jar and bottle formats for frozen sauces and condiments use injection-molded closures in Italian specialty retail.
- Cardboard Lid:Fiber-based lidding for molded fiber trays serves premium sustainable positioning in Nordic markets, though grease resistance remains a REACH-driven reformulation challenge.
Heat Seal commands volume throughput. Zipper closures are climbing the fastest.
Packaging Form:
Form selection channels directly into retail display economics versus logistics efficiency in food service.
- Tray:Thermoformed and pressed-fiber trays anchor frozen pizza, ready-meals, and seafood across German, French, and UK retail. France's EPR fee reductions reward mono-material tray designs.
- Pouch:Stand-up and flat pouches with high-barrier coextrusion expand fastest in single-serve plant-based proteins and ethnic meals. UK and French subscription services demand ship-ready thermal protection.
- Bag:Pillow and gusseted bags serve bulk frozen vegetables and bakery in discount retail across Poland and Romania.
- Box:Folding carton with barrier coating protects frozen bakery and pizza in retail, though REACH restrictions on PFAS grease resistance force silicone-based alternatives.
Tray retains specification dominance. Pouch formats are gaining share fastest.
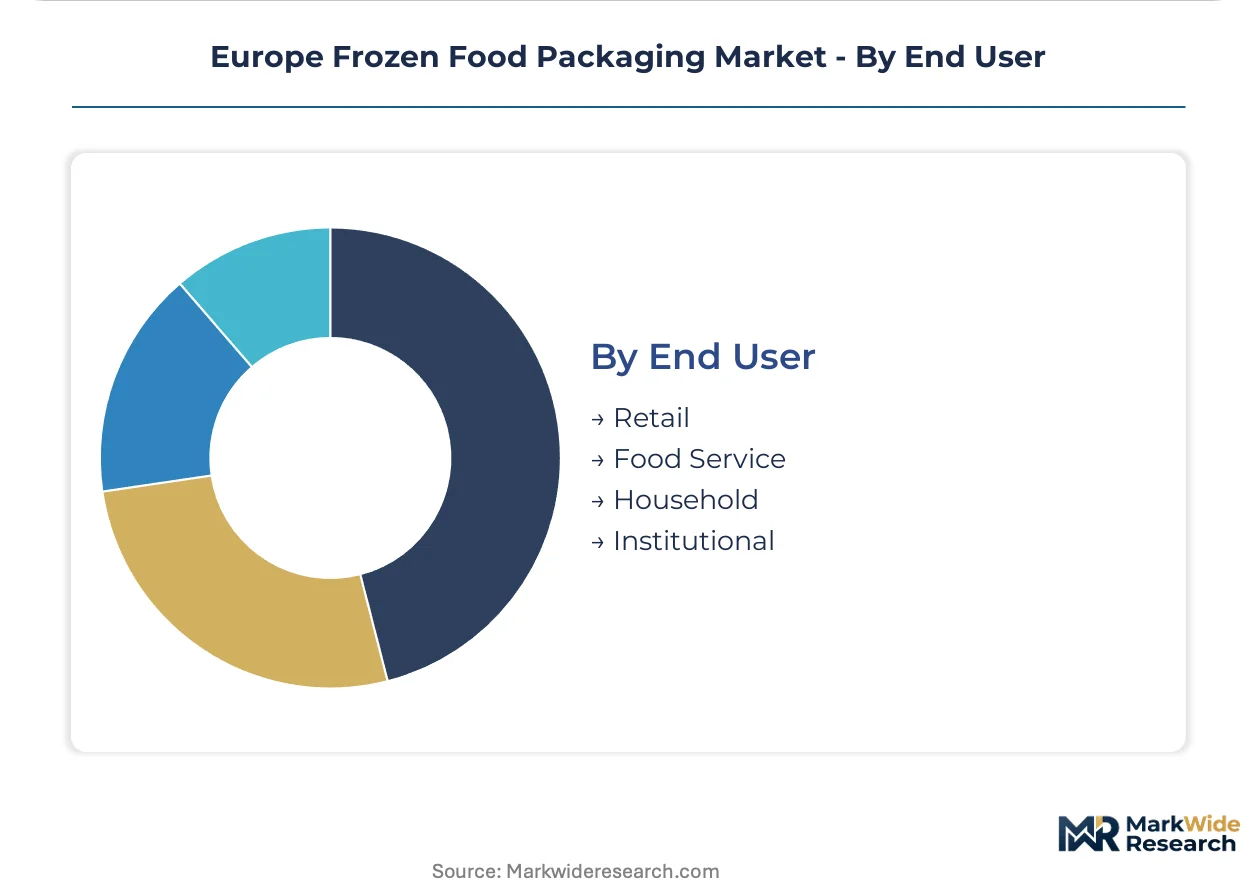
End User:
End-user segmentation concentrates buying power and dictates compliance exposure across the value chain.
- Retail:Aldi and Lidl's private-label expansion across Central Europe concentrates specification power with discount buying desks. EPR schemes and carbon-labeling requirements shape material choices.
- Food Service:Contract caterers and restaurant chains demand bulk formats with RFID-enabled time-temperature tracking for cold-chain accountability.
- Household:Direct-to-freezer e-commerce subscription services fragment case-pack specifications and compress minimum order quantities.
- Institutional:Hospital and school feeding programs in Eastern Europe prioritize cost-optimized formats with basic barrier performance.
Retail commands margin extraction. Food Service is where smart packaging premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and French retail buying desks, while Polish and Romanian markets reward localized technical service with margin premiums. Discount channel expansion across Central Europe is compressing specification approval timelines.
Germany
Frozen plant-meat processors in Berlin and Hamburg are expanding pouch-format procurement for single-serve portions. The EU F-Gas Regulation accelerates investment into vacuum-insulated panel alternatives for temperature-controlled logistics. The Rhine-Ruhr industrial corridor hosts integrated resin-to-pouch operations that sustain margin control in barrier films.
France
Aldi and Lidl's private-label expansion concentrates specification power with discount buying desks in Paris and Lyon. France's national Extended Producer Responsibility scheme rewards mono-material frozen tray designs with fee reductions. The Grand Est region anchors molded fiber technology leadership for premium sustainable packaging tiers.
United Kingdom
Direct-to-freezer e-commerce subscription services in London and Manchester demand individual-portion pouches with ship-ready thermal protection. EFSA review protocols for recycled content in food-contact plastics reshape R&D investment priorities among compounders. The Midlands corridor hosts agile make-to-order converters serving fragmented order quantities.
Poland
Discount channel expansion in Warsaw and Kraków creates first-mover advantage for packaging suppliers offering shorter lead times. REACH SVHC testing backlogs for novel bio-based additives extend new product qualification timelines. The Silesian industrial basin concentrates mid-tier converter operations serving cost-optimized institutional feeding programs.
Netherlands
Frozen plant-meat processors in Rotterdam and Amsterdam specify high-barrier coextruded films for ethnic food and plant-based protein offerings. The EU Green Deal compliance deadlines force wholesale reconstitution of cold-chain material specifications. The Randstad logistics hub enables rapid distribution across Northwestern European retail networks.
Europe Frozen Food Packaging Market Competitive Landscape
Concentration sits with integrated film extruders and paper-based specialists. Three tiers structure competitive positioning: capital-intensive resin-to-pouch operators, kraft-paper solution providers, and molded fiber technology leaders. Consolidation pressures mount as retailer specifications pivot toward sustainable alternatives. Dominant competitive moves include backward integration into resin compounding and geographic expansion into Central European retail modernization.
Within the integrated packaging tier, Amcor plc and Mondi plc exemplify scale-driven archetypes with captive supply chain control. Huhtamäki Oyj occupies a specialist position in fiber-based formats. Sealed Air and WestRock Company represent diversified material portfolios spanning plastic and paper barriers. These entities anchor competitive dynamics as REACH compliance and EPR schemes reshape specification authority across European retail channels.
| Leading Market Players |
|---|
| Owens-Illinois |
| Ball Corporation |
| WestRock Company |
| Crown Holdings |
| Sealed Air |
| Amcor plc |
| Mondi plc |
| Huhtamäki Oyj |
| Tetra Pak International |
| Others |
Supply & Pricing Matrix
Sixty-day resin inventory cycles at German petrochemical hubs concentrate converter pricing power with integrated film extruders while compressing margins for mid-tier operators dependent on spot polyamide and EVOH procurement. This lead-time asymmetry between captive supply and merchant-market sourcing directly shapes tiered margin structures across barrier film procurement for frozen ready-meals.
Pricing Analysis
The customization-premium spread between standard catalog films and configured-to-order coextrusions runs wide in European frozen food packaging, with contract-based long-term offtake dominating volume procurement for Aldi and Lidl buying desks. Price differentiation hinges on EFSA food-contact certification tier and volume scale, with private-label discount channels exhibiting highest sensitivity while premium organic lines absorb cost premiums for carbon-labeled kraft solutions. Pricing pressure stems from REACH SVHC testing backlogs extending qualification timelines beyond brand launch windows. Retail consolidation concentrates specification authority, squeezing standard-tier converters while rewarding early movers in bio-based barriers.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for resin imports from Belgian and German petrochemical complexes, exposing converters to container availability volatility on Asia-Europe trade lanes. Supply concentrates in Germany, Belgium, and the Netherlands for polyamide and EVOH barrier polymers, with converters drawing from these hubs for multi-layer frozen film production. Raw material dependencies center on ethylene feedstocks, specialty coextrusion resins, and bio-wax barrier coatings. Single-source vulnerability clusters with force majeure risk at Rhine-Ruhr industrial corridor facilities. Distribution runs through consolidated retail buying desks and direct-to-freezer e-commerce fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European frozen food packaging operates at a platform-economics inflection where retailer specification platforms and EPR scheme interoperability are displacing bilateral converter relationships with standardized approval pathways.
For Market Incumbents: Secure backward integration into resin compounding to defend margin control as REACH compliance costs concentrate with integrated operators. Capture specification authority through early EFSA food-contact certification for post-consumer recycled content layers before technical ceilings lift. Channel control through localized technical service in Polish and Romanian retail modernization protects against agile digital-native entrants.
For New Entrants and Emerging Players: CE marking fast-track for cellulose nanofiber barriers opens specification authority in Nordic organic private-label lines previously held by incumbent film extruders. Target direct-to-freezer e-commerce subscription services in the United Kingdom and France where fragmented order quantities and compressed minimums favor agile make-to-order capabilities. Go-to-market through ship-ready thermal protection bundles bypasses retail display approval bottlenecks.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EPR scheme alignment and REACH compliance cost concentration will structurally favor scaled operators with captive supply chains over fragmented mid-tier converters. Acquisition target archetype: molded fiber technology leaders with premium sustainable positioning and established private-label relationships. Signal to watch: France's national EPR fee reduction structure expanding to neighboring jurisdictions, accelerating mono-material format adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures margin control as REACH compliance concentrates with integrated operators serving Aldi and Lidl specifications. |
| Cellulose Nanofiber Barrier Certification | Displaces incumbent converter relationships in Nordic retail carbon-labeled private-label frozen meal lines. |
| Direct-to-Freezer E-commerce Capability Buildout | Captures fragmented order volumes from UK and French subscription services bypassing retail case-pack requirements. |
| Localized Technical Service in Poland and Romania | Secures first-mover positioning as discount channel expansion compresses approval timelines in Central European retail. |
| Mono-Material Tray Format Investment | Qualifies for France's EPR fee reductions while anticipating regulatory alignment across EU member states. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with frozen food brand managers, converter procurement leads, retail category buyers, and EFSA regulatory affairs specialists; and secondary validation through EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance registrations, Cefic resin production data, and national EPR scheme disclosures. Bottom-up triangulation across material type, packaging form, and end-user segmentation dimensions anchored volume estimates, while top-down cross-checks against petrochemical capacity data ensured supply-side consistency.
Across the analysis window, the forecasting framework modeled material type splits, packaging form evolution, and country-level retail channel concentration. CAGRs derived from segment-level growth assumptions weighted by EPR scheme implementation timelines and F-Gas Regulation compliance deadlines. Industry-specific inputs included EFSA food-contact approval velocity for recycled content and Nordic retail carbon-labeling penetration curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and stable Rhine-Ruhr petrochemical supply; material deviation in regulatory enforcement intensity or resin force majeure frequency would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot Drinks Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Food Punnets Market
Food Packaging
Egg Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Pizza Box Market
Food Packaging
Drink Carrier and Trays Market