
 Microwaveable Liquid Food Packaging Market | 2026-2036
Microwaveable Liquid Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Microwaveable Liquid Food Packaging Market Analytics
Market Context
The microwaveable liquid food packaging sector is consolidating around a sharp divergence between premium multilayer barrier films and commodity mono-material pouches. Amcor plc leverages its vertical integration in blown film extrusion to sustain margin pools in high-barrier retort structures. Tetra Pak International S.A. anchors its position through aseptic carton expertise adapted for microwaveable formats. Berry Global, Inc. competes aggressively in injection-molded polypropylene cups with integrated venting lids.
Technical Definition and Segment Structure
Microwaveable liquid food packaging denotes engineered containers designed to safely hold aqueous or semi-viscous food products through microwave heating cycles, typically incorporating temperature-resistant polymers, susceptor films, or vented closures rated for 100°C-plus internal pressure. These systems serve the primary commercial purpose of enabling shelf-stable to chilled liquid foods to transition from retail storage to consumption-ready state without vessel transfer. Plastic material types dominate current volume owing to cost scalability and forming flexibility, though paper-based laminates represent the fastest-growing structural category as brands pursue fiber-forward sustainability claims. The 500ml size bracket captures disproportionate margin concentration, aligning with single-serve positioning in convenience retail and food service channels.
Regulatory Frame and Outlook
FDA migration testing under 21 CFR 177 directly shapes polymer selection and additive packages for U.S.-bound microwaveable liquid packaging, while EU REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant barrier coatings. ISO 22000 food safety management certification has become a baseline market access requirement across major export corridors. Stakeholders must monitor evolving state-level extended producer responsibility mandates and decide whether to front-load recyclable mono-material designs or defend incumbent multilayer performance advantages.
Market Dynamics
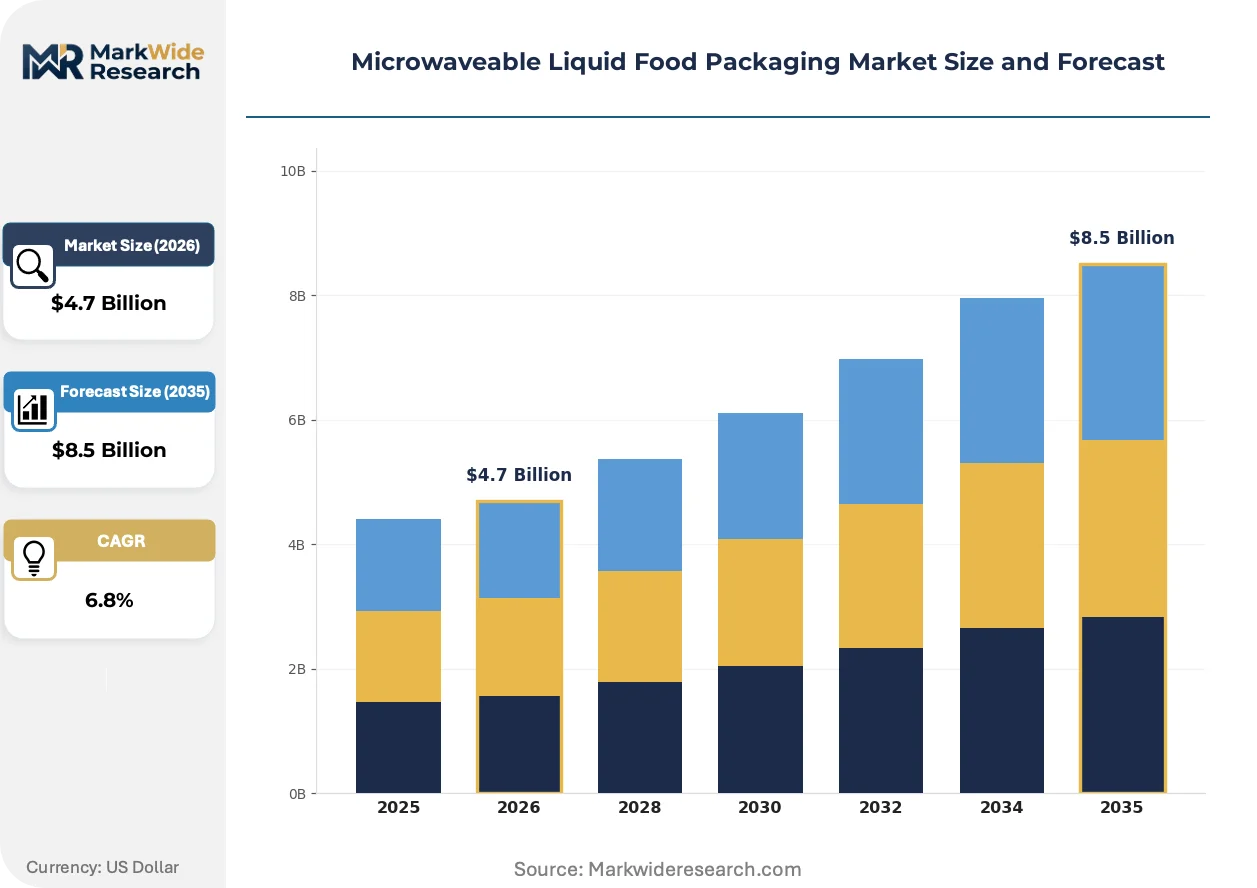
Material substitution pressure is the dominant structural force reshaping microwaveable liquid food packaging, as brand owners accelerate away from multilayer plastics toward fiber-based alternatives to preempt extended producer responsibility liabilities and satisfy retailer sustainability mandates.
Growth Catalysts
- EU REACH restrictions on PFAS:Per- and polyfluoroalkyl substance bans are compelling coating reformulation investments that create first-mover advantages for barrier technology suppliers with compliant aqueous or silicone-based alternatives.
- Single-serve soup brands in the United States:Ready-to-drink and ready-to-heat soup manufacturers are expanding microwaveable pouch lines to capture convenience-oriented household penetration and food service contract wins.
- Susceptor film integration:Metallized polyester susceptor layers enable even heating of viscous liquid foods, expanding addressable applications from thin broths to chowders and cream-based formulations.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:High-barrier EVOH resin production clusters in Japan and Belgium, exposing converters to freight cost volatility and currency fluctuation risks on imported feedstock.
- Migration testing protocol stringency:FDA 21 CFR 177 testing requirements for heated plastics extend development timelines and raise qualification costs for new polymer formulations entering U.S. commerce.
- Retort pouch substitution by aseptic cartons:Tetra Pak's microwaveable carton formats capture shelf-stable soup volume that might otherwise flow to flexible retort pouches, constraining segment expansion.
Strategic Opportunities
- India FSSAI packaged food growth:India's expanding organized retail and quick-service restaurant sectors create virgin demand for microwaveable liquid packaging formats previously absent from domestic supply chains.
- Curbside recyclable mono-material structures:Polypropylene homopolymer pouches with integrated venting zones qualify for existing mechanical recycling streams, unlocking brand owner marketing claims and EPR compliance advantages.
- Digital printing convergence with short-run forming:Narrow-web digital presses paired with compact pouch form-fill-seal lines enable regional brand test marketing and SKU proliferation without cylinder engraving costs.
Industry Challenges
- Migration testing laboratory capacity:FDA-recognized third-party testing facilities face queue backlogs extending qualification timelines for new material submissions, compressing product launch windows.
- Barrier coating application uniformity:Aqueous and bio-based barrier coatings require tighter web tension control and drying energy management than solvent-based predecessors, demanding capital upgrades to legacy coating lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwaveable Liquid Food Packaging Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Paper, Foil Closure Type: Lid, Cap, Snap-On, Straw Size: 200ml, 500ml, 1L, 2L End User: Retail, Food Service, Convenience Stores, Manufacturers |
| Companies Covered | Amcor plc, Sealed Air Corporation, Berry Global, Inc., Mondi Group plc, Tetra Pak International S.A., Sonoco Products Company, WestRock Company, Huhtamaki Oyj, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwaveable Liquid Food Packaging Market Evolving Landscape
Active material science advancement and regulatory chemistry restrictions are converging to redraw competitive boundaries between incumbent multilayer barrier systems and emerging mono-material or fiber-based alternatives.
Paper-based barrier laminates is overtaking conventional plastic pouches in premium soup and sauce applications where fiber-forward sustainability positioning commands retail shelf placement. Nestlé and Campbell Soup Company procurement teams are specifying heat-sealable paper structures with mineral oil barrier properties for North American launches. This material transition is overtaking multilayer plastic volume in the 250-500ml single-serve bracket, compressing margins for converters without paper lamination capability.
EU Green Deal packaging and packaging waste regulation revisions are mandating recyclability-by-design criteria and recycled content minimums for plastic packaging placed on European markets. Industrial consequence includes forced abandonment of non-separable multilayer structures and accelerated investment in compatible adhesive and coating systems. Soup and ready-meal brands exporting to Germany, France, and the Netherlands are responding with packaging redesign commitments announced to retail partners ahead of enforcement deadlines.
Direct-to-food service distribution is displacing traditional broker-mediated channel structures for microwaveable liquid packaging, as institutional buyers consolidate procurement through group purchasing organizations and contract food management companies. Aramark, Compass Group, and Sodexo are centralizing packaging specification authority at corporate headquarters, reducing regional autonomy and compressing supplier counts. This concentration is most visible in the United States, where healthcare and education sector contract wins now hinge on national distribution capability and volume tier pricing rather than local service relationships.
Microwaveable Liquid Food Packaging Market Segmentation
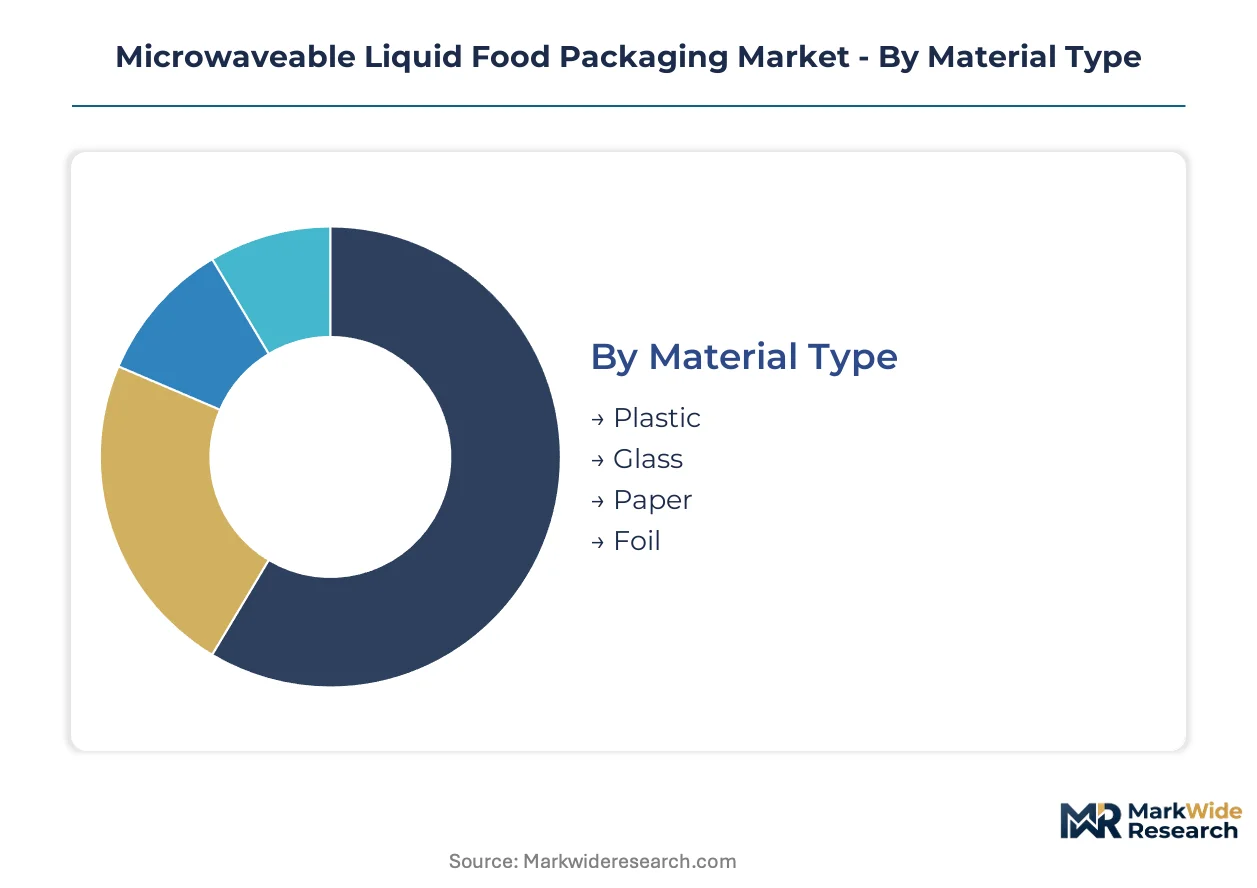
Material selection in microwaveable liquid packaging determines regulatory compliance pathways, with polymer formulations facing distinct FDA migration testing protocols under 21 CFR 177 versus paper-based alternatives subject to fiber safety standards. Closure engineering and size specification further segment the market by heating performance requirements and channel-specific logistics constraints.
Material Type:
FDA 21 CFR 177 compliance burdens fall heaviest on plastic formulations requiring extensive migration testing for heated contact, while paper and foil laminates navigate fiber safety and coating migration standards through separate regulatory tracks.
- Plastic:Polypropylene homopolymer and multilayer EVOH-barrier structures dominate current volume through cost scalability and forming flexibility. FDA migration testing timelines for new polymer additives extend development cycles, favoring incumbent suppliers with pre-qualified material libraries.
- Paper:Heat-sealable fiber-based laminates with mineral oil barrier properties are gaining share in premium soup applications where Nestlé and Campbell Soup Company procurement teams specify sustainability-forward structures. EU Green Deal packaging waste regulations are accelerating brand owner shifts away from non-recyclable multilayer plastics.
- Glass:Borosilicate and tempered soda-lime containers serve niche premium positioning with superior microwave transparency but carry freight cost penalties and breakage risk that limit food service penetration.
- Foil:Aluminum-laminated retort pouches deliver oxygen and light barrier performance for extended shelf-stable applications, though recyclability challenges constrain adoption under tightening extended producer responsibility frameworks.
Plastic sits at the top of the volume ranking, with paper climbing the fastest.
Closure Type:
Closure engineering separates segments by pressure management sophistication, with vented lid systems commanding premium positioning against commodity cap formats in high-viscosity applications.
- Lid:Integrated venting membranes and steam-release channels enable safe heating of viscous liquid foods without vessel transfer, expanding addressable applications from thin broths to chowders and cream-based formulations.
- Cap:Screw-thread and tamper-evident closures dominate shelf-stable beverage applications where resealability extends consumption occasions, though thread engagement reliability under thermal cycling remains a qualification hurdle.
- Snap-On:Press-fit polypropylene closures offer lowest unit cost for single-serve formats with immediate consumption positioning, common in convenience store channels.
- Straw:Pierceable foil membranes with attached flexible straws serve ready-to-drink soup and beverage segments where on-the-go consumption drives format selection.
Lid formats generate the highest margin concentration, with straw-integrated designs expanding most quickly in convenience retail.
Size:
Size segmentation aligns with channel economics and consumption occasion mapping, with single-serve brackets capturing disproportionate margin concentration relative to bulk formats.
- 500ml:The single-serve sweet spot captures premium positioning in convenience retail and food service channels, matching household penetration targets for ready-to-drink soup brands scaling microwaveable pouch adoption across the United States.
- 200ml:Compact portion formats serve healthcare and education sector contracts through Aramark, Compass Group, and Sodexo procurement consolidation, where portion control and waste reduction drive specification.
- 1L:Multi-serve containers address family consumption and food service back-of-house preparation, though vessel transfer requirements reduce microwaveable format advantage.
- 2L:Bulk formats concentrate in club retail and institutional procurement with lowest per-ounce packaging cost, minimal microwaveable-specific engineering investment.
500ml commands the revenue concentration peak, with 200ml gaining share fastest through healthcare and education contract wins.
End User:
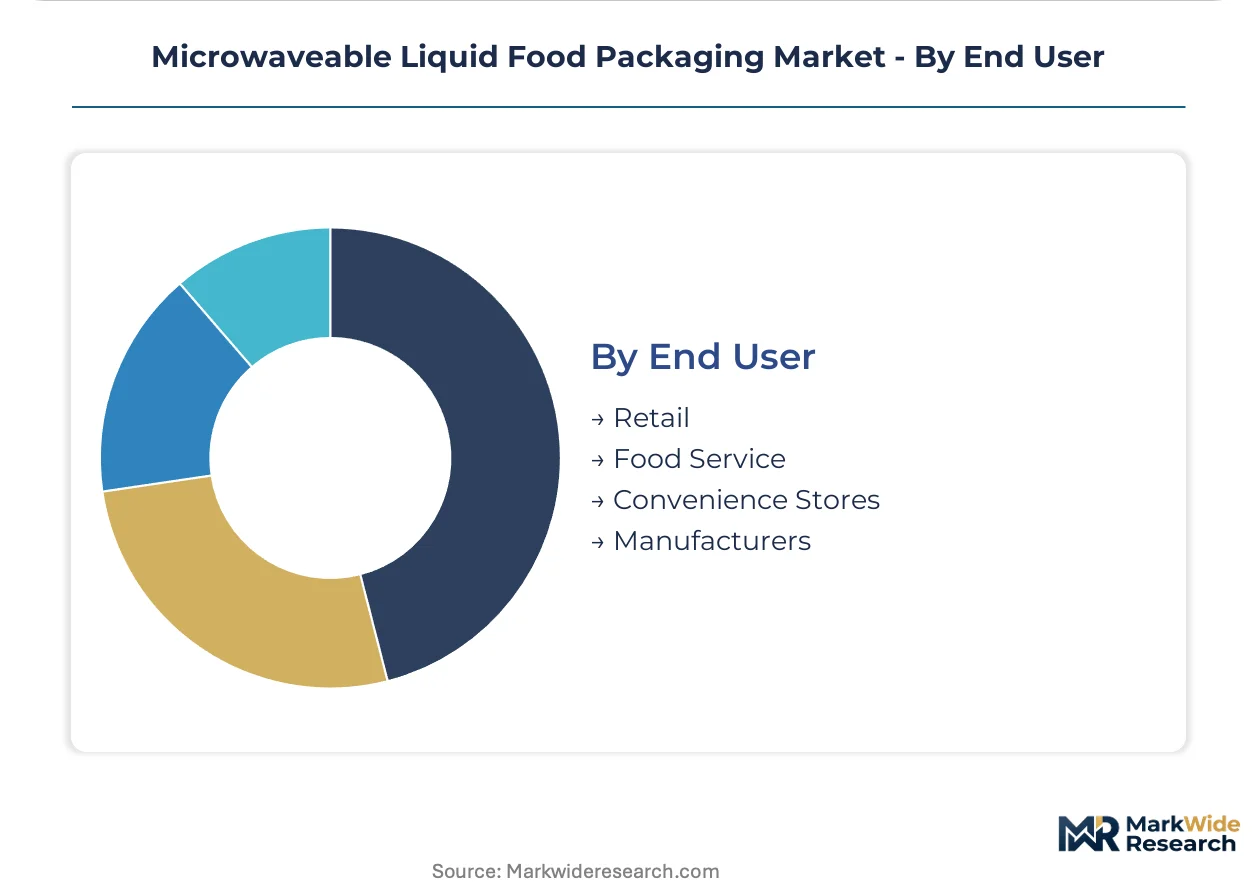
End user segmentation reflects diverging procurement authority structures, with food service consolidation through group purchasing organizations compressing supplier counts versus fragmented retail brand ownership.
- Retail:Branded consumer packaged goods companies drive format innovation through sustainability marketing claims and shelf differentiation, with paper-based barrier laminates overtaking plastic in premium soup launches.
- Food Service:Contract food management companies centralize packaging specification authority at corporate headquarters, reducing regional autonomy and demanding national distribution capability with volume tier pricing.
- Convenience Stores:Immediate consumption channels prioritize grab-and-go functionality with straw-integrated or sip-friendly closures, price sensitivity constraining premium material adoption.
- Manufacturers:Private label and co-manufacturing relationships require flexible production lines capable of short-run SKU proliferation without cylinder engraving costs.
Food service delivers the steepest expansion trajectory, with retail maintaining volume leadership through brand owner format diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineering talent clusters in the United States, Germany, and Japan anchor regional innovation capacity for microwaveable liquid food formats.
United States
Single-serve soup brands and ready-to-drink beverage manufacturers drive pouch adoption across convenience retail and food service channels. FDA 21 CFR 177 migration testing protocols tighten material specifications for heated plastics entering interstate commerce. Chicago and Minneapolis-St. Paul host converter clusters supplying Aramark, Compass Group, and Sodexo procurement networks.
Germany
EU Green Deal packaging waste regulations mandate recyclability-by-design criteria for plastic packaging placed on German markets. ECHA REACH restrictions on per- and polyfluoroalkyl substances force barrier coating reformulation across converter operations. The Düsseldorf-Cologne corridor concentrates flexible packaging R&D facilities developing aqueous barrier alternatives.
Japan
High-barrier EVOH resin production concentrates in domestic petrochemical complexes serving Asian converter demand. METI circular economy guidelines promote mono-material structures compatible with existing mechanical recycling infrastructure. Osaka and Nagoya anchor blown film extrusion clusters supplying retort pouch converters.
India
FSSAI packaged food growth and quick-service restaurant expansion create virgin demand for microwaveable liquid formats previously absent from domestic supply chains. BIS certification requirements for food-contact materials shape import substitution strategies. Mumbai-Pune and Delhi-NCR industrial corridors attract multinational converter joint ventures targeting institutional food service procurement.
China
Dual carbon goals and SAMR packaging waste regulations accelerate brand owner shifts toward fiber-based alternatives and recyclable mono-material designs. Yangtze River Delta converter clusters supply both domestic ready-meal brands and export-oriented soup manufacturers. Shanghai and Suzhou host pilot lines for paper-based barrier laminates with heat-seal functionality.
Microwaveable Liquid Food Packaging Market Competitive Landscape
Capital-heavy converters with captive film extrusion assets compete with asset-light packaging designers outsourcing forming and printing operations. The market structure consolidates around three strategic archetypes: vertically integrated multinationals controlling resin-to-pouch supply chains, regional specialists in paper-based barrier laminates, and private-label converters serving food service procurement consolidation. Dominant competitive moves include backward integration into blown film extrusion and strategic partnerships with susceptor film suppliers.
Within the integrated multinational tier, Amcor plc and Berry Global, Inc. exemplify scale-driven positioning through upstream control over polymer formulation and barrier layer engineering. Tetra Pak International S.A. occupies a distinct position anchored in aseptic carton expertise adapted for microwaveable formats, representing the fiber-based alternative archetype against incumbent plastic pouch systems.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Berry Global, Inc. |
| Mondi Group plc |
| Tetra Pak International S.A. |
| Sonoco Products Company |
| WestRock Company |
| Huhtamaki Oyj |
| Smurfit Kappa Group |
| Others |
Value Network & Pricing Analysis
A sharp performance gap between multilayer barrier films and commodity mono-material pouches manifests in divergent pricing power and sourcing configurations across the microwaveable liquid food packaging sector. Premium converters with captive EVOH extrusion assets command sustained margin pools in retort-grade structures, while commodity suppliers face relentless cost compression from brand owner sustainability mandates and food service procurement consolidation.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes pricing models across the market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by barrier performance certification and FDA pre-qualification status. Price differentiation stems from migration testing completion timelines and susceptor film integration complexity. Pricing pressure stems from EU REACH-driven coating reformulation costs that converters struggle to pass through. Food service buyers at Aramark and Compass Group exhibit highest price sensitivity through volume-tier negotiations, while premium retail brands tolerate premium positioning for fiber-forward sustainability claims.
Supply Chain Analysis
Reverse-logistics flows for recyclable mono-material structures remain underdeveloped, constraining closed-loop claims and EPR compliance verification. Raw material supply concentrates in the United States, Germany, and Japan, with EVOH resin production clustering in Japanese and Belgian petrochemical complexes. Feedstock dependencies include high-barrier copolymers, metallized polyester susceptor films, and aqueous barrier coatings. Single-source vulnerability around EVOH imports exposes converters to freight cost volatility and currency fluctuation. Distribution runs through converter-direct relationships with multinational brand owners and food service procurement networks, bypassing traditional broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The microwaveable liquid food packaging market reads as a late-cycle quality story, justified by the decisive demand shift toward heat-sealable paper structures with mineral oil barrier properties in premium soup applications.
For Market Incumbents: To counter Tetra Pak's aseptic carton encroachment on retort pouch volume, Amcor and Berry Global must accelerate backward integration into blown film extrusion for barrier layer control and pre-qualify polymer additive libraries under FDA 21 CFR 177 to compress competitor development timelines. Channel control through direct food service contracts with consolidated procurement at Sodexo and Compass Group represents the critical defensive lever. For New Entrants and Emerging Players: Enter via India's FSSAI-regulated packaged food expansion, where virgin demand for microwaveable formats outpaces domestic converter capability and multinational joint ventures in Mumbai-Pune corridor offer partnership pathways. The most penetrable segment lies in 200ml healthcare and education portions where Aramark procurement consolidation has yet to lock in incumbent supply. A narrow-web digital printing angle enables regional brand test marketing without cylinder engraving capital. For Investors and Strategic Acquirers: Consolidation pressure builds where paper lamination capability scarcity meets EU Green Deal recyclability mandates, forcing brand owner redesign commitments ahead of enforcement deadlines. Long-term viability favors converters with dual plastic-and-paper platform flexibility across the analysis window. The signal to watch is FDA-recognized third-party testing facility queue backlogs, which compress product launch windows and advantage incumbents with pre-qualified material libraries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blown Film Extrusion | Captive EVOH barrier production secures margin pools against resin import volatility. |
| Paper-Based Barrier Laminate Capacity Addition | Nestlé and Campbell procurement specifications favor fiber-forward sustainability positioning. |
| FDA Migration Testing Pre-Qualification Program | Pre-cleared additive libraries compress competitor development timelines under 21 CFR 177. |
| Food Service Procurement Consolidation Partnership | Direct contracts with Compass Group and Sodexo bypass broker-mediated channel structures. |
| Susceptor Film Supplier Strategic Alliance | Metallized polyester integration enables even heating of viscous chowder and cream formulations. |
Research Methodology
Direct dialogue with packaging engineers at converter operations, procurement directors at soup and beverage brand owners, food service specification managers at contract management companies, and regulatory affairs leads at FDA-recognized testing facilities grounded qualitative findings. Secondary validation drew from FDA 21 CFR 177 submission databases, EU ECHA REACH restriction updates, FSSAI packaged food growth statistics, and SEC filings of publicly traded packaging multinationals. Bottom-up volume modeling triangulated against top-down category spend estimates.
Segment-level projections across material type, closure configuration, size bracket, and end-user channel fed into an analytical framework spanning the projection horizon. CAGRs derived from regression against historical adoption curves of comparable format transitions, with specific inputs including EVOH resin trade flow data and digital printing equipment installation rates at narrow-web converters.
The model holds under stable regulatory enforcement timelines and sustained food service procurement consolidation; deviation in FDA testing facility capacity expansion or EU packaging waste regulation acceleration would shift volume trajectories. Practitioners should monitor EVOH supply chain disruption indicators and state-level extended producer responsibility enactment for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food and Drink Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Fresh Produce Trays Market