
 Processed Meat Packaging Market | 2026-2036
Processed Meat Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Processed Meat Packaging Market Analytics
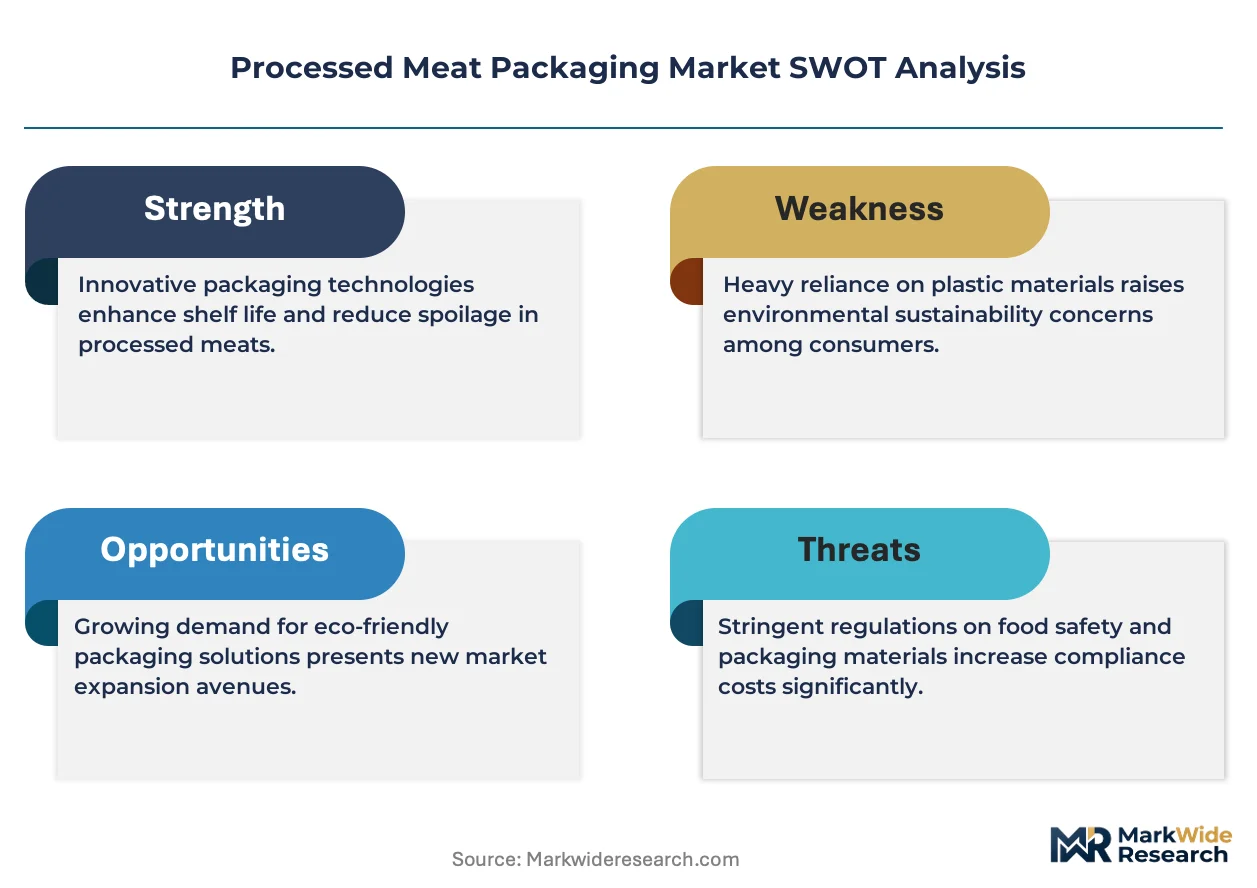
REACH compliance is hardening the cost-of-entry calculus for processed meat packaging suppliers entering European markets. Amcor plc leverages its integrated film manufacturing footprint to sustain margin control across vacuum and modified atmosphere formats. Sealed Air Corporation anchors its position through proprietary barrier technologies that extend shelf-life performance for chilled distribution networks. Mondi Group competes with fiber-based tray solutions that navigate emerging restrictions on single-use plastics in food contact applications.
Processed meat packaging encompasses barrier films, trays, casings, and closure systems engineered to exclude oxygen, retain moisture, and maintain thermal stability across chilled, frozen, and ambient supply chains. These systems typically deploy multi-layer coextruded structures with ethylene vinyl alcohol or polyamide cores achieving oxygen transmission rates below 1 cc per square meter per day to prevent lipid oxidation and microbial proliferation in cured and emulsified meat products. Modified atmosphere packaging now leads value contribution as nitrogen and carbon dioxide flush systems displace passive vacuum formats in premium retail segments. Compostable materials represent the fastest-growing material category, though performance gaps in moisture barrier and seal integrity constrain penetration in high-fat processed meat applications where plastic and metal still dominate margin pools.
The FDA governs indirect food additive migration limits under 21 CFR while the USDA enforces labeling and inspection standards for packaged meat products in the United States; in Europe, EFSA evaluates migration thresholds and ECHA administers REACH substance restrictions that directly shape laminate composition decisions. These frameworks collectively elevate testing burdens and reformulation costs, particularly for suppliers managing dual-continent qualification protocols. Stakeholders must monitor evolving state-level extended producer responsibility laws and bioplastics certification schemes to anticipate material substitution timelines and avoid stranded inventory positions.
Market Dynamics
REACH substance restrictions and the EU F-Gas Regulation are forcing laminate reformulation across European supply chains while supermarket private-label expansion concentrates purchasing power among fewer retail buyers.
Growth Catalysts
- EU Green Deal compliance mandates:Packaging producers serving Germany, France, and Italy must demonstrate circular material content, creating qualified supplier scarcity that rewards early reformulators with multi-year retail contracts.
- Modified atmosphere technology:Nitrogen and carbon dioxide flush systems now dominate premium chilled distribution, displacing passive vacuum formats as retailers demand extended shelf-life without synthetic preservatives.
- Centralized meat processing clusters:Germany's concentration of industrial slaughtering and curing facilities generates packaging standardization demand that reduces SKU complexity for film converters.
Market Restraints
- Ethylene vinyl alcohol resin supply concentration:Asian petrochemical producers control over 70% of high-barrier EVOH supply, exposing European converters to freight cost volatility and currency hedging complexity.
- Compostable performance gaps:Polylactic acid and cellulose-based structures fail moisture barrier tests in high-fat sausage applications, forcing continued reliance on fossil-derived multilayer films.
- Dual-continent qualification costs:Suppliers must simultaneously satisfy FDA 21 CFR migration limits and EFSA thresholds, doubling testing budgets for export-oriented producers.
Strategic Opportunities
- Extended producer responsibility tailwinds:France's AGEC law and Italy's plastic tax create price advantages for fiber-based tray suppliers over conventional plastic converters.
- Smart packaging convergence:Integration of time-temperature indicators with RFID-enabled logistics tracking opens premium positioning for cold-chain-verified processed meat exports.
- E-commerce chilled fulfillment:Direct-to-consumer subscription meat boxes require insulated barrier formats that withstand last-mile temperature excursions, a channel still lacking optimized packaging solutions.
Industry Challenges
- Multilayer delamination expertise shortage:Few polymer engineers possess combined knowledge of adhesive tie-layer chemistry and high-speed form-fill-seal line optimization.
- Compostable certification timeline compression:TÜV Austria and BPI industrial composting approvals require 18-24 month validation cycles that lag behind retailer sustainability commitments.
- Legacy vacuum chamber retrofit costs:Converting established thermoforming lines for modified atmosphere operation demands capital outlays that mid-size processors defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Processed Meat Packaging Market |
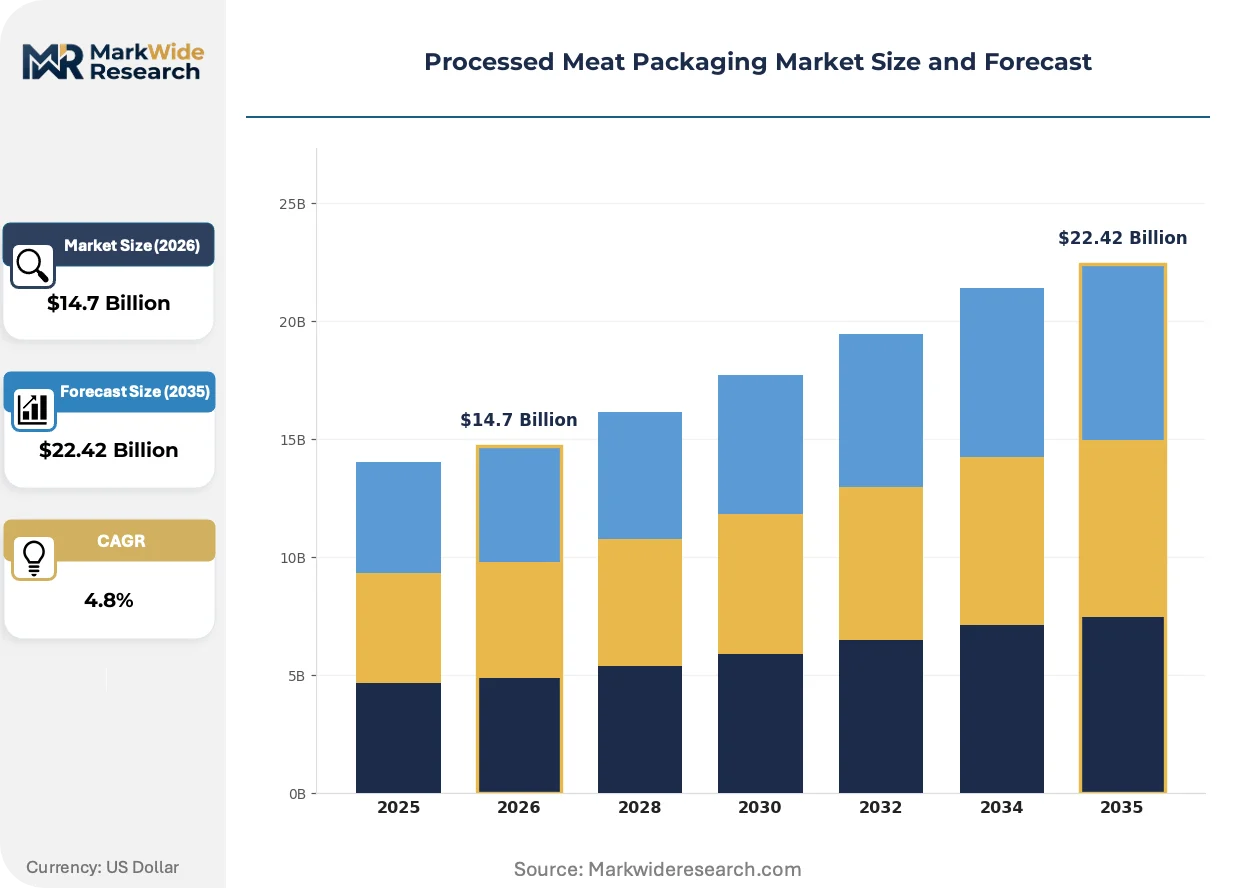
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Vacuum Packaging, Modified Atmosphere Packaging, Skin Packaging, Tray Sealing Material: Plastic, Metal, Paper, Compostable Materials End User: Retail, Food Service, Online Delivery, Supermarket Fill Type: Chilled, Frozen, Ambient, Ready-to-Eat |
| Companies Covered | Amcor plc, Berry Global, Sealed Air Corporation, Mondi Group, Winpak Ltd., Tetra Pak International S.A., Silgan Holdings, International Paper Inc., Novipax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Processed Meat Packaging Market Evolving Landscape
Active and intelligent packaging systems are displacing passive barrier formats as retailers demand real-time supply chain visibility and consumers expect longer unopened shelf life without chemical preservatives.
High-barrier coextruded films with ethylene vinyl alcohol cores are consolidating market share in premium processed meat segments. Major retail chains in Germany and the Netherlands now specify oxygen transmission rates below 0.5 cc per square meter per day for their private-label cured meat lines. This performance threshold is consolidating supplier tiers, forcing smaller converters to exit or partner with resin distributors holding exclusive EVOH supply agreements.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling fluoropolymer replacement in grease-resistant paper applications. ECHA's 2023 PFAS restriction proposal forces immediate reformulation of sausage overwrap papers used across Danish and Dutch export markets. Fiber-based tray producers are responding with bio-wax and clay coating alternatives that sacrifice some heat-seal performance.
Supermarket buyers now mandate packaging data transparency through digital product passports. French and Belgian retailers require blockchain-tracked material provenance for processed meat packaging by 2026. This behavioral shift compresses supplier qualification cycles and favors integrated film manufacturers with captive resin production over merchant converters dependent on spot polymer purchases.
Processed Meat Packaging Market Segmentation
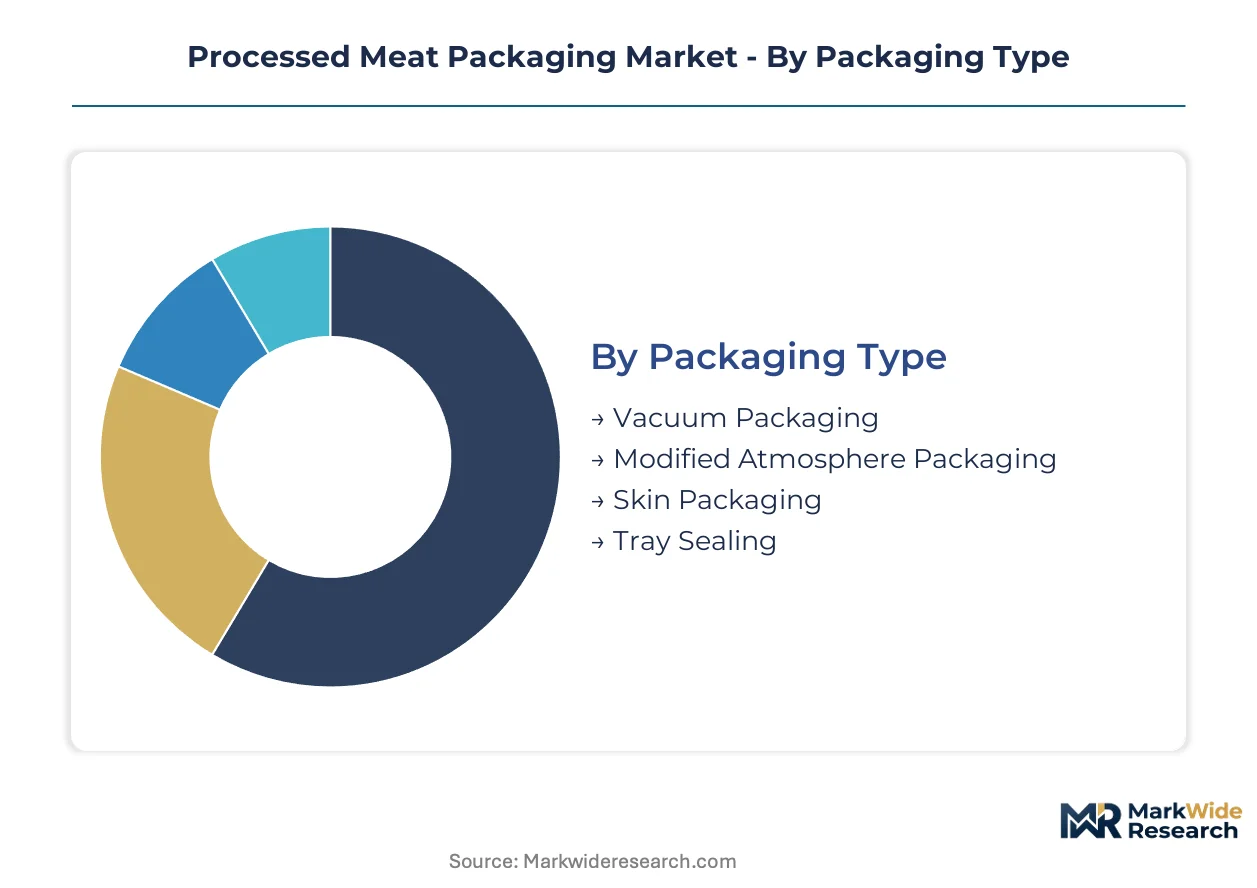
Segmentation in processed meat packaging reveals how shelf-life requirements, regulatory pressure on materials, and channel-specific logistics reshape procurement patterns. Buyers now specify performance thresholds that cross-cut multiple categories simultaneously.
Packaging Type:
Standardization dominates high-volume lines while premium chilled applications demand customized gas-flush configurations and proprietary barrier specifications.
- Vacuum Packaging:Multi-layer coextruded films with polyamide or EVOH cores achieve oxygen transmission rates below 1 cc per square meter per day. German centralized meat processing clusters drive standardization demand that reduces SKU complexity for film converters supplying private-label cured meat lines.
- Modified Atmosphere Packaging:Nitrogen and carbon dioxide flush systems displace passive vacuum formats in premium retail segments. French and Belgian retailers now mandate oxygen transmission rates below 0.5 cc per square meter per day for private-label cured meat, consolidating supplier tiers.
- Skin Packaging:Tight-film adhesion eliminates headspace oxygen exposure for high-value sliced deli products.
- Tray Sealing:Thermoformed bases with lidding films dominate economy-tier sausage and frankfurter applications.
Most installed capacity flows through vacuum packaging. Expansion is steepest in modified atmosphere packaging.
Material:
Cost tiers separate fossil-derived multilayer structures from emerging bio-based alternatives facing performance validation gaps.
- Plastic:Ethylene vinyl alcohol and polyamide cores in coextruded laminates deliver sub-1 cc oxygen barrier performance. Asian petrochemical producers control over 70% of high-barrier EVOH supply, exposing European converters to freight cost volatility.
- Compostable Materials:Polylactic acid and cellulose-based structures represent the fastest-growing material category. Moisture barrier failures in high-fat sausage applications force continued reliance on fossil-derived films where plastic still dominates margin pools.
- Metal:Aluminum casings and foils retain dominance in ambient-stable canned meat and retort pouch applications.
- Paper:Fiber-based trays navigate emerging EU single-use plastic restrictions, though clay and bio-wax coatings sacrifice heat-seal performance versus fluoropolymer predecessors.
Plastic retains the broadest installed base. Compostable materials are gaining share fastest among sustainability-mandated retail contracts.
End User:
Volume concentration sits with centralized retail procurement while direct-to-consumer channels fragment order patterns.
- Retail:Supermarket private-label expansion concentrates purchasing power among fewer buyers specifying circular material content and blockchain-tracked provenance.
- Supermarket:Dedicated private-label lines demand packaging standardization across national distribution networks, favoring suppliers with multi-site manufacturing footprints.
- Online Delivery:Direct-to-consumer subscription meat boxes require insulated barrier formats that withstand last-mile temperature excursions, a channel still lacking optimized packaging solutions.
- Food Service:Bulk portion packs for institutional catering prioritize cost efficiency over extended shelf-life performance.
Retail channels absorb the highest packaging volumes. Online delivery shows the steepest expansion trajectory as chilled fulfillment infrastructure matures.
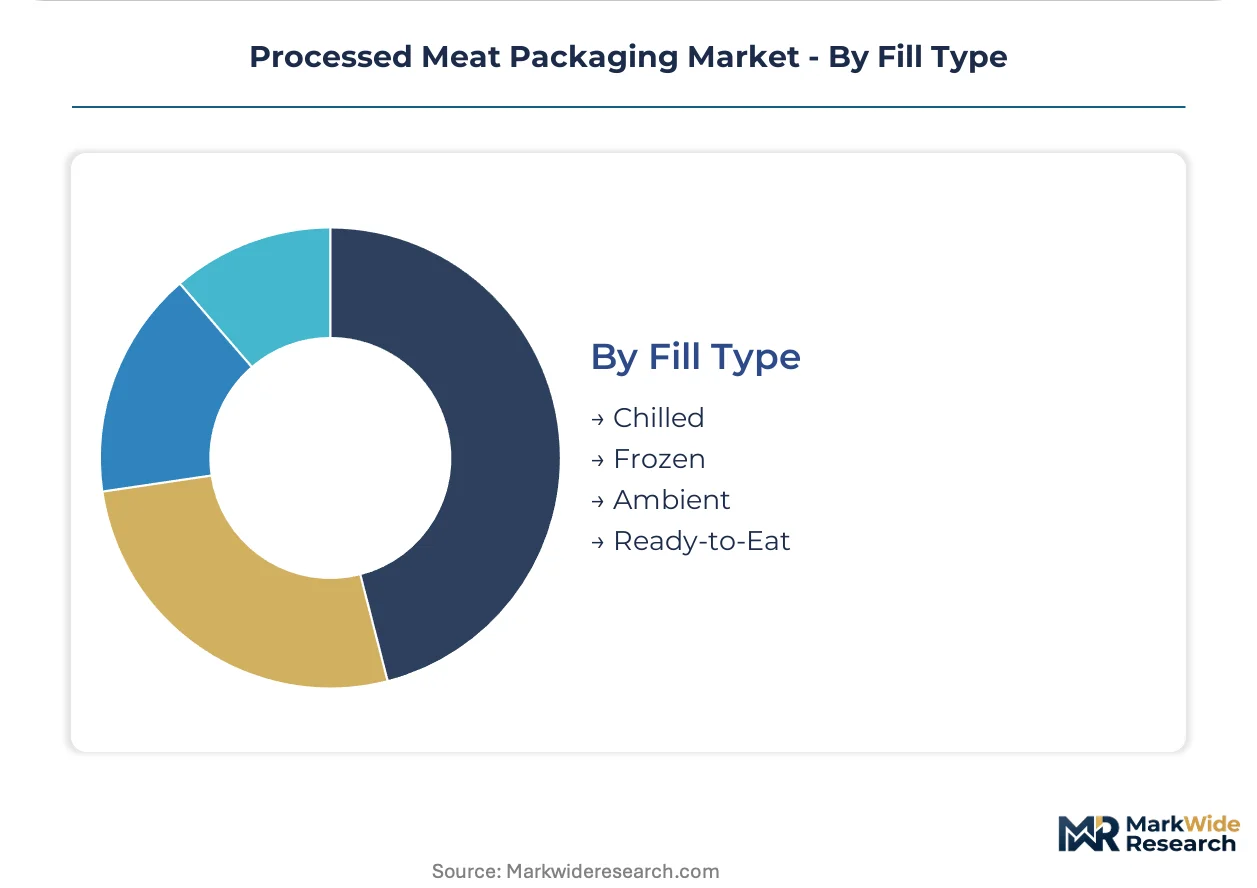
Fill Type:
Application temperature determines barrier specifications, with chilled distribution imposing the most stringent oxygen and moisture control requirements.
- Chilled:Modified atmosphere and vacuum formats with sub-0.5 cc oxygen transmission rates prevent lipid oxidation in cured and emulsified meat products distributed through premium retail networks.
- Ready-to-Eat:High-barrier laminates with integrated time-temperature indicators support cold-chain-verified positioning for convenience-oriented processed meat products.
- Frozen:Simplified barrier specifications focus on moisture retention and puncture resistance rather than oxygen exclusion.
- Ambient:Retort and aseptic formats accommodate shelf-stable canned meat and long-life sausage applications with metal-dominant packaging.
Chilled fill types command the most sophisticated packaging specifications. Ready-to-eat applications are climbing the fastest as convenience demand reshapes retail assortment planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer engineering talent concentrates in Germany's Ruhr industrial corridor and Switzerland's chemical manufacturing belt, anchoring Europe's barrier film innovation pipeline. These workforce clusters sustain the technical depth required for EVOH laminate development and modified atmosphere system integration.
Germany
Centralized meat processing clusters in Lower Saxony and North Rhine-Westphalia drive packaging standardization demand for private-label cured meat lines. The EU F-Gas Regulation forces laminate reformulation across German supply chains, elevating compliance costs for imported films. The Frankfurt-Rhine-Main logistics hub anchors chilled distribution networks requiring sub-0.5 cc oxygen transmission specifications.
France
Supermarket private-label expansion concentrates purchasing power among Carrefour and E.Leclerc procurement teams mandating circular material content. France's AGEC law creates price advantages for fiber-based tray suppliers through extended producer responsibility fees on conventional plastics. The Paris Basin food manufacturing corridor generates demand for blockchain-tracked packaging provenance systems.
United States
Retail channel consolidation at Walmart and Kroger standardizes packaging specifications across national distribution networks. FDA 21 CFR migration limits and USDA inspection standards elevate testing burdens for dual-continent suppliers. The Chicago-Joliet-Naperville meatpacking corridor anchors vacuum and modified atmosphere format demand for processed pork and beef exports.
Netherlands
Dutch export-oriented meat processors drive premium chilled packaging specifications for German and Belgian retail destinations. ECHA REACH Annex XVII restrictions on PFAS compounds force immediate reformulation of grease-resistant sausage overwrap papers. The Eindhoven-Tilburg polymer technology cluster supplies adhesive tie-layer chemistry expertise to regional film converters.
China
Asian petrochemical producers control over 70% of high-barrier EVOH resin supply, exposing European converters to freight cost volatility and currency hedging complexity. SAMR food contact material standards and GB migration limits shape laminate composition for export-oriented processors. The Yangtze River Delta chemical manufacturing belt anchors domestic barrier film production scaling.
Processed Meat Packaging Market Competitive Landscape
The competitive structure tilts toward integrated film manufacturers with captive resin production and proprietary barrier technology portfolios. Tiered supplier consolidation is accelerating as supermarket private-label expansion concentrates purchasing power among fewer retail buyers. Two strategic archetypes dominate: multinational packaging conglomerates with multi-site manufacturing footprints, and specialized converters holding exclusive EVOH supply agreements. Dominant competitive moves include backward integration into polymer compounding operations and strategic partnerships with meat processors for co-developed modified atmosphere configurations.
Among integrated packaging conglomerates, Amcor plc and Sealed Air Corporation exemplify the scale-driven archetype with multi-continent manufacturing presence. Mondi Group occupies a position within the fiber-based alternative tier, navigating emerging EU single-use plastic restrictions through tray solutions. These three companies anchor the supplier landscape that German and French retailers increasingly qualify for multi-year circular material contracts.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Sealed Air Corporation |
| Mondi Group |
| Winpak Ltd. |
| Tetra Pak International S.A. |
| Silgan Holdings |
| International Paper Inc. |
| Novipax |
| Others |
Value Network & Pricing Analysis
Backward integration into captive ethylene vinyl alcohol resin production anchors both supply security and pricing power for European film converters facing Asian petrochemical supply concentration. This structural choice separates margin-sustainable integrated manufacturers from merchant converters exposed to spot polymer volatility and currency hedging complexity.
Pricing Analysis
Bundled modified atmosphere system sales versus unbundled film-only supply splits the pricing architecture across German and French retail procurement. Three-tier pricing structure across premium, standard, and economy levels separates gas-flush configurations with sub-0.5 cc oxygen barriers from basic vacuum formats and commodity tray-sealed products. Certification tier under EFSA migration thresholds and REACH Annex XVII compliance status drives price differentiation within each tier. Pricing pressure stems from supermarket private-label expansion concentrating buyer power among fewer procurement teams. Economy-tier sausage and frankfurter applications show highest price sensitivity, while premium chilled cured meat lines tolerate cost premiums for extended shelf-life performance.
Supply Chain Analysis
Regional distribution centers in the Frankfurt-Rhine-Main corridor and Paris Basin food manufacturing belt anchor hub-and-spoke chilled fulfillment networks for processed meat packaging. Geographic supply concentration centers on Germany for polymer engineering talent and film converting capacity, China and South Korea for high-barrier EVOH resin production, and the Netherlands for adhesive tie-layer chemistry expertise. Raw material dependencies rest on ethylene vinyl alcohol copolymers, polyamide resins, and bio-wax coating formulations for fiber-based alternatives. Single-source vulnerability to Asian EVOH supply exposes European converters to freight cost volatility and currency hedging complexity. Distribution runs through centralized meat processing clusters in Lower Saxony and North Rhine-Westphalia that standardize packaging specifications across private-label networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Processed meat packaging has shifted into a late-cycle quality story as French and Belgian retailers mandate oxygen transmission rates below 0.5 cc per square meter per day for private-label cured meat lines, consolidating supplier tiers around technical performance leaders.
For Market Incumbents: Extend barrier technology leadership through proprietary modified atmosphere configurations that lock in multi-year retail contracts with Carrefour and E.Leclerc procurement teams. Deepen backward integration into polymer compounding operations to neutralize Asian EVOH supply concentration risks. Invest in TÜV Austria and BPI industrial composting certification pipelines to capture France's AGEC law extended producer responsibility tailwinds before 18-24 month validation cycles lag retailer sustainability commitments.
For New Entrants and Emerging Players: Begin with direct-to-consumer subscription meat box channels where insulated barrier formats for last-mile temperature excursions remain underdeveloped and lack optimized packaging solutions. Target e-commerce chilled fulfillment as the most penetrable segment, bypassing consolidated supermarket procurement gatekeepers. Pursue co-development partnerships with regional meat processors for RFID-enabled logistics tracking integration that opens premium cold-chain-verified positioning.
For Investors and Strategic Acquirers: Roll-up economics work for specialized converters holding exclusive EVOH supply agreements because supermarket private-label expansion concentrates purchasing power among fewer buyers seeking qualified suppliers with circular material content credentials. The five-to-ten year viability window favors acquisition of fiber-based tray specialists navigating EU single-use plastic restrictions through Mondi Group-competing solutions. Watch blockchain-tracked packaging provenance mandates as the signal to monitor for inflection timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive EVOH supply neutralizes Asian petrochemical concentration and freight volatility exposure. |
| Modified Atmosphere Technology Licensing | Nitrogen-carbon dioxide flush systems displace passive vacuum formats in premium retail segments. |
| Compostable Certification Pipeline Investment | TÜV Austria and BPI approvals capture France AGEC law extended producer responsibility advantages. |
| Smart Packaging Convergence Partnership | Time-temperature indicator integration with RFID tracking opens cold-chain-verified export positioning. |
| Fiber-Based Tray Capacity Expansion | Clay and bio-wax coated alternatives navigate REACH Annex XVII PFAS restrictions on grease-resistant papers. |
Research Methodology
Direct dialogue with film converter plant managers, supermarket private-label procurement directors, meat processor technical packaging leads, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from customs and trade data for polymer resin flows, SEC 10-K filings of integrated packaging conglomerates, EU F-Gas Regulation implementation guidance, and TÜV Austria industrial composting certification databases. Bottom-up and top-down triangulation cross-checked volume assumptions against capacity utilization rates at centralized meat processing clusters.
Bottom-up segment modeling across packaging type, material composition, fill temperature requirements, and end-user channel structure anchored the analytical framework. The projection horizon spans vacuum packaging standardization in German processing clusters, modified atmosphere displacement trajectories in premium chilled segments, and compostable material penetration constraints in high-fat sausage applications. CAGRs derived from segment-level volume build-ups incorporating EVOH supply concentration effects and REACH compliance cost pass-through assumptions. Forecast inputs included retailer sustainability mandate timelines and extended producer responsibility fee structures.
Caveats apply where ECHA PFAS restriction implementation timing, Asian petrochemical supply disruptions, or supermarket private-label consolidation pace could materially shift the outlook. Forecasts reflect documented assumptions around laminate reformulation cost curves and circular material content qualification cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Bamboo Plate Market
Food Packaging
Honey Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Food Tub Packaging Market