
 PTP Aluminum Foil Market | 2026-2036
PTP Aluminum Foil Market Size, Share, and Industry Trends Forecast 2026-2036
PTP Aluminum Foil Market Analytics
Europe's MDR is pivoting the cost-of-entry calculus for PTP aluminum foil suppliers serving pharmaceutical blister packs. Toyo Aluminium leverages captive rolling capacity in Japan to sustain premium-grade supply for EU-certified drug packaging. Amcor dominates multi-layer lidding formats across North American and European pharmaceutical accounts. Sichuan Huili Industry anchors cost-competitive 45-micron and 60-micron output for emerging-market generic drug makers.
Push-through packaging aluminum foil consists of cold-rolled aluminum alloy strip, typically 20-30 micrometers thick, heat-seal coated with vinyl or polyester lacquer to bond with PVC or PVDC blister cavities. Its primary purpose is to provide child-resistant, senior-friendly barrier protection for unit-dose pharmaceuticals against moisture, oxygen, and light ingress. Blister foil occupies the largest volume share as oral solid dosage remains the dominant drug delivery form globally. Lidding foil generates premium margins where high-barrier coatings and printability specifications apply. Form-fill-seal formats are gaining traction in food and cosmetics applications where automation and line speed override pharmaceutical-grade certification costs.
FDA's drug packaging guidelines, the EU's MDR, and China's NMPA registration requirements collectively shape material traceability, coating chemistry approvals, and migration limit testing for PTP foil suppliers. REACH compliance in Europe and evolving GB standards in China are forcing reformulation of heat-seal lacquers and pinhole density thresholds. Stakeholders must monitor regulatory divergence between major pharmaceutical markets to avoid stranded inventory and certification gaps.
Market Dynamics
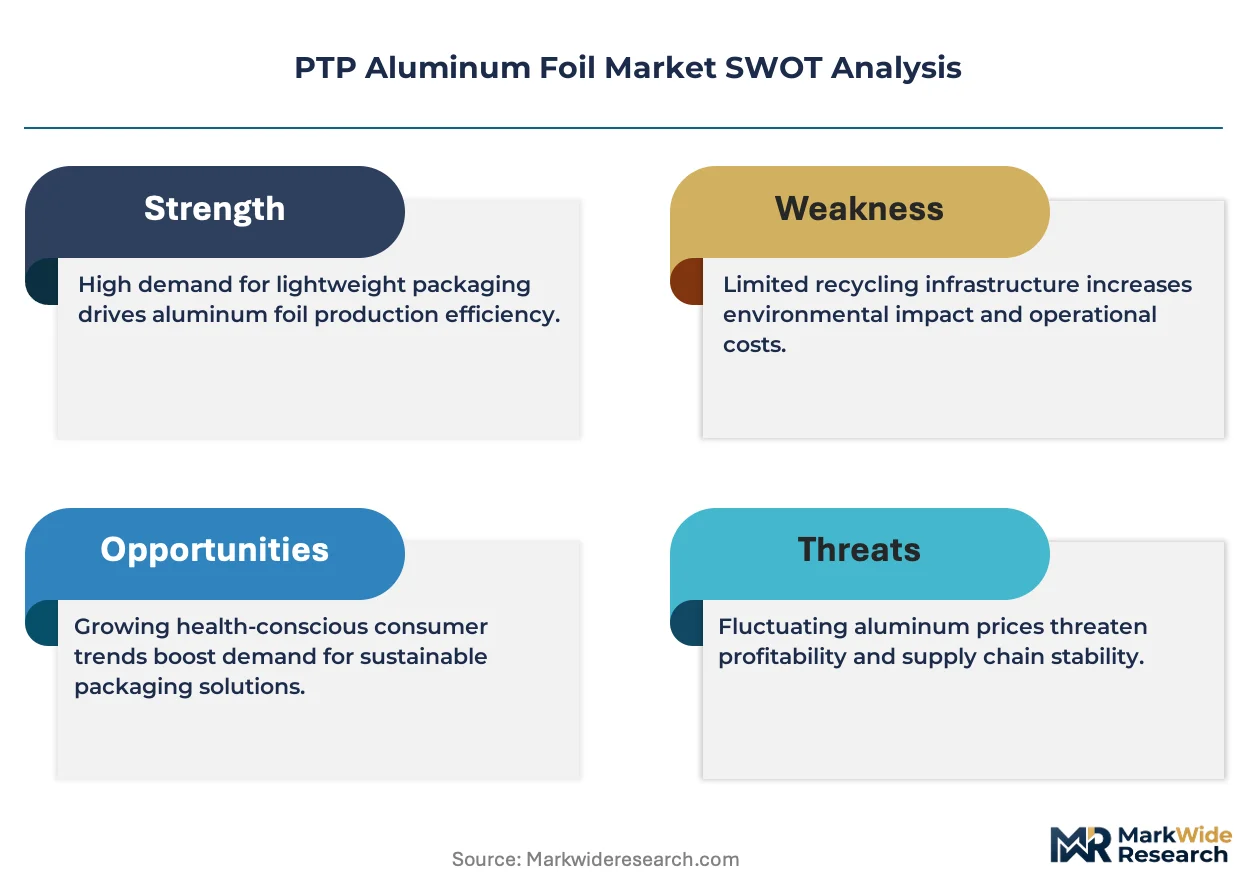
Europe's F-Gas Regulation is forcing PTP foil suppliers to reformulate heat-seal lacquers and validate alternative barrier chemistries, compressing margins for mid-tier converters while advantaging integrated rollers with captive coating R&D.
Growth Catalysts
- Oral solid dosage expansion:Global pharmaceutical output of tablets and capsules continues rising, anchoring unit-dose blister demand. Contract packaging growth in India and China sustains volume pull for 20-30 micron cold-rolled strip.
- REACH compliance premiums:European heat-seal lacquer reformulation requirements are creating certified-supplier scarcity. ECHA migration limit testing now gates market access for non-compliant imports.
- Child-resistant lidding innovation:Push-through foil with senior-friendly peelability is displacing traditional cold-form alternatives in North American geriatric formulations.
Market Restraints
- Primary aluminum volatility:LME price swings for 3003 and 8011 alloy inputs compress converter margins. Rolling mills with captive smelter links capture cost advantage over toll-dependent competitors.
- Pinhole density thresholds:EMA and FDA barrier specifications for oxygen transmission rates limit viable supplier pools. Sub-10 micron pinhole counts require capital-intensive rolling and annealing controls.
- PVC substitution pressure:Thermoformable PET and PP blister cavities are displacing PVC in sustainability-conscious European packaging. PTP foil bond compatibility must adapt to new substrate chemistries.
Strategic Opportunities
- India's CDSCO registration pathway:Domestic generic drug output is expanding blister packaging demand. Local foil converters with NMPA-equivalent quality systems can capture contract manufacturing growth.
- High-barrier PVDC lidding:Oncology and biologic oral dosages require moisture vapor transmission rates below 0.1 g/m²/day. Specialized coating lines command 40-60% margin premiums over standard vinyl lacquer formats.
- Digital printing integration:Serialized track-and-trace mandates under EU MDR and US DSCSA are converging with direct-to-foil inkjet. Print-on-demand lidding eliminates pre-printed inventory obsolescence.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for heat-seal lacquer adhesion and migration compliance resides with aging technical workforces in Japan and Germany.
- Multi-market certification timelines:Simultaneous FDA, EMA, and NMPA dossier preparation stretches quality assurance bandwidth. Staggered approval cycles strand capital in work-in-process inventory.
- Legacy slitting equipment retrofit:Tension control systems designed for 40-micron foils require rebuild for sub-25-micron pharmaceutical grades. Mechanical upgrade costs compete with greenfield automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PTP Aluminum Foil Market |
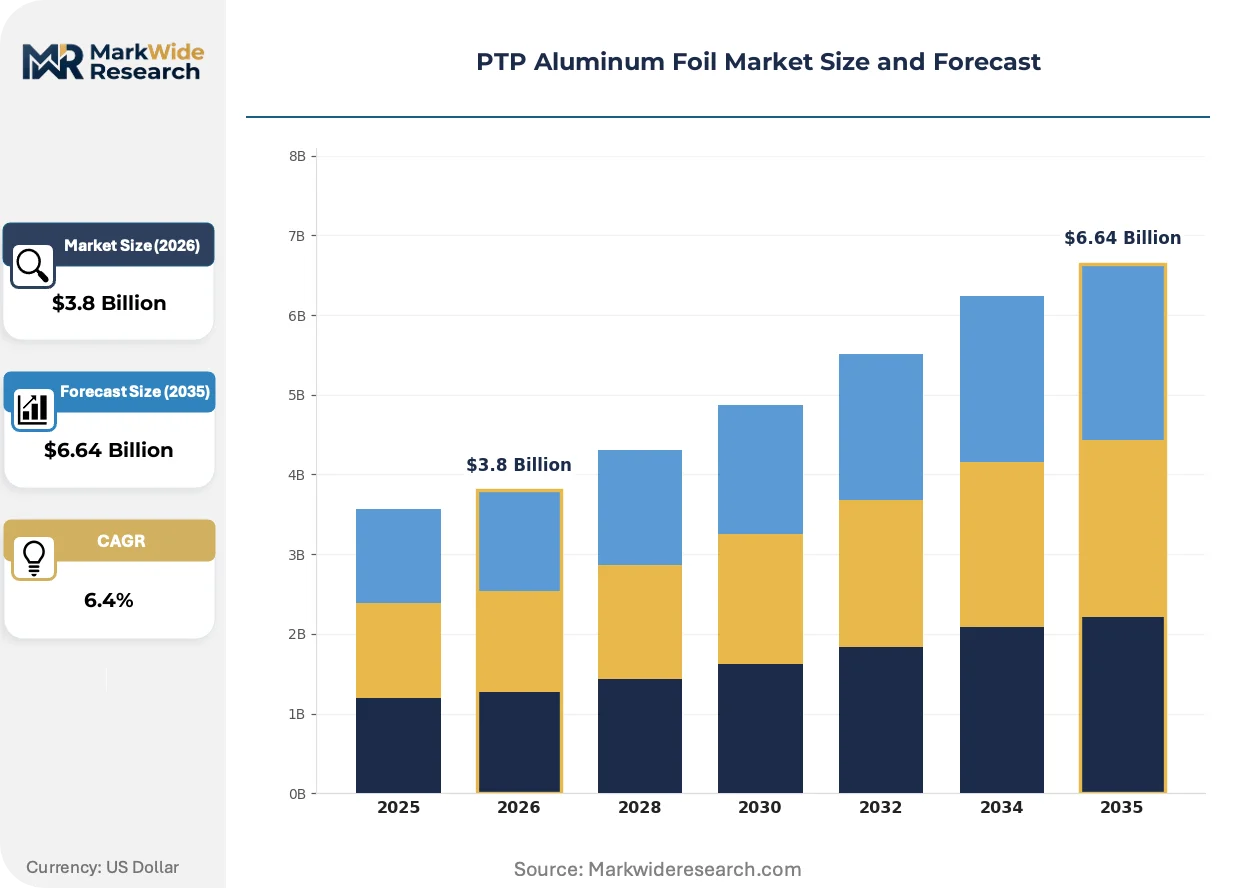
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Foil, Lidding Foil, Alufoil, Form-Fill-Seal End User: Pharmaceuticals, Food & Beverage, Cosmetics, Electronics Thickness: 45 Micron, 60 Micron, 80 Micron, 100 Micron Application: Packaging, Sealing, Food Preservation, Surgical |
| Companies Covered | Toyo Aluminium, Flexipack Group, Amcor, Sichuan Huili Industry, LSKB Aluminium Foils, UACJ Foil, Lotte Aluminium, HySum, Perlen Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PTP Aluminum Foil Market Evolving Landscape
Barrier-layer engineering and regulatory serialization mandates are converging to reshape PTP foil specifications, compressing the viable supplier base while opening premium niches for coating-specialized converters.
Multi-layer coextruded barrier films are consolidating position in high-value oncology packaging. Japanese pharmaceutical manufacturers specify these structures for moisture-sensitive kinase inhibitors. The technology is consolidating supply relationships around converters with in-house lamination and coating capabilities, marginalizing single-process toll rollers.
Europe's MDR Annex I general safety and performance requirements now explicitly address packaging material biocompatibility. EMA notified body scrutiny of blister foil technical documentation has intensified since the regulation's full enforcement. German and Swiss drug manufacturers are consolidating supplier panels to pre-qualified converters with established MDR technical files.
Direct purchasing of certified foil by large pharmaceutical manufacturers is displacing traditional converter-distributor relationships. Pfizer and Novartis procurement organizations now source lidding material through approved vendor lists with audit rights. This pattern is most visible in Basel's pharmaceutical cluster and New Jersey's generic drug corridor.
PTP Aluminum Foil Market Segmentation
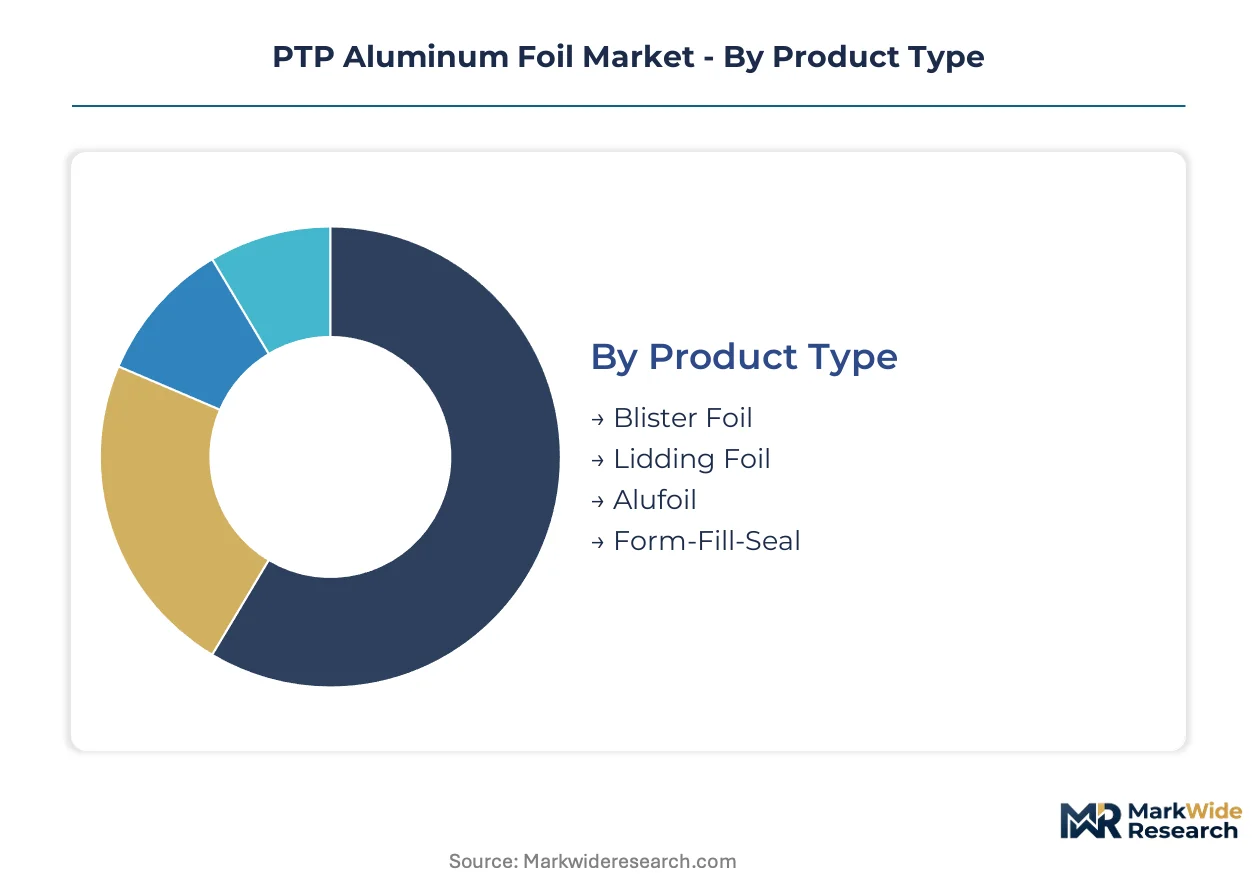
PTP aluminum foil specifications fragment across pharmaceutical certification grades, barrier performance tiers, and regional regulatory compliance requirements. Each segmentation dimension carries distinct margin structures and supplier qualification barriers that reshape competitive positioning.
Product Type:
Supply concentration clusters around pharmaceutical-grade formats where EMA and FDA certification gates limit viable converter pools.
- Blister Foil:Cold-rolled 20-30 micron aluminum strip with vinyl or polyester heat-seal lacquer bonds to PVC or PVDC cavities. Demand concentrates in Germany's pharmaceutical manufacturing corridor and India's expanding contract packaging sector, driven by oral solid dosage expansion.
- Lidding Foil:Multi-layer barrier structures with high-barrier PVDC or aluminum oxide coatings command premium margins in oncology and biologic packaging. Swiss and Japanese drug manufacturers specify these formats for moisture-sensitive kinase inhibitors.
- Alufoil:General-purpose aluminum foil without pharmaceutical-grade certification serves non-regulated industrial applications.
- Form-Fill-Seal:Automated packaging formats gain traction in food and cosmetics where line speed requirements override pharmaceutical certification costs.
Today's leader: Blister Foil. Tomorrow's challenger: Lidding Foil.
End User:
Customer type determines pricing tiers through certification burden and volume scale.
- Pharmaceuticals:Unit-dose blister packaging for tablets and capsules anchors volume demand. FDA, EMA, and NMPA registration requirements enforce material traceability and migration limit testing that stratifies supplier tiers.
- Food & Beverage:Form-fill-seal automation and modified atmosphere packaging applications drive specification flexibility.
- Cosmetics:Premium peelable lidding formats for single-dose serums and ampoules expand addressable market.
- Electronics:Static-dissipative foil formats for component moisture protection occupy niche specification territory.
Pharmaceuticals capture margin premiums. Food & Beverage offers volume scale.
Thickness:
Thickness selection maps directly to barrier performance requirements and rolling mill capability tiers.
- 45 Micron:Cost-competitive output from Chinese and Indian converters serves emerging-market generic drug makers with relaxed pinhole density thresholds.
- 60 Micron:Mid-tier pharmaceutical applications balance barrier performance with material cost.
- 80 Micron:Cold-form alternatives for deep-draw blister cavities requiring enhanced mechanical strength.
- 100 Micron:Specialized surgical and medical device packaging where puncture resistance overrides unit economics.
45 Micron dominates volume. 80 Micron climbs fastest on high-barrier demand.
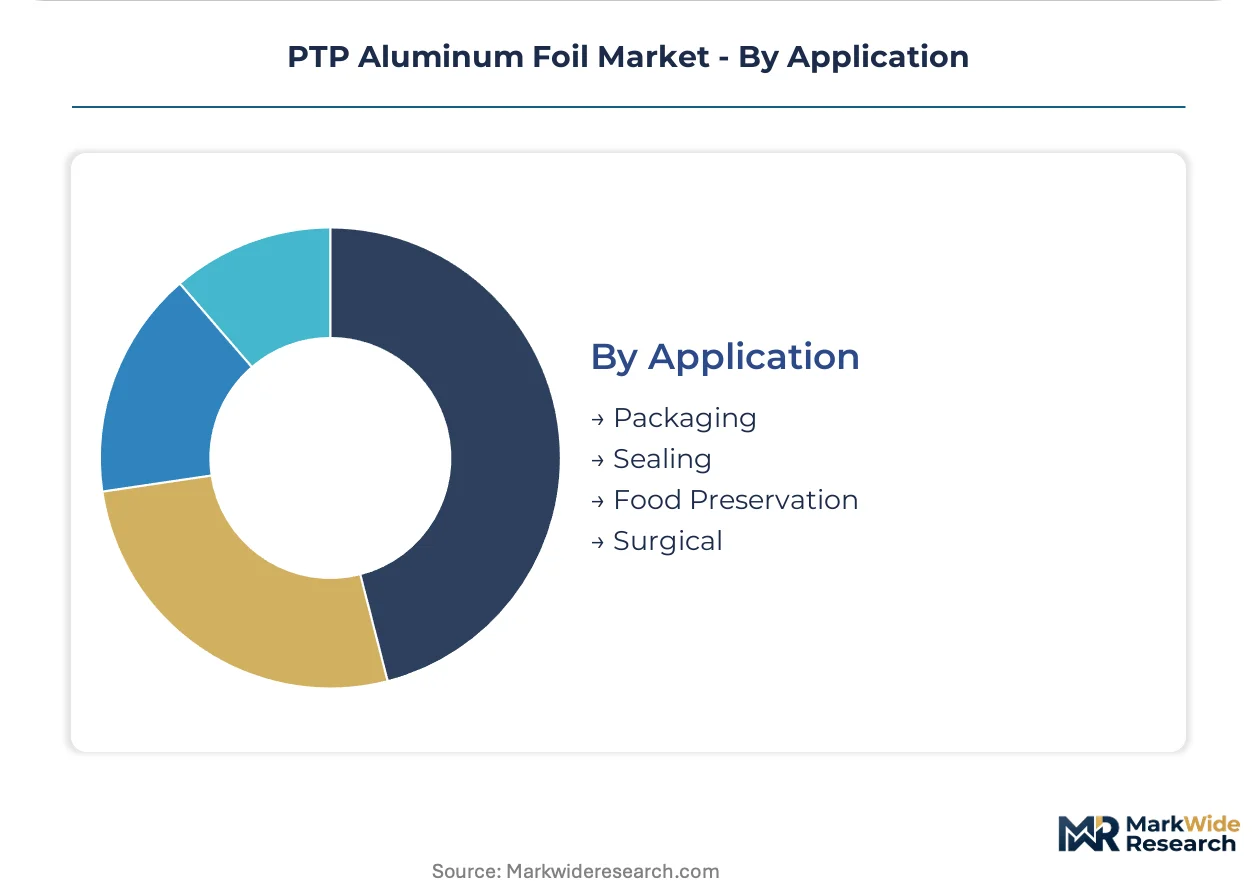
Application:
Application scope stretches from regulated pharmaceutical barriers to commodity food preservation.
- Packaging:Primary containment function across all end-use segments with specification divergence between pharmaceutical and non-regulated grades.
- Sealing:Heat-seal coating adhesion and bond strength requirements vary by substrate chemistry.
- Food Preservation:Modified atmosphere and barrier applications outside pharmaceutical certification pathways.
- Surgical:Sterile barrier systems for medical devices with biocompatibility documentation requirements.
Packaging commands revenue concentration. Surgical represents steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The PTP aluminum foil industry traces its commercial scale to post-war European pharmaceutical packaging standardization, with Basel and Frankfurt emerging as early centers of blister foil specification development before Asian contract manufacturing reshaped volume distribution.
Germany
Bavaria's pharmaceutical manufacturing corridor drives premium-grade foil consumption for export-oriented drug packaging. The EU's MDR Annex I biocompatibility requirements and F-Gas Regulation on coating chemistry now gate supplier qualification. Heidelberg and Frankfurt host converter clusters serving Swiss and German drug manufacturers consolidating approved vendor lists.
India
Contract packaging expansion in Gujarat and Maharashtra sustains volume pull for 20-30 micron cold-rolled strip. CDSCO registration pathways for domestic generic drug output create certified-supplier scarcity. Ahmedabad and Mumbai-Pune pharmaceutical zones anchor foil converter capacity serving export markets.
China
NMPA-equivalent quality systems and evolving GB standards on migration limits are forcing reformulation of heat-seal lacquers. Sichuan and Zhejiang provinces concentrate cost-competitive 45-micron and 60-micron output for emerging-market generic drug makers expanding blister packaging lines.
United States
FDA drug packaging guidelines and DSCSA serialization mandates shape material traceability requirements for unit-dose blister demand. New Jersey's generic drug corridor and Puerto Rico's pharmaceutical manufacturing base drive specification pull for child-resistant lidding formats with senior-friendly peelability.
Japan
PMDA pharmaceutical packaging standards and METI industrial policy sustain captive rolling capacity for premium-grade supply. Osaka-Tokyo pharmaceutical clusters specify multi-layer barrier structures for moisture-sensitive kinase inhibitors, consolidating supply relationships around integrated converters.
PTP Aluminum Foil Market Competitive Landscape
The competitive structure tilts toward integrated rollers with captive coating R&D capabilities. Mid-tier toll converters face margin compression from regulatory compliance costs and primary aluminum volatility. Three archetypes dominate: Japanese integrated aluminum conglomerates with pharmaceutical-grade rolling heritage, European packaging multinationals with MDR-certified coating lines, and Chinese cost-optimized converters serving emerging-market volume. Capacity expansion and strategic partnerships represent the dominant competitive vectors as certification requirements stratify viable supplier pools.
Among Japanese integrated producers, Toyo Aluminium and UACJ Foil exemplify the premium-grade archetype with established pharmaceutical rolling heritage. Amcor occupies a position on the multinational packaging tier with multi-layer lidding format capabilities across North American and European accounts. Sichuan Huili Industry anchors the cost-competitive segment for emerging-market generic drug packaging specifications.
| Leading Market Players |
|---|
| Toyo Aluminium |
| Flexipack Group |
| Amcor |
| Sichuan Huili Industry |
| LSKB Aluminium Foils |
| UACJ Foil |
| Lotte Aluminium |
| HySum |
| Perlen Packaging |
| Others |
Value Network & Pricing Analysis
Captive rolling capacity in Japan and Germany anchors premium-grade supply positions while compressing margins for toll-dependent converters in India and China. This integration choice concentrates pricing power with EMA-certified suppliers serving Basel and Frankfurt pharmaceutical clusters, whereas emerging-market generic drug makers source cost-competitive 45-micron strip through fragmented converter networks.
Pricing Analysis
Bundled certification-and-coating services command substantial premiums over unbundled toll rolling. Three-tier pricing structure across MDR-certified premium, FDA-standard mid-tier, and emerging-market economy levels separates Swiss oncology lidding from Indian generic blister formats. Cost compression in the 45-micron segment is intensifying because Chinese converters compete on primary aluminum input costs. Emerging-market generic drug makers exhibit highest price sensitivity, while Japanese kinase inhibitor manufacturers accept substantial premiums for sub-10 micron pinhole specifications.
Supply Chain Analysis
Direct-to-pharma procurement channels displace traditional converter-distributor relationships for large manufacturers in New Jersey and Basel. Geographic supply concentration clusters in Germany, Japan, and China, with Heidelberg and Osaka hosting integrated rolling-coating operations. Raw material dependencies draw from LME-traded 3003 and 8011 alloy inputs, vinyl heat-seal lacquers, and PVDC barrier coatings. Single-source vulnerability around Japanese coating chemist expertise presents structural risk. Distribution runs through approved vendor lists with audit rights rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European MDR compliance premiums and Asian contract manufacturing cost bases, with regulatory divergence creating persistent margin spreads.
For Market Incumbents: Anticipate PVC substitution pressure by validating PET and PP blister cavity compatibility ahead of European sustainability mandates. Prioritize backward integration into captive coating R&D to defend margin position against REACH-driven reformulation costs. Consolidate supplier panels around pre-qualified converters with established MDR technical files to reduce audit burden. For New Entrants and Emerging Players: Begin with CDSCO-registered foil supply for Gujarat and Maharashtra contract packaging expansion, where certified-supplier scarcity creates white-space opportunity. Target high-barrier PVDC lidding for oncology applications in Swiss and Japanese markets, where moisture vapor transmission specifications command substantial premiums. Pursue digital printing integration partnerships to capture EU MDR and US DSCSA serialization mandates. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European converters because MDR certification gates limit viable acquisition targets and create scarcity value. Five-to-ten year viability hinges on coating formulation expertise migration from aging German and Japanese technical workforces. Monitor pinhole density threshold tightening at EMA and FDA as inflection signal for capital-intensive rolling equipment retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating R&D | Captive heat-seal lacquer formulation secures REACH compliance and migration limit certification. |
| Digital Printing Line Installation | Direct-to-foil inkjet enables serialized track-and-trace compliance with EU MDR mandates. |
| CDSCO Registration Pathway Investment | Domestic Indian certification captures contract packaging growth in Ahmedabad pharmaceutical zones. |
| Multi-Layer Barrier Film Development | Aluminum oxide coating lines serve Japanese moisture-sensitive kinase inhibitor specifications. |
| Legacy Slitting Equipment Retrofit | Tension control rebuild for sub-25-micron grades addresses pharmaceutical pinhole density thresholds. |
Research Methodology
Bottom-up pharmaceutical packaging modeling reconciled against top-down aluminum rolling capacity tracking forms the analytical core. Primary interviews with heat-seal coating chemists, EMA regulatory consultants, pharmaceutical procurement managers, and foil converter operations directors combined with secondary validation from FDA packaging guidelines, EMA MDR technical documentation, REACH migration limit databases, and customs trade data. Triangulation against rolling mill capacity disclosures and pharmaceutical blister line expansion announcements ensures supply-demand balance integrity.
Historical trendline analysis of cold-rolled strip output and lidding format shipments established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type, end-user industry, thickness specification, and regional regulatory cluster dimensions. CAGRs derived from pharmaceutical oral solid dosage expansion rates and contract packaging capacity buildouts in India and China. Forecast inputs included primary aluminum alloy price volatility indices and EMA notified body certification timeline data.
Several conditions sit outside the modeled scope, including hypothetical F-Gas Regulation acceleration beyond current coating chemistry reformulation timelines and abrupt PVC substitution rates in European blister packaging. Forecasts reflect assumptions about sustained oral solid dosage dominance and gradual MDR enforcement consistency across notified bodies. Periodic stress-testing of base assumptions against primary aluminum LME price swings and regulatory divergence between FDA, EMA, and NMPA pathways is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metal Packaging
Aluminum Foil Lids Market
Metal Packaging
Metal Pails Market
Metal Packaging
GCC Metal Cans Market
Metal Packaging
Europe Metal Cans Market
Metal Packaging
Europe Metal Packaging Market
Metal Packaging
Metal Packaging Coatings Market
Metal Packaging
Beverage Metal Cans Market
Metal Packaging
Vietnam Metal Packaging Market
Metal Packaging
Converter Aluminum Foil Market
Metal Packaging
3-Piece Metal Cans Market
Metal Packaging
United States Aluminium Cans Market
Metal Packaging
Metal Containers Market
Metal Packaging
Middle East and Africa Metal Packaging Market
Metal Packaging
Pressurized Metal Containers Market
Metal Packaging
Egypt Metal Packaging Market
Metal Packaging
Metal Aerosol Packaging Market