
 Food Packaging Equipment Market | 2026-2036
Food Packaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Equipment Market Analysis
Mechatronics engineering talent is bifurcating the competitive landscape between vendors that can integrate servo-driven robotics and those locked into pneumatic legacy architectures. MULTIVAC Group leverages its vacuum chamber expertise to dominate thermoforming lines for proteins and cheeses. Ishida Co. Ltd. anchors Asian markets with multihead weighers that sustain throughput advantages in snack and seafood applications. GEA Group competes through dairy specialization, extending its position in aseptic filling systems for extended-shelf-life products.
Food packaging equipment comprises machinery engineered to enclose, protect, and preserve food products through controlled atmosphere, barrier, or sterile containment methods, typically operating at speeds from 50 to 1,200 units per minute with tolerance thresholds below one gram for portion-critical applications. Filling machines command the largest installed base due to universal deployment across liquid, powder, and viscous product categories, though margin pools are compressing in standard volumetric models. Robotics technology is displacing semi-automatic configurations in high-volume bakeries and ready-meal plants, where collaborative palletizing and pick-and-place modules reduce changeover downtime. Composite material handling is the fastest-growing material segment, driven by retort pouches and fiber-based trays that require modified sealing temperatures and pressure profiles.
The FDA enforces 21 CFR Part 110 and FSMA preventive controls that mandate hygienic design standards, pushing processors toward equipment with IP69K washdown ratings and clean-in-place compatibility. EFSA and REACH frameworks in Europe restrict certain polymer contact substances, compelling OEMs to validate new sealing bar coatings and conveyor belt compounds. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's packaging waste targets reshape capital allocation toward recyclable-format-ready machinery and away from single-use plastic-dependent lines.
Market Dynamics
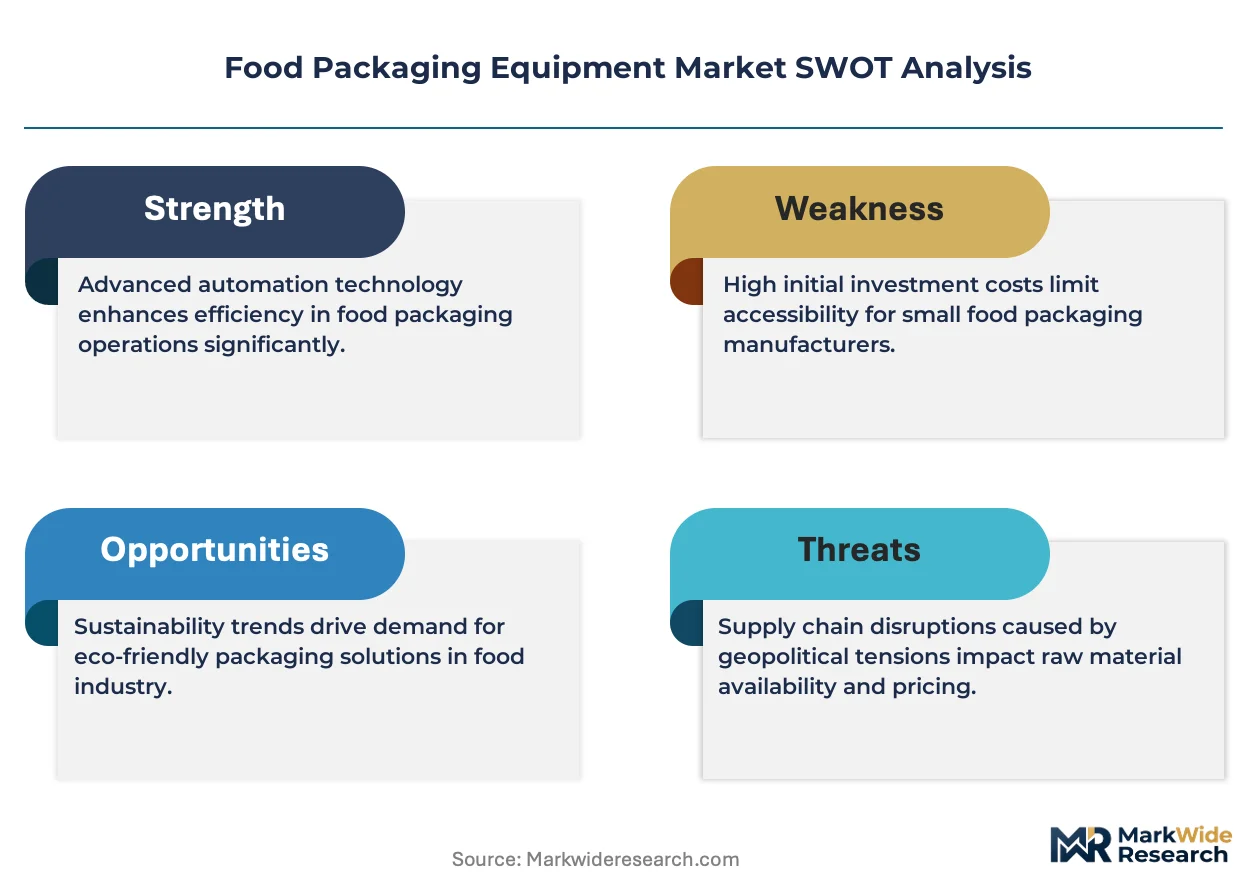
Automated packaging lines are compressing changeover windows from hours to minutes as servo-driven robotics replace pneumatic architectures across high-volume bakeries and ready-meal plants. This mechanical transition is redrawing competitive boundaries between OEMs that control integrated motion systems and those dependent on third-party automation suppliers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are forcing processors to retire legacy lines and install format-flexible machinery capable of handling fiber-based trays and retort pouches without dedicated change parts.
- Protein and cheese processing clusters:Thermoforming demand concentrates in Germany's Stuttgart-Munich corridor, where precision vacuum chamber systems anchor export supply to processors across France, Italy, and Poland.
- Extended-shelf-life dairy:Aseptic filling validation requirements under FDA FSMA preventive controls are accelerating replacement cycles for standard pasteurized milk lines in US and Canadian plants.
Market Restraints
- Stainless steel and servo motor cost volatility:Input price swings for 316L-grade contact surfaces and precision motion components compress margin pools for mid-tier volumetric filler manufacturers.
- Engineering talent bifurcation:Mechatronics specialists concentrate in German and Japanese industrial clusters, leaving North American and Southeast Asian OEMs dependent on licensed technology or expatriate engineering contracts.
- Clean-label packaging material substitution:Fiber-based barrier materials with limited heat-seal compatibility constrain throughput on legacy constant-temperature sealing systems, forcing premature capital retirement.
Strategic Opportunities
- India's organized food retail expansion:Cold chain infrastructure buildout under FSSAI modernization mandates creates first-mover positioning for aseptic pouch and modified-atmosphere tray equipment in dairy and spice processing.
- Dual carbon goals in China:MEE enforcement of energy-efficiency benchmarks for industrial equipment favors servo-electric packaging lines over pneumatic alternatives in Shanghai and Guangdong province.
- Collaborative robotics convergence:Integration of force-limited articulated arms with vision-guided quality inspection opens palletizing and case-packing applications previously blocked by cage requirements and changeover complexity.
Industry Challenges
- IP69K validation timelines:Third-party hygienic design certification for washdown-compatible electronics extends new product introduction cycles by eight to fourteen months.
- Legacy Allen-Bradley and Siemens PLC integration:Retrofitting servo-driven motion control onto existing packaging lines requires custom gateway programming and voids OEM warranty coverage for mixed-architecture installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Equipment Market |
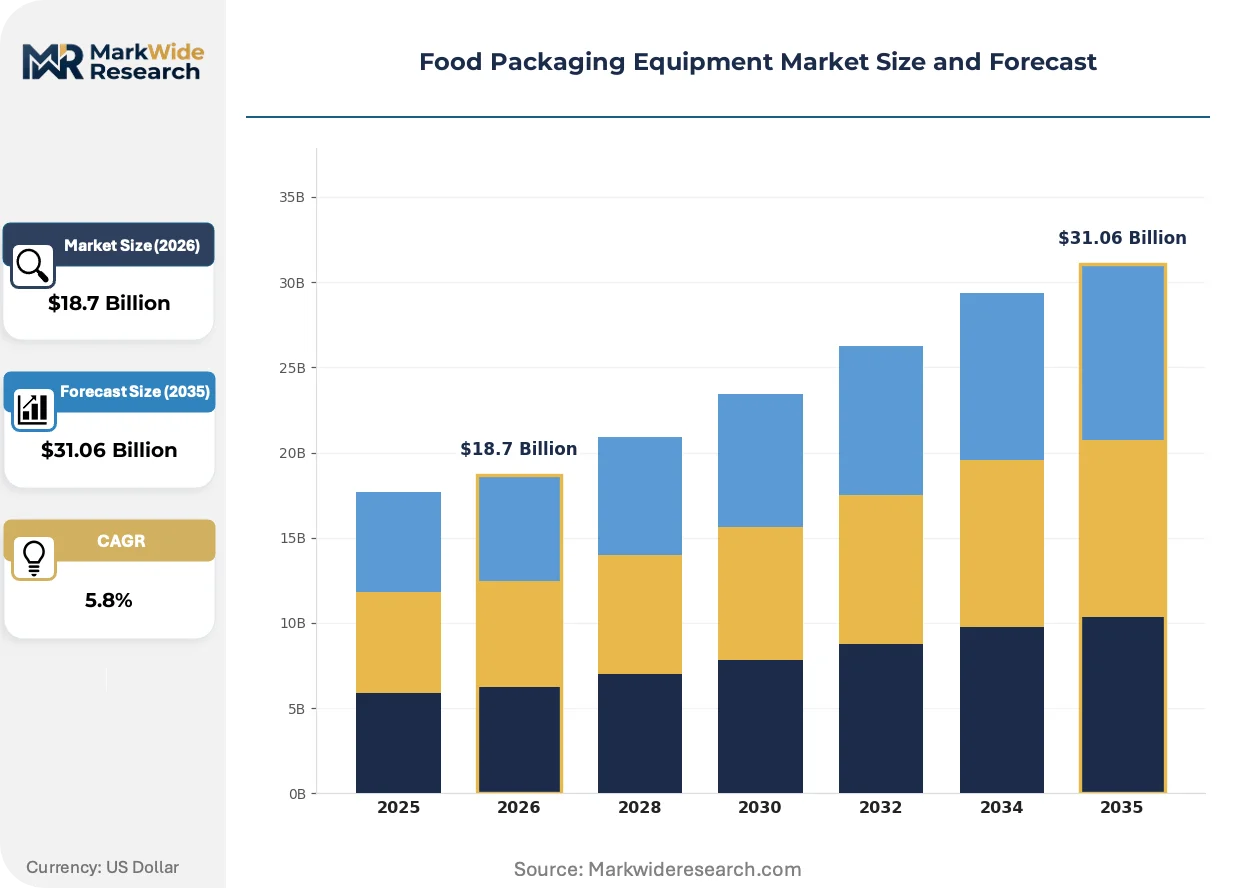
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Filling Machines, Sealing Machines, Labeling Machines, Wrapping Machines Technology: Automatic, Semi-Automatic, Manual, Robotics End User: Food Manufacturers, Restaurants, Catering Services, Food Retailers Material: Plastic, Glass, Metal, Composite |
| Companies Covered | MULTIVAC Group, Ishida Co. Ltd., Tetra Pak International S.A., GEA Group, Robert Bosch Packaging Technology GmbH, Coesia S.p.A., Krones AG, I.M.A. Industria Macchine Automatiche S.p.A., Illinois Tool Works Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Equipment Market Emerging Trajectories
Servo-electric motion control is displacing pneumatic actuation across filling, sealing, and indexing functions. This transition enables recipe-driven changeover without mechanical adjustment, compressing format switch downtime.
Collaborative palletizing robots with integrated force-torque sensing are displacing conventional caged automation in high-mix bakeries and ready-meal plants. Mid-sized processors in the Netherlands and Belgium are adopting these systems to handle seasonal SKU proliferation without dedicated line reconfiguration. The technology is displacing semi-automatic case packers and manual palletizing stations, reducing per-SKU capital intensity.
REACH restrictions on per- and polyfluoroalkyl substances in sealing bar coatings are compelling European OEMs to validate ceramic and plasma-deposited alternatives. ECHA enforcement timelines compress validation windows to eighteen months for equipment destined for French and German dairy processors. Aseptic filling system manufacturers face the steepest reformulation burden, as barrier integrity requirements conflict with eliminated PFAS chemistries.
Equipment-as-a-service contracting is penetrating the mid-market processor segment in North America and Western Europe. Capital-constrained meat and snack producers in Texas, Wisconsin, and Bavaria are adopting throughput-based payment structures that bundle maintenance, software updates, and format change support. This model is displacing traditional equipment financing through captive vendor leasing and third-party asset-backed lending.
Food Packaging Equipment Market Segmentation
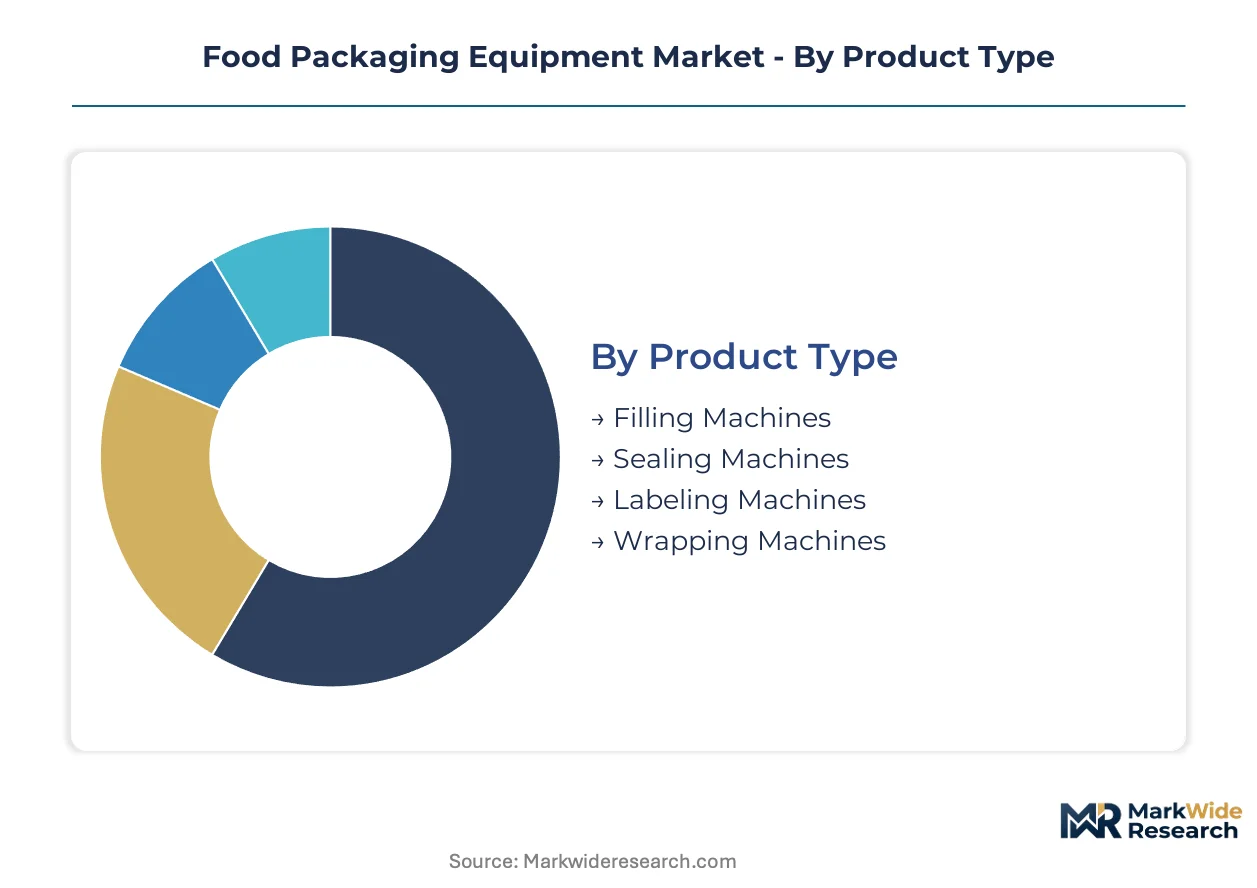
Equipment segmentation in food packaging tracks divergent capital allocation patterns between export-oriented OEMs and domestically focused system integrators. Understanding these splits clarifies where margin pools concentrate versus where volume commoditization accelerates.
Product Type:
German and Japanese OEMs dominate export supply for precision machinery, while domestic manufacturers in India and Brazil capture mid-tier volume with simplified mechanical designs.
- Filling Machines:Volumetric and gravimetric systems handle liquid, powder, and viscous products with tolerance thresholds below one gram. Demand clusters in dairy processors across Wisconsin and Bavaria, where aseptic validation requirements under FDA FSMA and EU hygiene standards force premature replacement of legacy pasteurized milk lines.
- Sealing Machines:Heat-seal, impulse, and vacuum chamber configurations protect barrier integrity for modified-atmosphere and retort applications. Thermoforming demand concentrates in Germany's Stuttgart-Munich corridor, where precision vacuum systems anchor export supply to protein and cheese processors in France, Italy, and Poland.
- Labeling Machines:Pressure-sensitive and sleeve applicators integrate vision inspection for regulatory compliance traceability.
- Wrapping Machines:Stretch, shrink, and flow-wrap systems handle unitization throughputs from 50 to 1,200 units per minute.
Filling machines command the established base. The steepest expansion runs through sealing machines adapting to fiber-based tray and retort pouch formats.
Technology:
Capital intensity separates deployment patterns: servo-electric robotics demand concentrated engineering talent in German industrial clusters, while pneumatic semi-automatic systems sustain volume markets in Southeast Asian contract packaging.
- Automatic:Fully integrated lines with recipe-driven changeover compress format switch downtime from hours to minutes. High-volume bakeries and ready-meal plants in the Netherlands and Belgium adopt these systems to handle seasonal SKU proliferation without dedicated line reconfiguration.
- Robotics:Collaborative palletizing arms with force-torque sensing displace caged automation, opening applications previously blocked by safety requirements. Mid-sized processors adopt throughput-based contracting models that bundle maintenance and software updates.
- Semi-Automatic:Operator-assisted configurations persist in emerging market processors with constrained capital budgets and irregular batch sizes.
- Manual:Hand-fed systems retain niche positioning in artisanal production and regulatory sample preparation.
Automatic systems anchor installed capacity. Robotics are climbing the fastest as force-limited articulated arms converge with vision-guided quality inspection.
End User:
Contract packaging concentration versus captive in-house operations determines equipment specification: co-manufacturers prioritize format flexibility, while branded food manufacturers emphasize traceability integration.
- Food Manufacturers:Dairy, meat, snack, and beverage processors deploy capital for throughput targets and labor constraint mitigation. Aseptic filling validation requirements accelerate replacement cycles in US and Canadian plants.
- Food Retailers:Private-label packaging operations in organized retail chains drive demand for modular lines with rapid changeover.
- Restaurants:Central kitchen and ghost kitchen formats adopt compact semi-automatic systems for portion control.
- Catering Services:Event and institutional foodservice operators prioritize mobile and washdown-compatible equipment.
Food manufacturers represent the dominant installed base. Food retailers are expanding most quickly as private-label penetration deepens in organized retail.
Material:
Regulatory fragmentation across FDA, EFSA, and China's MEE frameworks forces equipment OEMs to validate multiple sealing temperature and pressure profiles for format-flexible machinery.
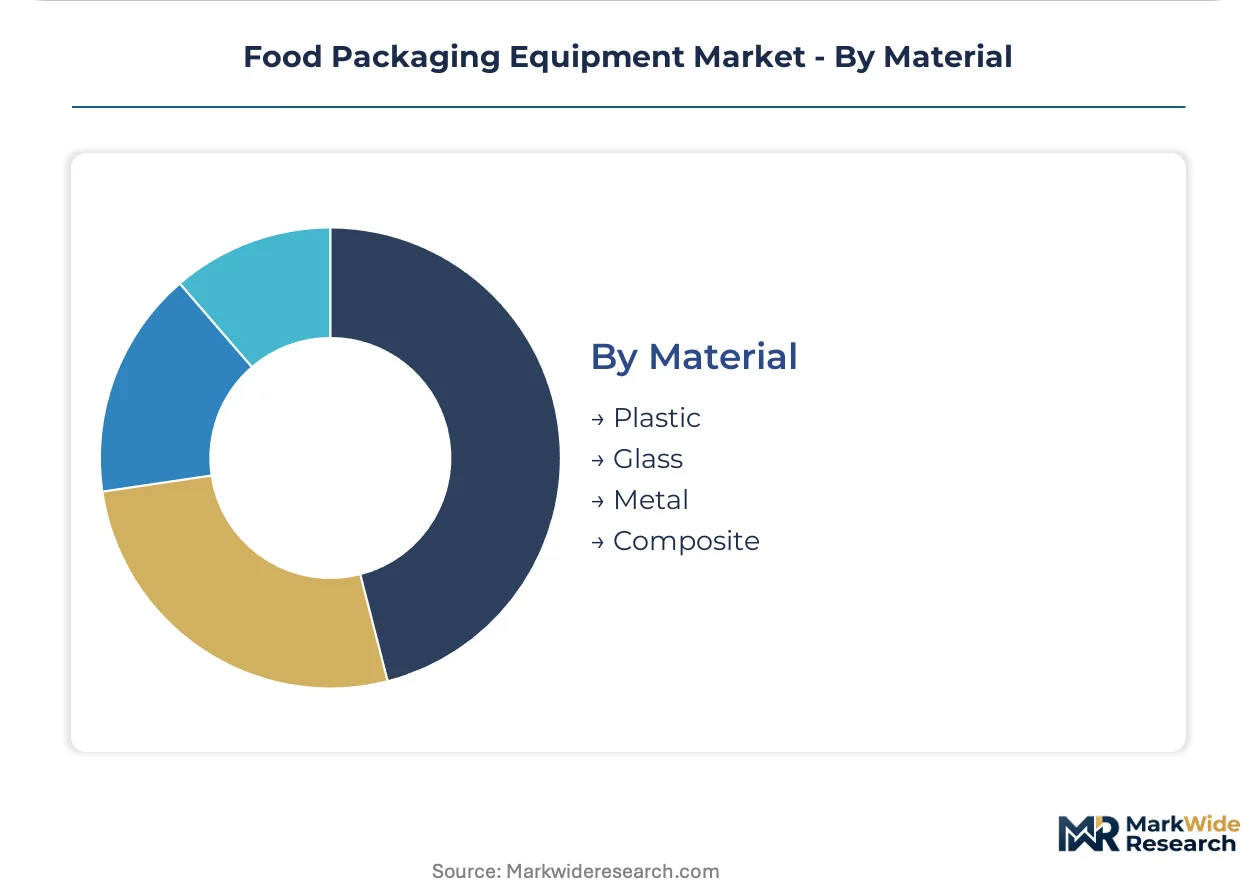
- Composite:Fiber-based trays and retort pouches with modified barrier layers require adjusted heat-seal compatibility. EU Packaging and Packaging Waste Regulation recyclability targets compel processors to retire legacy constant-temperature sealing systems.
- Plastic:Flexible films and rigid containers sustain volume demand despite regulatory pressure on single-use formats.
- Metal:Cans and closures retain positioning in shelf-stable and aseptic applications.
- Glass:Premium beverage and condiment packaging preserves market share in export-oriented European processors.
Plastic maintains volume leadership. Composite materials are gaining share fastest as REACH restrictions on PFAS chemistries and EU Green Deal targets reshape material selection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA preventive controls under FSMA anchor equipment replacement cycles in the United States, while EFSA hygiene standards and China's MEE dual carbon enforcement reshape capital allocation across Germany, Japan, and India. Demand clusters concentrate in precision engineering corridors and dairy processing belts where regulatory compliance intersects with throughput expansion.
United States
Dairy processors across Wisconsin and upstate New York deploy aseptic filling systems to meet FDA FSMA validation requirements for extended-shelf-life milk. The USDA enforces Grade A Pasteurized Milk Ordinance standards that accelerate retirement of legacy pasteurized lines. Equipment procurement concentrates in the Upper Midwest dairy belt, where co-manufacturers upgrade automated packaging lines to handle private-label SKU proliferation.
Germany
Protein and cheese processors drive thermoforming equipment demand through precision vacuum chamber systems engineered in the Stuttgart-Munich corridor. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that force format-flexible machinery adoption. Engineering talent clusters around Stuttgart, where OEMs supply sealing and filling systems to French, Italian, and Polish processors.
China
Shanghai and Guangdong province processors confront MEE enforcement of industrial equipment energy-efficiency benchmarks that favor servo-electric packaging lines. The dual carbon goals framework compels retirement of pneumatic architectures in high-volume bakeries and ready-meal plants. Domestic OEMs in the Yangtze River Delta capture mid-tier volume with simplified mechanical designs.
Japan
Snack and seafood applications sustain demand for multihead weighing systems in Osaka and Nagoya industrial zones. METI industrial standards emphasize precision motion control integration that differentiates Japanese OEM export supply. Engineering concentration in the Chubu region supports technology licensing to Southeast Asian contract packaging operations.
India
Cold chain infrastructure buildout under FSSAI modernization mandates creates positioning for aseptic pouch equipment in Maharashtra and Gujarat dairy processing. The PLI scheme for food processing machinery attracts capital toward automated lines capable of modified-atmosphere packaging. Spice processors in Telangana adopt semi-automatic systems as organized retail penetration deepens.
Food Packaging Equipment Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier controlling servo-driven motion systems and integrated automation architectures while mid-tier competitors rely on licensed technology or third-party component sourcing. The market structure separates players by capital intensity and mechatronics engineering access. Three archetypes dominate: precision vacuum system specialists, multihead weighing technology anchors, and aseptic filling validation leaders. Competitive moves concentrate on strategic partnerships for automation integration and portfolio diversification into format-flexible machinery.
Among Germany-based precision engineering groups, MULTIVAC Group and GEA Group represent the integrated tier, while Ishida Co. Ltd. anchors Japanese multihead weighing specialization. These three exemplify divergent competitive positioning: MULTIVAC leverages vacuum chamber expertise, GEA concentrates dairy aseptic systems, and Ishida sustains throughput advantages in portion-critical applications. Each occupies a distinct technology vector within the equipment segmentation.
| Leading Market Players |
|---|
| MULTIVAC Group |
| Ishida Co. Ltd. |
| Tetra Pak International S.A. |
| GEA Group |
| Robert Bosch Packaging Technology GmbH |
| Coesia S.p.A. |
| Krones AG |
| I.M.A. Industria Macchine Automatiche S.p.A. |
| Illinois Tool Works Inc. |
| Others |
Supply Flow & Price Mechanics
Servo-electric actuator substitution for pneumatic cylinders simultaneously redistributes component sourcing toward German and Japanese precision engineering clusters and compresses margin pools for mid-tier OEMs locked into legacy architectures. This mechanical transition forces processors to absorb upfront capital premiums while equipment vendors face stainless steel and servo motor cost volatility that constrains pricing flexibility.
Pricing Analysis
Long-term offtake contracts with bundled maintenance and software update provisions dominate capital procurement for high-volume dairy and protein processors. Three-tier pricing structure across premium, standard, and economy levels separates IP69K-validated servo-driven lines from pneumatic semi-automatic configurations and entry-level volumetric fillers. Cost compression in mid-tier volumetric models is intensifying because raw material volatility for 316L-grade contact surfaces erodes manufacturer margins. Private-label co-manufacturers in Texas and Wisconsin exhibit highest price sensitivity due to capital constraints, while multinational dairy processors prioritize validation-grade equipment with lowest total cost of ownership sensitivity.
Supply Chain Analysis
Germany and Japan anchor precision servo motor and motion control component fabrication, while China captures mid-tier mechanical subassembly production in the Yangtze River Delta. Equipment manufacturing draws from 316L stainless steel contact surfaces, ceramic sealing bar coatings, and precision ball screw assemblies. Single-source vulnerability concentrates in German-engineered vacuum chamber systems for thermoforming applications. Distribution runs through direct OEM sales teams for large integrated projects and specialized distributors for aftermarket parts and retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting represents a service-attach opportunity expanding faster than hardware sales, as throughput-based payment structures bundle predictive maintenance, remote diagnostics, and format change support into recurring revenue streams.
For Market Incumbents: Secure backward integration into servo drive and motion control component supply to reduce exposure to third-party automation vendor pricing power. Deepen captive engineering talent pools in Stuttgart and Nagoya clusters to defend against emerging Chinese OEMs acquiring licensed technology. The priority lever rests on accelerating IP69K validation timelines to compress new product introduction cycles. For New Entrants and Emerging Players: Lead with modular aseptic pouch equipment targeting India's Maharashtra and Gujarat dairy belt, where FSSAI modernization mandates and cold chain infrastructure buildout create first-mover positioning. Penetrate the semi-automatic segment for spice processors in Telangana through equipment-as-a-service contracting that reduces upfront capital barriers. Partner with established German or Japanese engineering firms for technology licensing rather than greenfield R&D. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier volumetric filler manufacturers facing margin compression from stainless steel cost volatility and servo motor supply constraints. Long-term viability over a multi-year horizon favors targets with installed base density enabling aftermarket parts and service revenue expansion. Watch MEE enforcement of dual carbon goals in China as the inflection signal accelerating pneumatic line retirement and servo-electric replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Architecture Transition | Enables recipe-driven changeover compressing format switch downtime from hours to minutes in high-volume bakeries. |
| Equipment-as-a-Service Contracting | Throughput-based payment structures penetrate capital-constrained meat and snack processors in Texas and Bavaria. |
| IP69K Validation Acceleration | Third-party hygienic design certification compresses new product introduction cycles for washdown-compatible electronics. |
| PFAS-Free Sealing Bar Development | REACH restrictions force ceramic and plasma-deposited coating validation for French and German dairy processors. |
| India Cold Chain Equipment Positioning | FSSAI modernization mandates create demand for aseptic pouch and modified-atmosphere tray systems in Maharashtra. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers and refined through secondary validation against SEC filings, customs and trade data, FDA FSMA guidance documents, and EU Packaging and Packaging Waste Regulation implementation timelines. Bottom-up equipment shipment data triangulated against top-down processor capital expenditure surveys established market sizing boundaries.
Variance decomposition across technology, material, and end-user segmentation dimensions modeled expansion trajectories over the projection horizon. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance deadline impacts, and processor throughput expansion plans. Servo-electric adoption curves, PFAS substitution timelines, and equipment-as-a-service penetration rates served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of FSMA preventive controls and EU recyclability targets would require recalibration. Forecasts reflect documented assumptions regarding stainless steel cost stability and engineering talent availability in German industrial clusters. Recalibration cycles align with material shifts in MEE dual carbon enforcement intensity and REACH restriction expansion scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
France Foam Pumps Market
Packaging Equipment
Big Bag Connection System Market
Packaging Equipment
Global Reverse Vending Machine Market
Packaging Equipment
Hot Melt Equipment Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Packing Belt Market
Packaging Equipment
Clip Applicator Market
Packaging Equipment
Burnisher Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Gas-Flushing Band Sealing Systems Market
Packaging Equipment
Aerosol Dispensing Systems Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
High Resolution Dispensing Systems and Equipment Market
Packaging Equipment
Blow Molding Tools Market