
 Europe Food Contract Manufacturing and Packaging Market | 2026-2036
Europe Food Contract Manufacturing and Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Contract Manufacturing and Packaging Market Foresight
The gap between artisan-positioned premium co-manufacturing and high-volume commodity packing is expanding across Europe. Hearthside Europe leverages pan-European bakery and snack production networks to sustain cost leadership at scale. Alexir Co-Packers Limited differentiates through flexible short-run capabilities serving challenger brands. SternMaid GmbH & Co. KG dominates powder-based contract manufacturing for infant nutrition and sports formulations.
Food contract manufacturing and packaging encompasses outsourced production, assembly, and packaging of finished food products where brand owners delegate manufacturing execution to third-party specialists operating under agreed formulations, quality protocols, and shelf-life parameters. Co-packers manage filling, sealing, labeling, and case-packing across ambient, chilled, and frozen temperature bands, enabling brand owners to convert fixed production overhead into variable cost structures without capital deployment. Private label and contract manufacturing services command the deepest margin pools as retailers consolidate supplier bases and demand end-to-end formulation-to-shelf accountability. Flexible packaging formats are displacing rigid alternatives in snacks and baked goods as material science advances barrier properties at lower unit weight. Beverage co-packing retains structural growth in functional and ready-to-drink segments where aseptic filling investments create entry barriers.
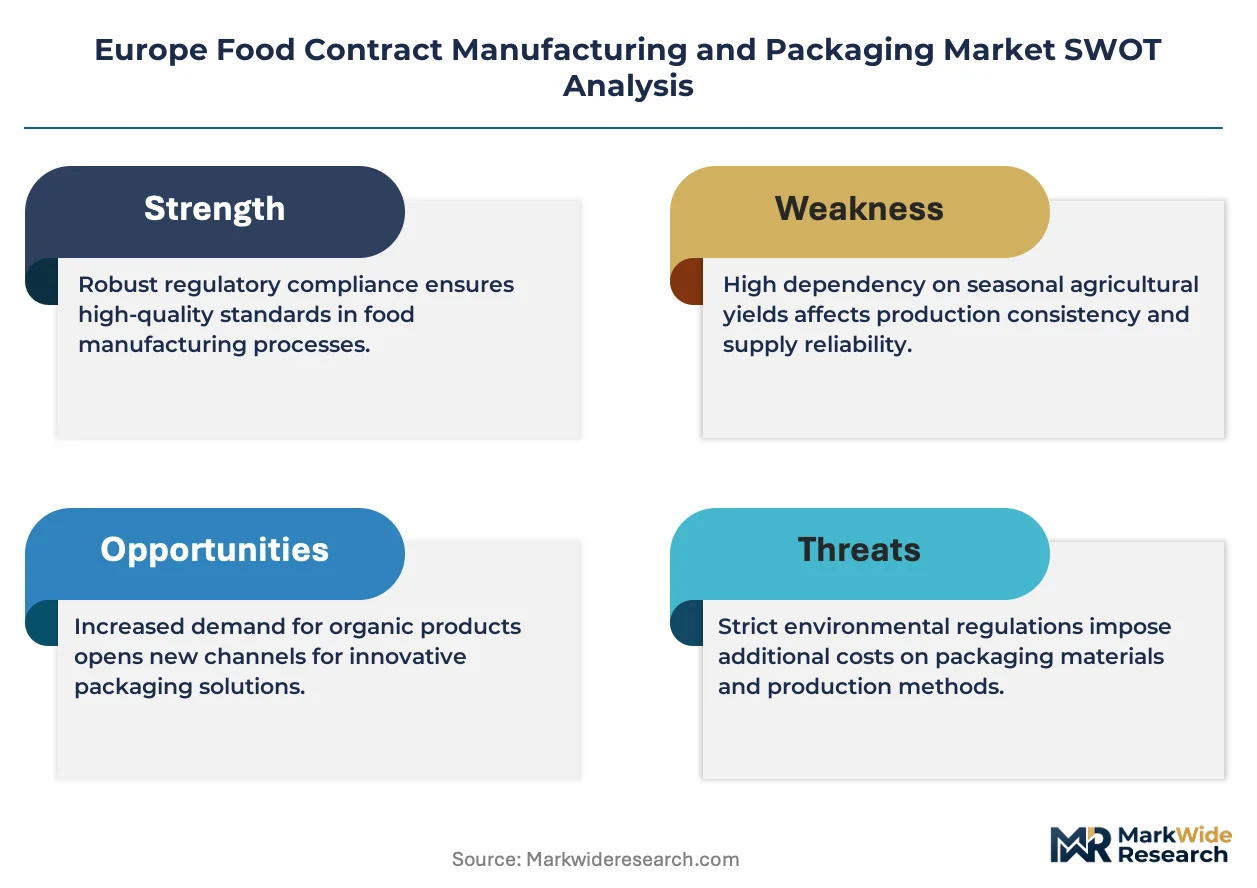
EMA food-contact material guidelines, EU Green Deal sustainability targets, and REACH chemical compliance obligations collectively elevate qualification costs and exclude subscale operators from retailer-approved supplier lists. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that reshape substrate selection and equipment retrofit cycles across German, Dutch, and Italian production corridors. Stakeholders must monitor regulatory implementation timelines and pre-qualify alternative material streams before compliance deadlines crystallize into supply disruptions.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates on recycled content minimums are forcing substrate conversions and equipment retrofits across German, Dutch, and Italian production corridors faster than depreciation cycles allow.
Growth Catalysts
- Plant-based dairy alternatives:Oat, almond, and pea-protein beverage brands outsource aseptic filling and chilled distribution to contract operators with validated cold-chain credentials.
- EU Green Deal sustainability targets:Brand owners accelerate packaging lightweighting programs, creating pull for co-packers with barrier-coated paper and mono-material film capabilities.
- Hamburg-Munich corridor concentration:Large-scale bakery and dairy contract operations cluster here, generating knowledge spillovers and shared logistics infrastructure that lower unit costs for regional challengers.
Market Restraints
- Recycled polymer feedstock volatility:rPET and rPP price swings squeeze margin predictability for beverage and dairy co-packers locked into fixed-price annual contracts.
- Equipment supplier concentration:Aseptic filling line builders cluster in northern Italy and southern Germany, creating bottlenecks for capacity expansion timelines.
- REACH chemical compliance:ECHA substance restrictions on certain adhesive and coating chemistries force formulation reformulations that delay product requalification.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania lack scaled ambient and chilled co-packing infrastructure for pan-European brand owners seeking lower labor-cost production alternatives.
- Smart packaging convergence:Integration of printed electronics and time-temperature indicators creates premium service tiers for pharmaceutical-adjacent nutrition products.
- Direct-to-retailer channel innovation:Discounters and convenience chains in the Netherlands and Belgium seek direct contract relationships bypassing traditional wholesaler layers.
Industry Challenges
- Automation technician scarcity:Servo-driven packaging line maintenance and PLC programming skills lag demand across the Rhine-Ruhr and northern Italian industrial zones.
- Dual certification timelines:Simultaneous IFS and BRCGS audits compress engineering resources and extend new customer onboarding by eight to fourteen weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Contract Manufacturing and Packaging Market |
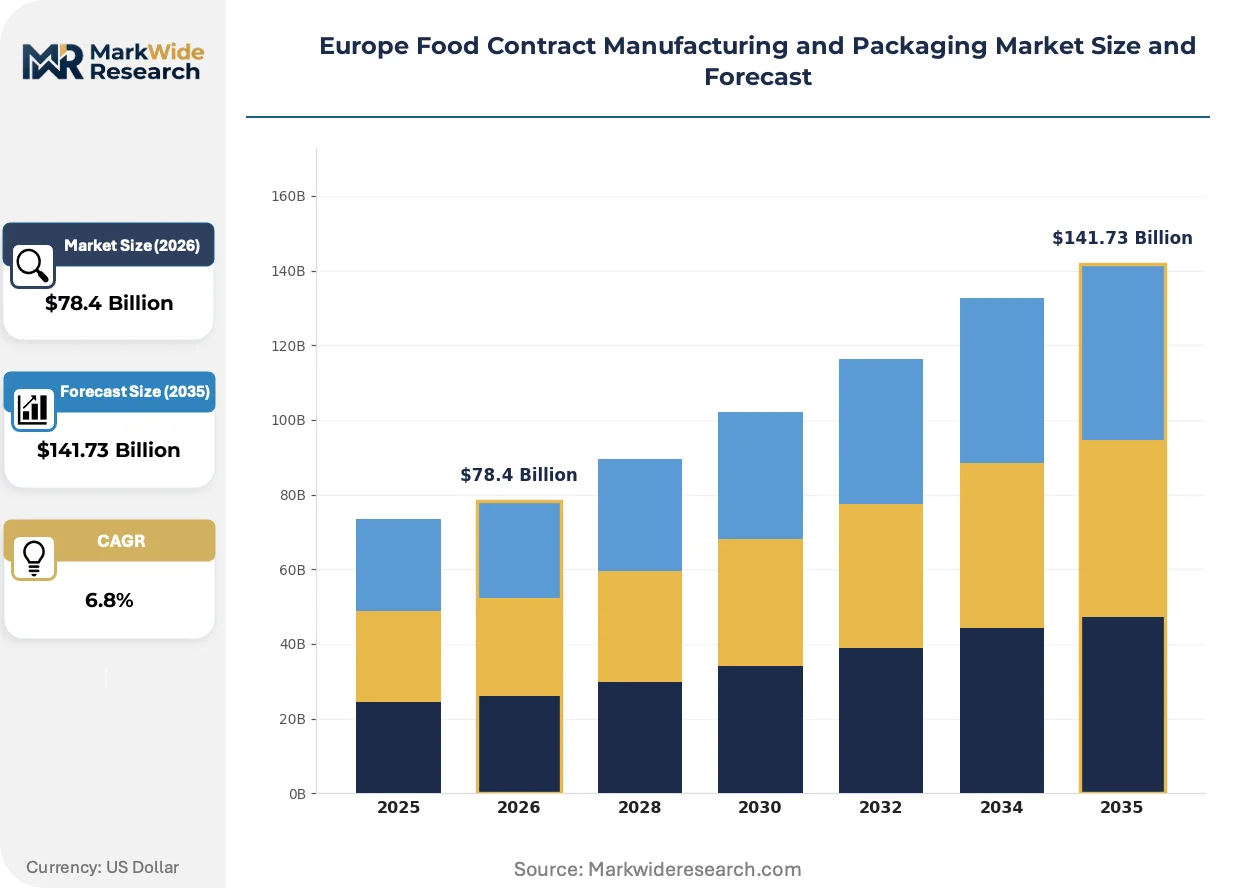
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Label, Co-Packing, Contract Manufacturing, Ingredient Sourcing Product Type: Baked Goods, Beverages, Dairy Products, Snacks Packaging Type: Flexible Packaging, Rigid Packaging, Glass Packaging, Vacuum Packaging End User: Retail Chains, Food Service, E-commerce, Wholesalers |
| Companies Covered | A and S Packing Company Limited, Hearthside Europe, Romix Foods Limited, STOCKMEIER Food GmbH & Co. KG, SternMaid GmbH & Co. KG, Aimia Foods Ltd, Alexir Co-Packers Limited, Budelpack Poortvliet BV, Alphapak International Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Contract Manufacturing and Packaging Market Shifts & Advancements
Material science advances and digital integration are compressing the gap between shelf-life performance and sustainability credentials across European food packaging operations.
Mono-material flexible packaging structures with enhanced oxygen and moisture barriers are unifying the previously separate functions of multi-layer laminates. Snack and baked goods brand owners in Germany and the Netherlands are adopting these substrates at pilot scale now, with full volume transitions planned within current equipment lifecycles. This unification eliminates separation steps in mechanical recycling streams, aligning co-packer offerings with retailer sustainability scorecards.
REACH chemical compliance obligations are expanding substance restriction lists faster than reformulation pipelines can adapt. Industrial consequence includes mandatory substitution of certain phthalate-based plasticizers and bisphenol-derived coatings in food-contact applications. Infant nutrition and ready-meal segments face the tightest compliance windows, with SternMaid and comparable powder specialists investing in analytical testing capacity ahead of enforcement phases.
Brand owners are consolidating supplier bases and demanding end-to-end formulation-to-shelf accountability from single contract partners. This displaces the traditional model of separate ingredient, manufacturing, and packaging vendors. The shift is most visible in private label relationships across German and French retail networks, where buyers now penalize fragmented supply chains in vendor scorecards.
Europe Food Contract Manufacturing and Packaging Market Segmentation
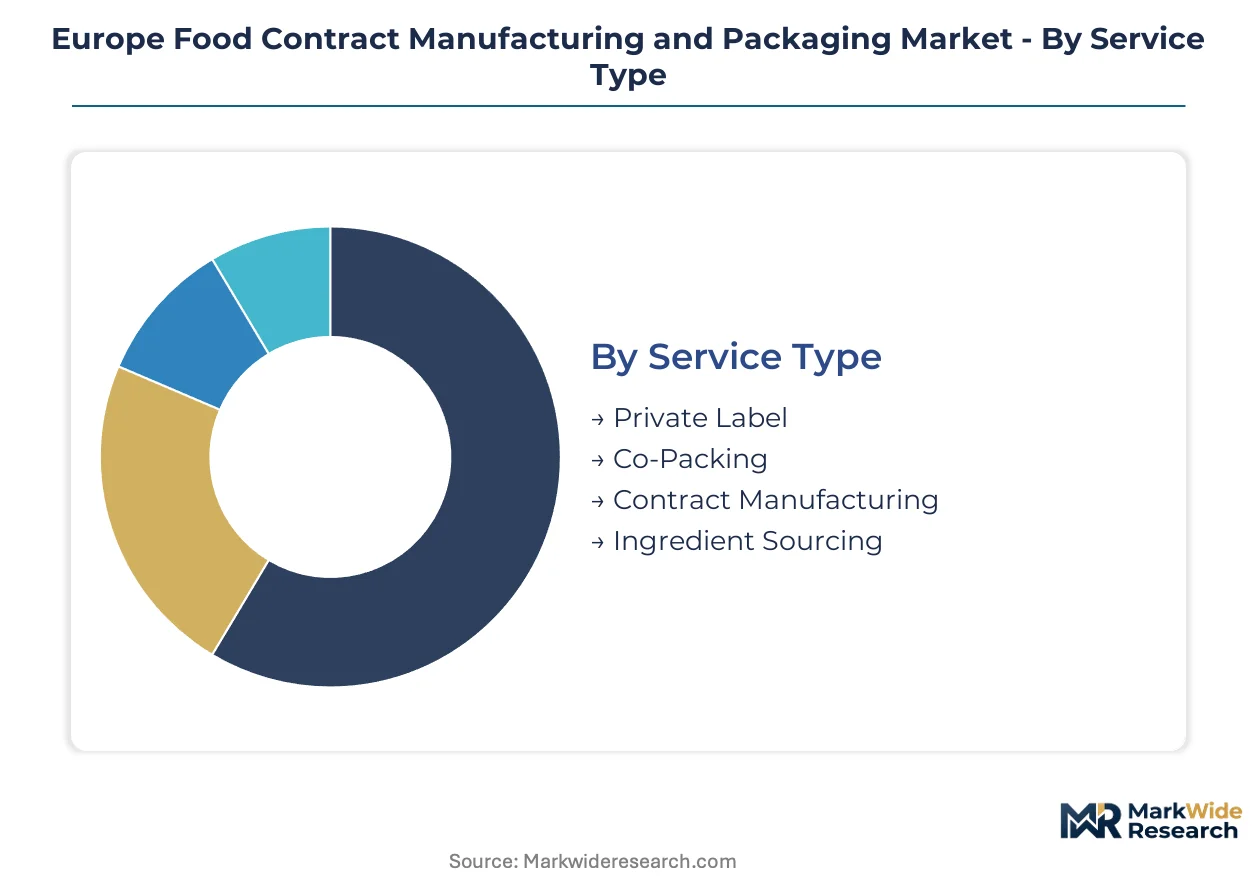
Segmentation in Europe food contract manufacturing and packaging reveals how service specialization, substrate technology, and channel requirements fragment procurement decisions. Brand owners match contract partners to specific shelf-life, volume, and sustainability mandates rather than sourcing generically.
Service Type:
Customization intensity varies from turnkey formulation to execution-only contracts, with margin structures compressing toward standardized co-packing and expanding at integrated private label services.
- Private Label:End-to-end accountability spans formulation development through retail-ready packaging. German discounters and French supermarket chains now require single-source accountability for their store brands, elevating qualification barriers. Margin pools deepen here as retailers consolidate supplier bases.
- Co-Packing:Execution-focused services cover filling, sealing, labeling, and case-packing under brand-owner specifications. Demand clusters around short-run flexibility for challenger brands in Netherlands and Belgium, where Alexir Co-Packers Limited and comparable operators serve rapid product iteration cycles.
- Contract Manufacturing:Full production delegation including recipe execution and quality protocol management. Powder-based infant nutrition and sports formulations in Germany concentrate at SternMaid GmbH & Co. KG facilities with validated dry-blending and analytical testing capacity.
- Ingredient Sourcing:Procurement and pre-processing of raw materials ahead of manufacturing execution. EU Green Deal traceability requirements are forcing investment in blockchain-enabled supply chain documentation.
Leading the category by volume: Co-Packing. Expanding most quickly: Private Label.
Product Type:
Perishability profiles and aseptic processing requirements divide the market between chilled distribution infrastructure and ambient-stable production corridors.
- Baked Goods:Ambient-stable bread, pastry, and snack production dominates Hamburg-Munich corridor operations. Hearthside Europe leverages pan-European production networks for cost leadership at scale, while artisan-positioned premium co-manufacturing commands price premiums elsewhere.
- Beverages:Functional and ready-to-drink segments drive structural growth where aseptic filling investments create entry barriers. Oat, almond, and pea-protein brands outsource to contract operators with validated cold-chain credentials across German and Dutch production zones.
- Dairy Products:Chilled distribution requirements concentrate demand around Munich and Hamburg dairy contract clusters with shared logistics infrastructure lowering unit costs for regional challengers.
- Snacks:Flexible packaging adoption accelerates barrier-coated paper and mono-material film transitions to align with retailer sustainability scorecards in German and Netherlands markets.
Highest revenue concentration: Baked Goods. Steepest expansion trajectory: Beverages.
Packaging Type:
EU Packaging and Packaging Waste Regulation mandates on recycled content minimums are forcing substrate conversions and equipment retrofits faster than depreciation cycles allow.
- Flexible Packaging:Mono-material structures with enhanced oxygen and moisture barriers unify previously separate multi-layer laminate functions. Snack and baked goods brand owners adopt these substrates at pilot scale now, with full volume transitions planned within current equipment lifecycles.
- Rigid Packaging:Recycled polymer feedstock volatility in rPET and rPP squeezes margin predictability for beverage and dairy co-packers locked into fixed-price annual contracts.
- Glass Packaging:Premium positioning in infant nutrition and pharmaceutical-adjacent nutrition products retains structural demand despite weight and fragility penalties in distribution.
- Vacuum Packaging:Extended shelf-life applications in ready-meal segments face tight REACH chemical compliance windows for adhesive and coating reformulations.
Dominant installed base: Flexible Packaging. Gaining share fastest: Mono-material flexible variants.
End User:
Channel consolidation and disintermediation pressures are reshaping contract manufacturing procurement relationships across European retail networks.
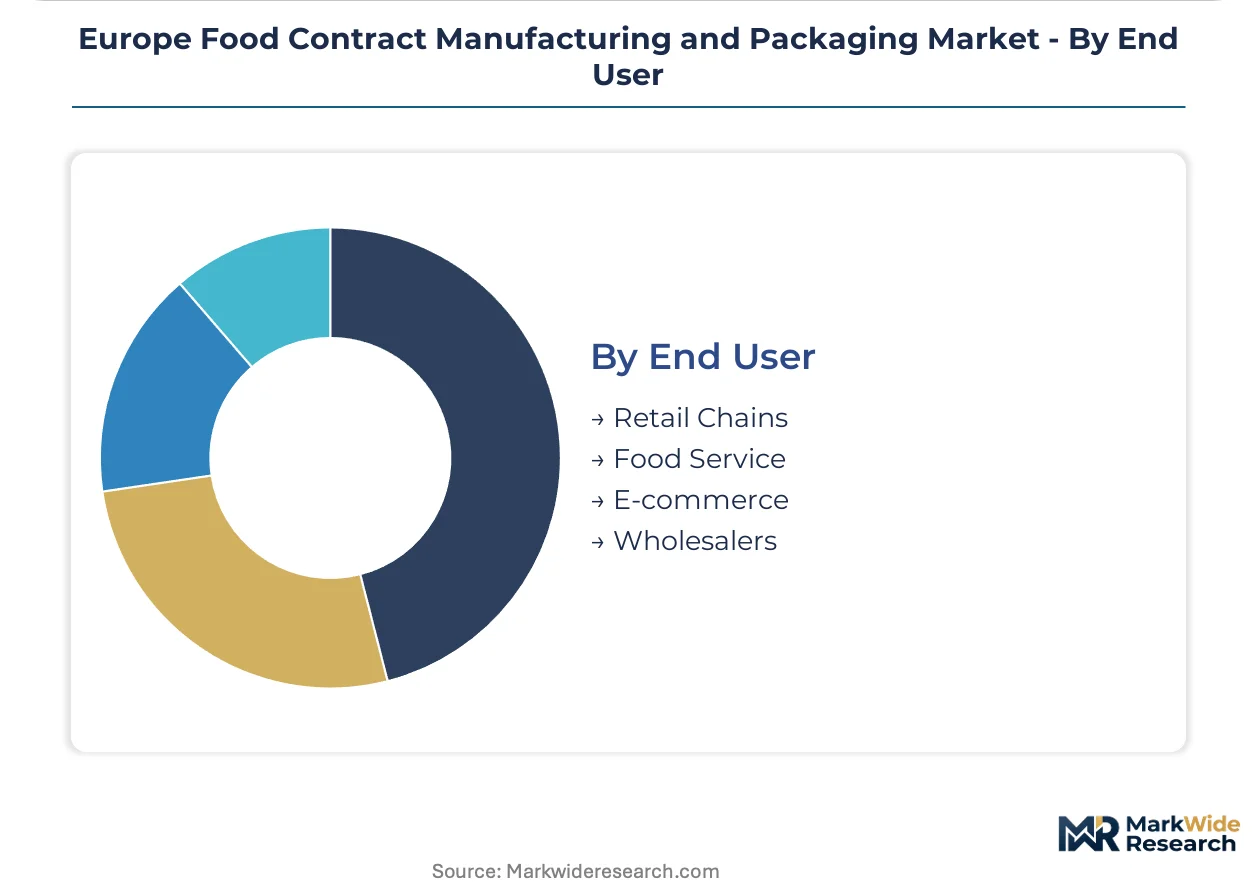
- Retail Chains:German and French retail buyers now penalize fragmented supply chains in vendor scorecards, consolidating supplier bases and demanding end-to-end formulation-to-shelf accountability from single contract partners.
- Food Service:Out-of-home consumption recovery drives demand for portion-controlled and extended shelf-life formats, with contract operators adapting production lines for food service pack sizes.
- E-commerce:Direct-to-consumer fulfillment requires damage-resistant packaging and single-unit picking compatibility, forcing retrofit investments in case-packing and palletization systems.
- Wholesalers:Traditional intermediary layers face bypass pressure as Netherlands and Belgium discounters seek direct contract relationships, compressing margin extraction points in distribution.
Primary demand source: Retail Chains. Channel climbing fastest: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Hamburg-Munich corridor anchors European food contract manufacturing, with dense clusters of bakery and dairy operations generating knowledge spillovers and shared logistics infrastructure that lower unit costs for regional challengers.
Germany
Bavaria and North Rhine-Westphalia concentrate powder-based infant nutrition and sports formulation capacity under EFSA oversight. The EU Green Deal packaging mandates accelerate substrate conversions faster than equipment depreciation cycles permit. Munich hosts validated dry-blending operations serving pan-European brand owners.
Netherlands
Randstad logistics hubs enable chilled distribution networks for plant-based dairy alternatives requiring cold-chain credentials. REACH chemical compliance obligations force adhesive and coating reformulations across Rotterdam and Amsterdam production zones. Discounters here seek direct contract relationships bypassing traditional wholesaler layers.
Italy
Northern Italian industrial zones around Milan and Bologna cluster aseptic filling line builders, creating equipment supply bottlenecks for capacity expansion timelines. EMA food-contact material guidelines elevate qualification costs that exclude subscale operators. Emilia-Romagna maintains structural demand for premium glass packaging in pharmaceutical-adjacent nutrition.
France
Île-de-France retail buyers penalize fragmented supply chains in vendor scorecards, consolidating supplier bases and demanding end-to-end formulation-to-shelf accountability. ANSM enforces substance restrictions on phthalate-based plasticizers in food-contact applications. Auvergne-Rhône-Alpes harbors artisan-positioned premium co-manufacturing commanding price premiums.
Poland
Warsaw and Łódź industrial zones lack scaled ambient and chilled co-packing infrastructure for pan-European brand owners seeking lower labor-cost production alternatives. EU Packaging and Packaging Waste Regulation recycled content minimums reshape substrate selection ahead of local compliance deadlines. Knowledge spillovers from German corridor operations remain limited.
Europe Food Contract Manufacturing and Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with private label specialists capturing deeper pools than execution-only co-packers. The vendor base organizes into three strategic archetypes: scale-driven pan-European networks, flexible short-run specialists, and powder-based formulation experts. M&A activity concentrates supplier bases for retailer scorecard compliance, while capacity expansion timelines stretch due to equipment builder concentration in northern Italy.
Among German-based operators, SternMaid GmbH & Co. KG and STOCKMEIER Food GmbH & Co. KG occupy positions within powder-based contract manufacturing archetypes, reflecting the GmbH & Co. KG structure common to family-held industrial enterprises. Hearthside Europe represents scale-driven network players leveraging pan-European production footprints. Alexir Co-Packers Limited exemplifies flexible short-run specialists serving challenger brands in Netherlands and Belgium markets.
| Leading Market Players |
|---|
| A and S Packing Company Limited |
| Hearthside Europe |
| Romix Foods Limited |
| STOCKMEIER Food GmbH & Co. KG |
| SternMaid GmbH & Co. KG |
| Aimia Foods Ltd |
| Alexir Co-Packers Limited |
| Budelpack Poortvliet BV |
| Alphapak International Limited |
| Others |
Supply & Pricing Matrix
Family-held GmbH & Co. KG structures across German powder specialists and Dutch co-packers constrain aggressive price competition while embedding long-term supplier relationships that resist spot-market commoditization. This ownership pattern reinforces supply discipline through patient capital allocation and generational succession planning rather than quarterly earnings pressure.
Pricing Analysis
Outcome-based pricing anchored to shelf-life extension and yield guarantees dominates private label contracts, where German discounters pay premiums for end-to-end formulation accountability. Three-tier pricing structure across premium, standard, and economy levels separates IFS-BRCGS dual-certified operators from single-audit facilities and commodity execution-only packers. Cost compression in standard-tier beverage co-packing is intensifying because rPET feedstock volatility squeezes fixed-contract margins. Challenger brands in Netherlands and Belgium exhibit highest price sensitivity, while infant nutrition multinationals prioritize analytical testing capacity over unit cost.
Supply Chain Analysis
Road freight costs from Hamburg-Munich corridor clusters to Randstad distribution hubs shape total landed cost calculations for pan-European brand owners. Supply concentrates in Germany, Netherlands, and northern Italy, with equipment builders around Milan and Bologna creating capacity expansion bottlenecks. Raw material flows draw from rPET and rPP recyclers, barrier-coated paper mills, and phthalate-free adhesive suppliers. Single-source vulnerability sits with aseptic filling line builders concentrated in southern Germany. Distribution runs through Rotterdam and Hamburg port-centric logistics zones with shared cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic filling line builder concentration in northern Italy props pricing power across beverage and dairy segments, creating structural supply constraints that favor qualified incumbents.
For Market Incumbents: Hedge against REACH chemical compliance disruption by pre-qualifying alternative coating chemistries ahead of ECHA enforcement phases. Secure backward integration into mono-material film extrusion to capture margin pools from EU Packaging and Packaging Waste Regulation substrate conversions. Prioritize automation technician apprenticeships in Rhine-Ruhr zones to defuse maintenance bottlenecks. For New Entrants and Emerging Players: Launch via direct-to-retailer channel models targeting Netherlands and Belgium discounters seeking wholesaler bypass. Poland and Romania present the most penetrable geographies for ambient and chilled co-packing infrastructure gaps. Emphasize flexible short-run capabilities with rapid product iteration support for challenger brands. For Investors and Strategic Acquirers: Distressed-cycle entries favor powder-based contract manufacturing specialists in Bavaria with validated dry-blending capacity and EFSA-compliant testing infrastructure. Long-term viability hinges on single-source accountability capabilities meeting retailer consolidation demands. Monitor IFS-BRCGS dual certification backlog durations as inflection signal for capacity utilization stress.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Film Transition | Aligns co-packer offerings with EU Green Deal recycled content mandates and retailer scorecards. |
| Dual Certification Investment | IFS-BRCGS combined audits qualify operators for German discounter and French supermarket private label contracts. |
| Eastern European Capacity Buildout | Poland and Romania infrastructure gaps offer lower labor-cost alternatives for pan-European brand owners. |
| Smart Packaging Integration | Printed electronics and time-temperature indicators create premium tiers for pharmaceutical-adjacent nutrition products. |
| Direct-to-Retailer Channel Bypass | Netherlands and Belgium discounters seek contract relationships eliminating traditional wholesaler margin extraction. |
Research Methodology
Independent corroboration across co-packing operations executives, retail category buyers, equipment supplier technical directors, and EFSA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from EU Packaging and Packaging Waste Regulation implementation timelines, ECHA substance restriction notifications, customs trade data for food-contact materials, and IFS-BRCGS audit publication records. Bottom-up capacity assessments at Hamburg-Munich corridor facilities triangulate against top-down market size estimates.
Historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-regulation implementation trajectories across the projection horizon. Segmentation dimensions modeled include service type integration depth, perishability profile by product category, substrate technology generation, and channel disintermediation intensity. CAGRs were derived from installed equipment depreciation cycles overlaid with regulatory compliance deadline clustering. Industry-specific inputs incorporate aseptic filling line lead times and REACH reformulation pipeline durations.
Recycled polymer feedstock price spikes, ECHA substance restriction list expansions, and automation technician labor shortages are the dominant revision risks. Forecasts reflect assumptions about regulatory implementation pacing and equipment supplier delivery reliability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Hot Drinks Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Food Partition Trays Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Fresh Food Packaging Market