
 Food and Drink Packaging Market | 2026-2036
Food and Drink Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Drink Packaging Market Foresight
Consolidation among North American beverage manufacturers is rebalancing contract negotiations toward multi-year, high-volume supply agreements. Berry Global leverages its blown-film expertise to sustain share in flexible dairy packaging. WestRock anchors North American corrugated beverage tray production through integrated boxboard mills. Smurfit Kappa Group competes aggressively in European fresh-produce carton formats.
Food and drink packaging encompasses protective enclosures, containment systems, and preservation barriers engineered from multi-layer substrates, with oxygen transmission rates below 0.1 cc/m²/day for sensitive applications, designed to extend shelf life and ensure supply-chain integrity from processor to consumer. Paperboard cartons dominate ambient liquid categories due to established recycling streams and lightweight logistics economics, while aluminum cans are displacing glass in craft beverage segments where portability and chill-retention matter. Plastic pouches are capturing share in condiment and baby-food segments where material efficiency and microwave compatibility drive format switching.
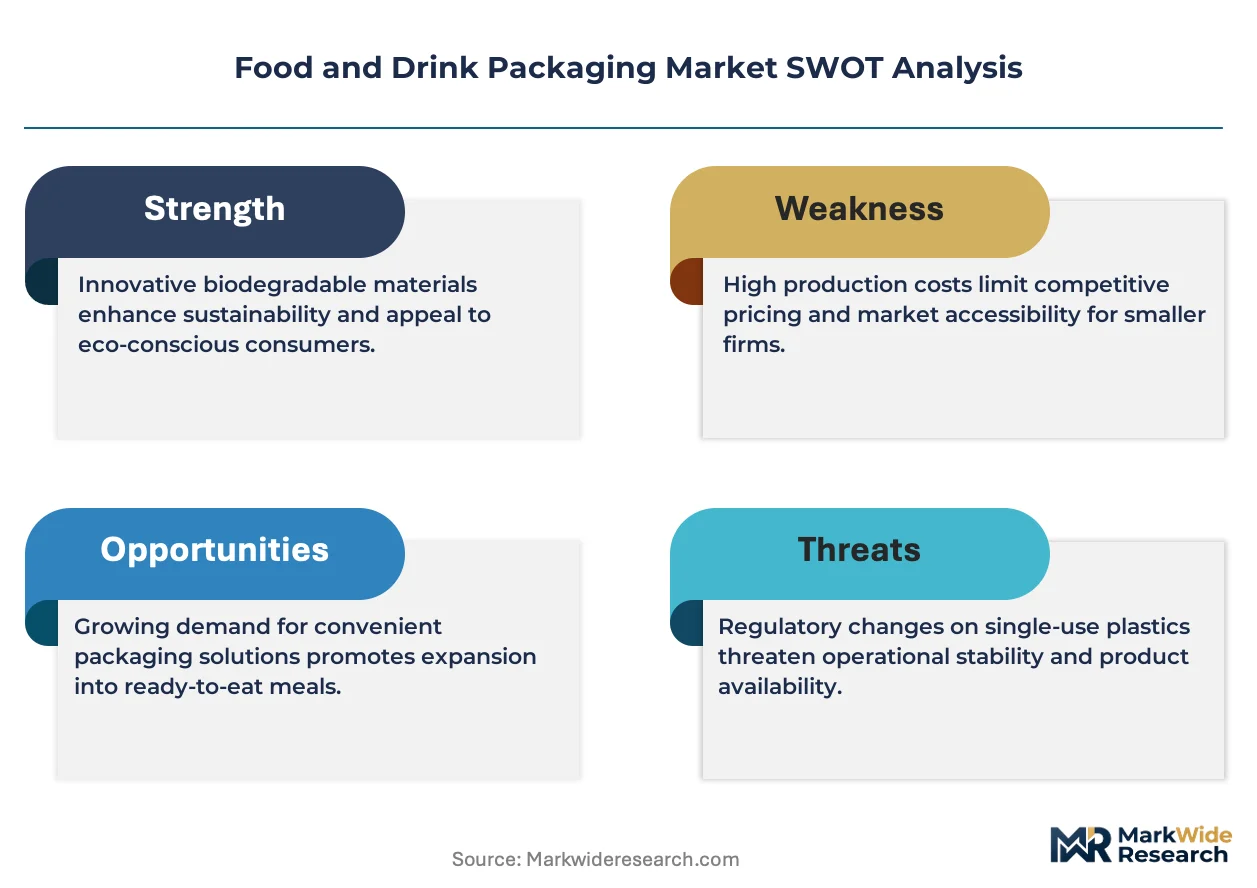
The EPA governs municipal recycling contamination thresholds in the United States, while the EU Green Deal mandates phased reductions in packaging waste per capita, and India's BIS enforces migration limits for food-contact plastics. These frameworks are redirecting capital toward mono-material designs and certified compostable substrates that ease compliance burden. Stakeholders must monitor evolving extended-producer-responsibility fee structures to calibrate material substitution timelines against cost pass-through capacity.
Market Dynamics
Recycled-content mandates across major economies are forcing material substitution timelines that outpace existing reprocessing infrastructure capacity, compressing supplier margins while redirecting capital toward mono-material R&D and certified compostable substrate qualification.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Phased recycled-content floors for plastic packaging are pulling forward investment in chemical recycling and advanced mechanical reprocessing lines across member states.
- India cold-chain buildout:Branded dairy and frozen food processors are procuring insulated corrugated and multi-layer barrier films at volumes that justify localized extrusion capacity.
- Aluminum can format migration:Craft beverage producers are specifying two-piece drawn-and-ironed bodies for chill-retention and logistics cube efficiency, displacing glass in on-premise and outdoor consumption occasions.
Market Restraints
- Recycled PET flake scarcity:Collection infrastructure gaps in the United States and inconsistent bale quality are inflating rPET premiums versus virgin resin, squeezing converter margins on beverage bottle contracts.
- Chinese substrate concentration:Flexible packaging substrate supply clusters in Zhejiang and Guangdong provinces expose converters to freight volatility and tariff uncertainty on laminated rollstock.
- Multi-layer incompatibility:Existing mechanical recycling streams cannot separate polyethylene-nylon-EVOH barrier films, forcing landfill diversion or energy recovery for high-performance pouches.
Strategic Opportunities
- Indonesia archipelago distribution:Instant noodle and condiment brands are piloting retort pouch formats with extended ambient shelf life to bypass refrigerated last-mile constraints across 17,000 islands.
- FSSAI migration limit alignment:Harmonized food-contact compliance standards are enabling Indian converters to supply GCC markets with single qualification runs, reducing technical barrier costs.
- Digital printing convergence:HP Indigo and Xeikon press installations at mid-size folding carton plants are compressing SKU changeover times from hours to minutes, supporting micro-lot personalization for craft spirits.
Industry Challenges
- Mono-material engineering talent:Polymer scientists capable of redesigning barrier properties without adhesive lamination layers command compensation premiums that smaller converters cannot match.
- Compostable certification timelines:TÜV Austria and BPI validation cycles for home and industrial compostable films extend 18-24 months, delaying revenue recognition on sustainable format launches.
- Legacy heat-seal retrofit complexity:Existing form-fill-seal lines require jaw and temperature profile reconfiguration to run new-generation bio-based sealant webs without leakage rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Drink Packaging Market |
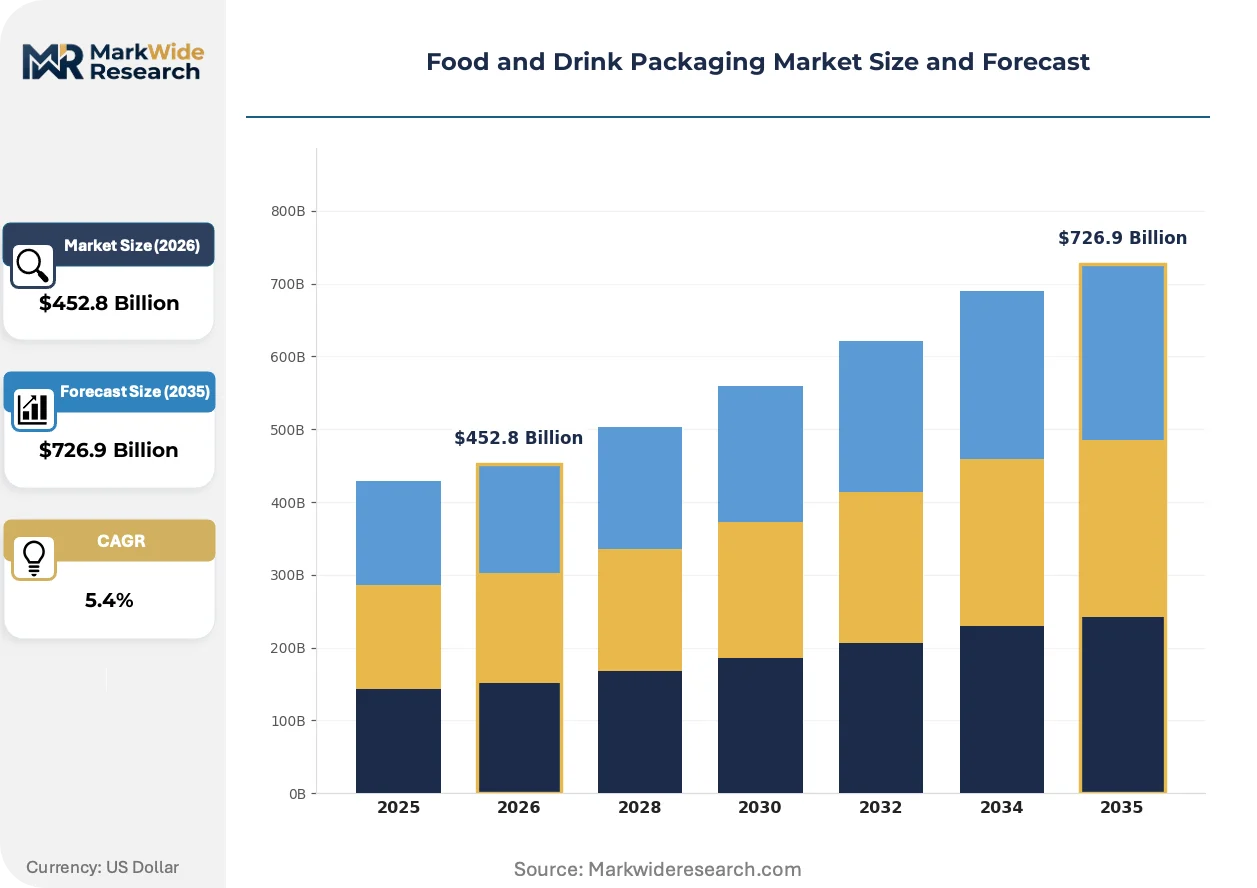
| Market Size in 2026 | $452.8 Billion |
| Market Size in 2035 | $726.9 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
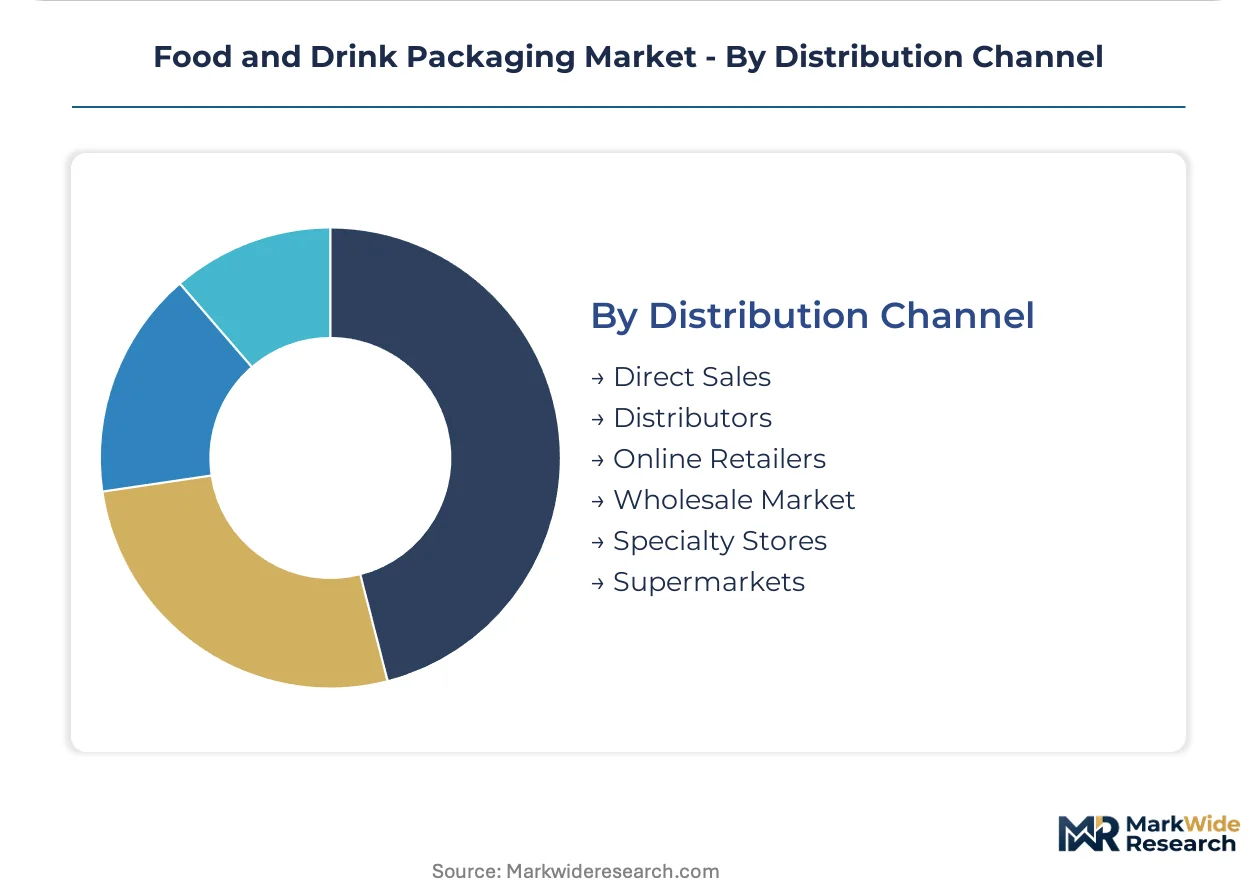
| Segmentation | Material Type: Plastic, Glass, Metal, Paperboard, Biodegradable Polymers, Aluminum Packaging Format: Bottle, Can, Pouch, Carton, Tray, Wrapper End User Type: Food Processing Companies, Beverage Manufacturers, Quick Service Outlets, Catering Services, Food Distributors, Retailers Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Market, Specialty Stores, Supermarkets |
| Companies Covered | Berry Global, WestRock, Ball Corporation, Graphic Packaging International, Smurfit Kappa Group, Crown Holdings, International Paper, Silgan Holdings, Ardagh Metal Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Drink Packaging Market Shifts & Advancements
Active and intelligent packaging systems are migrating from premium pharmaceuticals into mass-market food and beverage applications, while regulatory pressure on single-use plastics accelerates format experimentation beyond conventional substrate boundaries.
Machine vision-guided robotic pick-and-place systems are automating quality inspection and palletization at European dairy packaging lines, with Arla Foods and FrieslandCampina deploying these configurations for 24-hour continuous operation. Adoption rates in North American beverage co-packing facilities lag by approximately three years due to union negotiation complexity and legacy line amortization schedules. The technology is automating defect rejection and case packing at speeds that eliminate manual handling bottlenecks during seasonal volume spikes.
REACH restrictions on per- and polyfluoroalkyl substances are prohibiting fluoropolymer grease barriers in molded fiber foodservice containers across EU member states, with ECHA enforcement timelines accelerating reformulation deadlines into 2026. Industrial consequence includes rushed qualification of alternative bio-wax and clay coatings that sacrifice some oil resistance for regulatory compliance. Fresh-produce clamshell and quick-service salad bowl segments are most affected, with converters in Germany and the Netherlands reporting 15-20% yield loss during initial barrier coating trials.
Direct-store-delivery beverage distributors are consolidating supplier relationships from twelve-plus regional converters to three national contract holders, compressing negotiation cycles and demanding real-time inventory visibility through EDI integration. This concentration is displacing fragmented procurement patterns that previously accommodated local brand variations and seasonal promotional formats. The shift is most visible in the United States Southeast, where Coca-Cola and Pepsi bottling system reorganization has eliminated independent can and label sourcing for mid-tier regional brands.
Food and Drink Packaging Market Segmentation
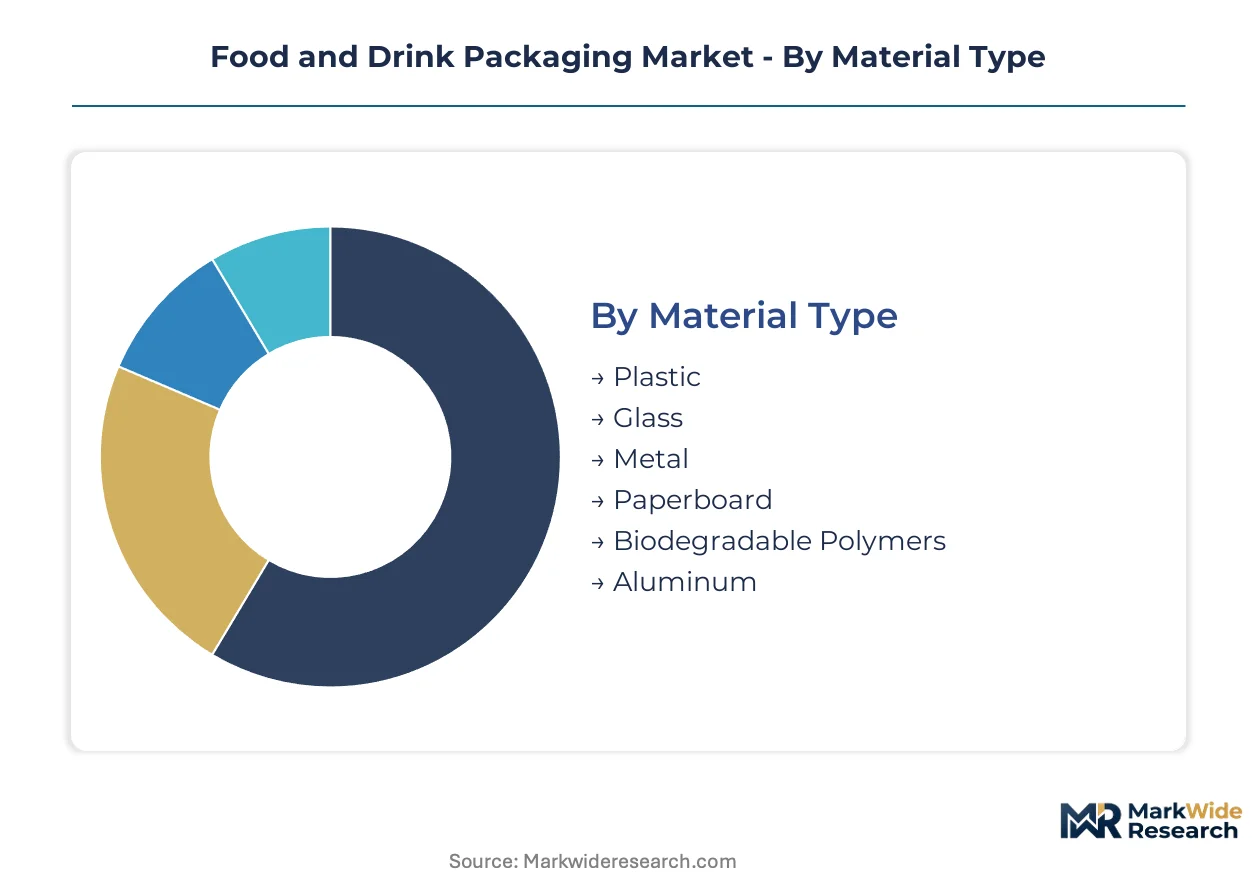
Food and drink packaging segmentation reveals divergent margin profiles across substrate classes and format geometries. Material selection dictates barrier performance and recycling pathway viability. End-user procurement scale determines converter contract structure and volume commitment terms.
Material Type:
Plastic commands the highest shipment volumes while aluminum and biodegradable polymers capture premium positioning through sustainability credentials and performance differentiation.
- Plastic:Multi-layer polyethylene terephthalate and polypropylene laminates dominate flexible and rigid applications with oxygen transmission rates below 0.1 cc/m²/day for sensitive products. Beverage bottlers in the United States and India are the largest procurement base, though recycled-content mandates from the EPA and BIS are forcing rapid substrate redesign timelines that outpace reprocessing infrastructure expansion.
- Aluminum:Two-piece drawn-and-ironed can bodies deliver superior chill-retention and logistics cube efficiency versus glass alternatives. Craft beverage producers across Germany, Brazil, and Japan specify this format for outdoor consumption occasions, displacing traditional bottle formats where portability drives purchasing decisions.
- Glass:Premium spirits and wine categories retain this substrate for brand heritage signaling and inert contact surface properties.
- Metal:Three-piece welded food cans sustain shelf-stable vegetable and protein segments with established retort compatibility.
- Paperboard:Liquid cartons leverage established recycling streams and lightweight logistics economics for ambient dairy and juice distribution.
- Biodegradable Polymers:PLA and PHA formulations qualify for industrial composting certification under TÜV Austria and BPI standards.
Today's leader: Plastic. Tomorrow's challenger: Aluminum.
Packaging Format:
Format geometry determines filling line compatibility, palletization density, and retail shelf space economics across ambient and chilled supply chains.
- Pouch:Stand-up and flat pouch configurations with spout fitments reduce material weight versus rigid alternatives by 60-70% while enabling microwave reheating. Condiment brands in Indonesia and baby-food processors in India are expanding procurement as mono-material barrier films reach commercial qualification.
- Carton:Gable-top and brick formats integrate spouts, straws, and resealable closures for ambient liquid distribution. European dairy processors at Arla Foods and FrieslandCampina deploy these for 24-hour continuous operation with automated case packing.
- Bottle:PET and HDPE blow-molded containers retain dominance in carbonated and still beverage categories.
- Can:Two-piece aluminum and steel formats displace glass in craft beer and ready-to-drink cocktail segments.
- Tray:Corrugated and molded fiber configurations protect fresh produce through direct-store-delivery networks.
- Wrapper:Flow-wrap and overwrap films provide primary containment for confectionery and baked goods.
Pouch formats gain share fastest in emerging markets with refrigerated last-mile constraints.
End User Type:
Procurement scale separates national contract holders from fragmented regional sourcing patterns.
- Beverage Manufacturers:Consolidated bottling system reorganization in the United States Southeast has compressed supplier relationships from twelve-plus regional converters to three national contract holders. Coca-Cola and Pepsi bottlers now demand real-time inventory visibility through EDI integration, eliminating independent can and label sourcing for mid-tier regional brands.
- Food Processing Companies:Branded dairy and frozen food processors in India are procuring insulated corrugated and multi-layer barrier films at volumes justifying localized extrusion capacity investment.
- Quick Service Outlets:Molded fiber foodservice container demand faces reformulation pressure as REACH restrictions prohibit fluoropolymer grease barriers.
- Catering Services:Bulk format procurement concentrates in institutional channels with standardized portion specifications.
- Food Distributors:Private-label packaging programs require flexible SKU changeover capabilities.
- Retailers:Own-brand development drives specification of differentiated format geometries.
Beverage manufacturers anchor current volume. Food processing companies represent the steepest expansion trajectory.
Distribution Channel:
Channel structure determines lead time requirements, order minimums, and technical service intensity.
- Direct Sales:National beverage and dairy processors negotiate multi-year supply agreements with dedicated technical service teams. Berry Global and WestRock anchor these relationships through integrated mill and extrusion assets that guarantee volume commitments and specification compliance.
- Distributors:Regional converter networks serve mid-tier food processors with fragmented procurement patterns and seasonal promotional format requirements.
- Supermarkets:Private-label packaging specifications demand rapid SKU changeover capabilities supported by digital press installations.
- Online Retailers:E-commerce fulfillment requirements drive protective packaging specifications for last-mile durability.
- Wholesale Market:Bulk format aggregation serves independent foodservice operators.
- Specialty Stores:Craft and premium positioning requires micro-lot personalization capabilities.
Direct sales capture the premium tier. Digital-enabled channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's cold-chain buildout is outpacing Germany's recycling infrastructure expansion, while the United States consolidates beverage bottling systems at a faster clip than China's substrate manufacturing clusters.
United States
Craft beverage producers are migrating toward aluminum can formats for outdoor consumption occasions. EPA recycling contamination thresholds are tightening municipal collection standards. Southeast bottling system reorganization has compressed supplier relationships from twelve-plus regional converters to three national contract holders.
Germany
Fresh-produce carton demand is accelerating as retailers prioritize shelf-stable distribution formats. ECHA enforcement timelines are accelerating PFAS-free barrier coating reformulation into 2026. Converters in the Netherlands and Germany are reporting yield loss during initial bio-wax coating trials for molded fiber containers.
India
Branded dairy and frozen food processors are procuring insulated corrugated and multi-layer barrier films at volumes justifying localized extrusion capacity. FSSAI migration limit alignment is enabling Indian converters to supply GCC markets with single qualification runs. Maharashtra and Gujarat are anchoring flexible packaging substrate manufacturing clusters.
Indonesia
Instant noodle and condiment brands are piloting retort pouch formats with extended ambient shelf life. The archipelago's 17,000 islands create refrigerated last-mile constraints that favor ambient-stable packaging. Java-based converters are expanding capacity for spout-fitment pouch assembly.
Japan
Craft beverage segments are specifying two-piece drawn-and-ironed aluminum bodies for chill-retention properties. METI industrial standards are guiding mono-material barrier film qualification timelines. Osaka and Nagoya manufacturing clusters are automating quality inspection through machine vision-guided robotic systems.
Food and Drink Packaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across substrate classes and format geometries. The vendor base organizes into three tiers: integrated mill operators with captive pulp and resin supply, mid-scale converters with regional extrusion assets, and specialized equipment-technology licensors. Consolidation is compressing negotiation cycles toward multi-year supply agreements. Capacity expansion is concentrating in India and Southeast Asia to serve localized cold-chain buildout.
Among North American integrated packaging suppliers, Berry Global exemplifies blown-film expertise in flexible dairy applications, while WestRock anchors corrugated beverage tray production through integrated boxboard mill assets. Smurfit Kappa Group occupies a position within European fresh-produce carton formats. These three represent distinct archetypes: resin-based flexible packaging, fiber-based rigid containment, and recycled-content corrugated solutions.
| Leading Market Players |
|---|
| Berry Global |
| WestRock |
| Ball Corporation |
| Graphic Packaging International |
| Smurfit Kappa Group |
| Crown Holdings |
| International Paper |
| Silgan Holdings |
| Ardagh Metal Packaging |
| Others |
Supply & Pricing Matrix
Polypropylene resin indices cascading from Zhejiang and Gujarat petrochemical complexes transmit directly into converter pricing tiers across flexible packaging contracts. Buyers in beverage and dairy segments absorb differential pass-through rates depending on volume commitment scale and specification complexity.
Pricing Analysis
Capacity additions in India and Indonesia are reshaping price floors for multi-layer barrier films and spout-fitment pouches. Three-tier pricing structure across premium certified-compostable, standard recyclable, and economy virgin-resin tiers separates sustainability-grade converters from commodity suppliers. Cost compression in standard-grade laminates is intensifying because recycled PET flake scarcity inflates rPET premiums versus virgin resin. National contract holders at Coca-Cola and Pepsi bottling systems exhibit lowest price sensitivity due to multi-year volume guarantees, while mid-tier regional brands face acute margin pressure from consolidation-driven supplier reduction.
Supply Chain Analysis
Polymer engineering talent shortages in Maharashtra and Gujarat extrusion corridors constrain qualified technician availability for mono-material barrier film production. Raw material supply draws from Saudi petrochemical complexes for virgin resin, Chinese Zhejiang province for laminated rollstock, and domestic Indian collection streams for recycled flake. Single-source vulnerability concentrates in fluoropolymer grease barrier alternatives as REACH restrictions force rushed bio-wax coating qualification. Distribution runs through direct-store-delivery beverage networks and insulated corrugated cold-chain channels for dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation compounds demand for compliant substrate alternatives, pulling forward investment timelines across member states and export-oriented converters.
For Market Incumbents: Anticipate margin compression from recycled-content mandates by accelerating captive chemical recycling capacity in Germany and the Netherlands. Secure multi-year rPET offtake agreements before flake scarcity intensifies. Certification investment in TÜV Austria and BPI compostable validation creates pricing power versus uncertified competitors facing 18-24 month qualification delays. For New Entrants and Emerging Players: Begin with Indonesia's archipelago distribution challenge, where 17,000 islands create refrigerated last-mile constraints favoring ambient-stable retort pouch formats. Indian dairy cold-chain buildout represents the most penetrable geography for insulated corrugated and barrier film supply. Go-to-market through FSSAI-aligned migration limit qualification enables single-run supply to GCC markets without duplicate testing costs. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale converters possessing regional extrusion assets in India and Southeast Asia but lacking national contract holder status. Long-term viability hinges on backward integration into resin reprocessing or captive pulp supply within a five-to-ten year capability buildout. Watch for EU member state enforcement timelines on PFAS-free coatings as inflection indicator for alternative barrier technology adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Capacity Expansion | EU recycled-content mandates pull forward investment in advanced reprocessing lines across Germany and the Netherlands. |
| Mono-Material Barrier Film Qualification | BPI and TÜV Austria certification cycles create 18-24 month competitive moats for early movers in pouch formats. |
| Backward Integration into rPET Collection | Captive supply of recycled flake insulates margins from collection infrastructure gaps inflating premiums. |
| Digital Press Installation at Mid-Scale Plants | HP Indigo and Xeikon deployments compress SKU changeover times for micro-lot craft spirits personalization. |
| Cold-Chain Corrugated Localization | Indian dairy processor procurement volumes justify extrusion capacity investment in Maharashtra and Gujarat clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with packaging converters, beverage procurement directors, dairy supply chain managers, and regulatory compliance officers with secondary validation. Bottom-up shipment data from customs records, BIS migration limit filings, and EPA municipal recycling reports anchored volume estimates, while top-down expenditure patterns from SEC 10-K disclosures of integrated mill operators informed value projections.
Segment-weighting applied material type, packaging format, and end-user procurement scale as primary dimensions across the analysis window, with regional regulatory cluster and cold-chain infrastructure maturity as secondary stratifiers. CAGRs derived from curve-fitting historical shipment trajectories against announced capacity expansion timelines and mandate enforcement schedules. Industry-specific inputs included oxygen transmission rate specifications for barrier applications and compostable certification validation cycle durations.
Several conditions sit outside the modeled scope, including unannounced tariff adjustments on Chinese laminated rollstock, abrupt ECHA enforcement acceleration beyond published timelines, and breakthrough mono-material barrier technologies achieving sub-0.1 cc/m²/day performance without adhesive lamination. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Fast Food Containers Market
Food Packaging
Foam Food Container Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Sugar Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Meal Kit Packaging Market