
 Probiotics Packaging Market | 2026-2036
Probiotics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics Packaging Market Analytics
Pharmaceutical buyers are unwinding their historical dominance over packaging specification as dietary supplement and functional food brands gain procurement authority. Amcor plc leverages its pharmaceutical barrier film heritage to compete in high-oxygen-barrier sachet formats for ambient-stable strains. Berry Global Group, Inc. anchors North American supply with in-house thermoforming capacity for probiotic bottles and single-serve cups.
Probiotics packaging encompasses primary and secondary containment systems engineered to maintain viable colony-forming units through controlled oxygen transmission rates, typically below 0.1 cc/m²/day, and moisture vapor barriers to prevent hydrolytic degradation of sensitive bacterial cultures. Sachet formats lead unit volume due to dose-level portioning and minimal material per serving, though blister packs capture margin concentration where pharmaceutical serialization requirements apply. Plastic materials dominate substrate selection, yet paper-based structures grow fastest where converters achieve comparable barrier performance through metallization or bio-coating layers.
The FDA's dietary supplement cGMPs and the EU's MDR framework for medical-grade probiotics both mandate stability documentation tied directly to packaging performance claims, creating compliance-driven demand for validated barrier systems. EFSA's health claim authorization process further tightens the link between packaging integrity and substantiated shelf-life declarations. Stakeholders must monitor how emerging state-level extended producer responsibility laws in the United States reshape material specifications before next-generation mono-material barrier platforms achieve commercial scale.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation mandates 70% material recovery targets by 2030, forcing converters to abandon multi-layer laminates and accelerate mono-material barrier development. Dietary supplement brands now wield procurement authority over pharmaceutical incumbents, rewriting specification standards for oxygen-barrier sachets and moisture-resistant bottles.
Growth Catalysts
- Shelf-Stable Strain Demand:Ambient-stable probiotic formulations from dietary supplement brands require oxygen transmission rates below 0.1 cc/m²/day, driving specification upgrades across sachet and blister formats.
- EFSA Health Claim Authorization:The European Food Safety Authority's substantiation requirements tie packaging integrity directly to shelf-life declarations, creating compliance-driven demand for validated barrier systems.
- Germany's Pharmaceutical-Grade Concentration:German probiotic manufacturers command premium barrier specifications, pulling converter R&D investment toward high-performance mono-material structures.
Market Restraints
- Aluminum Oxide Coating Volatility:Supply constraints in metallized film substrates create input cost instability for converters developing paper-based barrier alternatives.
- European Converter Consolidation:Mono-material barrier expertise concentrates among a limited pool of specialized film extruders, creating supply concentration risk for mid-tier probiotic brands.
- MDR Compliance Friction:The EU's Medical Device Regulation imposes stability documentation burdens on medical-grade probiotic packaging, extending validation timelines for cross-over suppliers.
Strategic Opportunities
- India's Dietary Supplement Expansion:FSSAI regulatory modernization and rising functional food consumption create white space for oxygen-barrier sachet formats in Mumbai and Bangalore markets.
- Bio-Coating Convergence:The intersection of cellulose nanofiber substrates and enzymatic barrier deposition enables paper-based structures to approach plastic-grade oxygen protection.
- US State EPR Legislation:Extended producer responsibility laws in California and Oregon mandate material recovery, creating regulatory tailwind for mono-material platforms ahead of federal standardization.
Industry Challenges
- Barrier Metrologist Scarcity:Validating oxygen transmission and moisture vapor transmission rates for novel mono-materials requires specialized analytical chemistry expertise that outpaces current training pipelines.
- Legacy Thermoforming Retooling:Converters with established pharmaceutical bottle lines face capital intensity in retrofitting equipment for thinner-gauge, higher-barrier mono-material sheet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics Packaging Market |
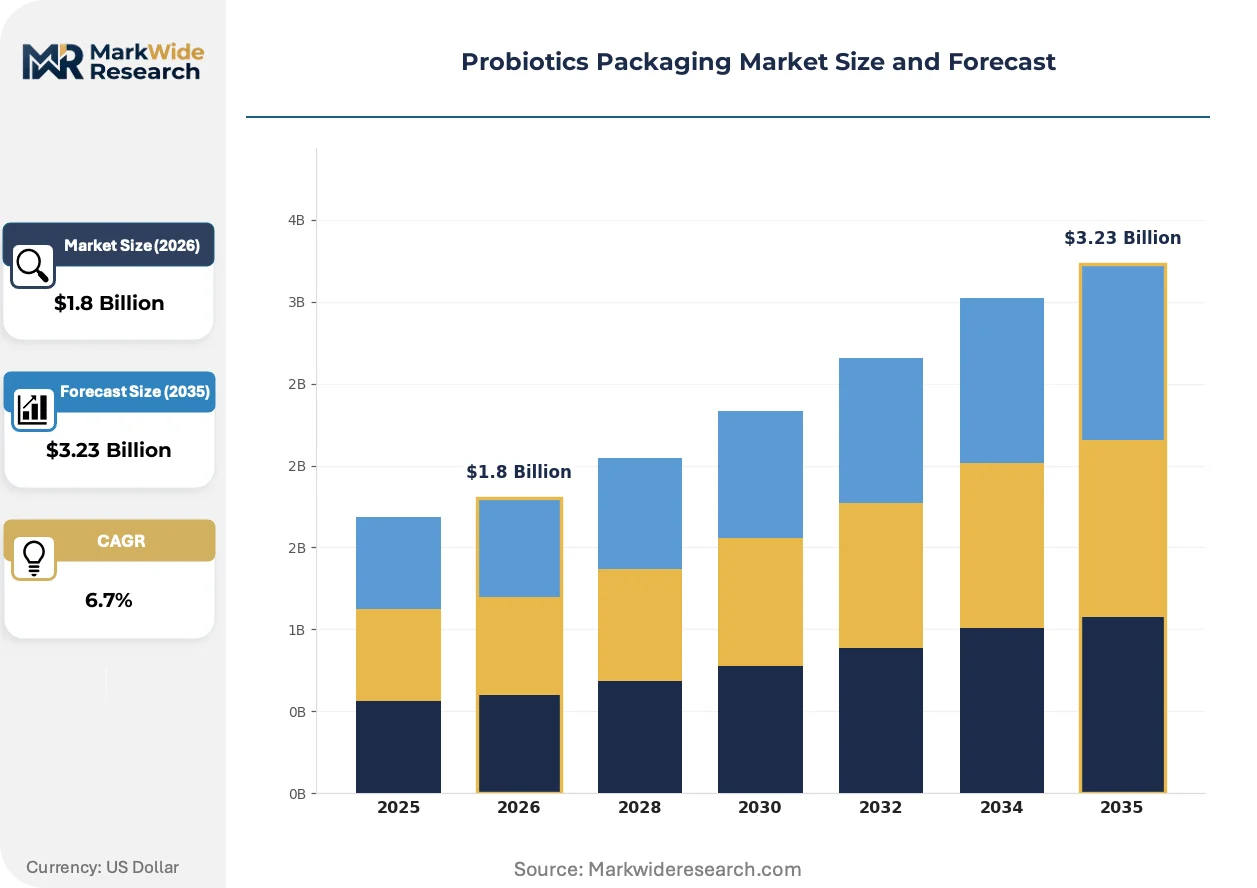
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Sachets, Jars, Blister Packs Material: Plastic, Glass, Aluminum, Paper End User: Healthcare, Food & Beverage, Dietary Supplements, Pharmaceutical Distribution Channel: Online, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | DS Smith Plc, Sealed Air Corporation, Amcor plc, Huhtamaki Oyj, Sonoco Products Company, Berry Global Group, Inc., Mondi Group, Tetra Pak International S.A., AptarGroup, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics Packaging Market Evolving Landscape
Active barrier technologies and substrate metallization are rewriting material hierarchies in probiotic containment. Regulatory frameworks now embed packaging performance into product authorization, while buyer-side procurement consolidation accelerates specification standardization.
High-barrier metallized paper substrates are supplanting conventional aluminum-foil laminates in ambient-stable probiotic sachets. German and Dutch dietary supplement brands have accelerated qualification timelines for these structures from 18 months to 8 months. The shift is compressing demand for multi-layer plastic laminates and redirecting converter capex toward vacuum metallization and bio-coating deposition equipment.
The EU's Packaging and Packaging Waste Regulation imposes recycled content mandates and extended producer responsibility fees on non-recoverable multi-material structures. Converters serving pharmaceutical-grade probiotic markets must now document end-of-life recovery pathways or face material exclusion from EU distribution. German and French probiotic brands are responding by pre-qualifying mono-material barrier films ahead of 2030 compliance deadlines.
Direct-to-consumer probiotic subscription models are fragmenting traditional pharmaceutical distribution channels. These brands specify portion-controlled, single-serve formats with premium unboxing aesthetics, displacing bulk bottle procurement through retail pharmacy networks. The behavioral shift is most visible in US and UK urban markets where wellness-focused consumers prioritize convenience over pharmacy-channel familiarity.
Probiotics Packaging Market Segmentation
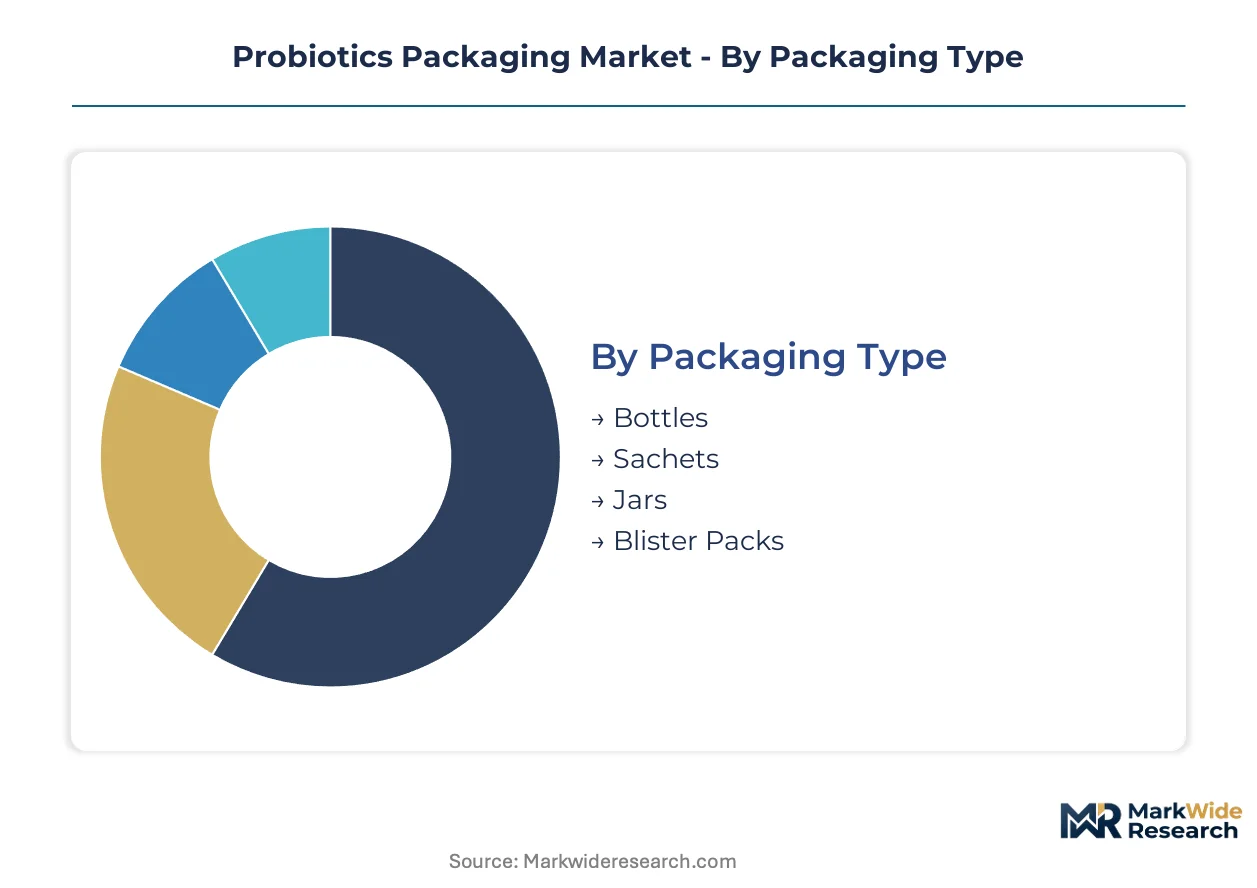
Probiotic packaging segmentation reflects divergent barrier requirements across regulatory regimes. FDA cGMPs, EU MDR, and FSSAI stability mandates each drive distinct specification clusters that reshape material selection and format preference.
Packaging Type:
FDA dietary supplement regulations and EU MDR stability documentation requirements create divergent format specifications for ambient-stable strains.
- Sachets:Multi-layer foil or metallized film structures achieve oxygen transmission rates below 0.1 cc/m²/day for single-serve dose protection. Dietary supplement brands in Germany and the United States specify these for direct-to-consumer subscription models requiring extended shelf stability.
- Bottles:HDPE and PET containers with desiccant closures dominate pharmaceutical-grade probiotic distribution through pharmacy channels. German manufacturers command premium barrier specifications including induction-sealed liners and nitrogen flush capabilities.
- Blister Packs:Cold-form aluminum or high-barrier PVC structures satisfy EU MDR serialization requirements for medical-grade probiotics.
- Jars:Wide-mouth PET or glass containers serve bulk powder formats in health store retail.
Sachets handle the majority of throughput; bottles are the fastest mover on share.
Material:
Cost tier differentiation separates premium barrier systems from commodity containment as mono-material development accelerates under EU packaging waste mandates.
- Plastic:Multi-layer EVOH and nylon coextrusions deliver pharmaceutical-grade oxygen and moisture barriers. German and Dutch converters concentrate R&D investment here for 2030 regulatory compliance.
- Paper:Metallized or bio-coated cellulose structures are gaining qualification for ambient-stable sachets as aluminum oxide coating deposition improves. European dietary supplement brands have compressed validation timelines from 18 months to 8 months.
- Aluminum:Cold-form foil and blister lidding remain essential for EU MDR-compliant medical-grade probiotics requiring absolute light and oxygen exclusion.
- Glass:Amber and cobalt blue bottles serve premium positioning in pharmacy and health store channels where perceived purity drives purchase decisions.
Plastic commands current volume leadership; paper is climbing the fastest as converters achieve barrier parity.
End User:
Customer type determines whether packaging specifications prioritize regulatory compliance, convenience, or premium aesthetics.
- Dietary Supplements:Oxygen-barrier sachets and single-serve sticks dominate as brands displace pharmaceutical procurement authority. US and UK direct-to-consumer subscription models specify portion-controlled formats with unboxing aesthetics.
- Pharmaceutical:Blister packs and high-barrier bottles satisfy FDA cGMPs and EU MDR stability documentation requirements. German manufacturers anchor demand for validated barrier systems with serialized traceability.
- Food & Beverage:Probiotic-fortified yogurts and beverages require refrigerated supply chain packaging with modified atmosphere capabilities.
- Healthcare:Clinical nutrition and enteral feeding probiotics specify sterile barrier systems with aseptic fill compatibility.
Dietary supplements drive the steepest expansion trajectory; pharmaceutical retains the highest barrier specification premiums.
Distribution Channel:
Geography and fulfillment velocity determine format sizing, barrier intensity, and shelf-life claims.
- Online:Direct-to-consumer shipments require robust barrier protection against temperature excursions and humidity during last-mile delivery. US subscription brands specify multi-layer sachets with desiccant integration.
- Pharmacies:Serialized blister packs and bottles with tamper-evident closures satisfy EU MDR and FDA track-and-trace requirements. German pharmacy networks demand pharmaceutical-grade stability documentation.
- Supermarkets:Shelf-ready secondary packaging and standard barrier bottles serve mass-market probiotic yogurts and supplements in refrigerated and ambient aisles.
- Health Stores:Premium glass jars and paper-based sachets with sustainability credentials align with wellness-focused consumer preferences in urban UK and US markets.
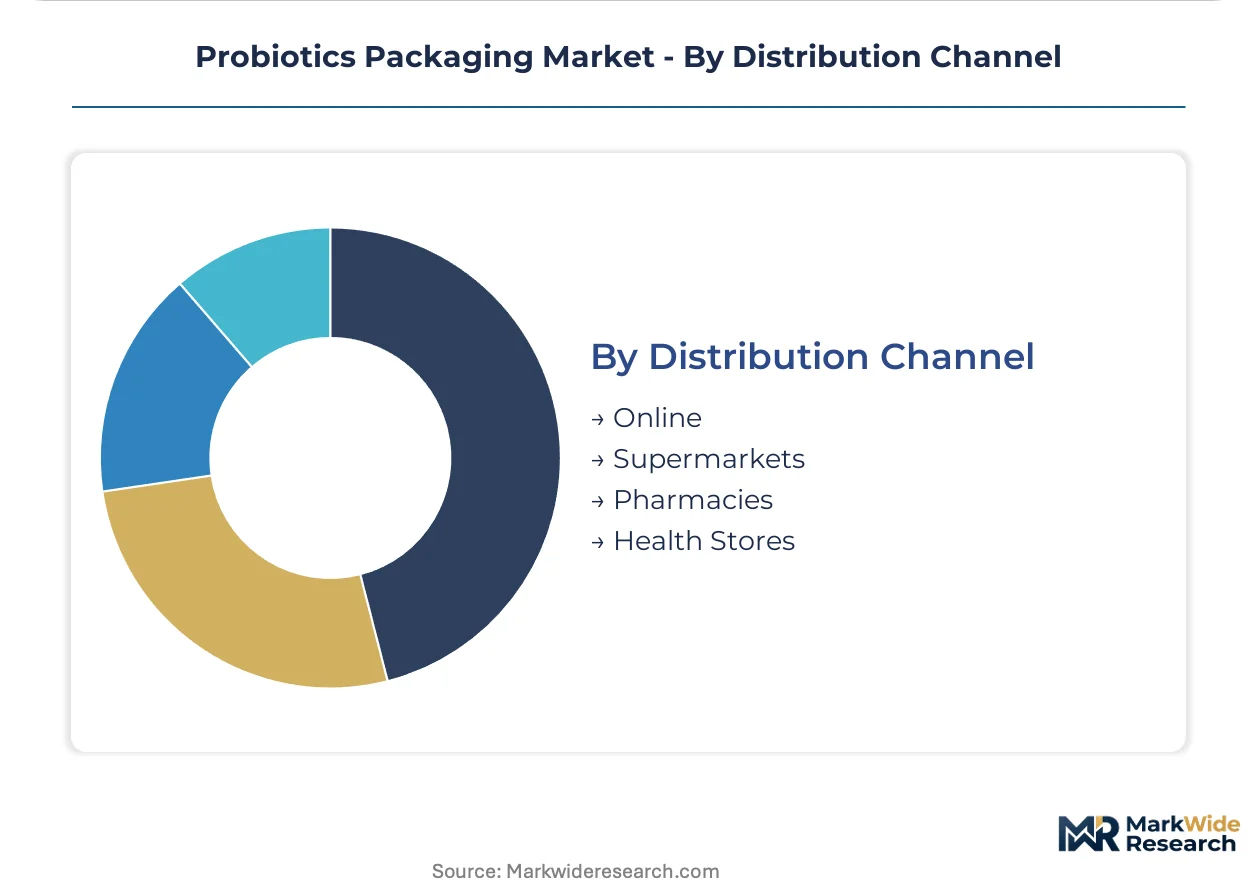
Pharmacies anchor specification standards; online is gaining share fastest as subscription models fragment traditional distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's dominance in probiotic packaging material flows, while the US Interstate 80 corridor connects Midwest converter capacity to coastal distribution nodes serving dietary supplement brands.
Germany
Pharmaceutical-grade probiotic formulations in Bavaria and Baden-Württemberg command oxygen transmission specifications below 0.1 cc/m²/day. The EU's Packaging and Packaging Waste Regulation imposes 70% material recovery targets by 2030, pressuring converters toward mono-material barrier development. Stuttgart's film extrusion cluster concentrates R&D investment for validated high-barrier systems serving medical-grade applications.
United States
Direct-to-consumer subscription brands in New York and Los Angeles specify portion-controlled sachet formats with premium unboxing aesthetics. California's extended producer responsibility laws mandate material recovery pathways, accelerating qualification timelines for paper-based barrier alternatives. Chicago's thermoforming corridor anchors North American supply for HDPE probiotic bottles with desiccant closure systems.
India
FSSAI regulatory modernization and rising functional food consumption in Mumbai and Bangalore create demand for oxygen-barrier sachet formats. The Food Safety and Standards Authority of India's packaging material notifications tighten migration limits for probiotic contact layers. Hyderabad's pharmaceutical packaging cluster attracts converter investment for ambient-stable strain containment systems.
Netherlands
Dietary supplement brands in Amsterdam and Rotterdam have compressed validation timelines for metallized paper substrates from 18 months to 8 months. The EU Green Deal's circular economy action plan drives converter capex toward vacuum metallization equipment. Eindhoven's advanced materials corridor hosts bio-coating deposition pilots for cellulose nanofiber barrier development.
United Kingdom
Wellness-focused consumers in London and Manchester prioritize convenience over pharmacy-channel familiarity, fragmenting traditional distribution. The UK's extended producer responsibility regulations for packaging waste reshape material specifications ahead of EU alignment debates. Birmingham's converter base retools thermoforming lines for thinner-gauge mono-material sheet serving supplement brands.
Probiotics Packaging Market Competitive Landscape
Concentration sits with diversified packaging conglomerates possessing in-house barrier film extrusion and pharmaceutical validation capabilities. The vendor base spans three tiers: integrated multinationals with global thermoforming networks, regional specialists in metallized substrates, and emerging paper-based barrier developers. Competitive positioning hardens around mono-material platform development, converter-retailer sustainability partnerships, and M&A targeting specialized barrier metrology expertise.
Among the integrated packaging conglomerates, Amcor plc and Berry Global Group, Inc. occupy positions reflecting pharmaceutical barrier heritage and North American thermoforming scale respectively. Sealed Air Corporation exemplifies the diversification archetype with sachet format specialization. Mondi Group and DS Smith Plc represent paper-based barrier development trajectories, while Huhtamaki Oyj and Sonoco Products Company sit within the regional converter tier with flexible packaging concentration.
| Leading Market Players |
|---|
| DS Smith Plc |
| Sealed Air Corporation |
| Amcor plc |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Berry Global Group, Inc. |
| Mondi Group |
| Tetra Pak International S.A. |
| AptarGroup, Inc. |
| Others |
Value Network & Pricing Analysis
Metallized paper substrates displacing aluminum-foil laminates simultaneously relocate converter investment toward vacuum metallization clusters in Germany and the Netherlands while compressing validation premiums that multi-layer plastic laminates once commanded. Dietary supplement brands exploit this substitution to extract price concessions from legacy pharmaceutical-grade suppliers.
Pricing Analysis
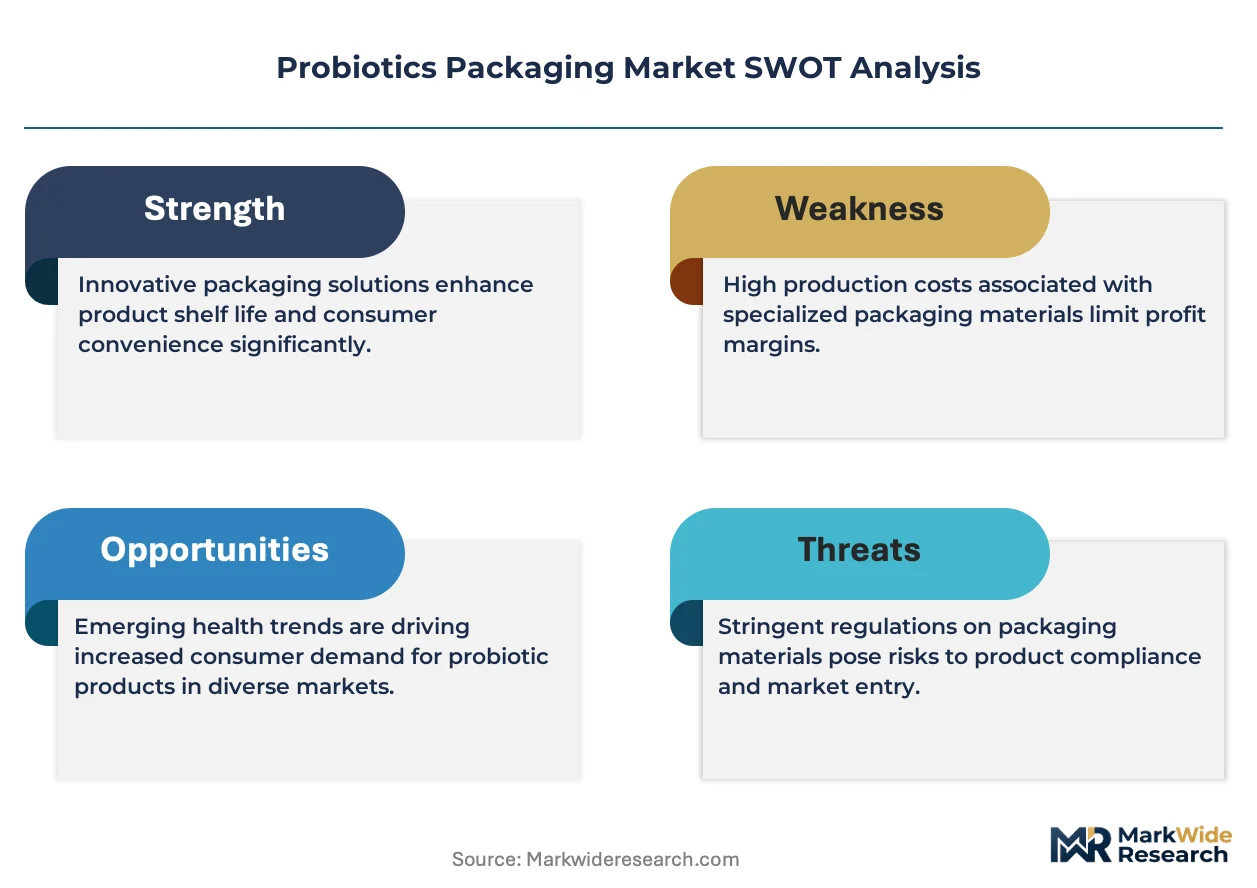
Volume-discount tiering structures separate pharmaceutical-grade serialization-compliant formats from commodity sachets serving direct-to-consumer subscription channels. Pricing stratifies across premium barrier specifications with EFSA health claim documentation, standard validated systems for pharmacy distribution, and economy mono-material alternatives for wellness retail. Cost compression in standard-tier metallized paper stems from accelerated qualification timelines compressing converter R&D amortization. Pharmaceutical buyers exhibit lowest price sensitivity due to MDR compliance requirements; dietary supplement brands drive hardest bargaining through consolidated procurement consortiums.
Supply Chain Analysis
Inbound logistics costs through the Port of Rotterdam fluctuate with container availability on Asia-Europe trade lanes, elevating working capital requirements for metallized film substrate imports. Raw material supply concentrates in Germany for EVOH coextrusions, the Netherlands for vacuum metallization equipment, and China for aluminum oxide coating precursors. The supply chain draws from single-source vulnerability in specialized barrier metrology equipment. Distribution runs through converter-direct relationships with dietary supplement brands, bypassing traditional pharmaceutical wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dietary supplement brand consolidation into direct-to-consumer subscription models has fragmented pharmaceutical procurement authority, concentrating buyer power among wellness-focused platforms.
For Market Incumbents: Secure mono-material barrier film capacity through backward integration into vacuum metallization assets before EU Packaging and Packaging Waste Regulation deadlines eliminate multi-layer laminate options. Anchor pharmaceutical validation capabilities against emerging paper-based barrier developers by accelerating EFSA health claim documentation services for medical-grade probiotic formats. For New Entrants and Emerging Players: Lead with bio-coated cellulose nanofiber substrates targeting India's FSSAI-regulated dietary supplement expansion in Mumbai and Bangalore. The most penetrable white space sits in oxygen-barrier sachets for ambient-stable strains where validation timelines remain compressed. Pursue converter-retailer sustainability partnerships as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging specialists possessing pharmaceutical barrier heritage but lacking mono-material platform development. Long-term viability hinges on converter capabilities spanning both metallized paper qualification and EFSA compliance documentation. Watch for inflection when California extended producer responsibility enforcement triggers paper-based barrier specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Platform Development | Converters achieving validated oxygen transmission below 0.1 cc/m²/day with single-substrate structures capture EU regulatory compliance premiums. |
| Vacuum Metallization Capacity Expansion | German and Dutch equipment investments compress qualification timelines for aluminum oxide-coated paper serving ambient-stable sachets. |
| EFSA Health Claim Documentation Services | Packaging performance substantiation bundled with shelf-life declarations tightens converter-dietary supplement brand relationships. |
| Backward Integration into Barrier Film Extrusion | In-house EVOH coextrusion capacity insulates margin pressure from European converter consolidation. |
| Direct-to-Consumer Format Specialization | Single-serve portion control with premium unboxing aesthetics displaces bulk bottle procurement through pharmacy networks. |
Research Methodology
Initial hypotheses were tested against primary input from packaging procurement managers at dietary supplement brands, pharmaceutical quality assurance directors, converter R&D heads, and barrier film extrusion specialists and refined through secondary validation. Trade data from EU customs authorities, EFSA health claim authorization databases, FDA cGMP inspection records, and FSSAI packaging material notifications anchored quantitative estimates. Bottom-up capacity assessments at Stuttgart and Eindhoven film extrusion clusters were triangulated against top-down demand modeling from probiotic formulation production volumes.
Variance decomposition across the projection horizon isolates volume drivers by packaging format, material substrate, regulatory compliance tier, and end-user concentration. Segmentation dimensions modeled include barrier intensity specifications, mono-material versus multi-layer construction, pharmaceutical versus dietary supplement procurement authority, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating shelf-stable strain adoption rates and EPR implementation schedules. Industry-specific inputs encompass oxygen transmission rate validation timelines and metallized paper substrate qualification trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU Packaging and Packaging Waste Regulation enforcement or breakthrough bio-coating barrier performance would require recalibration. Forecasts reflect assumptions regarding FSSAI regulatory modernization pace and dietary supplement brand procurement consolidation continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Pizza Box Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Cereal Packaging Market