
 Desserts Packaging Market | 2026-2036
Desserts Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Desserts Packaging Market Outlook
REACH compliance is hardening material substitution requirements across European dessert packaging supply chains. Amcor plc leverages its global R&D network to develop mono-material barrier solutions for chilled desserts. Berry Global anchors North American capacity with specialized thermoforming operations for single-serve pudding cups. Mondi Limited differentiates through kraft-paper-based alternatives targeting frozen dessert segments.
Desserts packaging encompasses primary and secondary containment systems engineered to preserve organoleptic properties, moisture stability, and temperature integrity of sweet food products through shelf-stable, chilled, or frozen distribution cycles. Multi-layer coextrusion and modified atmosphere sealing represent core manufacturing processes that extend shelf life while preventing flavor migration and textural degradation. Plastic films and cups command the largest share of packaging type demand, though cardboard boxes for premium gift assortments capture disproportionate margin pools. Glass jars retain dominance in artisanal dessert segments where visual product presentation drives purchase decisions, while metal tins sustain niche positions in traditional biscuit and confectionery categories.
The EU Green Deal and EFSA food-contact regulations jointly determine material eligibility and recyclability pathways for dessert packaging sold across European markets. FDA food-contact substance notifications govern parallel requirements in the United States, with particular scrutiny on per- and polyfluoroalkyl substance migration limits. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based material certification standards to secure competitive positioning.
Market Dynamics
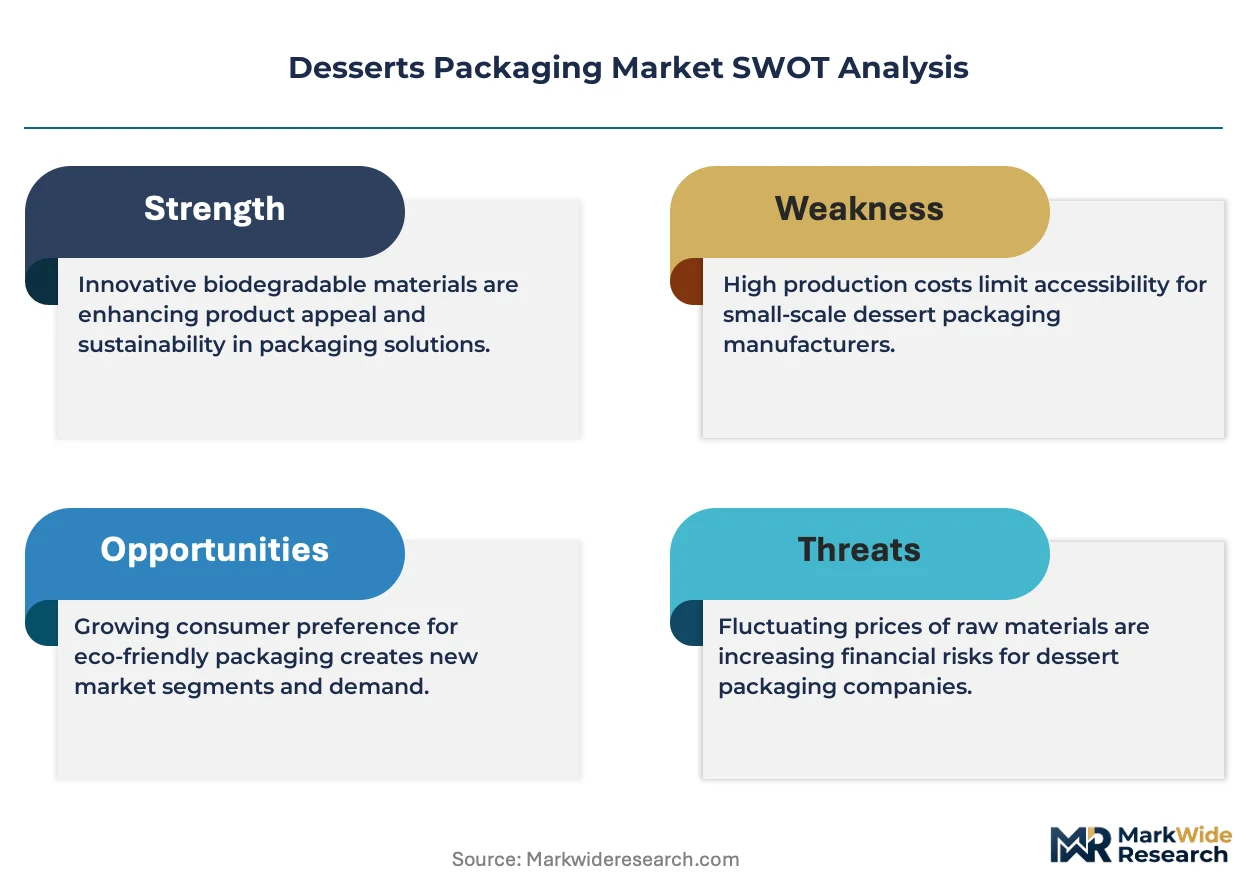
REACH compliance is forcing material substitution across European dessert packaging supply chains, compressing legacy multi-layer film architectures while mono-material barrier solutions scale from pilot to commercial deployment.
Growth Catalysts
- EU Green Deal recyclability mandates:Hardening requirements for multi-layer dessert cups accelerate demand for mono-material alternatives that maintain oxygen and moisture barriers.
- Frozen dessert segment expansion:Premium ice cream and gelato brands in Italy and France drive specialized kraft-paper-based packaging with enhanced thermal resistance.
- Modified atmosphere sealing technology:Bakery and patisserie channels adopt gas-flush systems to extend shelf life of chilled tarts and mousse products without preservatives.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:Japanese and Korean resin producers control critical oxygen barrier raw materials, exposing European converters to input cost volatility and allocation risk.
- Multi-layer coextrusion technical limitation:Current lamination adhesives lack certified recyclability pathways under EFSA food-contact standards, blocking circular design claims.
- Glass jar substitution threat:Artisanal dessert segments retain visual presentation advantages that polymer alternatives cannot replicate at equivalent cost points.
Strategic Opportunities
- Bio-based polylactic acid certification:EFSA and EU Green Deal bio-based material standards create first-mover advantage for converters achieving industrial compostability validation.
- Direct-to-patisserie distribution:Specialized logistics platforms bypass traditional wholesale channels, enabling customized short-run packaging for boutique dessert producers.
- Smart packaging convergence:Integration of time-temperature indicators with flexible films addresses cold-chain integrity gaps in frozen dessert last-mile delivery.
Industry Challenges
- Mono-material barrier R&D talent scarcity:Polymer scientists with dual expertise in food-contact compliance and high-performance film engineering command premium compensation, constraining converter expansion timelines.
- Thermoform tooling reconfiguration friction:Legacy pudding cup production lines require substantial capital redeployment to process next-generation recyclable substrates without yield degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desserts Packaging Market |
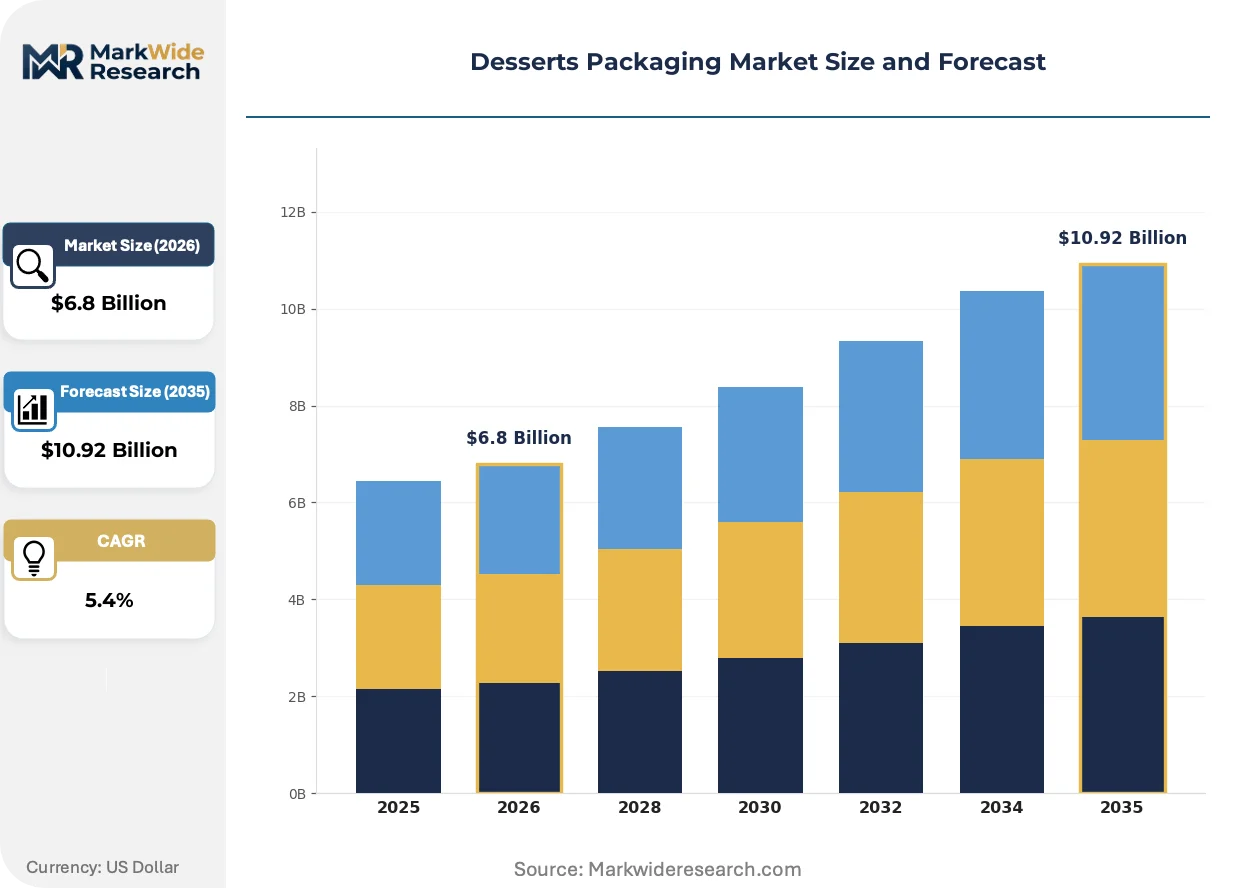
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Box, Jar, Film, Cup Material: Plastic, Glass, Cardboard, Metal Size: Small, Medium, Large, Extra Large Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service |
| Companies Covered | Amcor plc, Berry Global, Sealed Air Corporation, Smurfit Kappa, Mondi Limited, International Paper Company, Graphic Packaging International, DS Smith Plc, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desserts Packaging Market Strategic Shifts
Material science breakthroughs and regulatory compression are converging to reshape competitive positioning across chilled, frozen, and ambient dessert segments. Three forces dominate the transformation trajectory.
Mono-material polyethylene barrier films are absorbing functional properties previously delivered by multi-layer coextrusions. Premium confectionery brands in Germany and France are piloting these structures for chocolate assortments and praline boxes. The technology is absorbing margin pressure from EPR fee structures while enabling recyclability claims that satisfy retailer sustainability scorecards.
EFSA food-contact substance notifications are tightening scrutiny on per- and polyfluoroalkyl substance migration limits for grease-resistant dessert wraps. Industrial consequence includes accelerated phase-out of fluorinated chemistry in bakery release liners and frozen pastry interleaving papers. Chilled dessert segments in Italy face the most immediate compliance deadlines, driving reformulation partnerships between paper converters and chemical suppliers.
Patisserie procurement patterns are compressing order cycles from quarterly to monthly horizons. Boutique dessert producers in Paris and Milan now demand packaging runs as small as five thousand units with forty-eight-hour turnaround. This behavioral shift favors regional thermoforming specialists with digital prepress capabilities over centralized mass-production facilities.
Desserts Packaging Market Segmentation
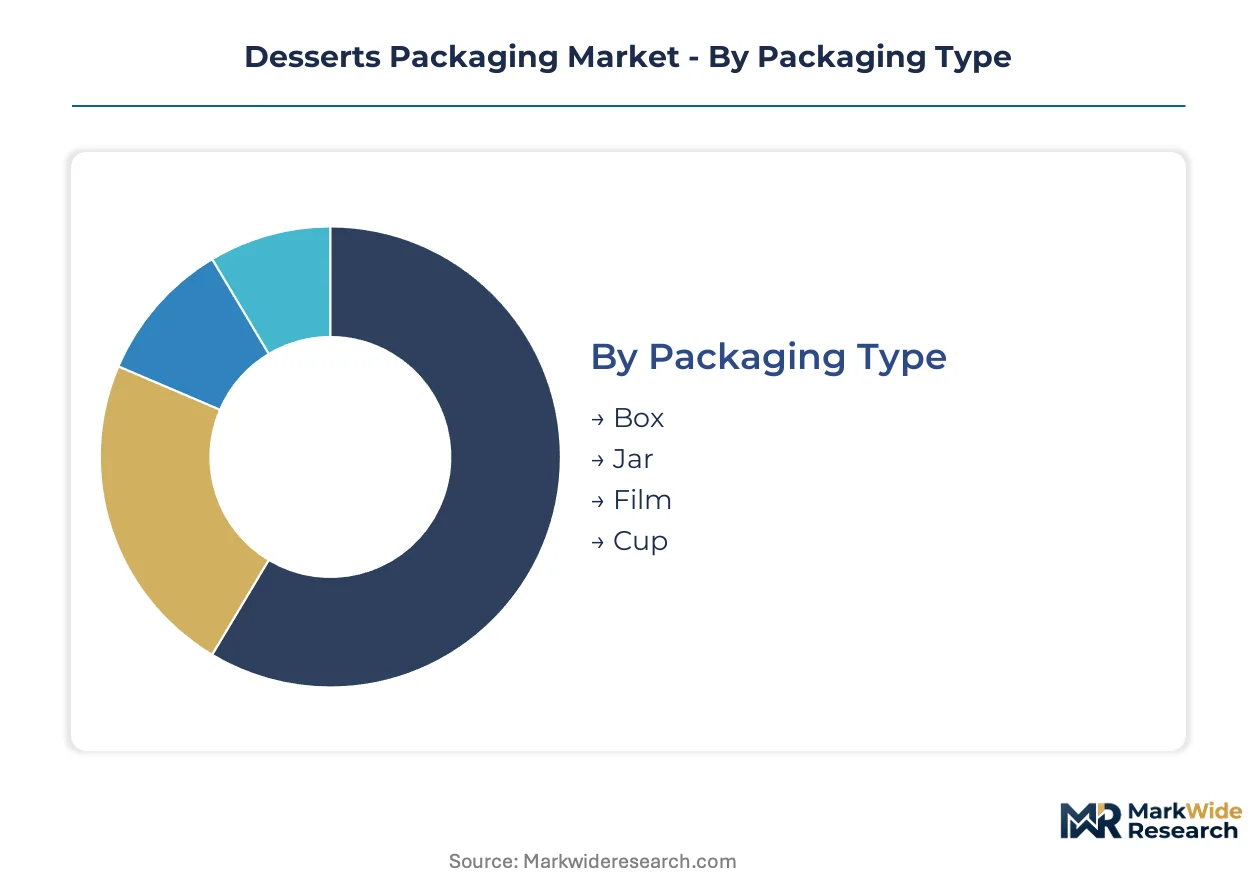
Desserts packaging segmentation reveals how material science capabilities and distribution economics partition value capture across the supply chain. Converters must align production assets with specific segment requirements to avoid margin erosion from capability mismatches.
Packaging Type:
Supply concentration in thermoforming and injection molding equipment shapes competitive dynamics across primary containment formats.
- Film:Multi-layer coextruded structures dominate chilled dessert applications, with oxygen transmission rates below 1 cc/m²/day preserving mousse and custard textures. German and French premium confectionery brands drive specification tightening for mono-material barrier alternatives as EPR fees reshape total cost of ownership calculations.
- Cup:Thermoformed polystyrene and polypropylene containers command single-serve pudding and yogurt segments, requiring precise seal integrity for modified atmosphere applications. Italian gelato producers specify enhanced thermal resistance for frozen distribution cycles, compressing order quantities toward short-run flexibility.
- Box:Folding carton constructions serve premium gift assortments and seasonal confectionery, leveraging offset lithography for visual differentiation at point of sale.
- Jar:Glass and polymer jar formats retain artisanal dessert positioning where product visibility drives purchase decisions in patisserie channels.
Today's leader: Film. Tomorrow's challenger: Cup.
Material:
Cost tier stratification separates commodity converters from specialty material suppliers with food-contact certification depth.
- Plastic:Polyethylene, polypropylene, and polystyrene resins constitute the volume foundation, with EVOH barrier layers embedded in multi-layer architectures. REACH compliance deadlines are forcing substitution toward certified recyclable mono-material structures, particularly for dessert cups sold across EU markets.
- Cardboard:Solid bleached sulfate and coated unbleached kraft grades capture premium positioning through printability and sustainability credentials. Frozen dessert applications in France and Italy specify enhanced moisture vapor transmission resistance for extended cold-chain exposure.
- Glass:Soda-lime containers sustain traditional preserves and artisanal segments where thermal processing and visual presentation outweigh logistics cost penalties.
- Metal:Tinplate and aluminum retain niche positions in biscuit tins and seasonal gift packaging, constrained by weight and recycling infrastructure limitations.
Plastic dominates volume. Cardboard commands margin expansion.
Size:
Volume concentration in single-serve formats reflects portion control trends and food service operational requirements.
- Small:Individual portions under 150ml target convenience retail and on-premise consumption, requiring precise dimensional tolerance for automated filling lines.
- Medium:Family-size containers between 500ml and 1L anchor supermarket refrigerated cases, balancing shelf presence with household consumption patterns.
- Large:Food service bulk formats above 2L supply institutional bakeries and catering operations with cost-optimized secondary packaging.
- Extra Large:Industrial totes and pails serve ingredient supply and manufacturing intermediates, outside branded consumer positioning.
Small formats scale fastest. Medium formats defend revenue concentration.
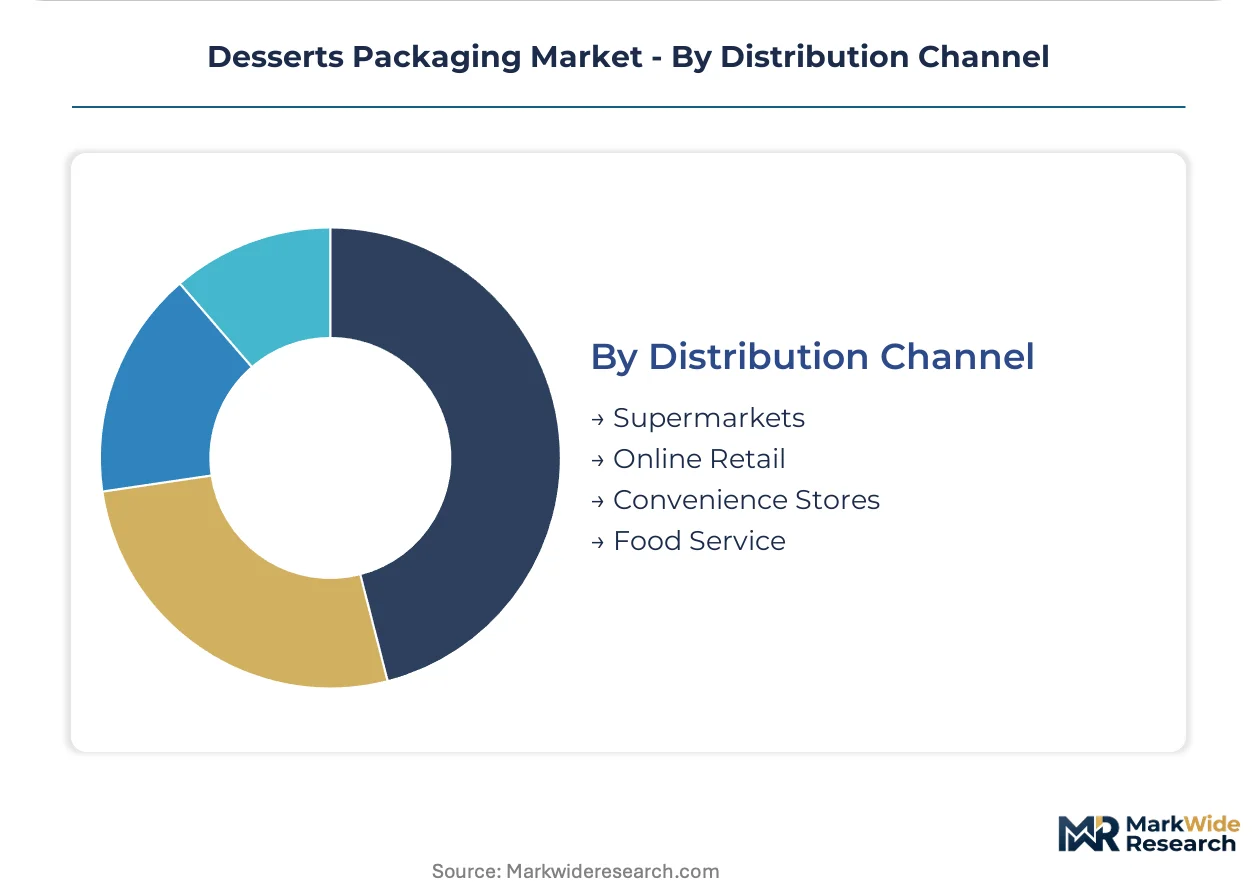
Distribution Channel:
Customer type fragmentation between retail and food service channels demands divergent packaging performance specifications and order cycle economics.
- Supermarkets:Multi-unit retail packs require shelf-ready secondary packaging with print registration precision for planogram compliance. German and French retailers enforce sustainability scorecards that disqualify non-recyclable multi-layer films from supplier approval.
- Food Service:Bulk supply to hotels, restaurants, and caterers prioritizes operational efficiency through stackability, portion consistency, and dispensing compatibility. Italian patisserie chains specify customized short-run packaging with forty-eight-hour turnaround requirements.
- Online Retail:Direct-to-consumer shipment demands enhanced structural integrity for last-mile handling, with void-fill reduction and temperature maintenance for frozen desserts.
- Convenience Stores:Impulse-oriented single-serve formats emphasize grab-and-go accessibility with reduced shelf footprint and prominent facing optimization.
Supermarkets anchor current volume. Food service expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial-scale dessert packaging originated in post-war Europe, where German and Italian engineering clusters developed the first automated thermoforming lines for dairy and confectionery applications. That technical foundation now diffuses across manufacturing hubs on three continents.
Germany
Premium confectionery brands in Cologne and Hamburg drive specification tightening for mono-material barrier films. The EU Green Deal's EPR fee structures compress total cost of ownership for multi-layer alternatives. Bavarian thermoforming specialists pilot recyclable cup architectures for chilled dessert segments.
France
Parisian patisserie chains compress order cycles to monthly horizons with forty-eight-hour turnaround demands. EFSA food-contact notifications tighten PFAS migration limits for grease-resistant bakery wraps. Lyon-based converters reformulate release liners with fluorine-free chemistry.
Italy
Gelato producers in Milan and Turin specify enhanced thermal resistance for frozen distribution cycles. REACH compliance deadlines force substitution toward certified recyclable substrates. Emilia-Romagna's packaging corridor scales short-run digital prepress capabilities for boutique dessert makers.
United States
FDA food-contact substance notifications govern per- and polyfluoroalkyl substance limits for dessert wraps and interleaving papers. Berry Global anchors North American capacity with specialized thermoforming operations. Chicago-area converters supply single-serve pudding cups to institutional food service channels.
China
Dual carbon goals and GB standards accelerate domestic substitution of non-recyclable multi-layer films. Yangtze River Delta manufacturers develop kraft-paper-based alternatives for frozen dessert export markets. Shanghai-based converters integrate smart packaging elements for cold-chain monitoring.
Desserts Packaging Market Competitive Environment
The competitive structure tilts toward diversified packaging conglomerates with cross-material capabilities. Tier-one players command thermoforming and extrusion assets across multiple continents. Three archetypes dominate: integrated resin-to-package converters, specialized film engineers, and paper-based sustainability specialists. Capacity expansion and portfolio diversification represent the dominant competitive moves as EPR frameworks reshape margin economics.
Within the diversified conglomerate tier, Amcor plc and Berry Global occupy positions spanning flexible films and rigid containers. Mondi Limited exemplifies the paper-based sustainability vector with kraft-paper alternatives targeting frozen segments. These three entities represent contrasting strategic postures—global scale, regional manufacturing density, and material-specific certification depth—without exclusive segment lock-in.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Sealed Air Corporation |
| Smurfit Kappa |
| Mondi Limited |
| International Paper Company |
| Graphic Packaging International |
| DS Smith Plc |
| Sonoco Products Company |
| Others |
Value Chain & Pricing Dynamics
Captive resin-to-package integration anchors competitive positioning for European dessert packaging converters, compressing input cost volatility while enabling premium pricing for EFSA-certified mono-material barrier solutions. This structural choice locks in margin defense against Asian EVOH supply concentration and hardens recyclability claims that satisfy retailer sustainability scorecards.
Pricing Analysis
Bundled technical service contracts dominate premium tier relationships, while unbundled commodity film transactions anchor economy segments. Three-tier pricing structure across premium, standard, and economy levels separates certified recyclable mono-material films from legacy multi-layer architectures and basic polyethylene wraps. Cost compression in standard tiers is intensifying because EPR fee structures reshape total cost of ownership calculations. Food service channels exhibit highest price sensitivity due to operational procurement protocols, while patisserie boutiques prioritize turnaround speed over unit cost.
Supply Chain Analysis
Direct-to-patisserie channels handle boutique producer demand with forty-eight-hour turnaround requirements, while consolidated distributor networks supply supermarket and food service volume. German, Italian, and French converters anchor European thermoforming capacity. Critical input dependencies rest on Japanese and Korean EVOH resin supply, German extrusion equipment, and Nordic kraft pulp for frozen dessert segments. Single-source vulnerability in oxygen barrier raw materials exposes converters to allocation risk. Distribution runs through specialized logistics platforms for chilled and frozen segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Germany and France exceed equivalent certification thresholds in Emilia-Romagna, creating margin capture opportunities for Italian converters with digital prepress capabilities.
For Market Incumbents: Lock in mono-material barrier R&D talent through captive compensation structures and accelerate thermoform tooling reconfiguration toward recyclable substrates. Bio-based polylactic acid certification investment hardens positioning against emerging sustainability specialists. Backward integration into EVOH resin supply or strategic partnerships with Korean producers mitigates raw material allocation risk. For New Entrants and Emerging Players: Launch via direct-to-patisserie distribution platforms targeting Milan and Paris boutique producers with sub-five-thousand-unit order capabilities. Short-run digital prepress flexibility represents the most penetrable white space, as centralized mass-production facilities cannot match forty-eight-hour turnaround demands. Specialty kraft-paper-based frozen dessert packaging offers a defensible entry angle with lower capital intensity than thermoforming. For Investors and Strategic Acquirers: Consolidation pressure builds where mono-material barrier R&D talent scarcity constrains converter expansion timelines. Five-to-ten-year viability favors regional specialists with EFSA certification depth and digital prepress assets over undifferentiated commodity film producers. Patent filing velocity in fluorine-free grease-resistant chemistry signals inflection timing for bakery wrap segment repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Investment | Amcor plc and Berry Global deploy capital to develop EFSA-certified recyclable films for chilled dessert segments. |
| Digital Prepress Capability Expansion | Emilia-Romagna converters scale short-run flexibility to capture Paris and Milan patisserie procurement shifts. |
| Fluorine-Free Chemistry Partnership | Lyon-based converters reformulate release liners under tightening EFSA per- and polyfluoroalkyl substance limits. |
| Smart Packaging Integration | Shanghai manufacturers embed time-temperature indicators for frozen dessert cold-chain integrity gaps. |
| Bio-Based Material Certification | First-mover converters achieve industrial compostability validation under EU Green Deal bio-based standards. |
Study Parameters
Direct dialogue with polymer scientists, thermoforming plant managers, patisserie procurement leads, and EFSA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from EU Green Deal implementation documents, EFSA food-contact substance notifications, REACH compliance databases, and customs trade data for EVOH resin flows. Bottom-up and top-down triangulation cross-checked converter capacity estimates against end-use demand segmentation.
Bottom-up modeling anchored volume projections in individual country-level thermoforming line counts and throughput assumptions, while top-down approaches validated aggregate demand through retail channel shipment data. Segmentation dimensions across the analysis window included packaging type, material substrate, size tier, and distribution channel. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory phase-in timelines and EPR fee implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or EVOH supply disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Pizza Box Market
Food Packaging
Food Can Market
Food Packaging
Fresh Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Burger Boxes Market