
 Canned Food Packaging Market | 2026-2036
Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Food Packaging Market Analysis
Pet food manufacturing is restructuring demand profiles across the canned food packaging value chain, drawing volume away from traditional soup and vegetable packers. Crown Holdings leverages its global manufacturing footprint to supply multinational pet food brands with consistent two-piece aluminum can formats. Ball Corporation anchors North American beverage-to-food can conversion capacity as it navigates shifting substrate preferences. Silgan Holdings specializes in steel and tinplate solutions for legacy vegetable and soup processors seeking cost containment.
Canned food packaging encompasses rigid metal, plastic, or composite containers hermetically sealed to preserve shelf-stable food products through retort sterilization, typically achieving 12-36 month shelf life without refrigeration. The primary commercial purpose centers on distributing processed foods through ambient retail and foodservice channels while preventing microbiological degradation and flavor loss. Steel and tinplate retain dominant share in vegetable and soup applications where cost sensitivity structures procurement decisions, while aluminum is accelerating fastest in premium pet food and ready-meal segments where lightweighting and printability command margin premiums. Plastic cans occupy niche positions in microwaveable soup formats where differential convenience justifies material switching costs.
The FDA enforces 21 CFR Part 175 compliance for indirect food-contact coatings and linings inside metal cans, while the EPA regulates volatile organic compound emissions from can coating operations under Clean Air Act standards. The EU Green Deal's packaging waste targets and REACH chemical restrictions are forcing reformulation of epoxy-based can linings across European supply chains. Stakeholders must monitor bisphenol-A substitution timelines and substrate-specific recycling infrastructure investments to align product portfolios with evolving compliance and collection requirements.
Market Dynamics
EU Green Deal packaging waste targets and REACH chemical restrictions are forcing wholesale reformulation of epoxy-based can linings, compressing lead times for European suppliers while accelerating bisphenol-A substitution timelines across the value chain.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recycled content mandates are pulling investment into European metal can collection infrastructure and closed-loop aluminum systems.
- Pet food wet line expansion:Premium pet food manufacturers are converting volume from traditional soup and vegetable packers toward two-piece aluminum formats for shelf-stable animal nutrition.
- Southeast Asia processing capacity:Regional canmaking investments in Thailand, Vietnam, and Indonesia are shortening supply chains for tropical fruit and seafood exporters.
Market Restraints
- Tinplate cost volatility:Steel input price swings and energy-intensive tinning processes constrain margin predictability for legacy vegetable and soup processors.
- Coating chemical supply concentration:Epoxy resin and polyester coating formulation expertise clusters among a handful of European and Japanese specialty chemical suppliers.
- Retort sterilization energy intensity:Thermal processing requirements for shelf-stable foods limit facility siting flexibility and expose operations to electricity price spikes.
Strategic Opportunities
- India organized retail expansion:Modern trade penetration in tier-2 and tier-3 cities is creating first-mover advantage for ambient ready-meal and curry can formats.
- FSSAI packaging safety harmonization:India's national food regulator is consolidating state-level standards, reducing compliance fragmentation for multinational canmakers.
- Digital printing convergence:Combination of high-speed inkjet and variable-data capabilities enables micro-batch customization for regional brand launches.
Industry Challenges
- Can lining chemist scarcity:Formulation expertise for BPA-NI (non-intent) and polyester alternatives is concentrated among retiring specialists in European coating houses.
- Retort equipment reconfiguration:Legacy steel can lines require substantial capex to accommodate lighter aluminum body diameters and modified seaming profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Food Packaging Market |
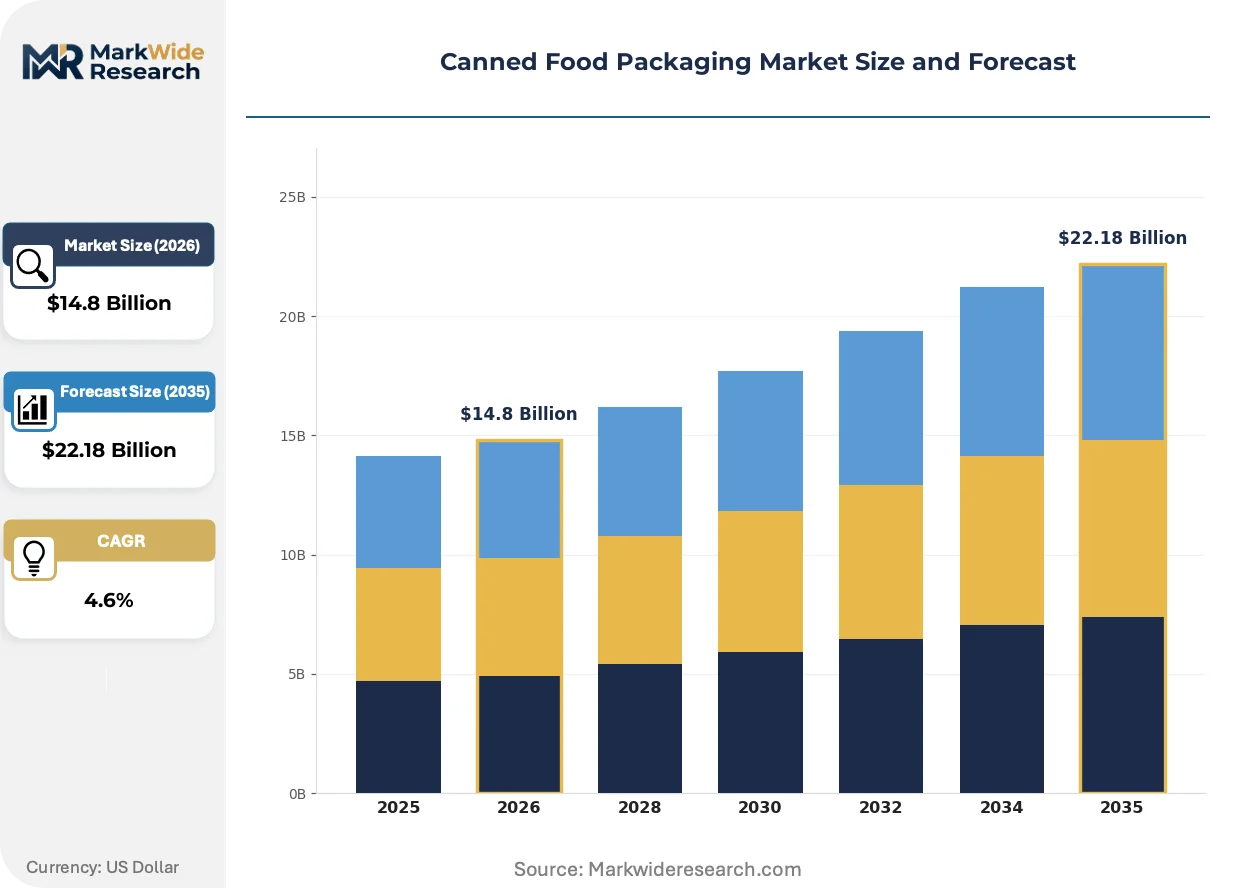
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Material: Aluminum, Steel, Tinplate, Plastic Closure Type: Pull Tab, Easy Open, Screw Cap, Can End Can Size: Small, Medium, Large, Family Size End Use: Vegetables, Fruits, Meat, Soup |
| Companies Covered | Crown Holdings, Ball Corporation, Silgan Holdings, Ardagh Group, Sonoco Products Company, CPMC Holdings Limited, Toyo Seikan Group Holdings, CANPACK, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Food Packaging Market Emerging Trajectories
Active reshaping in canned food packaging centers on substrate substitution, regulatory chemistry overhaul, and procurement consolidation among multinational brand owners seeking supply security.
Two-piece aluminum draw-redraw technology is overtaking three-piece steel construction in premium pet food and ready-meal segments. Mars Petcare and Nestlé Purina procurement teams are specifying aluminum for lightweighting and superior lithographic reproduction. This substrate migration is compressing steel can demand in traditional vegetable categories while expanding aluminum rolling mill commitments for food-grade coil.
REACH authorization restrictions on bisphenol-A are compelling coating reformulation across European canmaking operations. ECHA's sunset date enforcement is accelerating polyester and acrylic lining development, with retort stability testing consuming 18-24 month validation cycles. Italian and Spanish tomato processors face the tightest compliance windows given their seasonal production concentration.
Direct sourcing contracts between pet food multinationals and integrated aluminum producers are displacing traditional can distributor intermediaries. Mars and Nestlé procurement teams are negotiating tolling arrangements with smelter-rolling combinations in Brazil and the Middle East. This channel compression is most advanced in North American and Western European supply bases where volume concentration justifies dedicated production lines.
Canned Food Packaging Market Segmentation
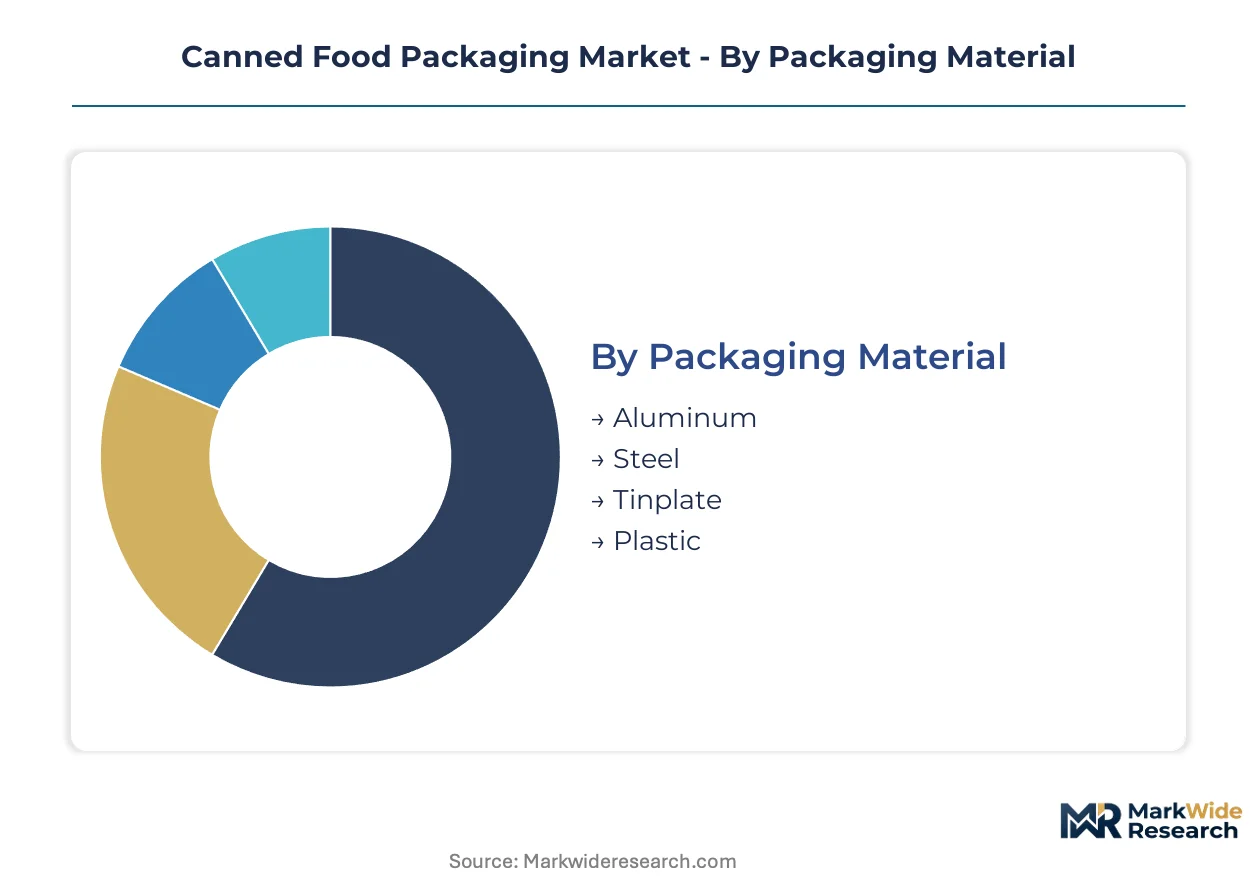
Segmentation in canned food packaging reveals how substrate choices, opening mechanisms, and format sizing align with distinct supply chain economics and end-use shelf-life requirements. Material and closure selections cascade through manufacturing capex, sterilization protocols, and retail channel placement decisions.
Packaging Material:
Material selection determines whether cans function as standalone premium formats or embed within broader packaging systems requiring secondary containment.
- Aluminum:Two-piece draw-redraw construction delivers sub-0.3mm wall thickness with superior lithographic reproduction. Pet food multinationals in North America and Western Europe are specifying aluminum for lightweighting and brand differentiation, displacing steel in premium wet food lines.
- Steel:Three-piece welded construction dominates vegetable and soup applications where cost sensitivity structures procurement. Legacy processors in Italy and Spain retain steel commitments despite aluminum migration, constrained by existing seaming equipment and seasonal production windows.
- Tinplate:Electrolytic tin coating provides corrosion resistance for acidic fruit and tomato products. Tinplate demand concentrates in Mediterranean canning clusters where established supply contracts and retort line configurations preserve incumbent substrate positions.
- Plastic:Polypropylene and polyethylene terephthalate barrier constructions serve microwaveable soup formats requiring differential convenience justification. Plastic occupies niche positions where material switching costs are offset by consumer preparation speed premiums.
Steel leads volumes today; aluminum is gaining share fastest.
Closure Type:
Closure engineering separates commodity can formats from value-added convenience tiers through opening force requirements and resealability.
- Pull Tab:Aluminum ring-pull scored openings enable single-motion access without tools. Beverage-to-food can converters in North America are standardizing pull-tab diameters across aluminum food formats to leverage existing end-making equipment.
- Easy Open:Full-aperture steel ends with scored tear strips address aging demographics and accessibility requirements. European vegetable processors face ECHA compliance pressure on easy-open lining chemistries alongside mechanical performance validation.
- Screw Cap:Threaded plastic or metal closures permit resealability for multi-serve formats and foodservice portions. Screw cap adoption concentrates in institutional channels where portion control and storage flexibility command procurement premiums.
- Can End:Traditional seamed steel ends requiring opener tools persist in economy vegetable segments and export markets with limited retail infrastructure. Can end retention correlates with price-sensitive consumer bases and established distribution networks.
Pull tab configurations dominate new line investments; easy open is climbing the fastest as accessibility regulations tighten.
Can Size:
Format scaling maps directly to household composition trends, foodservice portioning standards, and retail shelf-space allocation algorithms.
- Small:Single-serve portions under 200ml address on-the-go consumption and senior household downsizing. Small format demand is expanding in Japan and South Korea where convenience store penetration and solo dining trends structure purchasing patterns.
- Medium:Standard 300-400g capacities align with two-person household meal preparation norms. Medium formats retain dominant position across European and North American retail where established planogram slots and case pack economics preserve incumbent sizing.
- Large:500-800g capacities serve family meal preparation and recipe ingredient requirements. Large format procurement concentrates in value-oriented retail banners and ethnic grocery channels where per-gram cost optimization drives selection.
- Family Size:Multi-serve containers exceeding 1kg address foodservice institutional demand and bulk retail formats. Family size volumes correlate with club store expansion in Mexico and Brazil where household stockpiling behavior supports larger format adoption.
Medium formats anchor current production volumes; small sizes show steepest expansion trajectory as household fragmentation accelerates.
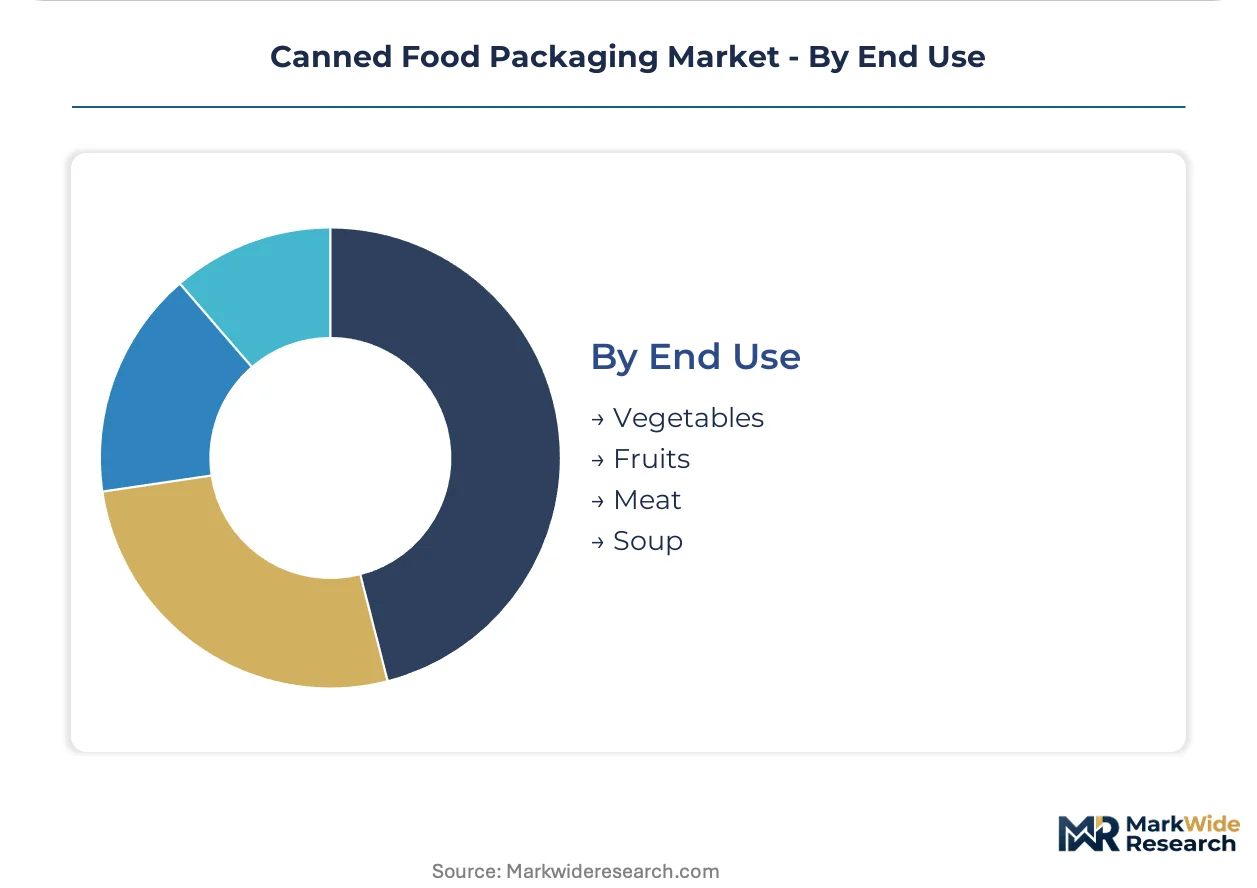
End Use:
Application segmentation reveals divergent sterilization protocols, shelf-life requirements, and brand concentration patterns across food categories.
- Vegetables:Corn, peas, and green beans in brine or light syrup represent legacy canning volumes with established harvest-to-can seasonal patterns. Vegetable processing gravity centers on Midwestern United States, northern Italy, and eastern France where contract farming relationships and cooperatives preserve regional supply concentration.
- Fruits:Tropical fruits, stone fruits, and citrus segments require acid-resistant linings and precise thermal processing to preserve texture. Thai and Vietnamese pineapple and lychee exporters are expanding regional canmaking capacity to shorten supply chains for European and Japanese importers.
- Meat:Poultry, beef, and pork products in gravy or brine demand stringent retort protocols and oxygen barrier performance. Meat canning concentrates in Brazil and Poland where integrated slaughter-to-can operations capture margin through captive raw material supply.
- Soup:Ready-to-serve and condensed formats span premium organic positioning to economy cream soups. Soup brand owners in the United Kingdom and Germany are specifying aluminum two-piece formats for premium lines while retaining steel for value-tier private label production.
Vegetables maintain volume leadership; pet food wet lines are displacing traditional soup and vegetable packers fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling canmaking capacity toward jurisdictions with lower compliance costs and expanding feedstock access, while REACH-driven reformulation expenses compress margins for European suppliers serving domestic tomato and vegetable processors.
United States
Pet food multinationals headquartered in St. Louis and Chicago are driving aluminum can procurement for wet food lines, displacing traditional steel commitments. FDA 21 CFR Part 175 enforcement on indirect food-contact coatings structures lining chemistry investments. Midwestern canmaking clusters in Ohio and Indiana are retooling lines to accommodate lighter aluminum body specifications.
Germany
ECHA sunset date enforcement on bisphenol-A is compelling polyester and acrylic lining development across domestic canmaking operations. The EU Packaging and Packaging Waste Regulation mandates tightening recycled content thresholds for aluminum food cans. Bavarian tomato processors face compressed validation cycles for retort-stable BPA-NI alternatives ahead of seasonal harvest windows.
China
NMPA harmonization of food-contact material standards is consolidating provincial-level compliance requirements for metal can exporters. Dual carbon goals under MEE oversight are elevating energy efficiency scrutiny for retort sterilization facilities. Yangtze River Delta canmaking investments in Jiangsu and Zhejiang are capturing tropical fruit processing demand from Southeast Asian exporters.
Brazil
Integrated slaughter-to-can operations in São Paulo and Paraná are capturing margin through captive poultry and beef supply for shelf-stable meat formats. ANVISA packaging safety protocols align with Mercosur technical regulations for intra-regional trade. Southeastern canmaking capacity is expanding to serve Argentine and Chilean import demand.
Thailand
Pineapple and lychee exporters are shortening supply chains through domestic canmaking investments rather than shipping bulk fruit to European processors. FSSAI-equivalent Thai FDA standards facilitate parallel export qualification for Indian market access. Eastern seaboard industrial zones in Chonburi and Rayong are attracting Japanese coating chemical suppliers seeking regional formulation hubs.
Canned Food Packaging Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated aluminum producers and independent canmakers race to capture pet food procurement consolidation. The vendor base stratifies across three tiers: multinational metal packaging conglomerates with smelter-rolling combinations, regional specialists in steel and tinplate legacy formats, and emerging Asian fabricators serving tropical fruit and seafood export clusters. Two competitive vectors define positioning: substrate substitution acceleration favoring aluminum lightweighting, and direct tolling arrangements displacing traditional distributor intermediaries.
Among North American metal packaging conglomerates, Crown Holdings and Ball Corporation exemplify the integrated aluminum-to-can value chain archetype, while Silgan Holdings occupies a distinct position within steel and tinplate specialization for cost-sensitive vegetable and soup processors. Toyo Seikan Group Holdings represents the Asia-Pacific regional specialist model with concentrated coating chemistry expertise and proximity to tropical fruit processing demand. These three anchors illustrate how competitive positioning fragments across substrate technology, geographic feedstock access, and regulatory compliance specialization rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Crown Holdings |
| Ball Corporation |
| Silgan Holdings |
| Ardagh Group |
| Sonoco Products Company |
| CPMC Holdings Limited |
| Toyo Seikan Group Holdings |
| CANPACK |
| Amcor |
| Others |
Supply Flow & Price Mechanics
Pet food multinational procurement teams command disproportionate pricing leverage through consolidated volume commitments, compressing distributor margins while elevating direct tolling arrangements with integrated aluminum producers. This buyer concentration shifts pricing power upstream toward smelter-rolling combinations capable of dedicating food-grade coil production lines.
Pricing Analysis
Distributor margin layers face sustained compression as Mars Petcare and Nestlé Purina procurement teams negotiate direct tolling contracts with aluminum producers in Brazil and the Middle East. Three-tier pricing structure across premium, standard, and economy levels separates lithography-grade aluminum cans from commodity steel formats and legacy tinplate vegetable containers. Cost compression in steel can segments is intensifying because tinplate input volatility and energy-intensive tinning processes constrain processor margin predictability. Legacy vegetable packers in Italy and Spain exhibit highest price sensitivity, while premium pet food brands prioritize lightweighting and print quality over per-unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from pet food multinationals, displacing traditional can distributor intermediaries in North American and Western European supply bases. Manufacturing concentration centers on China, Germany, and the United States, with Yangtze River Delta investments capturing Southeast Asian fruit processing demand. Raw material flows draw from bauxite refining corridors, steel rolling mills, and epoxy resin formulation clusters concentrated among European and Japanese specialty chemical suppliers. Single-source vulnerability in coating chemistry expertise—particularly BPA-NI and polyester lining development—exposes canmakers to validation cycle delays. Distribution runs through ambient retail and foodservice channels with secondary containment requirements for institutional formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification premiums for aluminum lightweighting and BPA-NI lining compliance are displacing commodity steel procurement across premium pet food and ready-meal segments.
For Market Incumbents: Acquire coating chemistry formulation expertise to secure BPA-NI and polyester lining capabilities ahead of ECHA sunset date enforcement. Aluminum rolling mill capacity in Brazil and the Middle East offers defensive positioning against substrate substitution acceleration. Backward integration into food-grade coil production insulates margin from smelter pricing volatility. For New Entrants and Emerging Players: Regional canmaking partnerships in Thailand and Vietnam offer lowest competitive density for tropical fruit and seafood export formats. India's tier-2 and tier-3 organized retail expansion presents penetrable white space for ambient ready-meal and curry can launches. Digital printing convergence enables micro-batch customization without dedicated line investments. For Investors and Strategic Acquirers: Integrated aluminum producers are the most active acquirer in this space, consolidating tolling arrangements with pet food multinationals. Mid-cap steel and tinplate specialists with established vegetable processor relationships offer consolidation targets for portfolio diversification. Retort equipment reconfiguration capex requirements signal inflection timing for aluminum format adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Food-Grade Aluminum Coil | Crown Holdings and Ball Corporation secure captive supply from Middle Eastern smelter-rolling combinations. |
| BPA-NI Coating Formulation Investment | European canmakers accelerate polyester and acrylic lining development ahead of ECHA enforcement windows. |
| Southeast Asian Canmaking Capacity Expansion | Thai and Vietnamese investments shorten supply chains for pineapple and lychee exporters to Japanese importers. |
| Digital Printing Line Conversion | High-speed inkjet capabilities enable variable-data micro-batches for regional brand launches without plate costs. |
| Direct Tolling Contract Negotiation | Pet food multinationals displace distributor intermediaries through volume-commitment arrangements with integrated producers. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Plant managers at canmaking facilities, procurement leads at pet food multinationals, coating chemistry specialists at European formulation houses, and distribution channel partners in Southeast Asian export corridors contributed stakeholder perspectives. Secondary sources include customs and trade data on aluminum and steel coil movements, EPA Clean Air Act enforcement records, ECHA REACH authorization timelines, and SEC filings from listed packaging conglomerates. Bottom-up volume modeling triangulates against top-down macroeconomic demand indicators.
Rate-of-change decomposition separates volume growth from value expansion across substrate material, closure type, can size, and end-use application dimensions. Aluminum versus steel substrate migration, pet food wet line expansion rates, and regional processing capacity additions in Southeast Asia feed analytical frameworks. CAGRs derive from segment-level trajectory blending rather than single-point extrapolation. Retort sterilization energy intensity and coating chemistry validation cycles constrain near-term capacity elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bisphenol-A substitution timelines and EU recycled content mandate enforcement. Periodic stress-testing of base assumptions is recommended, particularly regarding tinplate cost volatility and aluminum rolling mill commissioning schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Sugar Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Disposable Cups Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Cake Box Market