
 Europe Canned Food Packaging Market | 2026-2036
Europe Canned Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Canned Food Packaging Market Foresight
The buyer base for canned food packaging across Europe is broadening as discount grocery chains and online food retailers enter the market alongside traditional supermarkets. Ardagh Group leverages its integrated metal supply network to serve this fragmented demand across multiple countries. Crown Holdings, Inc. anchors its position through deep specialization in two-piece aluminum can technology. Silgan Holdings Inc. competes by controlling a diverse portfolio spanning metal, glass, and plastic formats for regional food brands.
Europe canned food packaging encompasses sealed containers manufactured from metal, glass, or plastic materials designed to preserve food products through hermetic closure and thermal processing, with metal cans typically constructed from tinplate or aluminum alloys ranging from 0.15 to 0.25 millimeters in wall thickness. The primary commercial purpose centers on extending shelf life without refrigeration while protecting contents from microbial contamination, oxidation, and mechanical damage throughout distribution. Metal Cans dominate value capture due to established recycling infrastructure and consumer familiarity, while Vacuum Sealing technology leads growth as processors pursue reduced thermal exposure for nutrient retention. Aseptic Processing occupies a specialized margin pool serving premium ready-to-eat segments where flavor preservation commands price premiums.
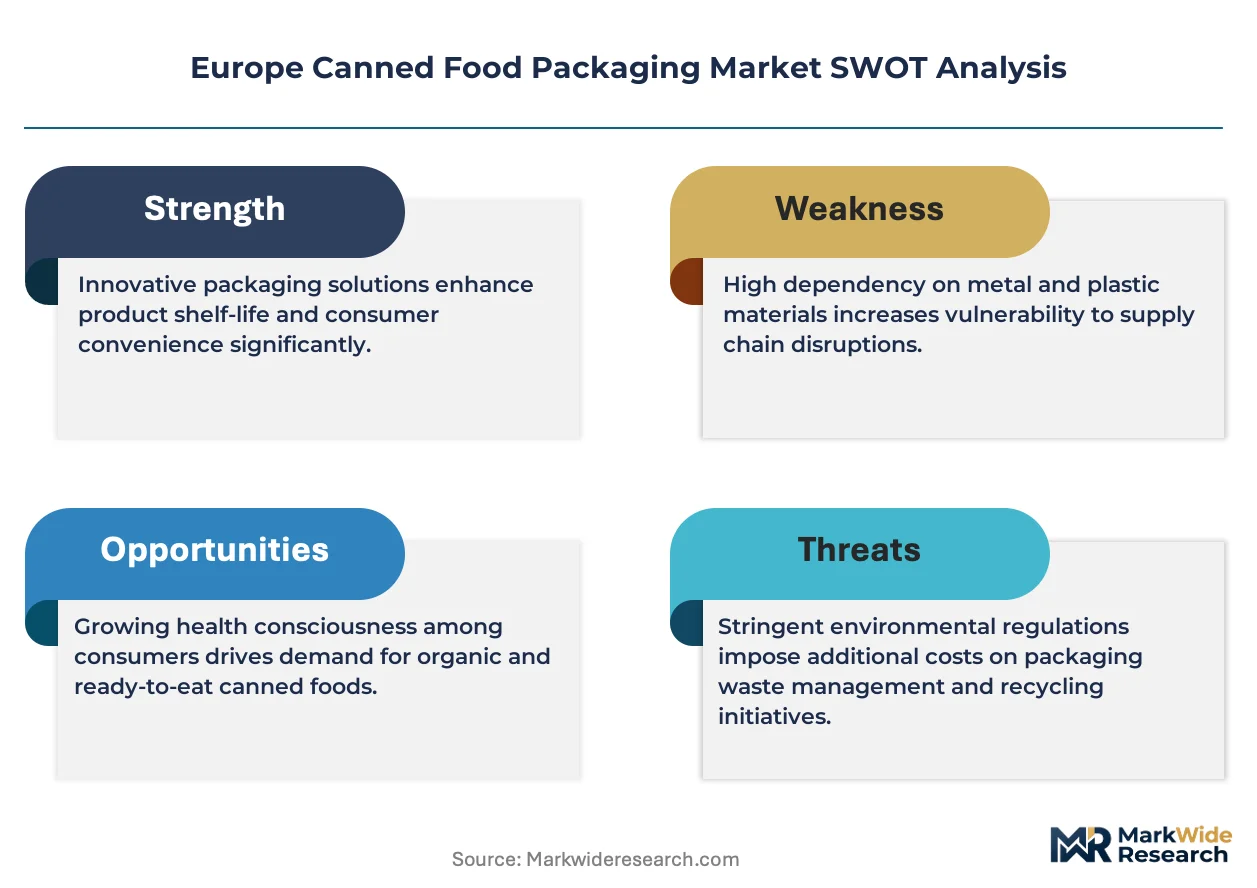
REACH and the EU Green Deal shape material selection by restricting certain chemical coatings and mandating recycled content thresholds for packaging placed on European markets. EFSA guidelines on food contact materials further constrain substrate and lining choices available to can manufacturers operating within EU member states. Stakeholders must monitor evolving Extended Producer Responsibility frameworks as these regulations will determine which packaging formats retain cost-competitive access to European retail channels.
Market Dynamics
Metal can manufacturers across Europe face mounting pressure from the EU Green Deal's recycled content mandates, forcing rapid retooling of coating chemistries and supply chain sourcing to maintain market access.
Growth Catalysts
- REACH-compliant coating innovation:ECHA's evolving substance restrictions are accelerating substitution of bisphenol-based linings with polyester and oleoresin alternatives, opening premium positioning for compliant suppliers.
- Discount grocery expansion:Aldi and Lidl are extending private-label canned food ranges across Germany, Poland, and Spain, creating volume pull for standardized two-piece aluminum formats.
- Vacuum sealing technology:Reduced thermal processing preserves nutrient profiles in premium vegetable and fish segments, allowing processors to command shelf price premiums in Italian and French retail.
Market Restraints
- Tinplate cost volatility:ArcelorMittal and thyssenkrupp dominate European steel substrate supply, exposing can makers to raw material price swings that compress margin predictability.
- Extended Producer Responsibility frameworks:Germany's VerpackG and France's AGEC law impose rising compliance fees on metal packaging, structurally elevating cost-to-serve versus flexible alternatives.
- Aseptic carton substitution:SIG Combibloc and Tetra Pak formats capture ambient soup and sauce volumes previously held by steel cans, particularly in Nordic retail channels.
Strategic Opportunities
- Poland and Romania underpenetration:Modern retail density remains below Western European benchmarks, offering first-mover advantage for canning line investments serving emerging discount chains.
- EU Green Deal circularity incentives:Member state recovery infrastructure subsidies favor aluminum can formats with established closed-loop recycling, rewarding producers with integrated scrap processing.
- E-commerce ambient food channels:Amazon Pantry and regional platforms are building shelf-stable assortment depth, creating demand for damage-resistant packaging with extended shelf life.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise for BPA-NI (non-intent) and polyester lining development concentrates at a handful of European research centers, constraining R&D velocity.
- Legacy canning line integration:Mid-sized French and Italian food processors operate equipment with 20-plus year depreciation cycles, slowing adoption of lightweighting and inspection technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Canned Food Packaging Market |
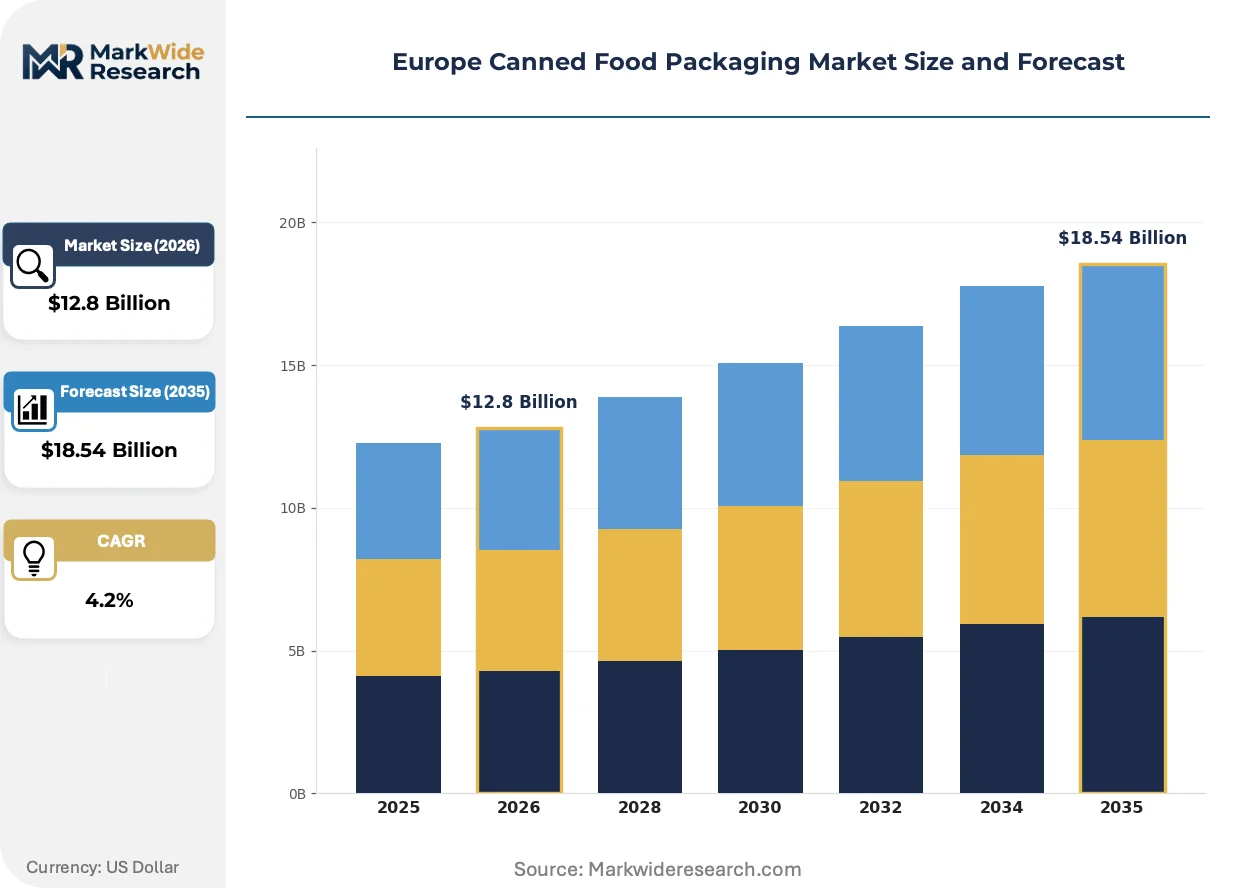
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Metal Cans, Glass Jars, Plastic Containers, Tetrapak Closure Type: Pull-Tab, Screw Caps, Twist-Off, Bimetallic End User: Retail Chains, Food Service Providers, Supermarkets, Distributors Technology: Vacuum Sealing, Aseptic Processing, Injection Molding, Can Filling |
| Companies Covered | Ardagh Group, Crown Holdings, Inc., Ball Corporation, Can-Pack S.A., Amcor Limited, Silgan Holdings Inc., CPMC Holdings Limited, Tetra Pak International, CCL Industries Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Canned Food Packaging Market Shifts & Advancements
European can makers are prioritizing material lightweighting and lining chemistry reinvention as dual pathways to compliance and cost reduction. These shifts are compressing traditional equipment lifecycles while opening margin pools for specialized substrate suppliers.
Polyester-based internal coatings are absorbing the functional role previously served by epoxy-phenolic linings in acidic food applications. German fish canners and Italian tomato processors are piloting these formulations at commercial scale. The technology is absorbing regulatory risk from ECHA's bisphenol scrutiny while demanding new curing oven configurations.
CSRD disclosure requirements are mandating granular Scope 3 emissions reporting across packaging supply chains. Metal can producers must now document recycled content percentages and end-of-life recovery rates for every EU member state market. Spanish and Portuguese food exporters face the steepest compliance burden as they serve multiple national Extended Producer Responsibility schemes.
Direct sourcing from can manufacturers is displacing traditional merchant distributor intermediaries among mid-sized European food brands. Buyers in the Netherlands and Belgium are negotiating annual volume contracts with Ardagh and Crown facilities rather than regional metal brokers. This channel compression is most visible in the organic and specialty food segment where traceability requirements favor supplier relationships with integrated quality documentation.
Europe Canned Food Packaging Market Segmentation
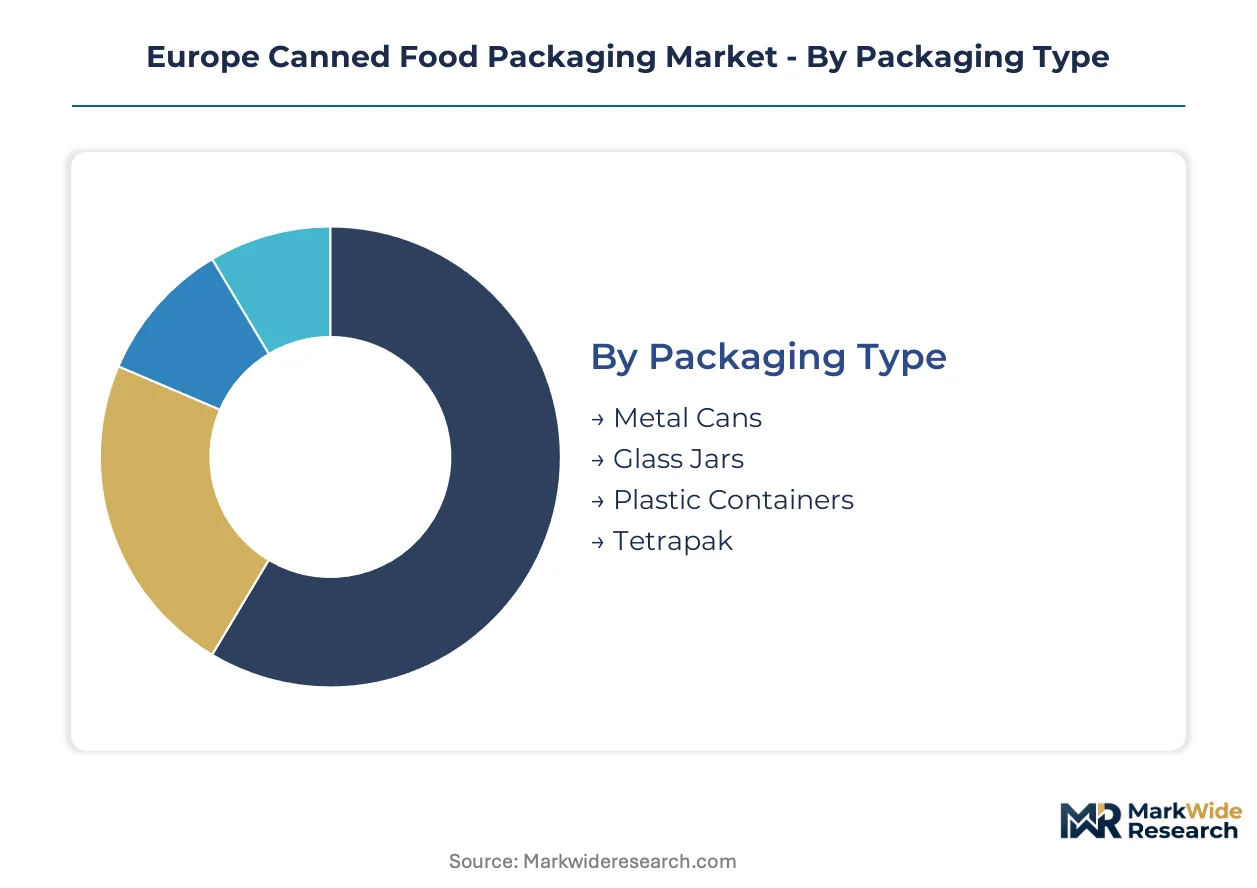
European canners select packaging formats based on thermal processing requirements, recyclability mandates under the EU Green Deal, and shelf-life specifications for ambient distribution. Segmentation reveals how coating chemistry approvals and material recovery infrastructure shape viable options across member states.
Packaging Type:
EFSA food contact material approvals and REACH substance restrictions determine which substrates qualify for EU market entry, with recycled content thresholds varying by national implementation of Extended Producer Responsibility schemes.
- Metal Cans:Constructed from tinplate or aluminum alloys between 0.15 and 0.25 millimeters wall thickness, these containers rely on epoxy-phenolic or polyester internal linings to prevent metal-ion migration into acidic foods. German fish processors and Italian tomato canneries anchor demand as they modernize lines to meet ECHA's evolving bisphenol restrictions. Germany's VerpackG imposes strict recovery documentation, favoring formats with established closed-loop recycling.
- Glass Jars:Borosilicate and soda-lime compositions withstand thermal processing temperatures while offering chemical inertness for premium preserves and sauces. French organic food brands in Provence and the Loire Valley specify glass for traceability-sensitive products, though weight penalties elevate logistics costs versus metal alternatives.
- Plastic Containers:Polypropylene and polyethylene terephthalate formats serve ready-meal segments where microwaveability commands retail positioning. EFSA migration limits constrain additive packages, with Spain and Portugal enforcing additional national testing protocols for polymeric food contact.
- Tetrapak:Laminated paperboard structures with aluminum barrier layers capture ambient soup and dairy alternatives in Nordic retail channels, though multi-material construction complicates sorting under EU Packaging and Packaging Waste Directive targets.
Leading the category by volume: Metal Cans. Growing fastest: Tetrapak.
Closure Type:
Opening convenience and hermetic integrity requirements vary sharply across retail versus foodservice channels, with resealability premiums concentrated in single-serve and household formats.
- Pull-Tab:Aluminum ring-pull mechanisms dominate two-piece beverage and food cans, eliminating separate opener dependency. Aldi and Lidl private-label ranges across Poland and Spain standardize on this format for cost efficiency at high throughput.
- Screw Caps:Metal or thermoplastic threaded closures enable resealing for multi-use glass jar applications. German sauerkraut and pickled vegetable processors specify deep-thread designs for pressure retention during pasteurization cycles.
- Twist-Off:Lug-style metal caps with plastisol gaskets provide tamper-evident seals for heat-processed preserves. Italian conserve producers in Emilia-Romagna favor this mechanism for traditional fruit and tomato products.
- Bimetallic:Tinplate-aluminum hybrid constructions balance corrosion resistance with lightweighting in specialty seafood applications. French Brittany sardine canneries specify these for coastal humidity exposure.
Volume concentrates in Pull-Tab for standardized retail. Screw Caps command premium positioning through resealability.
End User:
Procurement scale and quality documentation requirements fragment demand, with direct manufacturer relationships displacing distributor intermediaries among traceability-focused buyers.
- Retail Chains:Discounters and supermarkets negotiate annual volume contracts with integrated documentation for organic and allergen-free claims. Netherlands and Belgian buyers source directly from Ardagh and Crown facilities rather than regional metal brokers.
- Food Service Providers:Institutional caterers and restaurant chains prioritize portion control and stackability for ambient storage. French collective catering sector specifications drive demand for standardized can dimensions compatible with automated kitchen equipment.
- Supermarkets:Traditional full-service grocers maintain broader format diversity including glass premium tiers. Italian Coop and Conad networks sustain multi-material assortments despite centralization pressures.
- Distributors:Merchant intermediaries retain relevance for smaller Spanish and Portuguese exporters serving multiple national Extended Producer Responsibility schemes with fragmented compliance needs.
Retail Chains capture the largest procurement volumes. Food Service Providers are expanding fastest as institutional catering consolidates.
Technology:
Regulatory scrutiny of thermal processing intensity and nutrient retention specifications drives equipment replacement cycles unevenly across member states.
- Vacuum Sealing:Reduced-temperature processing preserves vitamin and protein profiles in premium vegetable and fish segments. Italian and French retailers command shelf price premiums for vacuum-sealed artichoke hearts and tuna products.
- Aseptic Processing:Sterile filling and sealing of pre-sterilized containers enables ambient storage without retort thermal exposure. SIG Combibloc and Tetra Pak capture ready-to-eat soup volumes previously held by steel cans in Nordic markets.
- Injection Molding:Thermoplastic container formation serves barrier-coated polypropylene ready-meal trays. German engineering integration dominates equipment supply for this segment.
- Can Filling:Traditional seaming and retort processing remains cost-dominant for high-acid and low-acid shelf-stable foods. Legacy French and Italian canning lines with 20-plus year depreciation cycles slow adoption of lightweighting and inspection upgrades.
Vacuum Sealing leads technology investment for premium positioning. Aseptic Processing climbs fastest as processors seek thermal reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German food processors generate the strongest pull for advanced canning solutions as discount grocery chains expand private-label shelf-stable ranges across the continent.
Germany
Aldi and Lidl are extending canned food assortments nationwide, creating standardized demand for two-piece aluminum formats. VerpackG mandates strict recovery documentation for metal packaging, elevating compliance costs versus flexible alternatives. Food processors in Baden-Württemberg are modernizing canning lines to meet ECHA's evolving bisphenol restrictions.
France
Organic food brands in Provence and the Loire Valley specify glass jars for traceability-sensitive preserves, sustaining multi-material procurement patterns. AGEC law imposes rising Extended Producer Responsibility fees on metal packaging, structurally shifting cost comparisons. Brittany sardine canneries specify bimetallic hybrid constructions for coastal humidity exposure.
Italy
Tomato processors in Emilia-Romagna and artichoke canners in Puglia pilot polyester-based internal coatings at commercial scale. EFSA food contact material guidelines constrain substrate choices for acidic food applications. Traditional conserve producers in Emilia-Romagna favor twist-off lug-style caps for heritage fruit products.
Spain
Spanish food exporters face steep CSRD compliance burdens as they serve multiple national Extended Producer Responsibility schemes across EU markets. National testing protocols for polymeric food contact materials exceed baseline EFSA requirements. Processors in Murcia and Valencia are negotiating direct annual volume contracts with integrated can manufacturers rather than regional metal brokers.
Poland
Modern retail density remains below Western European benchmarks, offering first-mover positioning for canning line investments serving emerging discount chains. EU Green Deal circularity incentives favor aluminum formats with established closed-loop recycling infrastructure. Food processors in the Łódź and Wrocław clusters are expanding capacity to supply Lidl and Biedronka private-label ranges.
Europe Canned Food Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent sustainable coating technologies and lightweight substrate niches. The supplier base concentrates around integrated metal supply networks and specialized two-piece aluminum fabricators. Three archetypes dominate: diversified packaging conglomerates with cross-material portfolios, pure-play metal can specialists with deep coating expertise, and multi-material challengers serving regional brand fragmentation. Competitive moves center on backward integration into recycled aluminum sourcing and strategic partnerships with coating chemistry innovators to secure REACH-compliant formulation pipelines.
Within the integrated network tier, Ardagh Group and Crown Holdings, Inc. exemplify scale-driven positioning across multiple European production facilities. Silgan Holdings Inc. occupies a diversified archetype spanning metal, glass, and plastic formats for fragmented regional food brand demand. These three anchors represent contrasting strategic postures: captive metal supply control, deep specialization in aluminum can technology, and portfolio breadth across substrate categories.
| Leading Market Players |
|---|
| Ardagh Group |
| Crown Holdings, Inc. |
| Ball Corporation |
| Can-Pack S.A. |
| Amcor Limited |
| Silgan Holdings Inc. |
| CPMC Holdings Limited |
| Tetra Pak International |
| CCL Industries Inc |
| Others |
Supply & Pricing Matrix
Coating chemist concentration in German industrial clusters creates labor-cost differentials that widen pricing-tier spreads between REACH-compliant premium suppliers and standard-tier competitors. Formulation expertise scarcity in Baden-Württemberg and the Rhineland elevates specialist wages, forcing buyers to absorb premium differentials or accept longer lead times from lower-tier sources.
Pricing Analysis
Volume concentrates in standardized two-piece aluminum cans for discount retail, while margin pools accrue to polyester-lined specialty formats serving premium fish and vegetable segments. Price differentiation separates REACH-compliant coating grades from legacy epoxy-phenolic alternatives, with ECHA substance restrictions acting as the primary tiering mechanism. Pricing pressure stems from tinplate cost volatility driven by ArcelorMittal and thyssenkrupp supply dominance, compressing predictability for mid-tier can makers. Discount grocery chains exhibit highest price sensitivity, while organic food brands in France and Italy tolerate premium positioning for traceability documentation.
Supply Chain Analysis
Regional distribution centers in Germany, Poland, and Spain anchor hub-and-spoke patterns serving Aldi and Lidl private-label networks. Raw material dependencies center on tinplate and aluminum substrate from European steel mills, polyester resin feedstocks, and oleoresin lining compounds. Supply chain risk concentrates in single-source vulnerability for BPA-NI coating formulations, where ECHA restrictions have collapsed qualified supplier lists. Distribution runs through direct manufacturer relationships displacing regional metal brokers, particularly among Dutch and Belgian buyers seeking integrated quality documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where REACH compliance costs and CSRD disclosure burdens force sub-scale coating specialists and legacy equipment operators toward exit. Regulatory complexity advantages integrated producers with captive R&D and documentation infrastructure.
For Market Incumbents: Lock in coating chemistry pipelines through exclusive partnerships with German research centers developing polyester and oleoresin alternatives. Secure backward integration into recycled aluminum sourcing to capture EU Green Deal circularity subsidies. Threat substitution from aseptic carton formats in Nordic markets demands premium positioning through vacuum sealing technology investment. For New Entrants and Emerging Players: Capture white-space opportunity in Poland and Romania where modern retail density trails Western benchmarks and discount chain expansion outpaces local canning capacity. Target emerging private-label ranges at Biedronka and emerging Lidl operations with standardized two-piece aluminum formats. Go-to-market leverage rests on offering REACH-compliant coating documentation bundled with volume contracts. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier metal can specialists possessing integrated scrap processing and established EFSA coating approvals, given EU Green Deal recycled content mandates accelerating format preference shifts. Long-term viability favors producers with geographic diversification across German, French, and Italian regulatory jurisdictions. Signal to monitor: ECHA bisphenol restriction timeline acceleration triggering forced equipment replacement cycles among legacy processors.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Coating Investment | Polyester and oleoresin R&D partnerships with ECHA substance restrictions secure premium market access. |
| Recycled Aluminum Integration | Captive scrap processing capabilities unlock EU Green Deal circularity subsidies across member states. |
| Direct Manufacturer Contracting | Annual volume agreements with Dutch and Belgian buyers displace regional metal broker intermediaries. |
| Vacuum Sealing Technology Deployment | Reduced thermal processing preserves nutrient profiles commanding shelf price premiums in Italian retail. |
| Poland-Romania Capacity Expansion | First-mover positioning serves underpenetrated discount grocery growth in emerging Central European markets. |
Research Methodology
Multi-period observation of coating chemistry approval timelines, ECHA substance restriction trajectories, and discount grocery private-label expansion anchored the trend analysis, supplemented by interviews with can manufacturing plant managers, food processor procurement leads, coating R&D directors, and retail category buyers. Secondary validation drew from EFSA food contact material guidelines, EU Packaging and Packaging Waste Directive implementation reports, national Extended Producer Responsibility scheme filings, and trade customs data. Bottom-up demand modeling across end-user segments triangulated against top-down macroeconomic indicators for European food packaging consumption.
Input-output matrices mapped substrate material flows through coating application, forming, and filling stages across the projection horizon. Segmentation dimensions modeled include packaging type, closure mechanism, end-user channel, and processing technology tier. CAGRs derived from elasticity-adjusted volume projections incorporating ECHA regulatory phase-in assumptions and retail format penetration curves. Industry-specific forecast inputs encompassed tinplate price indices and aluminum scrap recovery rates.
The model holds under stable REACH implementation schedules and continued EU Green Deal subsidy continuity; deviation in ECHA acceleration timelines or member state EPR fee structures would shift volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Food Punnets Market
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Food Can Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Hot Drinks Packaging Market