
 Ambient Food Products Packaging Market | 2026-2036
Ambient Food Products Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Ambient Food Products Packaging Market Outlook
Retail shelf space allocation is tilting toward ambient-stable categories, forcing packaging suppliers to align volume commitments with private-label and branded food programs. Amcor Limited leverages its global film and paperboard footprint to secure multi-year supply contracts with retailers. Tetra Pak sustains technology leadership in aseptic carton systems for shelf-stable dairy and beverages. Berry Global competes through rigid container specialization for sauces, soups, and ready-to-eat meals.
Ambient food products packaging denotes barrier-engineered enclosures designed to preserve shelf-stable foods without refrigeration, typically incorporating oxygen scavengers, moisture barriers, and light-blocking layers to achieve 6-24 month stability at 20-25°C. The primary commercial purpose is to extend distribution reach for perishable food categories while eliminating cold-chain dependency and associated energy costs. Flexible packaging dominates volume in snack and sauce applications where lightweight films reduce freight expense, while rigid packaging commands margin pools in premium segments requiring stack strength and resealability. Paperboard growth is accelerating as EU Green Deal mandates and FDA food-contact regulations push brands away from multi-layer plastics toward renewable, fiber-based substrates with compatible barrier coatings.
FDA food-contact substance notifications and EU REACH compliance on adhesive and coating chemistries are reshaping material qualification timelines for suppliers serving North American and European food manufacturers. China's SAMR national food safety standards and GB packaging regulations impose additional testing protocols for imports, creating divergent certification burdens for multinational converters. Stakeholders must monitor how extended producer responsibility frameworks in the EU, California, and emerging Asian markets redefine cost allocation between packaging producers and food brand owners.
Market Dynamics
EU Green Deal mandates on packaging recyclability are forcing material substitution away from multi-layer plastics toward fiber-based substrates with compatible barrier coatings, compressing qualification timelines for converters serving European food manufacturers.
Growth Catalysts
- Shelf-Stable Dairy Expansion:Aseptic carton technology is capturing volume from chilled distribution in emerging markets, eliminating cold-chain infrastructure requirements for milk and yogurt products.
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content targets are accelerating paperboard and aluminum substrate adoption across ready-meal and sauce categories.
- Ready-to-Eat Meal Proliferation:Urbanization in Brazil and China is concentrating demand for retort pouch and bowl formats that withstand 121°C sterilization.
Market Restraints
- Aluminum Price Volatility:Energy-intensive smelting costs in China and Russia are transmitting unpredictability into lidstock and tray pricing for converters.
- Adhesive Supply Concentration:European and Japanese specialty chemical producers control solvent-free laminating adhesive formulations, creating single-source risk for barrier film assemblers.
- Multi-Material Recycling Limitations:Current mechanical separation infrastructure cannot process metallized film-paperboard laminates, diverting post-consumer waste to energy recovery rather than circular loops.
Strategic Opportunities
- Mono-Material Flexible Packaging:Polyethylene and polypropylene barrier structures compatible with existing store-dropoff collection streams are capturing share from incompatible multi-polymer formats.
- India Ambient Food Production:FSSAI standardization of UHT milk and retort curry packaging is opening volume commitments for aseptic carton and pouch converters.
- Digital Printing Integration:Inkjet and toner systems are enabling SKU proliferation and seasonal versioning without plate costs, compressing minimum order quantities for private-label programs.
Industry Challenges
- Barrier Coating Qualification:Water-based and bio-derived oxygen barrier chemistries require 18-24 month migration testing under FDA and EU food-contact protocols.
- Legacy Equipment Retrofit Costs:Converting lines designed for solvent-based adhesives demand capital-intensive ventilation and drying system modifications to handle aqueous alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ambient Food Products Packaging Market |
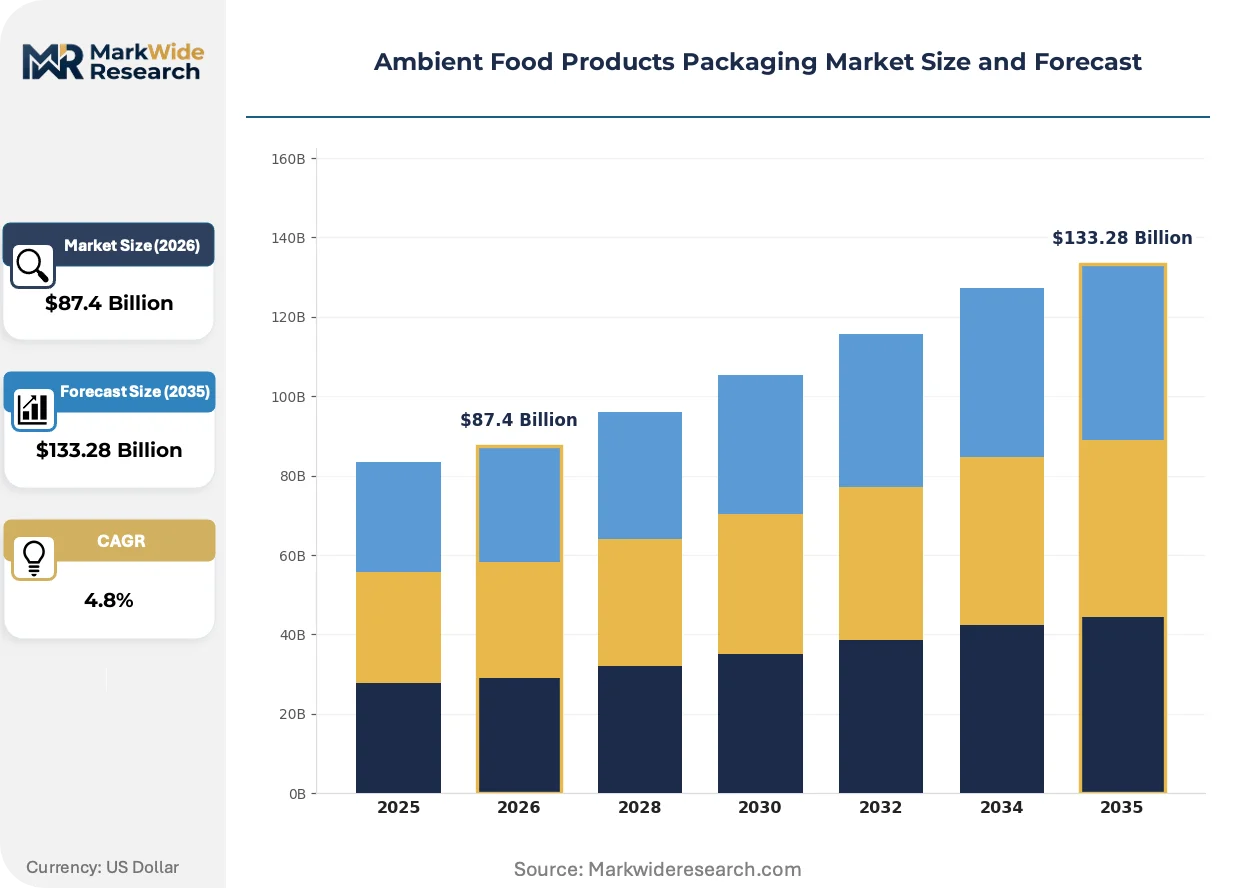
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Multi-pack Material: Polypropylene, Paperboard, Glass, Aluminum End User: Food Manufacturers, Retailers, Food Service Providers, E-commerce Closure Type: Screw Cap, Snap-on Cap, Peel-off Lid, Vacuum Seal |
| Companies Covered | Alexir Partnership, Alto Packaging, Amcor Limited, Berry Global, Rexam, Tetra Pak, Marsden Packaging Limited, WestRock Company, SIG Combibloc Obeikan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ambient Food Products Packaging Market Strategic Shifts
Active and intelligent packaging systems are embedding sensing and communication capabilities directly into barrier structures, transforming passive enclosures into data-generating supply chain nodes.
Printed electronics integration is digitizing temperature and freshness monitoring for ambient-stable pharmaceuticals and premium ready meals. Pharmaceutical and high-value food logistics providers are piloting NFC-enabled cartons that transmit chain-of-custody data to blockchain verification platforms. This capability is digitizing quality assurance workflows and compressing insurance and liability exposure for temperature-sensitive shipments.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating grease-resistant fluorochemical coatings from paperboard foodservice applications. EU member state enforcement divergence is creating compliance complexity for pan-European suppliers, with Germany and Denmark advancing stricter timelines than the bloc-wide baseline. Paperboard converters are responding with silicone and bio-wax alternative formulations that sacrifice some performance for regulatory certainty.
Retailers are consolidating secondary packaging specifications to reduce handling complexity in automated distribution centers. Walmart and Carrefour are mandating standardized case dimensions and barcode placement across ambient food suppliers, displacing brand-customized shipping containers. This standardization is most visible in North American and Western European dry grocery and beverage categories where pallet optimization drives freight economics.
Ambient Food Products Packaging Market Segmentation
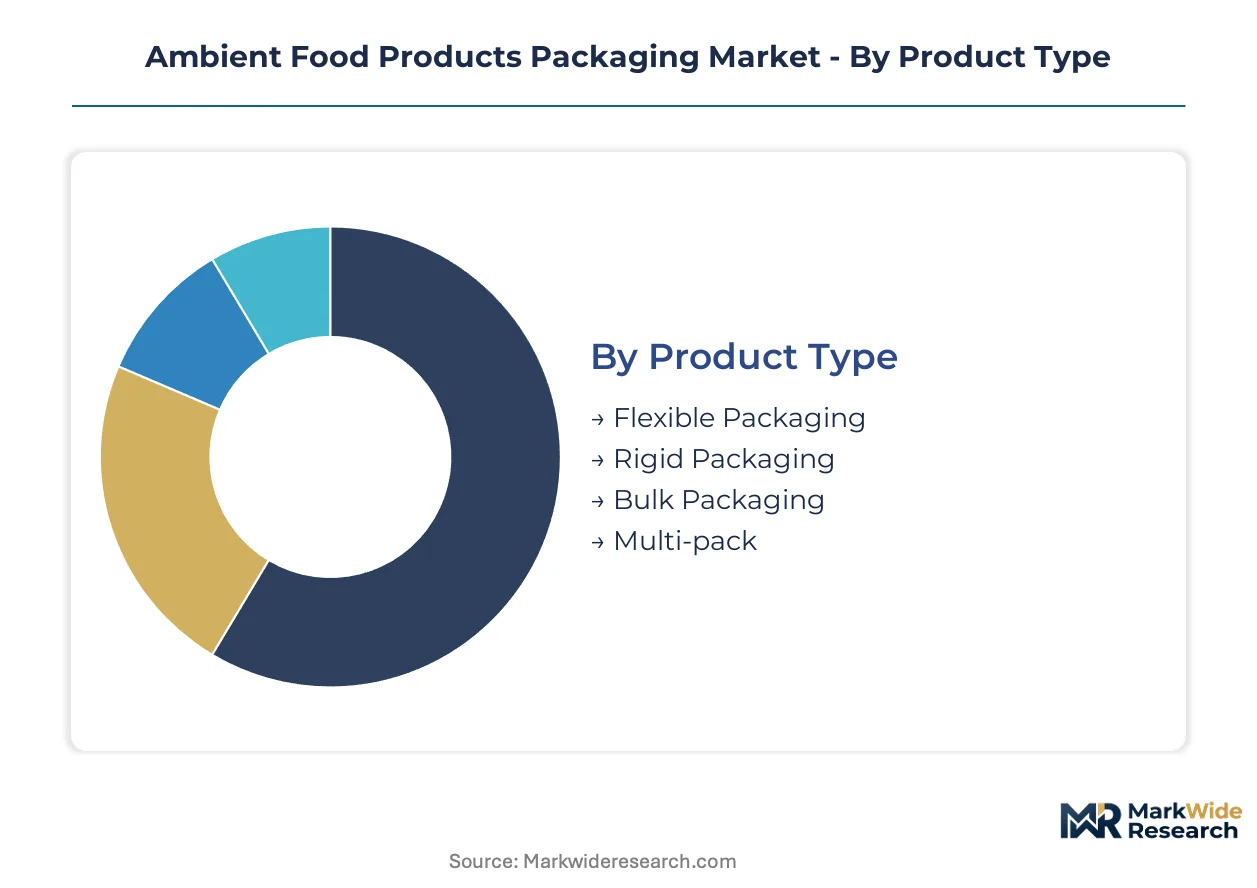
Ambient food packaging segmentation reflects divergent technical requirements across shelf-stable categories. Material choices and format specifications vary sharply between aseptic dairy, retort meals, and ambient sauces, driving specialized converter capabilities.
Product Type:
Mature formats dominate volume, while emerging structures capture reformulation-driven substitution.
- Flexible Packaging:Multi-layer films with oxygen scavengers and moisture barriers achieve 12-24 month stability for sauces and snacks. Demand concentrates in Brazil and China where retort pouch adoption for ready-to-eat meals eliminates refrigerated distribution infrastructure.
- Rigid Packaging:Injection-molded polypropylene and thermoformed trays provide stack strength and resealability for premium ready meals. Germany's private-label retailers specify rigid formats for shelf-stable curry and pasta dishes requiring microwave reheating.
- Bulk Packaging:Industrial pails and bag-in-box systems serve foodservice and institutional procurement.
- Multi-pack:Shrink-wrapped and paperboard-bundle configurations address club store and e-commerce fulfillment economics.
Flexible packaging handles the majority of throughput; rigid packaging is the fastest mover on share.
Material:
Cost tiers separate commodity substrates from barrier-engineered alternatives with regulatory-compliant coatings.
- Polypropylene:Oriented and cast films provide moisture barriers and heat-seal layers for pouch and lidstock applications. China's SAMR food-contact protocols are accelerating homopolymer qualification for domestic UHT milk packaging.
- Paperboard:Liquid packaging board with polyethylene extrusion or aluminum lamination dominates aseptic carton volumes. EU Green Deal recyclability mandates are redirecting European dairy brands toward fiber-based substrates with water-based barrier coatings.
- Glass:Premium sauce and condiment applications leverage inert chemistry and optical clarity for brand differentiation.
- Aluminum:Tray and lidstock formats withstand 121°C retort sterilization for shelf-stable proteins and complete meals.
Polypropylene handles the majority of throughput; paperboard is expanding most quickly on regulatory tailwinds.
End User:
Customer type determines order scale, specification complexity, and co-development intensity with converters.
- Food Manufacturers:Multinational dairy and sauce processors specify custom barrier structures with 18-24 month shelf life validation. Nestlé and Unilever procurement teams in Germany and Brazil are consolidating supplier panels to secure volume commitments for aseptic carton and retort pouch formats.
- Retailers:Private-label programs demand rapid SKU versioning and seasonal graphics flexibility. Carrefour and Walmart are standardizing secondary packaging dimensions across ambient food categories to optimize automated distribution center throughput.
- Food Service Providers:Institutional and chain restaurant procurement favors bulk formats with portion-control dispensing.
- E-commerce:Direct-to-consumer ambient meal kits require damage-resistant primary and secondary packaging for parcel network handling.
Food manufacturers handle the majority of throughput; e-commerce is climbing the fastest on channel shift.
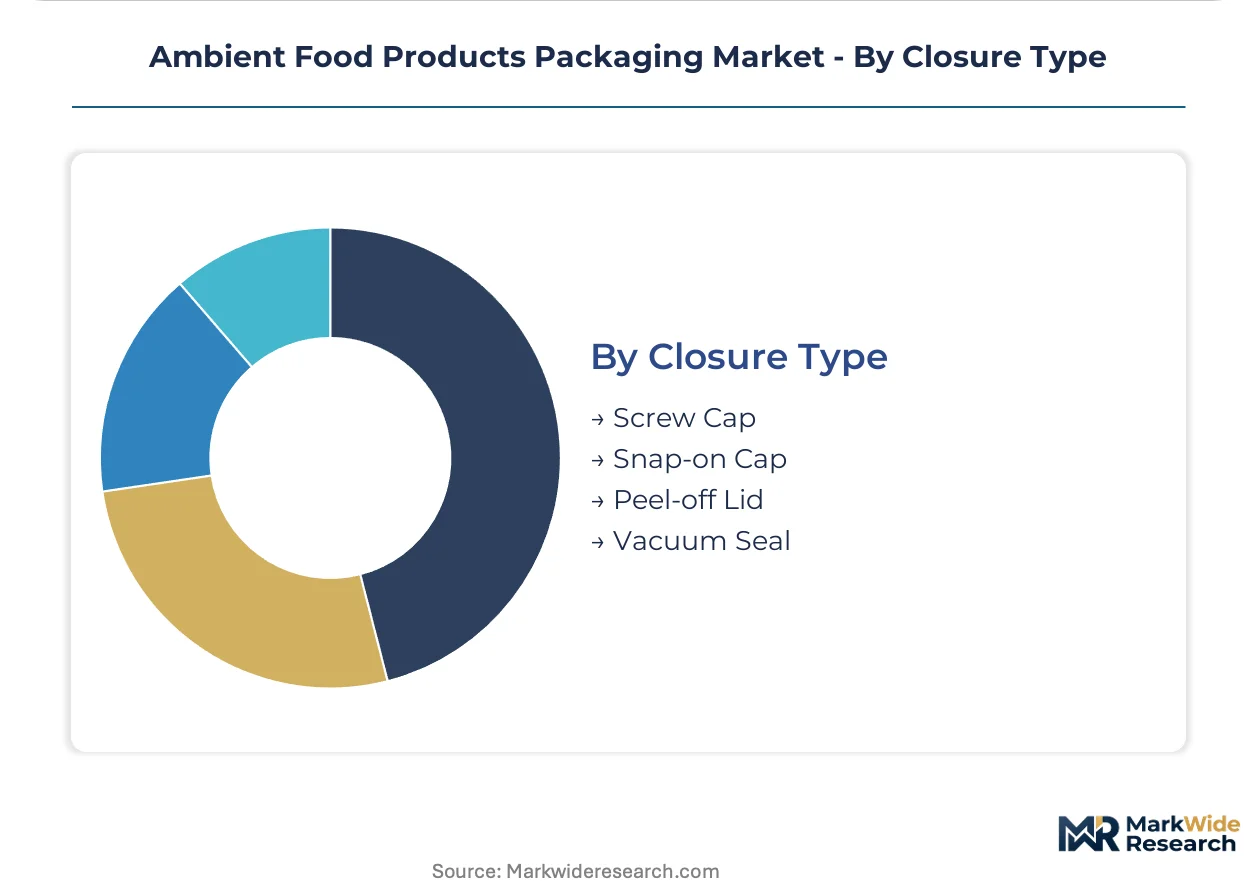
Closure Type:
Application requirements dictate resealability, tamper evidence, and consumer convenience trade-offs.
- Screw Cap:Injection-molded polypropylene closures with induction seals provide resealability for ambient beverages and cooking sauces. China's expanding UHT juice sector is standardizing 38mm neck finishes compatible with existing filling equipment.
- Snap-on Cap:Press-fit closures enable single-serve convenience for dairy and dessert applications. Germany's Aldi and Lidl private-label programs specify snap-on formats for ambient yogurt drinks to reduce unit cost versus threaded alternatives.
- Peel-off Lid:Aluminum and metallized film lidding provides tamper evidence and easy opening for retort trays and portion cups.
- Vacuum Seal:Heat-sealed flexible films achieve oxygen exclusion for shelf-stable meat and fish products.
Screw cap handles the majority of throughput; peel-off lid is gaining share fastest on ready-meal proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Germany command premium pricing for aseptic carton substrates, while Brazilian suppliers compete on volume for retort pouch formats, revealing a stark pricing-power asymmetry between European precision engineering and Latin American scale manufacturing.
Germany
Aldi and Lidl private-label programs drive demand for rigid polypropylene trays in shelf-stable curry and pasta segments. EU Green Deal recyclability mandates accelerate paperboard substrate adoption with water-based barrier coatings. The Rhine-Ruhr industrial corridor hosts specialized converters retrofitting legacy solvent-based adhesive lines for aqueous alternatives.
China
UHT milk and retort-ready meal production expansion concentrates demand for aseptic carton and multilayer pouch formats. SAMR national food-safety standards impose additional testing protocols for imported packaging materials. The Yangtze River Delta manufacturing belt sees dairy processors consolidating supplier panels to secure volume commitments.
Brazil
Urbanization and cold-chain infrastructure gaps propel retort pouch and bowl adoption for shelf-stable proteins and complete meals. ANVISA pharmaceutical and food-contact regulations align with Mercosur technical standards for barrier material qualification. São Paulo state food manufacturers are standardizing 121°C sterilization-compatible formats to eliminate refrigerated distribution.
United States
Walmart's standardized secondary packaging specifications compress SKU variety for ambient food suppliers serving automated distribution centers. FDA food-contact substance notifications extend qualification timelines for novel barrier coatings. The Midwest dairy processing cluster demands extended shelf-life validation for aseptic carton systems replacing chilled distribution.
India
FSSAI standardization of UHT milk and retort curry packaging opens volume commitments for converters with aseptic and high-barrier capabilities. BIS certification requirements for food-contact materials create domestic qualification advantages over importers. Maharashtra and Gujarat dairy cooperatives are expanding ambient-stable product lines to bypass cold-chain limitations in rural distribution.
Ambient Food Products Packaging Market Competitive Environment
Integrated material-science conglomerates and specialized rigid-container fabricators split the market between substrate innovation and format engineering. The competitive structure tilts toward consolidation at the substrate layer and fragmentation at the converting tier. Three archetypes dominate: global film-and-paperboard suppliers with multi-year retail contracts, aseptic-system technology licensors with proprietary filling equipment ecosystems, and regional rigid-container specialists serving private-label programs. Capacity expansion and mono-material portfolio diversification represent the dominant competitive moves as recyclability mandates reshape material specifications.
Within the integrated-materials tier, Amcor Limited and Berry Global occupy positions spanning flexible film and rigid container supply. Tetra Pak exemplifies the technology-licensor archetype through its aseptic carton system dominance. WestRock Company represents the fiber-based substrate vector accelerating on EU regulatory tailwinds. Marsden Packaging Limited and Alto Packaging sit within the mid-scale converting specialist category serving UK and European private-label programs with customized barrier structures.
| Leading Market Players |
|---|
| Alexir Partnership |
| Alto Packaging |
| Amcor Limited |
| Berry Global |
| Rexam |
| Tetra Pak |
| Marsden Packaging Limited |
| WestRock Company |
| SIG Combibloc Obeikan |
| Others |
Value Chain & Pricing Dynamics
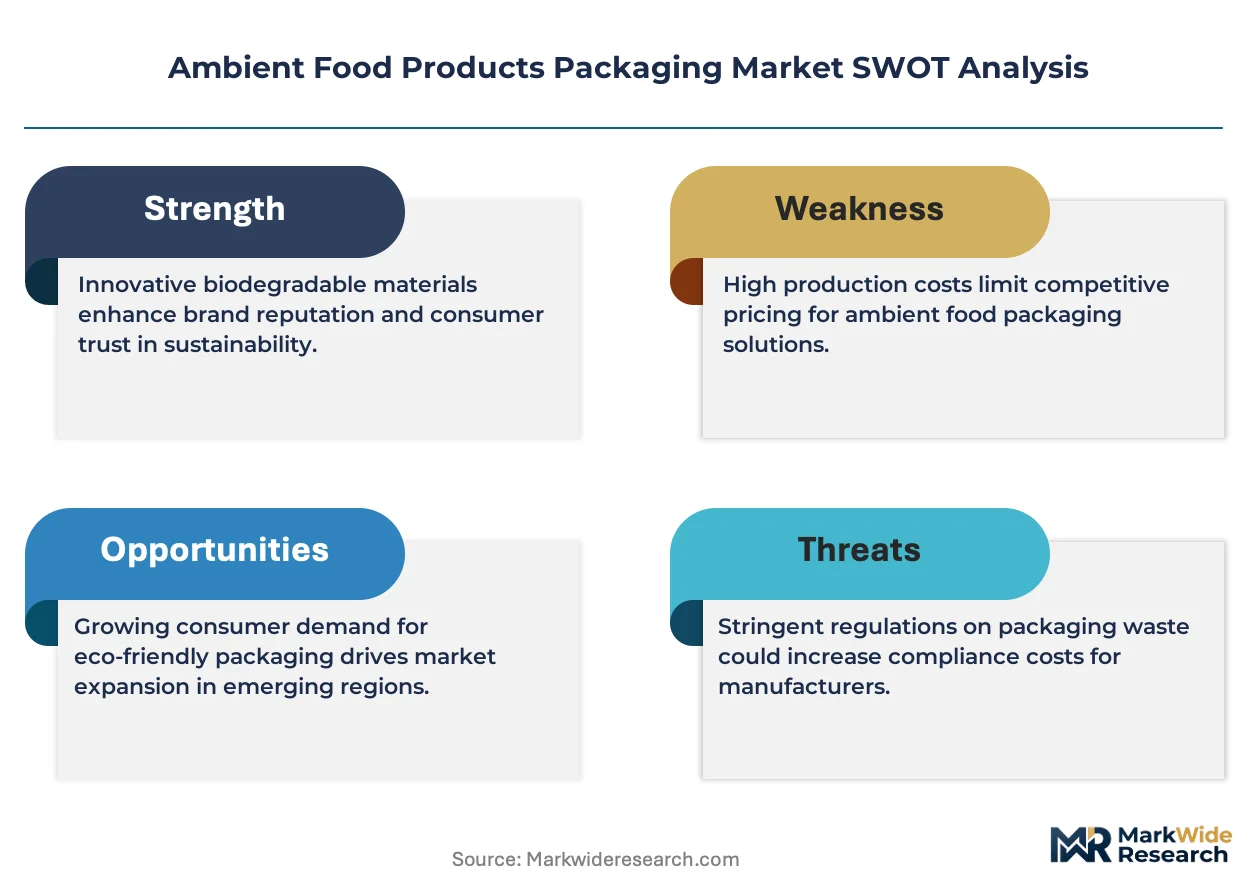
The Rhine-Ruhr industrial corridor anchors European aseptic carton substrate capacity, and its specialized converters command premium pricing for barrier-engineered paperboard with EU Green Deal-compliant water-based coatings. German engineering precision translates into 15-20% pricing premiums over Latin American volume suppliers, though Brazilian retort pouch manufacturers capture cost-sensitive ready-meal segments through scale economics.
Pricing Analysis
The customization-premium spread separates configured-to-order barrier structures from standard catalog formats by 25-40%. Contract-based long-term offtake dominates procurement between multinational dairy processors and integrated film suppliers, with price differentiation resting on FDA food-contact certification tier and volume scale commitments. Cost compression in standard-grade polypropylene films is intensifying because Chinese capacity expansion feeds global spot markets. Private-label retailers at Aldi and Lidl exhibit highest price sensitivity, while pharmaceutical-logistics providers purchasing NFC-enabled intelligent packaging show least sensitivity due to liability-insurance bundling.
Supply Chain Analysis
Contract manufacturing concentration sits with Tetra Pak's proprietary aseptic filling ecosystems and Amcor's integrated film-converting networks, supplemented by regional specialists in São Paulo and Mumbai. Geographic supply concentration centers on Germany for precision-engineered substrates, China for commodity polypropylene films, and Brazil for retort-compatible multilayer structures. Raw material dependencies draw from Saudi petrochemical feedstocks, Chilean aluminum smelter output, and Nordic pulp mills. Single-source vulnerability pervades European solvent-free laminating adhesive supply, with Japanese and German specialty chemical producers controlling formulation IP. Distribution runs through automated retail distribution centers mandating standardized case dimensions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ambient food packaging market functions as a service-attach opportunity where digital printing integration and intelligent packaging data layers expand faster than commodity substrate supply. Recurring revenue from SKU versioning services and blockchain-verified chain-of-custody subscriptions outpaces hardware margin capture.
For Market Incumbents: Entrench through captive supply of mono-material barrier films compatible with EU Green Deal recyclability mandates, while retrofitting legacy solvent-based adhesive lines for aqueous alternatives. Tetra Pak and Amcor should deepen backward integration into water-based coating chemistry to offset Japanese adhesive supply concentration risk. Certification investment in China's SAMR protocols secures volume commitments from Yangtze River Delta dairy processors consolidating supplier panels. For New Entrants and Emerging Players: Mid-tier Indian dairy cooperatives in Maharashtra and Gujarat represent the most penetrable entry point, as FSSAI standardization of UHT milk packaging creates first-mover advantages for converters with aseptic capabilities. Brazil's cold-chain infrastructure gaps propel retort pouch demand for shelf-stable proteins in São Paulo state food manufacturers. Go-to-market angle: partner with European paperboard substrate suppliers to offer EU-compliant barrier coatings as a bundled qualification service. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EU Green Deal mandates and REACH restrictions on fluorochemical coatings force material substitution cycles that favor converters with qualified alternative formulations. Acquisition target archetype: mid-scale regional specialists with validated water-based barrier chemistries and retrofit-equipped converting lines. Signal to watch: FDA food-contact substance notification backlogs for novel oxygen barrier coatings, which would extend qualification timelines and inflate incumbents' switching-cost advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Portfolio Diversification | Polyethylene and polypropylene barrier structures compatible with store-dropoff streams capture share from multi-polymer formats. |
| Backward Integration into Barrier Coatings | In-house production of water-based oxygen barrier chemistries reduces dependency on Japanese and European adhesive suppliers. |
| Digital Printing Integration | Inkjet systems enable SKU proliferation for Walmart and Carrefour private-label programs without plate-change costs. |
| Intelligent Packaging Development | NFC-enabled cartons transmit chain-of-custody data to blockchain platforms, compressing insurance exposure for pharmaceutical logistics. |
| Geographic Capacity Expansion | Aseptic carton and retort pouch lines in India and Brazil bypass cold-chain limitations in rural distribution networks. |
Study Parameters
A spread of perspectives from packaging procurement directors at Nestlé and Unilever, plant managers at Rhine-Ruhr converting facilities, regulatory affairs leads navigating FDA and EU REACH compliance, and aftermarket service heads for aseptic filling equipment converged on the working assumptions. Secondary validation drew from FDA food-contact substance notifications, EU ECHA REACH substance registrations, SAMR GB standard filings, and SEC 10-K disclosures from integrated material-science conglomerates. Bottom-up and top-down triangulation reconciled converter capacity utilization rates with dairy processor volume commitments.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include packaging format (flexible, rigid, bulk, multi-pack), material substrate (polypropylene, paperboard, aluminum, glass), end-user archetype (food manufacturer, retailer, food service, e-commerce), and closure type (screw cap, snap-on, peel-off lid, vacuum seal). CAGRs derived from regression analysis of historical capacity expansion correlated with regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated EU Green Deal recycled content target phase-ins and FSSAI standardization schedules for UHT milk packaging.
Macroeconomic conditions sit as an overlay; deviation in aluminum smelting energy costs, pulp fiber pricing, and ocean freight rates would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement consistency across EU member states and SAMR import testing protocol stability. Quarterly review of adhesive supply chain disruptions, barrier coating qualification backlogs, and retailer private-label program expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
North America PET Food Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
Cereal Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Ready Meals Packaging Market