
 Global Disposable Tableware Market | 2026-2036
Global Disposable Tableware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Disposable Tableware Market Analysis
A shift from single-source plastic resin contracts toward multi-material supplier networks is repositioning procurement strategies across the disposable tableware value chain. Huhtamaki Oyj leverages its molded fiber technology leadership to anchor European QSR supply relationships. Pactiv Evergreen Inc sustains North American manufacturing scale through integrated resin-to-product operations. Dart Container Corporation dominates foam-based foodservice distribution through extensive wholesale channel control.
Disposable tableware encompasses single-use serving vessels and utensils manufactured from thermoformed plastics, molded pulp, extruded polystyrene, or laminated paperboard, typically designed for one meal cycle before disposal. Products must meet food-contact migration limits, grease resistance thresholds, and stacking strength parameters calibrated to automated filling lines. Plates and cups capture the dominant volume share across food service applications, while bamboo and molded fiber materials are expanding fastest as operators phase out conventional plastics. Paper-based cutlery occupies a narrower margin pool due to performance limitations in high-moisture applications, though coating innovations are narrowing this gap.
The EU Single-Use Plastics Directive and REACH chemical compliance frameworks are reshaping material eligibility across European supply chains, with EFSA food-contact assessments now gatekeeping novel biopolymer introductions. The US FDA maintains migration testing protocols for recycled content incorporation, while China's GB standards and SAMR oversight govern domestic production quality benchmarks. Stakeholders must monitor regulatory divergence between compostability certification schemes and actual industrial composting infrastructure availability.
Market Dynamics
Material substitution mandates across the European Union are compressing demand for conventional polystyrene tableware while redirecting capital toward molded fiber and biopolymer production lines. This regulatory pivot is restructuring supplier relationships and procurement specifications across foodservice channels.
Growth Catalysts
- EU Single-Use Plastics Directive:The directive bans expanded polystyrene food containers and cups, compelling QSR operators across Germany, France, and Italy to convert supply contracts toward fiber-based alternatives.
- India's urban food delivery corridors:Swiggy and Zomato's last-mile expansion into tier-2 cities is generating concentrated demand for compostable clamshell containers and bagasse plates.
- Molded fiber thermoforming:Advances in pulp molding automation are reducing unit costs for rigid food containers, enabling Southeast Asian quick-service restaurants to abandon plastic-lined paperboard.
Market Restraints
- Resin price volatility:Polypropylene and polystyrene feedstock costs fluctuate with crude oil benchmarks, compressing margins for integrated manufacturers dependent on virgin resin supply.
- Composting infrastructure gaps:Industrial composting facilities remain concentrated in Western Europe and select US coastal states, rendering PLA and bagasse products non-compostable in most disposal environments.
- Performance limitations of paper cutlery:Uncoated wooden and paper utensils fail in high-moisture applications exceeding fifteen minutes, restricting penetration into soup and noodle segments.
Strategic Opportunities
- Brazil's informal foodservice sector:Street vendors and open-air markets in São Paulo and Rio de Janeiro represent an underpenetrated channel for low-cost molded fiber plates and bowls.
- Deposit-return schemes:Germany's DRS expansion to foodservice packaging creates infrastructure for reusable container pooling systems that complement single-use alternatives.
- Barrier coating chemistry:Convergence of aqueous barrier coatings with high-speed paper cup forming lines enables grease-resistant performance without polyethylene lamination.
Industry Challenges
- Food-contact migration testing timelines:EFSA novel food assessments for emerging biopolymers extend eighteen to thirty-six months, delaying product launches for European markets.
- Automated filling line integration:Fiber-based containers exhibit variable dimensional tolerances that disrupt high-speed cup dispensers and lidding equipment calibrated to plastic specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Disposable Tableware Market |
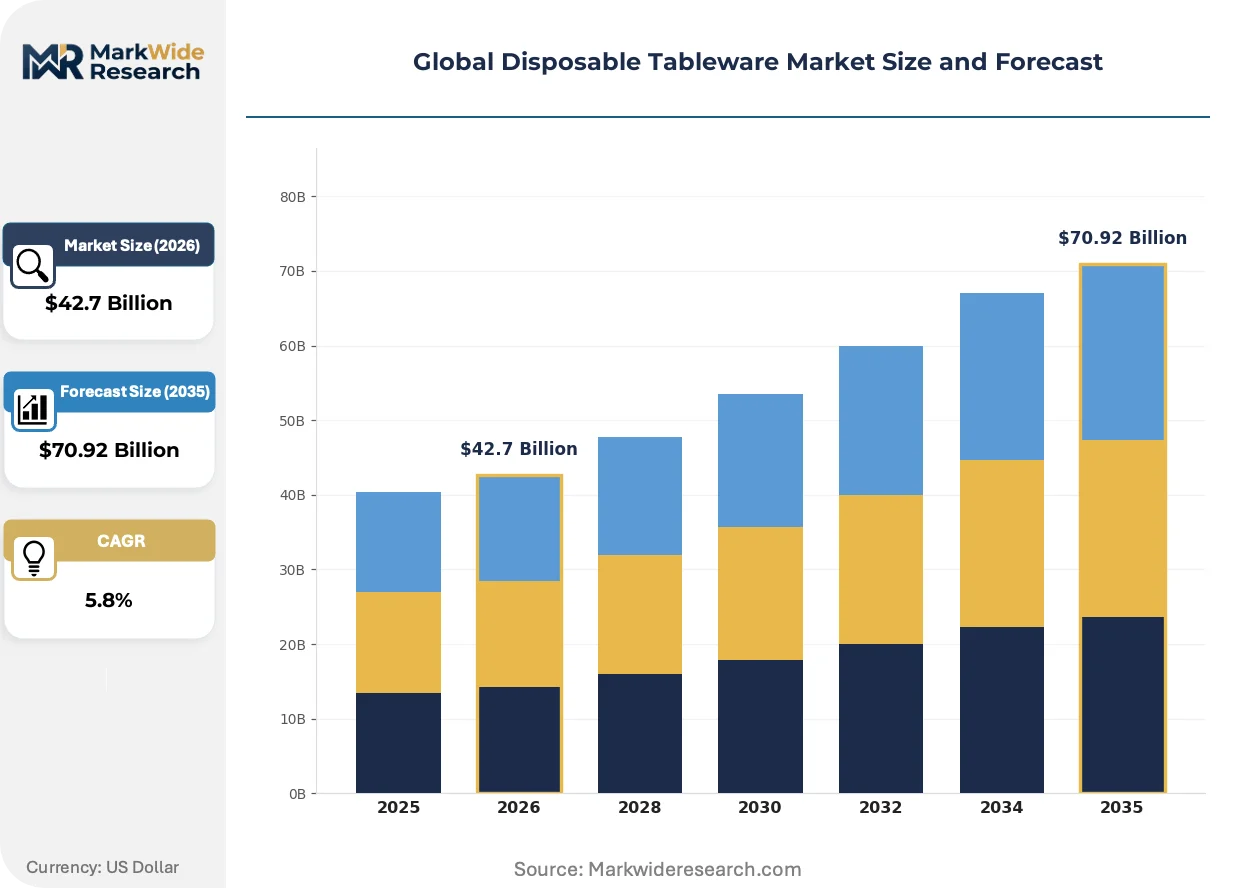
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $70.92 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Bowls, Cups, Cutlery Material: Plastic, Paper, Bamboo, Foam Application: Food Service, Catering, Events, Outdoor Activities Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Pactiv Evergreen Inc, Berry Global, Inc., Dart Container Corporation, Duni Group, Graphic Packaging, Huhtamaki Oyj, Novolex Holdings, LLC, Vegware Ltd., Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Disposable Tableware Market Emerging Trajectories
Barrier coating chemistry and forming automation are converging to close the performance gap between fiber-based and plastic tableware. These technical advances are reshaping procurement specifications and manufacturing investment priorities across foodservice supply chains.
Molded fiber technology is consolidating its position as the dominant alternative to conventional plastics in European and North American QSR supply chains. The material delivers grease resistance and structural rigidity sufficient for hot food applications without petroleum-based inputs. Major fast-casual chains in Germany and the Netherlands are converting entire SKU portfolios to fiber-based equivalents, compressing the addressable market for expanded polystyrene food containers.
REACH chemical compliance frameworks are tightening migration limits for recycled content incorporation across European supply chains. EFSA assessments now gatekeep all novel biopolymer introductions, extending qualification timelines and favoring incumbent suppliers with established regulatory dossiers. Small and mid-sized converters without dedicated compliance teams face exclusion from branded foodservice contracts.
Consolidated procurement by multinational QSR chains is compressing supplier diversity and favoring integrated manufacturers with multi-material capabilities. Single-source resin contracts are giving way to framework agreements covering plastics, fiber, and hybrid laminates under unified specifications. This pattern is most visible in the US and UK, where Yum! Brands and Compass Group have centralized category management for disposable tableware.
Global Disposable Tableware Market Segmentation
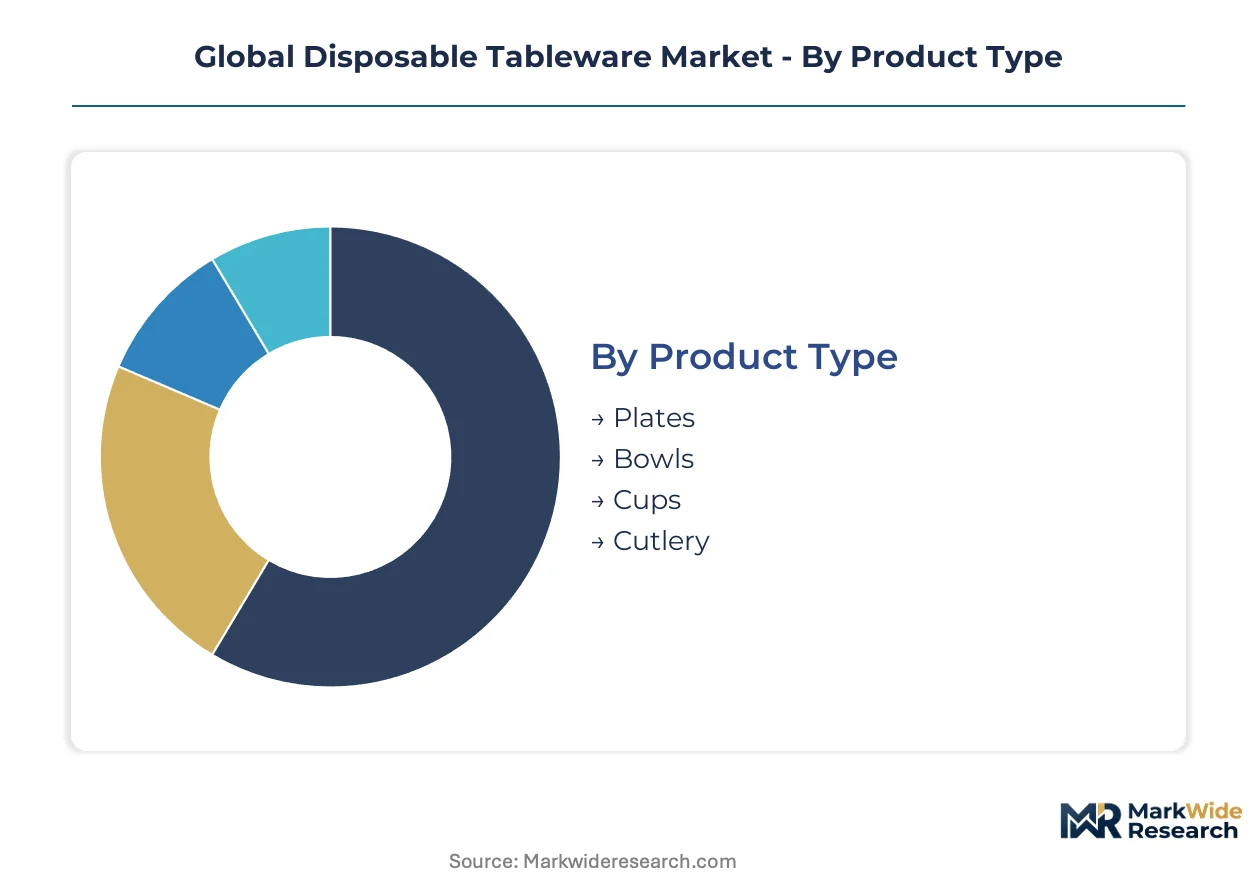
Segmentation in disposable tableware reveals how regulatory pressure and end-use requirements fragment procurement strategies. Each dimension carries distinct compliance burdens and margin profiles that reshape supplier positioning.
Product Type:
EFSA food-contact assessments and FDA migration protocols apply differentially across serving vessels, with dimensional tolerances and barrier requirements varying by product geometry.
- Plates:Flat-bottomed thermoformed or pressed fiber vessels designed for single-serve meals. Demand concentrates in European QSR chains converting from polystyrene under the EU Single-Use Plastics Directive, with automated filling lines requiring precise rim diameter consistency.
- Cups:Tapered vessels with rolled rims for lidding compatibility, manufactured from extruded polystyrene, polypropylene, or molded fiber with aqueous barrier coatings. India's urban food delivery corridors generate concentrated procurement of compostable cup formats for chai and lassi vendors.
- Bowls:Deep-drawn containers for soup and noodle applications requiring elevated rim strength.
- Cutlery:Single-use utensils facing performance limitations in high-moisture environments exceeding fifteen minutes.
Plates sit at the top of the volume ranking, with cups climbing the fastest.
Material:
Cost tiers stratify sharply between commodity resins and certified alternatives, with REACH compliance and compostability certification adding premium layers to fiber and biopolymer grades.
- Plastic:Thermoformed polypropylene and polystyrene resins calibrated to automated filling line specifications. Resin price volatility tied to crude oil benchmarks compresses margins for integrated manufacturers dependent on virgin feedstock supply.
- Paper:Laminated paperboard with polyethylene or aqueous barrier coatings for grease resistance. Germany's deposit-return scheme expansion to foodservice packaging redirects investment toward recyclable paper formats.
- Bamboo:Rapid-renewable grass fiber processed into rigid serving vessels.
- Foam:Expanded polystyrene containers facing phased bans across EU member states.
Plastic retains the dominant volume position, though bamboo is expanding most quickly as Southeast Asian QSR operators abandon conventional formats.
Application:
Customer type determines packaging performance requirements and regulatory exposure, with institutional buyers enforcing stricter sustainability specifications than individual consumers.
- Food Service:Quick-service restaurants and fast-casual chains requiring high-volume supply continuity and multi-material sourcing flexibility. Yum! Brands and Compass Group have centralized category management across plastics, fiber, and hybrid laminates.
- Catering:Event and institutional food providers with batch-variable demand patterns.
- Events:Temporary gatherings with concentrated waste generation and visibility-driven sustainability preferences.
- Outdoor Activities:Camping and recreational use cases prioritizing lightweight durability.
Food Service commands the largest volume share, with Events showing the steepest expansion trajectory as festival organizers adopt zero-waste mandates.
Distribution Channel:
Supply concentration varies by channel control, with wholesale networks dominating institutional procurement while direct-to-operator platforms fragment smaller buyer relationships.
- Online:E-commerce platforms serving fragmented small-restaurant and event-organizer demand with mixed-SKU fulfillment. Swiggy and Zomato's procurement platforms in India aggregate demand for compostable clamshell containers and bagasse plates.
- Supermarkets:Retail shelf presence for consumer partyware and household stock-up occasions.
- Specialty Stores:Premium and certified-sustainable formats for environmentally segmented buyers.
- Wholesale:Dart Container Corporation and Pactiv Evergreen sustain North American volume through extensive distributor relationships.
Wholesale channels handle the greatest throughput, with online gaining share fastest as food delivery platforms integrate procurement functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity is migrating toward jurisdictions with lower compliance costs for novel biopolymers, creating arbitrage opportunities between REACH-regulated European supply chains and emerging Asian manufacturing hubs. This geographic divergence is reshaping supplier networks and procurement specifications across foodservice channels.
Germany
Deposit-return scheme expansions to foodservice packaging are redirecting investment toward recyclable paper formats and reusable container pooling systems. EFSA assessments gatekeep novel biopolymer introductions, extending qualification timelines for converters serving branded QSR contracts. Berlin and Hamburg anchor molded fiber production clusters supplying Dutch and French quick-service restaurant chains.
United States
FDA migration testing protocols for recycled content incorporation are compressing launch timelines for sustainable product lines. Resin price volatility tied to crude oil benchmarks squeezes margins for integrated manufacturers dependent on virgin polypropylene supply. The Southeast manufacturing corridor concentrates foam-based foodservice distribution through extensive wholesale channel relationships.
India
Swiggy and Zomato's last-mile expansion into tier-2 cities is generating concentrated procurement of compostable clamshell containers and bagasse plates. FSSAI food-contact compliance frameworks govern domestic production quality benchmarks for urban food delivery corridors. Mumbai and Bangalore clusters specialize in molded fiber thermoforming for Southeast Asian QSR export markets.
China
GB standards and SAMR oversight govern domestic production quality benchmarks while dual carbon goals accelerate material substitution in coastal manufacturing zones. Pulp molding automation advances are reducing unit costs for rigid food containers serving regional quick-service restaurant chains. The Yangtze River Delta concentrates integrated resin-to-product operations for Asia-Pacific export markets.
Brazil
Street vendors and open-air markets in São Paulo and Rio de Janeiro represent underpenetrated channels for low-cost molded fiber plates and bowls. ANVISA food-contact regulations apply less stringently to informal foodservice sectors than to institutional buyers. The Southeast industrial corridor is attracting Asian capital for bagasse processing facilities serving Mercosur trade bloc demand.
Global Disposable Tableware Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue certification-heavy sustainable formats to differentiate procurement relationships. The vendor base stratifies between integrated resin converters with captive supply chains and specialized fiber-forming operations serving sustainability-mandated accounts. Three archetypes dominate: multinational multi-material platforms, regional molded fiber specialists, and legacy foam distributors defending wholesale channel control. Competitive moves center on backward integration into pulp supply and strategic partnerships with QSR procurement platforms.
Within the multi-material platform tier, Pactiv Evergreen Inc and Huhtamaki Oyj exemplify integrated manufacturers sustaining volume through unified specifications across plastics, fiber, and hybrid laminates. Dart Container Corporation anchors the legacy distributor archetype with extensive wholesale relationships. These three occupy positions that reflect the market's structural tension between scale-driven resin operations and regulatory-displaced fiber alternatives.
| Leading Market Players |
|---|
| Pactiv Evergreen Inc |
| Berry Global, Inc. |
| Dart Container Corporation |
| Duni Group |
| Graphic Packaging |
| Huhtamaki Oyj |
| Novolex Holdings, LLC |
| Vegware Ltd. |
| Georgia-Pacific LLC |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in North American molded fiber production anchor supply discipline through consolidated procurement platforms, while family-owned mid-caps in Southeast Asia compete on resin-to-product integration. This ownership fragmentation produces divergent pricing power across the value chain, with integrated players capturing margin from volatile polypropylene feedstock exposure while fiber specialists extract premiums from EFSA-compliant certification tiers.
Pricing Analysis
Distributor margin layers dominate the European channel, with wholesale markups compressing as QSR procurement centralizes under framework agreements. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified fiber grades from conventional polystyrene and uncoated paper alternatives. Pricing pressure stems from resin price volatility tied to crude oil benchmarks, squeezing integrated manufacturers dependent on virgin feedstock. Street vendors and informal foodservice operators in emerging markets exhibit the highest price sensitivity, while multinational QSR chains prioritize specification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in China's Yangtze River Delta and India's Mumbai-Bangalore corridor are redirecting pulp molding automation investments toward Vietnam and Indonesia. Supply concentrates in China, Germany, and the United States, with bagasse feedstock dependency drawing from Brazilian and Indian agricultural waste streams. Single-source vulnerability runs through European EFSA assessment bottlenecks for novel biopolymers. Distribution runs through wholesale networks anchored by Dart Container Corporation and Pactiv Evergreen in North America, while online platforms gain share fastest in India's urban food delivery corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable tableware market functions as a regulatory compounder, with the EU Single-Use Plastics Directive mandating material substitution across member states and compressing demand for conventional polystyrene formats.
For Market Incumbents: Extend molded fiber capacity in Germany and the Netherlands to anchor QSR supply relationships before REACH compliance timelines harden. Backward integration into bagasse pulp supply secures feedstock against agricultural commodity swings. Certification investment in EFSA dossiers protects against novel biopolymer entrants with shorter assessment timelines. For New Entrants and Emerging Players: Street vendors and open-air markets in Brazil's Southeast industrial corridor represent the most penetrable buyer archetype, with ANVISA regulations applying less stringently than to institutional channels. Low-cost molded fiber plates and bowls targeting São Paulo and Rio de Janeiro bypass entrenched wholesale relationships. Direct-to-operator platforms bypass distributor margin layers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional molded fiber specialists with captive pulp supply but limited multi-material capabilities. Long-term viability hinges on regulatory divergence between compostability certification schemes and actual industrial composting infrastructure availability. Watch for deposit-return scheme expansions beyond Germany as the signal indicating reusable container pooling viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive bagasse feedstock from Brazilian agricultural waste secures margin against commodity volatility. |
| EFSA Certification Investment | Novel food dossiers for biopolymers gatekeep European QSR procurement relationships from faster competitors. |
| Wholesale Channel Expansion | Dart Container's distributor relationships demonstrate defensive moats in North American foam-based distribution. |
| Aqueous Barrier Coating R&D | Convergence with high-speed paper cup forming lines enables grease resistance without polyethylene lamination. |
| Direct-to-Operator Platform Launch | Swiggy and Zomato's procurement integration in India shows online channel aggregation potential. |
Methodological Framework
Bottom-up foodservice procurement modeling reconciled against top-down resin-to-product manufacturing tracking forms the analytical core of this study. Primary interviews with QSR category managers, molded fiber plant engineers, EFSA regulatory consultants, and wholesale distribution heads combined with secondary validation from EU Single-Use Plastics Directive implementation reports, FDA migration testing protocols, FSSAI compliance frameworks, and customs trade data on pulp molding equipment imports. Triangulation across these sources isolates volume and value estimates from reporting bias.
Historical trendline analysis of material substitution patterns across European member states anchors the projection framework. Segmentation modeling covers product type, material grade tier, application channel, and regional regulatory cluster throughout the forecast period. CAGRs derive from regression against QSR unit volume growth, resin price indices, and composting infrastructure penetration curves. Forecast inputs include Swiggy and Zomato delivery expansion timelines and EFSA assessment queue lengths for novel biopolymers.
Underlying measurement precision varies by segment; REACH-regulated European supply chains carry tighter precision than informal foodservice channels in Brazil. Forecasts reflect assumptions on regulatory enforcement consistency and composting infrastructure buildout rates. Material deviation in EFSA assessment timelines or crude oil benchmark volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Latin America Canned Food Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Fast Food Containers Market
Food Packaging
Burger Boxes Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Europe Chocolate Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Food Green Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Frozen Seafood Packaging Market