
 Silicone Release Films Market | 2026-2036
Silicone Release Films Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Release Films Market Analytics
Medical Devices is restructuring the demand profile for silicone release films as wound care and transdermal patch volumes climb. 3M Company leverages its vertical integration across adhesive and release liner production to capture value at multiple stages. Wacker Chemie AG anchors European supply through specialized silicone emulsion technology. Mondi plc competes with broad extrusion and coating capabilities across multiple substrate formats.
Silicone release films are thin polymer substrates coated with cross-linked polydimethylsiloxane layers that enable clean separation from aggressive adhesives without residue transfer or surface damage. Coating weights typically range from 0.5 to 2.0 grams per square meter depending on adhesive aggressiveness and peel force requirements. Single-Sided films dominate current volume as labels and tapes represent the largest installed base of converting equipment. Double-Sided configurations capture expanding margin pools in medical device lamination where precise adhesive alignment and biocompatibility certification command premium positioning. Thickness segmentation shows 50-100 Microns films leading in flexible packaging conversions while Above 200 Microns grades serve structural automotive damping applications with heavier release requirements.
REACH restrictions on volatile organic compound emissions from solvent-based coating processes are accelerating waterborne and UV-cured silicone system adoption across European converting operations. FDA biocompatibility testing protocols for skin-contact medical devices directly influence release film substrate selection and extractables documentation burdens. ISO 10993 standards provide the harmonized testing framework that multinational device manufacturers reference when qualifying second-source liner suppliers. Stakeholders must monitor evolving EU F-Gas Regulation implications for fluorosilicone alternatives and assess captive coating investments versus merchant supply as regional regulatory fragmentation deepens.
Market Dynamics
Medical device sterilization protocols and REACH solvent restrictions are compressing silicone release film formulation cycles, forcing converters to requalify coating chemistries and substrate purity standards simultaneously.
Growth Catalysts
- Wound Care Expansion:Chronic disease prevalence and aging populations in Germany and the United States are expanding sterile adhesive patch volumes. Device manufacturers require certified release liners for transdermal drug delivery systems.
- REACH VOC Limits:ECHA solvent emission caps are accelerating waterborne silicone coating line conversions across European converting operations. Facilities in Germany and France are retrofitting curing ovens to meet compliance deadlines.
- Fluorosilicone Substitution:EU F-Gas Regulation phase-down schedules are displacing fluorinated release agents in high-temperature automotive applications. Silicone alternatives are capturing specification wins in German automotive damping programs.
Market Restraints
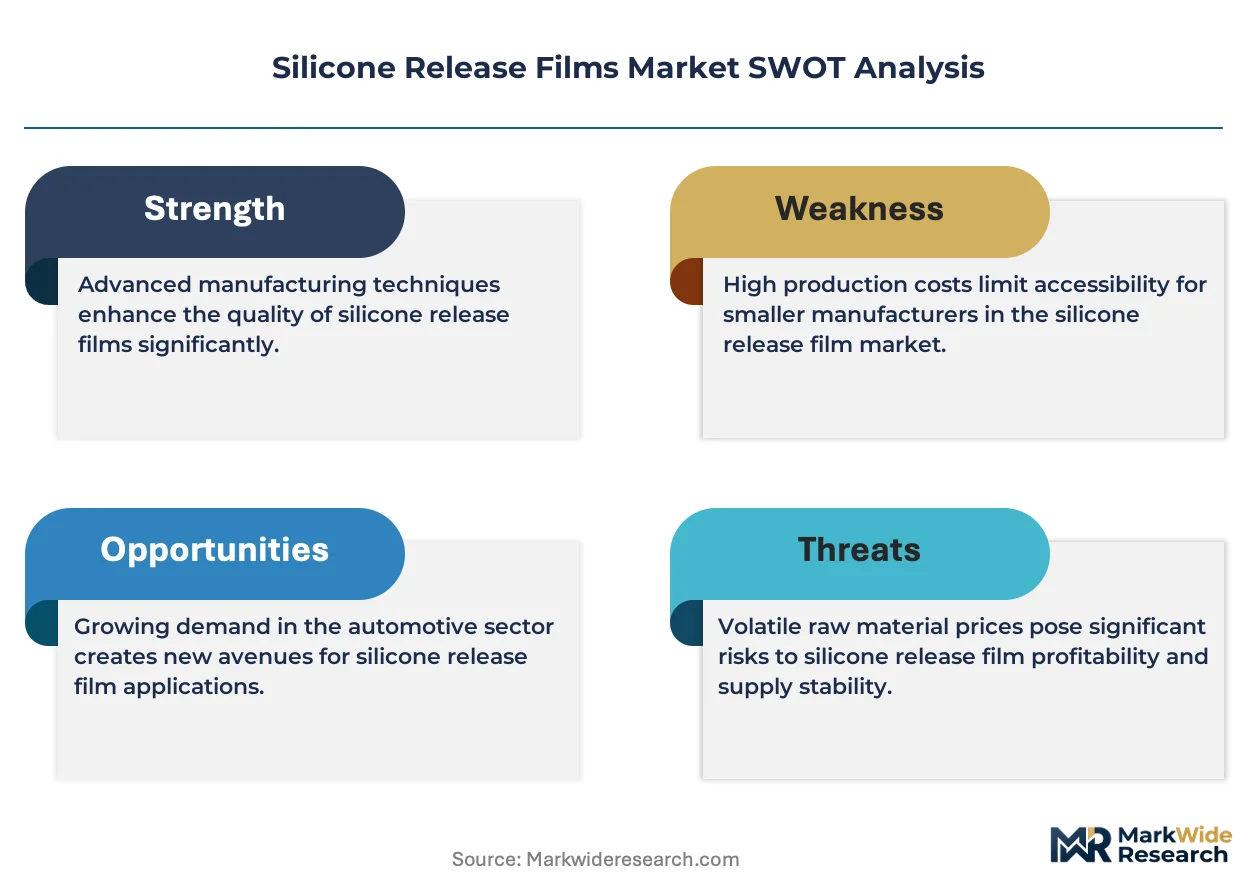
- Petrochemical Feedstock Volatility:Polydimethylsiloxane precursor costs track methanol and silicon metal commodity swings. Coating operations face margin compression when input spikes coincide with fixed-price medical supply contracts.
- Coating Capacity Concentration:Merchant silicone coating capacity clusters in southern Germany, northern Italy, and coastal China. Buyers in North America face extended lead times and freight exposure when qualifying second-source suppliers.
- Extractables Documentation Burden:FDA biocompatibility testing protocols for ISO 10993 compliance require extensive substrate and coating characterization. Small converters lack analytical chemistry resources to support medical device dossier submissions.
Strategic Opportunities
- India Medical Device Manufacturing:CDSCO regulatory harmonization with ISO 13485 standards is attracting multinational device assembly to Gujarat and Karnataka. Local release liner supply remains underdeveloped.
- UV-Cured Silicone Convergence:Electron beam and ultraviolet curing technologies are merging with precision coating head designs to eliminate thermal damage on heat-sensitive polymer substrates.
- Biodegradable Substrate Development:Polylactic acid and cellulose-based carrier films are emerging as compostable alternatives to polyester and polypropylene in European sustainable packaging mandates.
Industry Challenges
- Cross-Functional Talent Scarcity:Coating engineers with simultaneous expertise in silicone polymerization, web handling, and medical regulatory affairs command premium compensation. Training pipelines at technical universities in Germany and the United States remain insufficient.
- Legacy Equipment Retrofit Costs:Solvent-based coating lines require capital-intensive ventilation and abatement upgrades to meet tightening EPA and ECHA emission thresholds. Mid-tier converters defer investments, ceding share to integrated producers with captive coating assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Release Films Market |
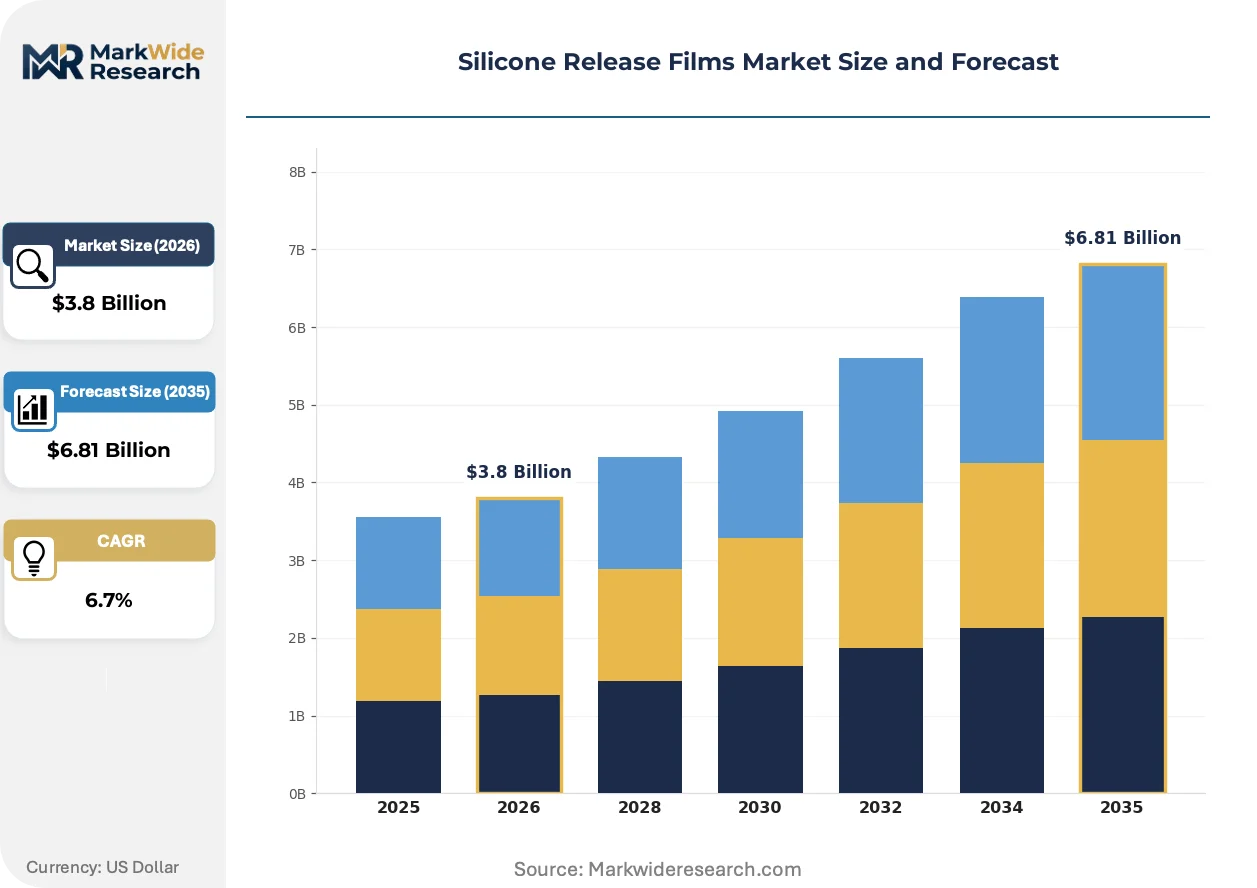
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Sided, Double-Sided, Laminated, Perforated End Use: Medical Devices, Food Packaging, Adhesives, Automotive Components Thickness: Below 50 Microns, 50-100 Microns, 100-200 Microns, Above 200 Microns Coating Type: Silicone Coated, Non-Silicone Coated, Release Agent, Others |
| Companies Covered | 3M Company, Wacker Chemie AG, Mondi plc, Loparex LLC, Avery Dennison Corporation, Elkem Silicones, Mitsubishi Polyester Film, UPM Raflatac, Lintec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Release Films Market Evolving Landscape
Silicone release film technology is pivoting toward solvent-free coating architectures and precision thickness control systems that enable thinner, higher-performance medical laminates.
UV-curable silicone systems are integrating into high-speed coating operations through dual-cure formulations that combine cationic and free-radical polymerization mechanisms. Medical device manufacturers in Germany and the United States are adopting these systems to eliminate thermal oxidation risks on temperature-sensitive drug layers. This chemistry is integrating quality control loops that monitor cure conversion in real time, compressing batch release timelines from days to hours.
ECHA REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other process solvents are mandating aqueous emulsion and solventless coating transitions across European converting facilities. Coating weight uniformity requirements for medical-grade films have tightened to plus-or-minus five percent tolerances. German automotive and medical clusters are responding by consolidating supplier qualifications around vertically integrated producers with in-house emulsion polymerization capabilities.
Device manufacturers are consolidating release liner procurement under single-source framework agreements that bundle substrate, coating, and certification services. Large medical OEMs in the United States are displacing spot-buying patterns with multi-year supply contracts that lock in extractables documentation and second-source qualification timelines. This concentration is most visible in transdermal patch and advanced wound care segments where FDA 510(k) submission risks amplify supplier switching costs.
Silicone Release Films Market Segmentation
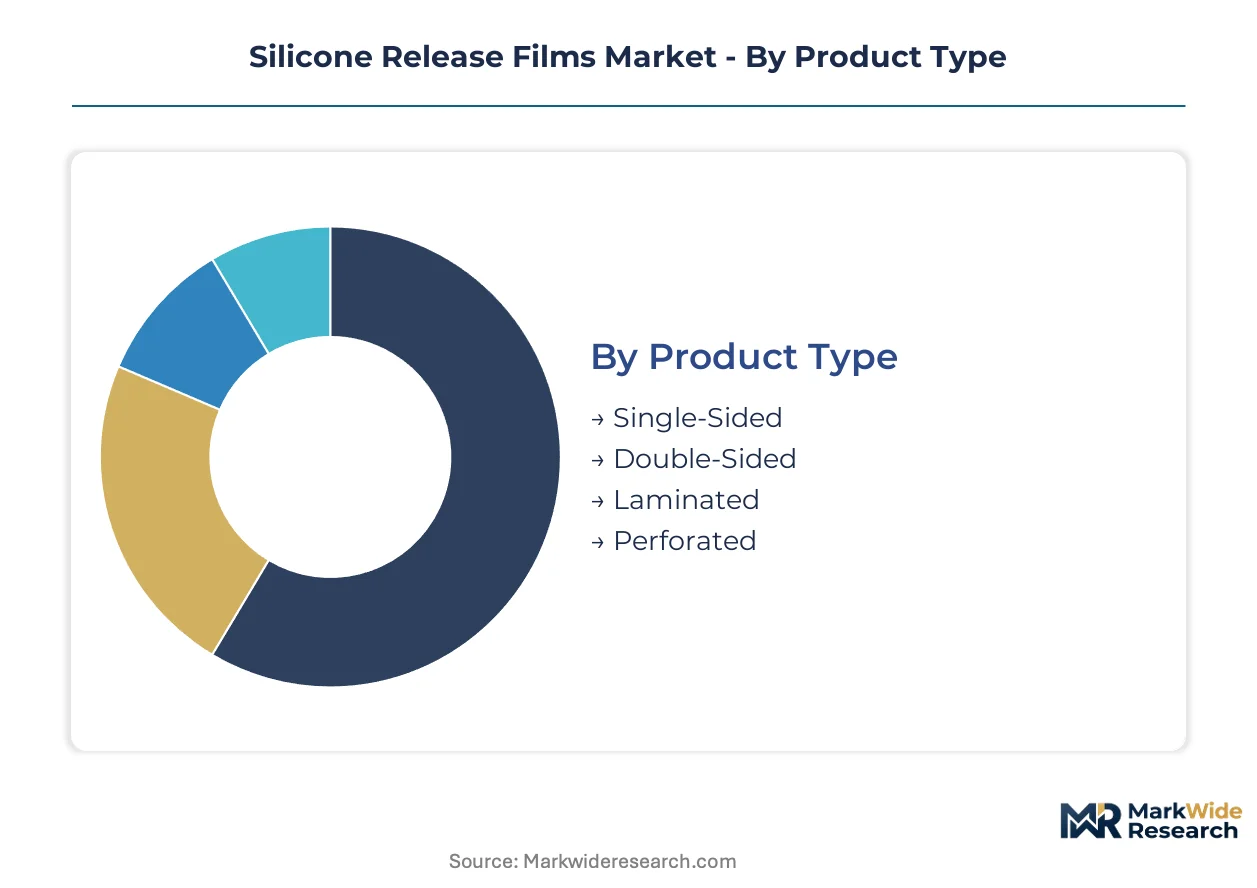
Silicone release film specifications vary sharply by integration depth—standalone liners for labels operate on different performance thresholds than multi-layer medical laminates where release films embed as functional substrates. Converters must match coating chemistry, thickness tolerance, and substrate purity to specific end-use sterilization and adhesion requirements.
Product Type:
Standalone release liners dominate high-volume converting, while embedded configurations capture premium positioning in precision lamination stacks.
- Single-Sided:One active release surface supports label stock and tape converting where adhesive contacts only one substrate face. Demand concentrates in German and United States label converting clusters serving e-commerce logistics packaging volumes.
- Double-Sided:Dual release surfaces enable precise adhesive layer alignment in medical device lamination where biocompatibility certification and extractables documentation command supplier consolidation. Transdermal patch manufacturers in the United States specify these configurations for multi-layer drug delivery stacks.
- Laminated:Pre-bonded multi-layer constructions reduce downstream converting steps for food packaging barrier applications.
- Perforated:Controlled pore patterns support breathable medical dressings and selective adhesive exposure.
Single-Sided films lead volumes today; Double-Sided configurations are gaining share fastest in medical device procurement consolidation.
End Use:
Application maturity separates established industrial demand from regulated medical segments with stringent qualification barriers.
- Medical Devices:Sterile adhesive patches, transdermal drug delivery systems, and advanced wound care dressings require ISO 10993-compliant release liners with documented substrate and coating extractables. FDA biocompatibility protocols and REACH purity standards are compressing supplier qualification timelines in Germany and the United States.
- Adhesives:Pressure-sensitive tape and label stock converting represents the largest installed equipment base, with coating weight tolerances of plus-or-minus five percent standard for high-speed slitting operations.
- Food Packaging:Migration-tested silicone coatings comply with EFSA and FDA food contact regulations for lidding and tray sealing applications.
- Automotive Components:Structural damping pads and interior trim adhesives specify heavier release coatings for aggressive rubber-based adhesives in German OEM supply chains.
Adhesives maintains the broadest volume base; Medical Devices shows the steepest expansion trajectory as chronic disease prevalence climbs.
Thickness:
Thickness selection maps directly to structural load requirements and converting equipment gauge limits across flexible versus rigid applications.
- 50-100 Microns:Mid-range gauges balance handling durability with conformability for flexible packaging conversions and standard label stock. European sustainable packaging mandates are testing polylactic acid substrate alternatives in this thickness band.
- Above 200 Microns:Heavy-gauge films provide dimensional stability for structural automotive damping applications where aggressive adhesive release forces require robust carrier substrates. German automotive clusters specify these grades for NVH (noise, vibration, harshness) component manufacturing.
- Below 50 Microns:Ultra-thin films minimize material usage for cost-sensitive disposable applications.
- 100-200 Microns:Intermediate gauges serve industrial tape and specialty medical dressing applications requiring puncture resistance.
50-100 Microns dominates current converting volumes; Above 200 Microns is expanding most quickly in automotive lightweighting programs.
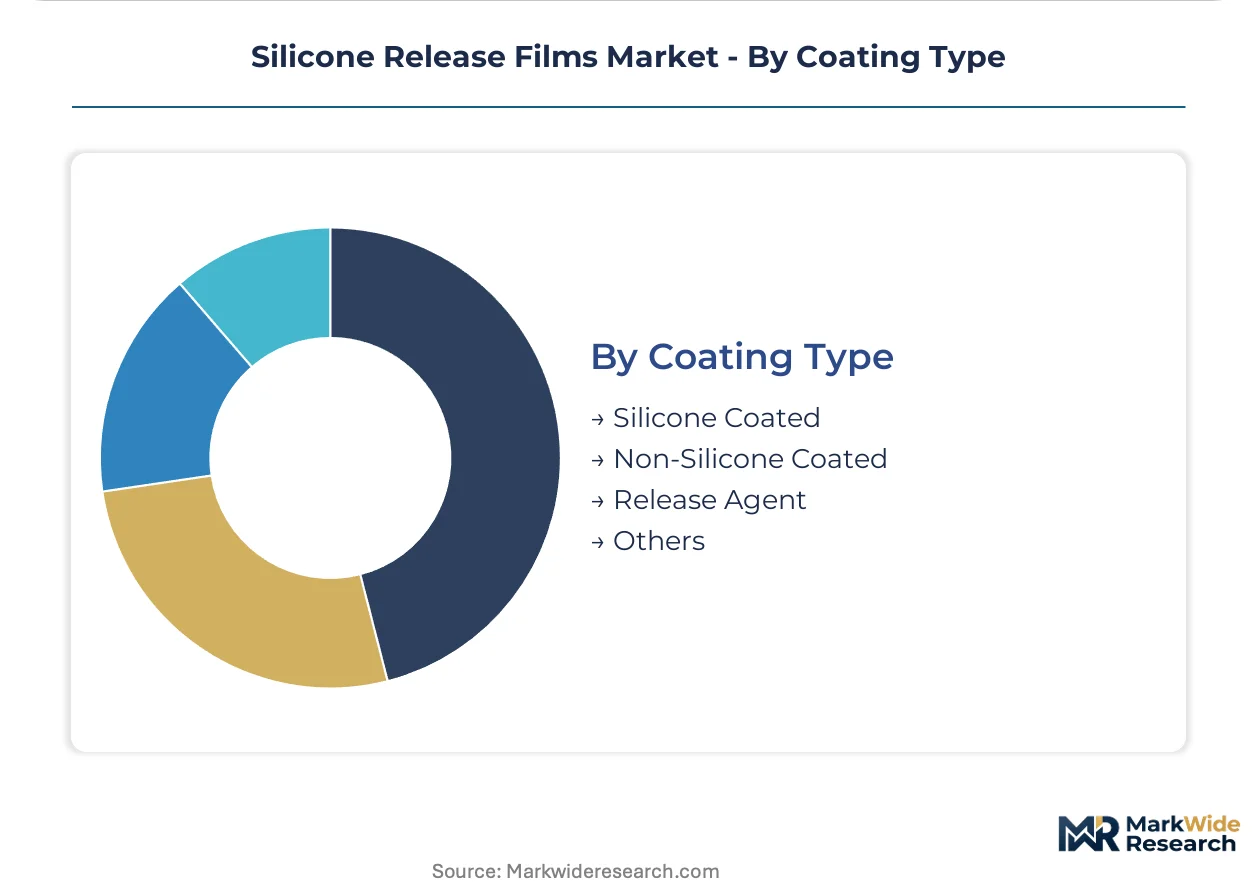
Coating Type:
Coating chemistry determines release force profiles and regulatory compliance pathways, with solvent-free systems displacing legacy architectures.
- Silicone Coated:Cross-linked polydimethylsiloxane layers deliver clean release from aggressive acrylic and rubber adhesives without residue transfer. REACH VOC emission caps are accelerating waterborne and UV-cured silicone adoption across German and French converting facilities retrofitting curing ovens.
- Non-Silicone Coated:Fluoropolymer and polyolefin alternatives serve specialized electronics and optical applications where silicone contamination risks device performance.
- Release Agent:Low-surface-energy topical treatments provide temporary release for short-cycle molding and casting processes.
- Others:Hybrid and experimental coating chemologies address niche temperature or chemical resistance requirements.
Silicone Coated retains the dominant specification share; Non-Silicone Coated alternatives are climbing fastest in electronics manufacturing contamination-sensitive segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting silicone release film production toward jurisdictions with lower compliance costs for solvent-based coating operations. REACH VOC limits in Europe are accelerating capacity migration to Asia-Pacific and North American facilities with grandfathered emission allowances.
United States
FDA biocompatibility protocols for ISO 10993 compliance are compressing supplier qualification timelines for transdermal patch manufacturers. EPA emission thresholds for solvent-based coating lines remain less stringent than ECHA caps, preserving cost advantages for domestic converters. Medical device clusters in Minnesota and Massachusetts are consolidating procurement under multi-year framework agreements with captive coating assets.
Germany
ECHA REACH Annex XVII restrictions on N-methyl-2-pyrrolidone are mandating aqueous emulsion transitions across Bavarian and Baden-Württemberg converting facilities. The EU F-Gas Regulation phase-down is displacing fluorinated release agents in automotive damping applications. Industrial clusters around Stuttgart and Munich are retrofitting curing ovens to meet compliance deadlines, raising capital barriers for mid-tier operators.
China
Dual carbon goals under MEE oversight are tightening emission controls on solvent-based silicone coating operations in the Yangtze River Delta. NMPA medical device registration harmonization with ISO 13485 is attracting multinational assembly to Jiangsu and Zhejiang provinces. Local release liner supply remains underdeveloped relative to converting demand from electronics and packaging sectors.
India
CDSCO regulatory alignment with ISO 13485 standards is drawing multinational device manufacturing to Gujarat and Karnataka. BIS certification requirements for food-contact silicone coatings are creating specification gaps versus European EFSA benchmarks. Industrial corridors around Ahmedabad and Bengaluru lack merchant coating capacity, forcing converters to rely on imported liners.
Japan
METI industrial standards for electronics-grade release films are maintaining specification premiums for domestic manufacturers. PMDA pharmaceutical packaging regulations require extractables documentation that favors vertically integrated suppliers with in-house analytical capabilities. Precision coating operations in the Kansai and Chubu regions serve contamination-sensitive optical and semiconductor applications.
Silicone Release Films Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical device procurement favoring integrated suppliers while label converting tolerates merchant sourcing. The vendor base concentrates around three strategic archetypes: chemical majors with captive silicone emulsion capabilities, diversified packaging conglomerates with extrusion assets, and specialized release liner pure-plays with regulatory dossier expertise. Dominant competitive moves include backward integration into substrate polymerization and geographic expansion through qualified second-source partnerships.
Among chemistry-anchored players, Wacker Chemie AG and Elkem Silicones exemplify the integrated model combining silicone polymerization with coating operations. 3M Company occupies a distinct position spanning adhesive formulation, release liner production, and end-use device manufacturing. These three represent contrasting approaches to value capture across the silicone release film stack.
| Leading Market Players |
|---|
| 3M Company |
| Wacker Chemie AG |
| Mondi plc |
| Loparex LLC |
| Avery Dennison Corporation |
| Elkem Silicones |
| Mitsubishi Polyester Film |
| UPM Raflatac |
| Lintec Corporation |
| Others |
Value Network & Pricing Analysis
Polydimethylsiloxane precursor costs flow from methanol and silicon metal commodity markets through coating operations into tiered pricing structures that separate medical-grade certified liners from industrial label stock. ECHA REACH solvent restrictions in Germany and France compress margins on legacy coating lines while waterborne system investments command premium positioning in transdermal patch supply chains.
Pricing Analysis
Direct-to-OEM framework agreements capture volume discounts that distributor markups cannot match in medical device procurement. Pricing stratifies across premium, standard, and economy tiers where ISO 10993 certification and extractables documentation separate medical-grade premiums from industrial label stock. Cost compression in mid-tier converting intensifies because REACH retrofit investments coincide with fixed-price medical contracts. Small converters in spot-buying label segments exhibit highest price sensitivity; large medical OEMs with captive coating assets show lowest.
Supply Chain Analysis
Release liner returns and substrate waste streams flow back to specialized recyclers in Germany and China for reprocessing into lower-grade industrial applications. Merchant coating capacity clusters in southern Germany, northern Italy, and coastal China, drawing from polydimethylsiloxane precursors, polyester substrates, and silicone emulsion chemistries. Single-source vulnerability concentrates in German automotive damping programs where fluorosilicone phase-downs strain qualified supplier pools. Distribution runs through converting houses that laminate, slit, and sterilize for end-use device manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone release films constitute a late-cycle quality story as chronic disease prevalence and aging demographics in Germany and the United States shift procurement toward premium medical-grade specifications with biocompatibility certification.
For Market Incumbents: Extend coating chemistry portfolios into UV-cured and waterborne systems to capture REACH-compliant specification wins in European medical device clusters. Consolidate supplier qualifications around captive emulsion polymerization capabilities before mid-tier competitors complete solvent-line retrofits. Fluorosilicone substitution in German automotive damping creates incremental volume pools for silicone alternatives with thermal stability credentials. For New Entrants and Emerging Players: Medical device contract manufacturers in Gujarat and Karnataka present underdeveloped local supply gaps as CDSCO regulatory harmonization accelerates multinational assembly migration. Target sterile adhesive patch converters with toll-coating partnerships that bundle ISO 10993 documentation and second-source qualification support. Electronics-grade precision coating for optical and semiconductor applications in Japan offers contamination-sensitive entry points with specification premiums. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier European converters with stranded solvent assets because ECHA emission caps force distressed exits and consolidate share toward integrated producers. Five-to-ten year viability hinges on coating chemistry transition completion and medical certification dossier depth. Monitor EU F-Gas Regulation phase-down velocity and NMPA harmonization progress in Jiangsu province for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Coating Line Conversion | REACH Annex XVII compliance in Germany and France preserves market access for medical device supply chains. |
| Backward Integration into Silicone Emulsion | In-house polymerization capabilities secure supply continuity against methanol and silicon metal commodity volatility. |
| Medical Certification Dossier Investment | ISO 10993 extractables documentation commands premium positioning in transdermal patch procurement consolidation. |
| Second-Source Qualification Partnership | Framework agreements with large US medical OEMs lock in multi-year volume commitments and reduce spot-buying exposure. |
| UV-Cured System Technology Licensing | Dual-cure formulations eliminate thermal oxidation risks for temperature-sensitive drug layers in German device manufacturing. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating engineers, medical device procurement managers, regulatory affairs specialists at notified bodies, and converting plant operators with secondary validation against ECHA REACH guidance documents, FDA 510(k) submission databases, ISO 10993 testing protocols, and customs trade flow records. Bottom-up capacity assessments at merchant coating facilities triangulated against top-down demand modeling from end-use segment consumption patterns.
Historical reference periods anchored volume and value trajectories across the analysis window, with growth rates derived from segmented modeling across product type, end-use application, thickness specification, coating chemistry, and regional production hub dimensions. CAGRs reflect convergence of equipment utilization rates, regulatory compliance cost pass-through assumptions, and medical device sterilization protocol adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation enforcement timing, CDSCO harmonization completion in India, and petrochemical feedstock volatility. Practitioners should monitor REACH solvent emission compliance deadlines, NMPA medical device registration acceleration in Zhejiang, and fluorosilicone displacement rates in German automotive programs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polyethylene Terephthalate (PET) Shrink Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Global BOPP Films Market
Poly film
Italy Plastic Packaging Films Market
Poly film
Spain Plastic Packaging Films Market
Poly film
Laminated Packaging Films Market
Poly film
Printed Plastic Films Market
Poly film
Polyester Film Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Polymer Dispersed Liquid Crystal (PDLC) Film Market
Poly film
India Plastic Packaging Film Market
Poly film
Bopet Films Market
Poly film
Indonesia Plastic Packaging Films Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Resealable Films Market
Poly film
Thermoforming Films Market