
 Edible Oil Packaging Market | 2026-2036
Edible Oil Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Oil Packaging Market Foresight
The gap between premium and commodity edible oil packaging is broadening as oxygen-barrier multilayer bottles and single-use sachets diverge in material cost, shelf-life performance, and brand communication value. Amcor PLC leverages its global flexible film footprint to supply high-barrier pouches for emerging-market brands. Berry Global Group anchors North American blow-molded bottle capacity for mid-tier household formats. Tetra Laval competes through aseptic carton systems that extend liquid-oil shelf stability without refrigeration.
Edible oil packaging encompasses primary containers and secondary wraps engineered to exclude oxygen, moisture, and light while enabling controlled pouring and retail display. Specifications include ethylene vinyl alcohol copolymer barrier layers at six to fifteen microns, blow-molded or thermoformed fabrication, and closure systems with induction-sealed liners to prevent rancidity. Plastic bottles dominate volume across the one-liter and two-liter household tiers, where polyethylene terephthalate and high-density polyethylene balance clarity with drop resistance. Pouches represent the fastest-growing format, driven by material-lightweighting goals and foodservice portion-pack demand, though margin pools remain thinner than in glass or metal alternatives for gourmet and gift segments.
FDA food-contact substance notifications govern barrier additive approvals in the United States, while EFSA and REACH frame migration limits and substance restrictions across Europe. India's FSSAI packaging regulations and BIS standards for food-grade plastics reshape what converters can supply to domestic edible oil brands. Stakeholders must monitor how extended producer responsibility mandates and bio-based content thresholds redefine material specifications and supplier qualification criteria.
Market Dynamics
Converters face mounting pressure from the EU F-Gas Regulation and REACH compliance deadlines, which mandate phase-down of high-global-warming-potential barrier films and full substance disclosure across polymer supply chains.
Growth Catalysts
- Urban branded-oil transition:India's metropolitan clusters are shifting from loose-oil distribution to pre-packaged formats, creating demand for one-liter PET bottles and laminated pouches with twelve-month shelf stability.
- EVOH barrier layer advances:Six-micron ethylene vinyl alcohol copolymer films now deliver oxygen transmission rates below 0.5 cc/m²/day, enabling converters to downgauge multilayer structures without rancidity risk.
- Foodservice portion-pack surge:Quick-service restaurants and institutional caterers across Southeast Asia are adopting single-serve sachets and bulk dispensing systems for frying and salad applications.
Market Restraints
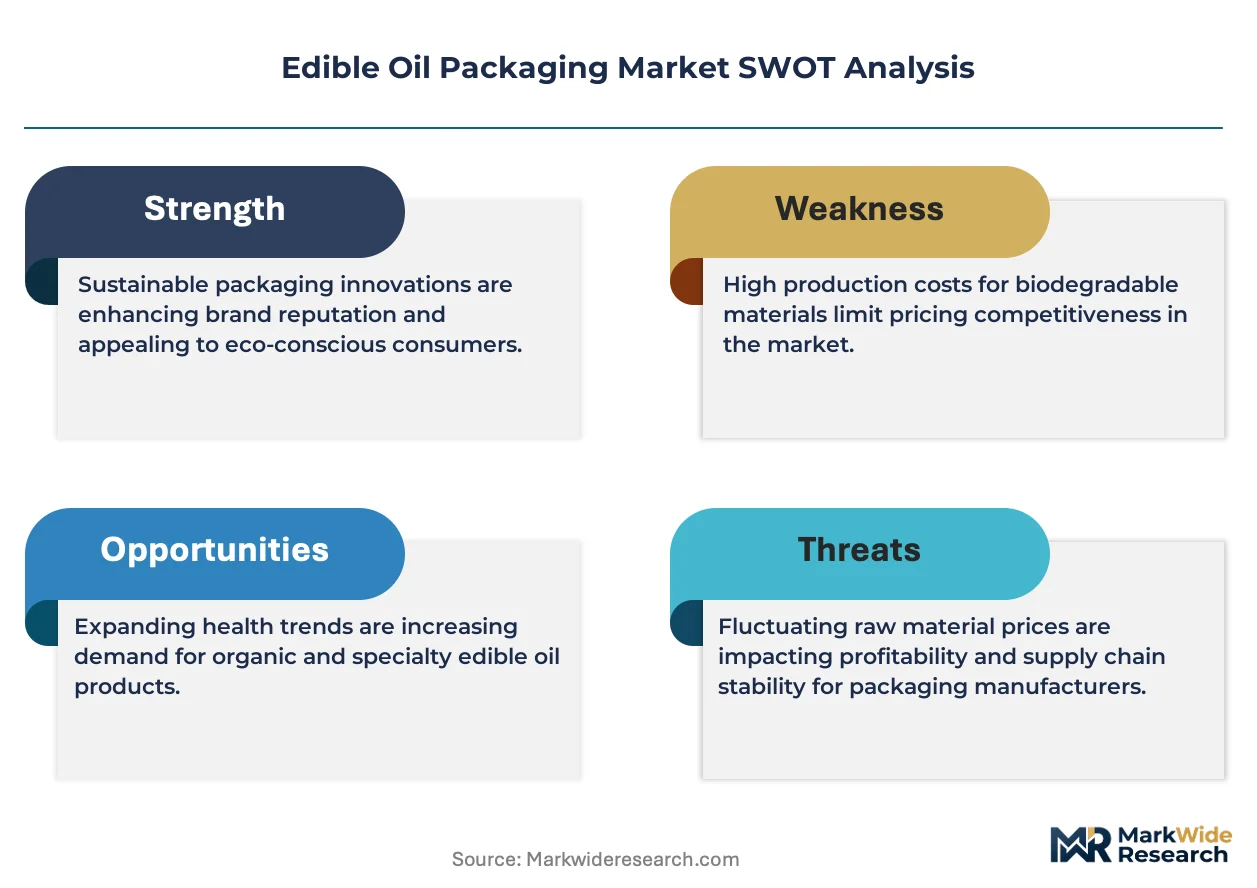
- Polyolefin resin volatility:High-density polyethylene and polypropylene feedstock costs swing with naphtha-cracker margins, compressing converter margins on fixed-price annual contracts with oil brands.
- Barrier additive approval timelines:FDA food-contact substance notifications and EFSA migration assessments stretch eighteen to thirty-six months, delaying commercialization of novel oxygen scavengers and bio-based barrier layers.
- Glass and metal substitution in premium segments:Gourmet olive oil and cold-pressed mustard oil brands retain tinplate cans and amber glass for shelf presence, limiting plastic penetration in high-margin gift formats.
Strategic Opportunities
- Bio-based film regulatory tailwinds:The EU Green Deal and extended producer responsibility mandates in Germany and France are creating preferential procurement channels for packaging with thirty-percent or higher renewable content.
- Aseptic carton expansion:Tetra Laval's aseptic systems are penetrating ambient liquid-oil segments in Brazil and Saudi Arabia, displacing rigid plastics where cold-chain infrastructure remains underdeveloped.
- Induction-seal liner technology convergence:Combination of foil-based liners with tamper-evident banding is unifying child-resistance and leak-prevention functions for export-oriented brands shipping to humid climates.
Industry Challenges
- Multilayer film recycling infrastructure gaps:Current mechanical sorting systems cannot separate EVOH from PE tie layers, forcing converters to fund chemical recycling pilot programs or face landfill surcharges under France's AGEC law.
- Migration testing capacity bottlenecks:Accredited laboratories for overall migration and specific migration limit testing face six-month backlogs, delaying product launches for Indian exporters seeking EU market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Oil Packaging Market |
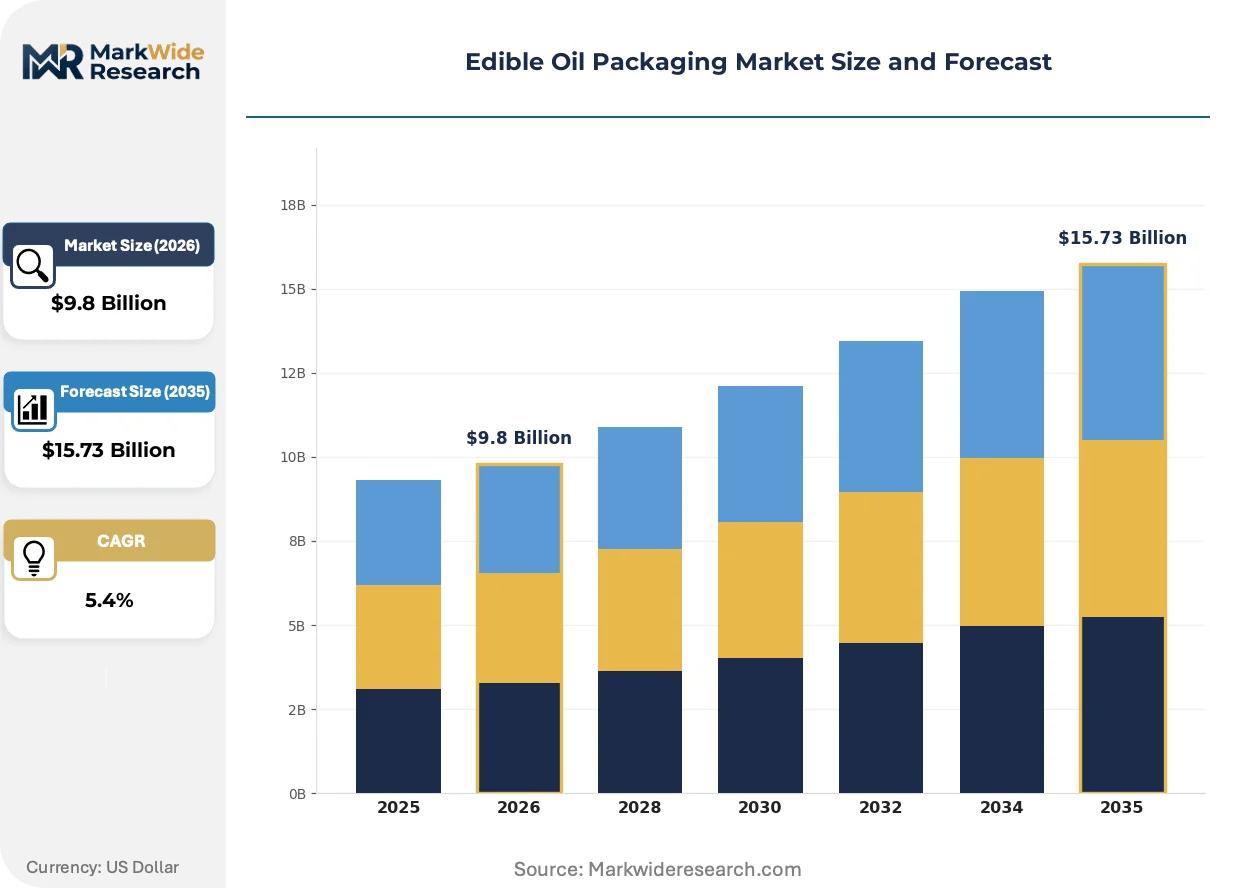
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Cans, Jars Material: Plastic, Glass, Metal, Paper End User: Food Industry, Retailers, Households, Foodservice Size: 500ml, 1L, 2L, 5L |
| Companies Covered | Amcor PLC, Berry Global Group, Tetra Laval, DS Smith, Sealed Air, Smurfit Kappa Group, Tetra Pak, Sonoco, Scholle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Oil Packaging Market Shifts & Advancements
Active barrier technologies and circular material flows are restructuring how edible oil brands specify packaging, with shelf-life extension and end-of-life compliance now co-equal design criteria.
Coextruded five-layer films incorporating nylon-6 and EVOH are unifying oxygen barrier and puncture resistance in stand-up pouches for two-liter household formats. Mid-tier brands in Indonesia and Vietnam are adopting these structures to replace rigid bottles in e-commerce channels. The technology is compressing freight costs by forty percent versus blow-molded alternatives while maintaining eighteen-month shelf stability.
REACH substance restrictions on per- and polyfluoroalkyl substances are compelling European converters to eliminate fluorinated barrier coatings from oil-contact layers by 2025. The regulation is accelerating migration to silicon oxide and aluminum oxide physical vapor deposition coatings. Premium olive oil bottlers in Spain and Italy are qualifying these ceramic barriers for their organic product lines to maintain export eligibility.
Foodservice procurement teams are consolidating supplier bases and demanding integrated dispensing equipment with bulk oil deliveries. Institutional buyers in Saudi Arabia and the UAE are replacing twenty-liter metal tins with bag-in-box systems featuring Scholle IPN-style fitments. This shift concentrates volume with packaging vendors capable of co-designing liquid handling hardware.
Edible Oil Packaging Market Segmentation
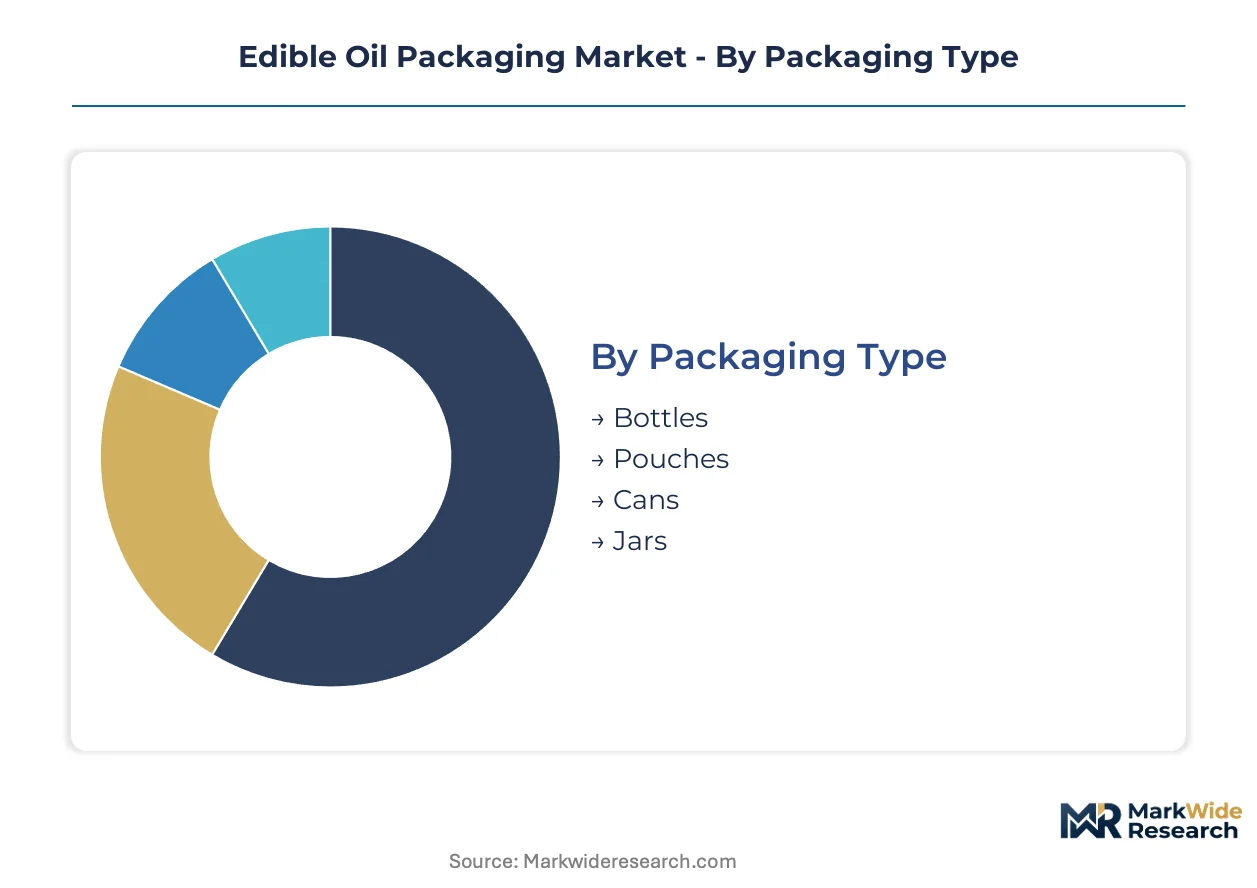
Edible oil packaging specifications diverge sharply across consumption contexts, with barrier requirements, handling durability, and portion control driving format selection. Material choices and size configurations further stratify based on cold-chain availability, retail density, and household purchasing power.
Packaging Type:
Buyers prioritize either shelf visibility and controlled pouring or material lightweighting and logistics efficiency.
- Bottles:Blow-molded PET and HDPE structures with induction-sealed liners dominate one-liter and two-liter household tiers. India's urban branded-oil transition concentrates demand in Delhi-Mumbai corridors where retail cold-chain infrastructure remains patchy.
- Pouches:Coextruded multilayer films incorporating EVOH barrier layers at six to fifteen microns enable downgauging without rancidity risk. Foodservice procurement across Southeast Asia and institutional buyers in Saudi Arabia favor stand-up formats for bulk dispensing compatibility.
- Cans:Tinplate and aluminum containers retain preference for premium olive oil and cold-pressed mustard oil gift segments where shelf presence commands margin premiums.
- Jars:Glass and PET wide-mouth formats serve gourmet and organic lines requiring resealability and label adhesion for retail differentiation.
Volume sits with bottles; growth tilts toward pouches.
Material:
Cost tiers separate commodity polyolefin solutions from barrier-enhanced and sustainable alternatives.
- Plastic:PET clarity and HDPE drop resistance balance performance across household formats. EVOH copolymer integration at sub-fifteen-micron gauges now delivers oxygen transmission rates below 0.5 cc/m²/day.
- Glass:Amber and flint varieties exclude light and oxygen for premium cold-pressed oils. Italian and Spanish organic bottlers qualify ceramic-coated barriers to maintain EU export eligibility under REACH substance restrictions.
- Metal:Tinplate cans and aluminum aerosol-style containers preserve flavor stability for extended-shelf-life exports to humid climates.
- Paper:Aseptic carton systems from Tetra Laval penetrate ambient liquid-oil segments in Brazil where refrigeration infrastructure remains underdeveloped.
Plastic captures volume leadership; paper-based alternatives gain fastest.
End User:
Application scale determines whether packaging emphasizes portion precision or bulk logistics.
- Food Industry:Processors specify high-barrier drums and intermediate bulk containers for ingredient-scale oil handling. BIS standards and FSSAI packaging regulations govern Indian domestic supply.
- Retailers:Supermarket chains demand twelve-month shelf stability with tamper-evident banding and induction-seal liner convergence for leak prevention.
- Households:Urban Indian clusters shift from loose-oil distribution to pre-packaged one-liter PET bottles with controlled-pour closures.
- Foodservice:Quick-service restaurants across Southeast Asia adopt single-serve sachets; institutional buyers in UAE replace twenty-liter metal tins with bag-in-box systems featuring Scholle IPN-style fitments.
Household consumption anchors volume; foodservice applications expand most quickly.
Size:
Purchasing frequency and storage constraints shape volume preferences across geographies.
- 500ml:Compact formats serve trial-size marketing and single-person households in dense urban clusters. E-commerce channels in Indonesia and Vietnam favor these for last-mile efficiency.
- 1L:The standard household tier balances consumption velocity with handling convenience. India's metropolitan transition concentrates demand here.
- 2L:Family-size configurations with ergonomic grips and flow-control spouts target weekly-purchase patterns in suburban markets.
- 5L:Bulk formats for institutional catering and price-sensitive rural households; BIS food-grade plastic standards apply to Indian domestic supply.
One-liter formats dominate volume; five-liter containers gain share fastest in foodservice consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's industrial corridor anchors branded edible oil packaging demand as India's urban transition accelerates. Delhi-NCR and Bangalore follow with concentrated foodservice procurement. São Paulo and Jeddah emerge as secondary growth poles for aseptic carton penetration.
India
Urban clusters in Maharashtra and Gujarat shift from loose-oil distribution to pre-packaged PET bottles and laminated pouches. FSSAI packaging regulations and BIS food-grade plastic standards reshape converter qualification requirements. The Delhi-Mumbai industrial corridor concentrates blow-molded bottle capacity for one-liter household formats.
Brazil
Aseptic carton systems penetrate ambient liquid-oil segments where refrigeration infrastructure remains patchy. ANVISA food-contact substance notifications govern barrier additive approvals for domestic brands. São Paulo's packaging converters supply multilayer structures to national oil processors expanding northeast distribution.
Saudi Arabia
Institutional buyers in Riyadh and Jeddah replace metal tins with bag-in-box systems for bulk oil dispensing. SFDA packaging regulations align with Gulf standardization initiatives for food-grade plastics. The Eastern Province's logistics hubs facilitate export-oriented production for regional foodservice chains.
Germany
REACH substance restrictions and EU F-Gas Regulation deadlines push converters toward bio-based films and ceramic barrier coatings. The EU Green Deal's extended producer responsibility mandates create preferential procurement channels for renewable-content packaging. Bavarian converters qualify silicon oxide coatings for organic olive oil exports.
United States
FDA food-contact substance notifications govern oxygen scavenger and barrier additive approvals for multilayer bottles. EPA extended producer responsibility frameworks in California and New York reshape post-consumer recycling infrastructure requirements. Texas-based resin processors supply HDPE and polypropylene for mid-tier household formats.
Edible Oil Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology tiers and geographic coverage breadth. The vendor base stratifies into three archetypes: global flexible film specialists with integrated polymer supply, regional blow-molded bottle fabricators serving branded oil accounts, and aseptic carton system providers with liquid handling equipment integration. Consolidation pressures concentrate around M&A activity targeting EVOH barrier film capacity and chemical recycling infrastructure partnerships.
Within the global flexible film tier, Amcor PLC and Berry Global Group represent archetypal positions. Amcor occupies a position as a multinational flexible packaging supplier with broad geographic reach. Berry Global Group anchors North American blow-molded capacity for household-format bottles. Tetra Laval exemplifies the integrated system provider model combining aseptic cartons with dispensing equipment design.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Group |
| Tetra Laval |
| DS Smith |
| Sealed Air |
| Smurfit Kappa Group |
| Tetra Pak |
| Sonoco |
| Scholle |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates gate qualified supply access and premium-tier pricing eligibility for converters serving European edible oil brands. REACH compliance deadlines and bio-based content thresholds reshape supplier qualification criteria, concentrating pricing power with converters holding certified barrier film capacity and disclosed polymer supply chains.
Pricing Analysis
Shelf-life extension guarantees anchor value-based pricing for high-barrier multilayer structures, with oxygen transmission rate performance below 0.5 cc/m²/day commanding material premiums. Pricing stratifies across premium, standard, and economy tiers based on EVOH gauge thickness and induction-seal liner integration. Cost compression in commodity polyolefin bottles intensifies as naphtha-cracker margin volatility squeezes converter margins on fixed-price annual contracts. Foodservice buyers exhibit highest price sensitivity due to thin margin pools, while gourmet olive oil brands retain lowest sensitivity given gift-format shelf presence premiums.
Supply Chain Analysis
Freight cost differentials between rigid and flexible formats concentrate procurement shifts toward pouches for e-commerce channels in Indonesia and Vietnam. Raw material supply draws from Saudi Arabia and UAE for polyolefin resin feedstocks, India for EVOH barrier film integration, and Germany for ceramic coating qualification. Single-source vulnerability sits with EVOH copolymer supply concentrated among specialty chemical producers. Distribution runs through converter-direct relationships with national oil processors in India and Brazil, supplemented by foodservice equipment-integrated bag-in-box systems in Gulf markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where backward control over EVOH barrier film supply and chemical recycling infrastructure determines margin sustainability. Players are pursuing captive supply of high-barrier polymers to defend against resin volatility and regulatory disclosure mandates.
For Market Incumbents: Anchor blow-molded bottle capacity in India's Delhi-Mumbai corridor to capture urban branded-oil transition demand. Secure chemical recycling partnerships to address France's AGEC law landfill surcharges and multilayer film infrastructure gaps. Defend against aseptic carton displacement by qualifying induction-seal liner convergence for humid climate exports. For New Entrants and Emerging Players: Foodservice procurement teams consolidating supplier bases represent the most penetrable buyer archetype. Target bag-in-box system co-design opportunities with institutional buyers in Saudi Arabia and UAE replacing metal tins. Pursue integrated dispensing equipment partnerships as the go-to-market angle to bypass established converter relationships. For Investors and Strategic Acquirers: FDA food-contact substance notification approval for novel oxygen scavengers is the leading indicator that bio-based barrier layers are approaching commercial viability. Position acquisitions around EVOH film capacity and ceramic coating qualification capabilities over the medium-term horizon. Monitor migration testing laboratory backlogs as the signal for EU market access bottlenecks easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Barrier Film | Captive supply of six-micron oxygen barrier layers insulates converters from specialty resin volatility. |
| Chemical Recycling Infrastructure Partnership | France's AGEC law penalties for non-recyclable multilayer structures create compliance-driven investment urgency. |
| Aseptic Carton System Expansion | Tetra Laval's ambient liquid-oil penetration in Brazil displaces rigid plastics where cold-chain gaps persist. |
| Foodservice Equipment Co-Design | Scholle IPN-style fitment integration with bulk dispensing systems locks in institutional buyer volume commitments. |
| Ceramic Barrier Coating Qualification | Spain and Italy's organic olive oil exporters require REACH-compliant silicon oxide coatings for EU market retention. |
Research Methodology
Multi-period observation of EVOH gauge downgauging trends, foodservice format adoption rates, and regulatory disclosure timelines anchored the trend analysis, supplemented by interviews with packaging converters, edible oil brand procurement leads, foodservice equipment suppliers, and polymer resin distributors. Secondary validation drew from FDA food-contact substance notification databases, EFSA migration assessment records, FSSAI packaging regulation updates, BIS food-grade plastic standards, and EU F-Gas Regulation implementation reports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Segment-weighting approaches modeled packaging type, material composition, end-user application, and size tier as primary dimensions, with regional regulatory cluster and barrier technology tier as secondary stratifiers. CAGRs derived from fitted growth curves applied to base-year volume estimates, with cross-validation against historical penetration rates for comparable format transitions. Industry-specific forecast inputs included urban branded-oil transition velocity in Indian metropolitan clusters and aseptic carton displacement rates in ambient liquid-oil segments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction amendments, polyolefin resin feedstock volatility, and mechanical recycling infrastructure buildout pace. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Processed Meat Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Produce Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
Seafood Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Bamboo Plate Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
North America Canned Food Packaging Market