
 Aluminum Beverage Bags Market | 2026-2036
Aluminum Beverage Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Beverage Bags Market Outlook
The aluminum beverage bags category is recalibrating around a widening split between premium spirits pouches with embossed finishes and commodity juice bags competing on unit cost. Novelis leverages its rolled aluminum leadership to supply thin-gauge substrate for barrier layers. Ball Corporation competes through vertical control over can-to-pouch conversion equipment. Constantia Flexibles differentiates via heat-seal coating chemistry that extends shelf life for sensitive formulations.
Aluminum beverage bags are flexible-to-semi-rigid packages combining aluminum foil laminates with polyethylene or polypropylene sealant layers, manufactured through extrusion coating and multi-web lamination to block oxygen, light, and moisture for shelf-stable liquid containment. Stand-up pouches occupy the dominant position in spirits and energy drink applications where shelf visibility and dispensing convenience command margin premiums. Spouted pouches lead growth in children's juice segments where resealability drives repeat purchase; flat bags remain the mature, cost-driven format for institutional soft drink dispensing.
FDA food contact substance regulations govern aluminum migration limits into beverages in the United States, while the EU Green Deal and REACH framework restrict certain adhesive chemistries in multi-layer laminates destined for European markets. EFSA migration testing protocols shape reformulation priorities for suppliers seeking continental market access. Stakeholders must monitor evolving extended producer responsibility schemes that will determine whether aluminum-polymer hybrid structures qualify for circular economy labeling.
Market Dynamics
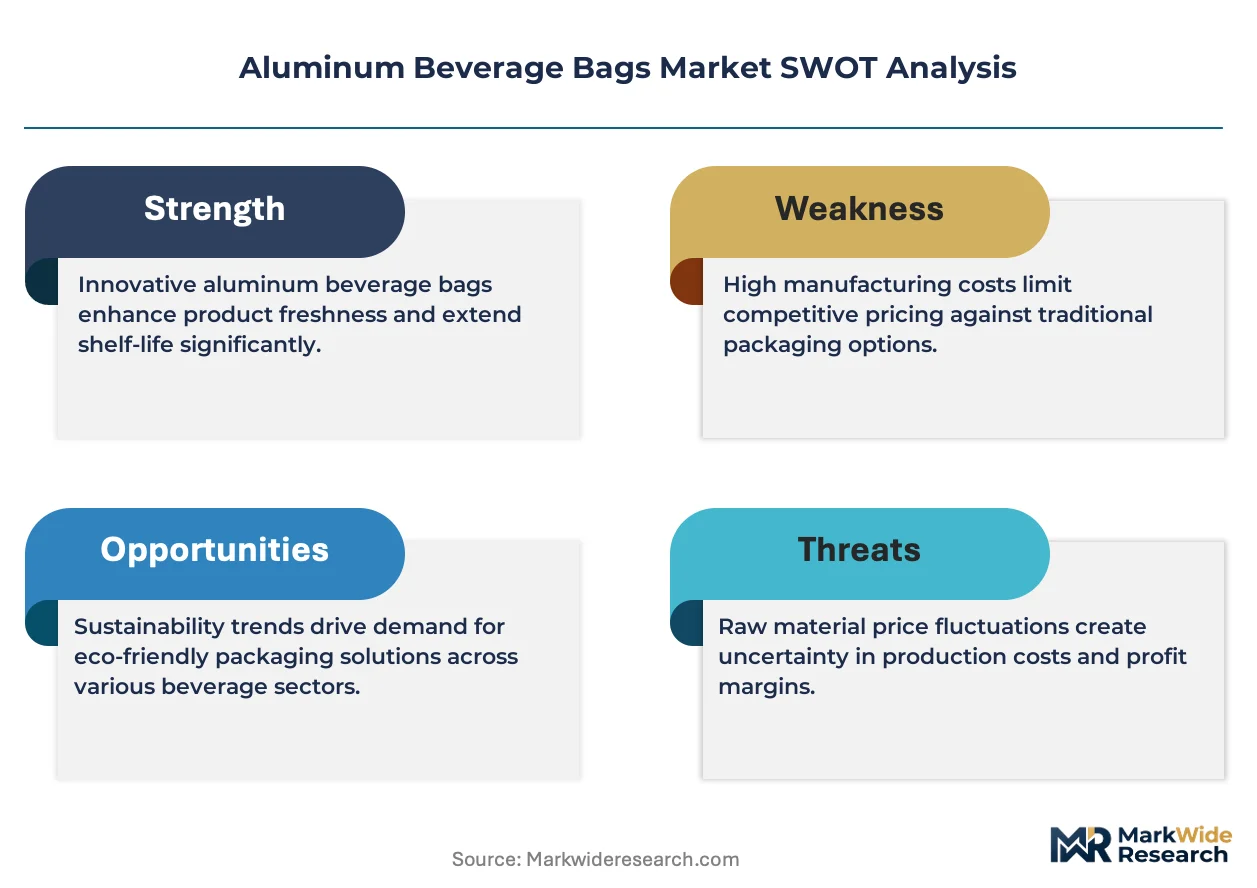
The EU Green Deal's packaging waste directives are forcing beverage co-packers to redesign multi-layer laminates for circular economy compliance, creating a structural pivot toward recyclable aluminum-barrier structures.
Growth Catalysts
- REACH framework reformulation:ECHA restrictions on legacy adhesive chemistries are accelerating supplier investment in compliant heat-seal coatings for European market access.
- Energy drink outdoor consumption:Sports and adventure beverage brands are migrating from rigid cans to flexible pouches for portability and reduced shipping weight.
- Germany co-packer retrofit wave:Beverage contract manufacturers in Bavaria and North Rhine-Westphalia are converting canning lines to pouch-compatible formats.
Market Restraints
- Aluminum substrate volatility:Thin-gauge foil supply concentrates among a handful of European and Asian rolling mills, exposing converters to input cost swings.
- Multi-layer recycling incompatibility:Current mechanical separation processes cannot recover aluminum from polyethylene-polypropylene hybrid structures, limiting circular economy claims.
- Retort sterilization ceiling:Aluminum-polymer laminates face temperature-pressure limits that exclude them from ultra-high-temperature beverage categories.
Strategic Opportunities
- Extended producer responsibility schemes:Germany's VerpackG and France's AGEC law are creating first-mover advantages for suppliers with certified recyclable designs.
- Spouted pouch pediatric expansion:Children's juice brands are adopting resealable formats to capture repeat purchase behavior in convenience retail.
- Digital printing convergence:HP Indigo and Xeikon systems enable short-run variable decoration for craft spirits limited editions.
Industry Challenges
- Migration testing capacity:EFSA protocols for aluminum ion detection require specialized analytical laboratories with months-long queue times.
- Laminate-to-line compatibility:Heat-seal coating chemistry variations force co-packers to revalidate forming-fill-seal equipment for each substrate supplier.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Beverage Bags Market |
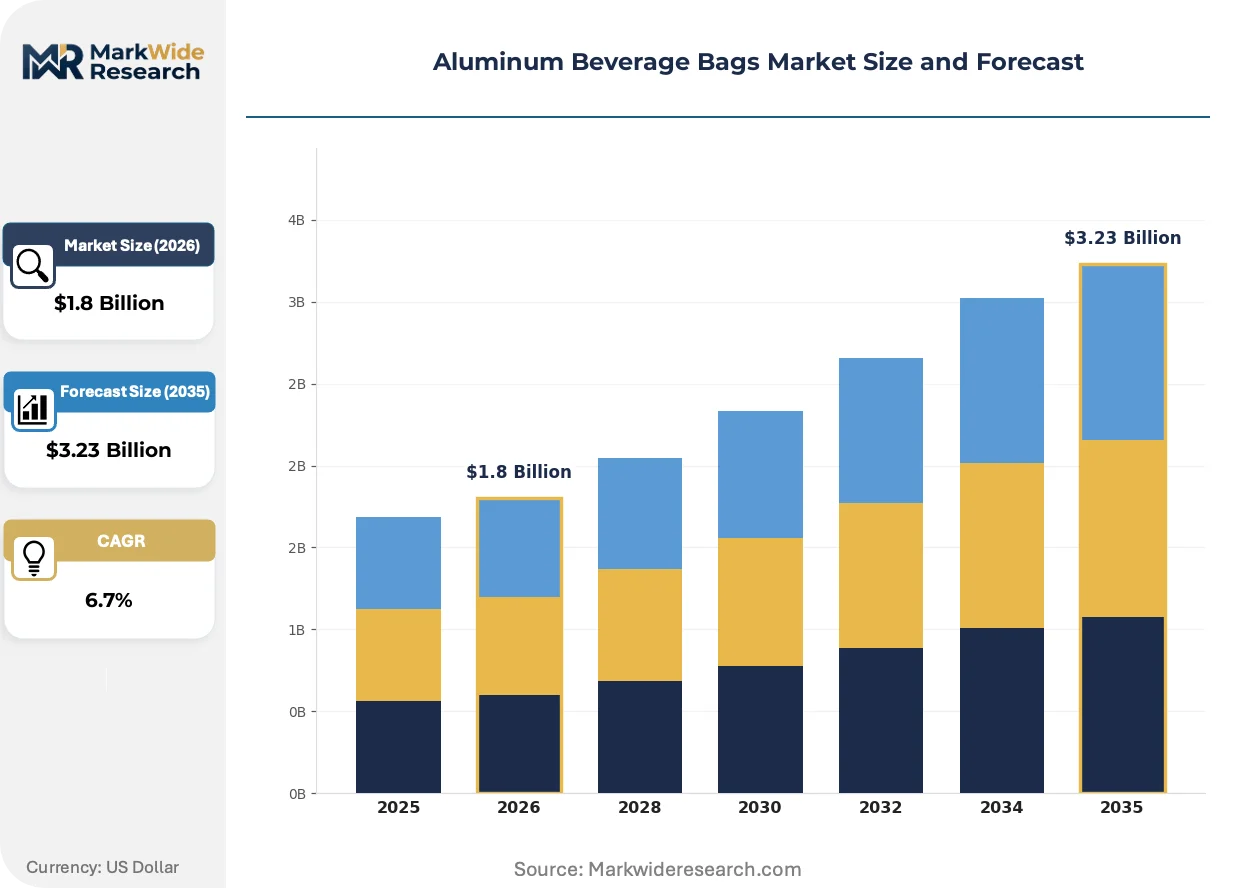
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Bags, Spouted Pouches, Rigid Containers End User: Food & Beverage Manufacturers, Retailers, Distributors, E-commerce Platforms Application: Juices, Soft Drinks, Spirits, Energy Drinks Material: Polyethylene, Polypropylene, Paper-Laminated, Others |
| Companies Covered | Silgan Holdings, Novelis, Ball Corporation, Sonoco Products Company, Alcoa Corporation, Crown Holdings, Amcor plc, Constantia Flexibles, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Beverage Bags Market Strategic Shifts
Material science advances and regulatory pressure are compressing development cycles for next-generation barrier structures. Three active shifts are reconfiguring competitive requirements.
High-barrier aluminum oxide nanocoating is converging with conventional foil laminates to enable downgauging without oxygen transmission rate degradation. Premium spirits producers in France and Italy are piloting these substrates for embossed pouch applications. The technology is converging with rotogravure printing to deliver metallic visual effects at reduced material intensity.
EFSA migration testing protocols are tightening aluminum ion thresholds for acidic beverage contact. Suppliers serving citrus and energy drink formulations face reformulation mandates for sealant layer chemistry. German converters are responding by qualifying alternative acid-resistant copolymer grades ahead of anticipated enforcement.
Direct-to-retail procurement by craft beverage brands is compressing minimum order quantities and accelerating design refresh cycles. Traditional distributor-mediated supply chains in North American spirits are losing share to platform-based packaging sourcing. This pattern is most visible in California and Texas where incubator brands bypass legacy co-packer relationships.
Aluminum Beverage Bags Market Segmentation
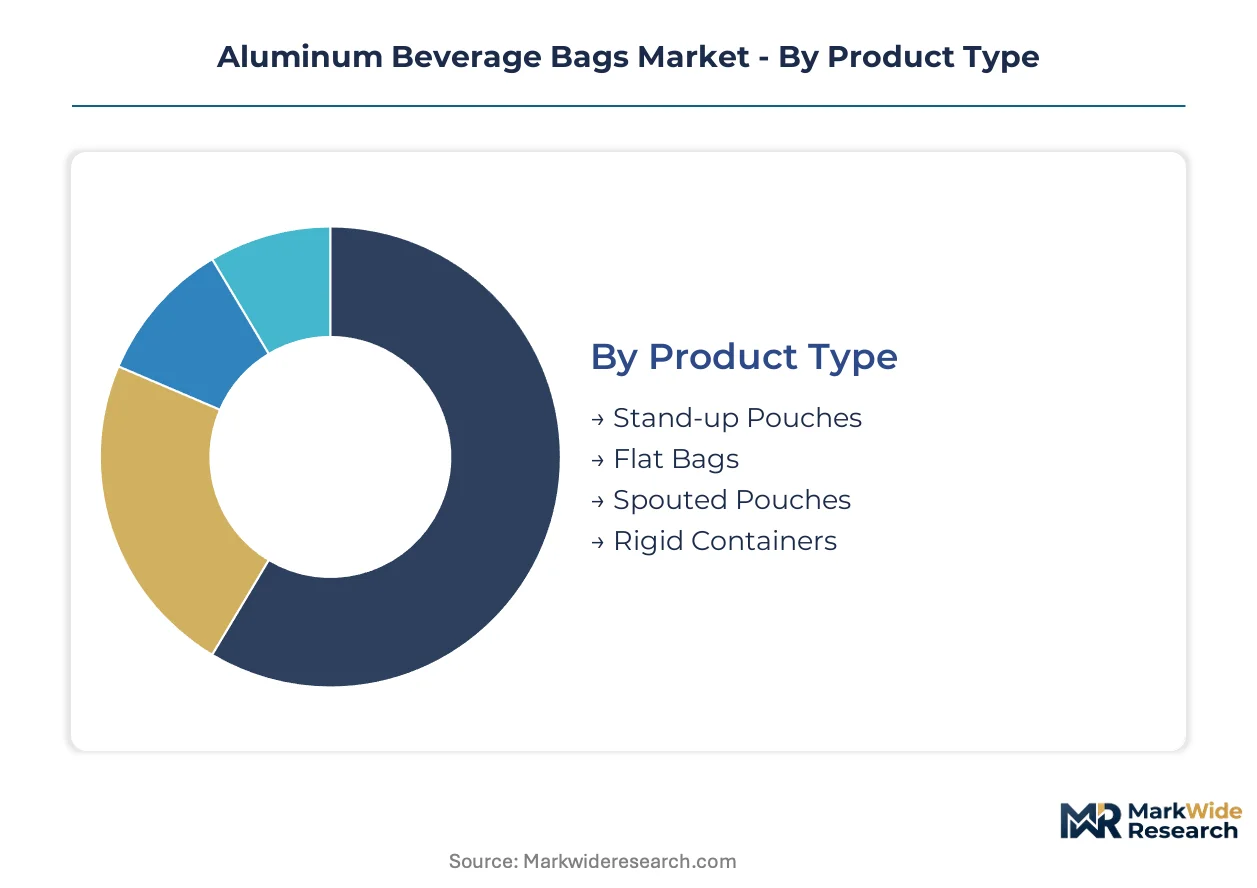
Aluminum beverage bags serve divergent functional requirements across portable consumption, retail shelf presence, and institutional dispensing. Segmentation reveals how format choices map to margin structures and regulatory compliance burdens in this hybrid packaging category.
Product Type:
Buyers differentiate primarily by shelf visibility requirements and dispensing mechanics rather than barrier performance alone.
- Stand-up Pouches:Self-supporting gusseted structures with aluminum-oxide barrier layers provide 180-degree retail visibility and pour-control spouts. Spirits and energy drink brands in Germany and France specify these for premium positioning where countertop presence commands wholesale price premiums.
- Spouted Pouches:Resealable fitment-integrated formats combine child-resistant closures with extended shelf life for pediatric juice applications. Bavarian co-packers are retrofitting forming-fill-seal lines to accommodate these formats as repeat purchase behavior concentrates in convenience retail channels.
- Flat Bags:Two-web laminates without structural gussets minimize unit cost for high-volume institutional soft drink dispensing. The format dominates foodservice contracts where storage density outweighs merchandising requirements.
- Rigid Containers:Semi-rigid aluminum-composite cans and bottles occupy niche applications requiring stackability and thermal resistance beyond flexible laminate limits.
Stand-up pouches lead volumes today; spouted pouches are gaining share fastest.
End User:
Procurement scale and technical specification authority separate the four buyer categories.
- Food & Beverage Manufacturers:Brand owners with captive formulation expertise drive substrate specifications for oxygen transmission rates and migration compliance. These buyers qualify multiple converters against EFSA protocols for European market access.
- Retailers:Private-label programs at German discounters and French hypermarkets are consolidating pouch sourcing through direct platform procurement, compressing design refresh cycles.
- Distributors:Intermediary buyers aggregate fragmented craft beverage demand in North American spirits, though their share erodes as incubator brands bypass traditional channels.
- E-commerce Platforms:Direct-to-consumer fulfillment requirements prioritize damage-resistant formats with reduced shipping weight, favoring flexible pouches over rigid alternatives.
Food and beverage manufacturers command the largest procurement volumes; e-commerce platforms are expanding most quickly.
Application:
Acidity levels and thermal processing requirements dictate laminate structure selection across beverage categories.
- Spirits:High-alcohol formulations with low acidity permit thinner barrier layers and enable embossed metallic finishes for premium positioning. Italian and French producers pilot aluminum-oxide nanocoating to reduce material intensity.
- Energy Drinks:Acidic formulations with added vitamins drive demand for acid-resistant sealant chemistries as EFSA tightens aluminum ion migration thresholds. Sports brands are shifting from cans to pouches for outdoor portability.
- Juices:Pasteurized and aseptic versions span commodity flat bags for institutional dispensing and premium spouted formats for children's segments.
- Soft Drinks:Carbonation retention requirements have historically excluded flexible formats, though nitrogen-flush pouch trials are underway for flat, non-carbonated variants.
Soft drinks dominate absolute consumption volumes; energy drinks show the steepest expansion trajectory.
Material:
Recyclability certification and heat-seal compatibility determine material selection priorities.
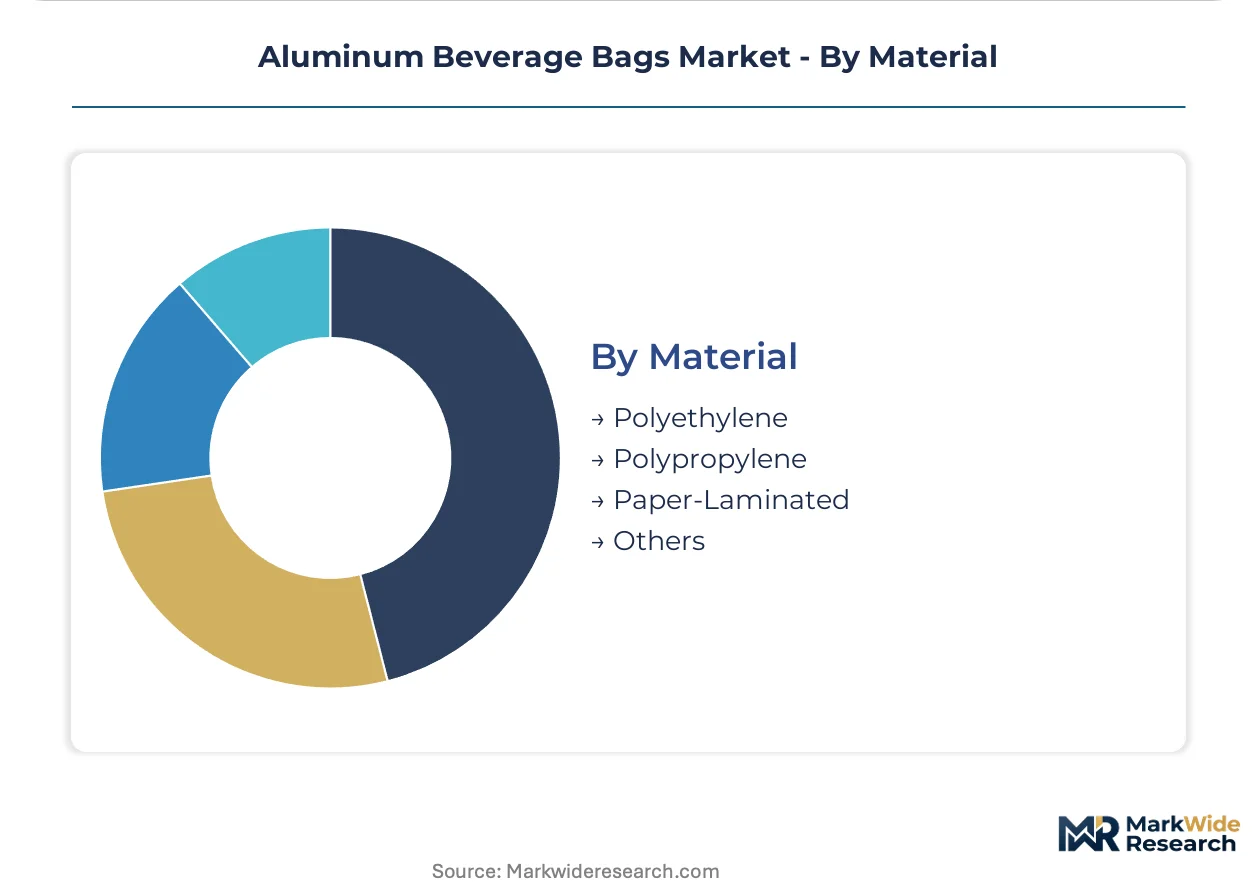
- Polyethylene:Linear low-density grades provide sealant layer flexibility and chemical resistance for acidic beverages. German converters are qualifying acid-resistant copolymer grades ahead of anticipated EFSA enforcement.
- Polypropylene:Higher thermal tolerance enables retort sterilization applications, though temperature-pressure limits still exclude ultra-high-temperature categories. Cast film structures offer clarity for windowed pouch designs.
- Paper-Laminated:Fiber-based outer webs support EU Green Deal circular economy labeling claims where mechanical separation processes can recover aluminum from hybrid structures.
- Others:Bio-based sealants and dissolvable adhesive systems occupy experimental niches awaiting regulatory qualification for food contact.
Polyethylene leads installed base volumes; paper-laminated constructions are climbing the fastest as extended producer responsibility schemes mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled co-packer workforces in Bavaria and North Rhine-Westphalia anchor European aluminum beverage bag production. German technical specialists operate retrofitted forming-fill-seal lines that service spirits and energy drink brands across the continent.
Germany
Beverage co-packers in Bavaria and North Rhine-Westphalia drive retrofit demand for pouch-compatible equipment. The EU Green Deal's packaging waste directives force laminate redesign toward recyclable structures. Munich-area converters qualify acid-resistant copolymer grades for energy drink formulations ahead of anticipated EFSA enforcement.
United States
Craft spirits incubator brands in California and Texas compress design refresh cycles through direct platform procurement. FDA food contact substance regulations govern aluminum migration limits for acidic beverages. West Coast contract manufacturers pilot short-run digital printing for limited-edition pouch decoration.
France
Premium spirits producers in the Île-de-France and Provence-Alpes-Côte d'Azur regions pilot aluminum-oxide nanocoating for embossed pouch applications. France's AGEC law creates first-mover advantages for suppliers with certified recyclable designs. Lyon-area converters integrate rotogravure printing to deliver metallic visual effects at reduced material intensity.
Italy
Spirits brands in Lombardy and Piedmont specify thinner barrier layers for high-alcohol formulations with embossed metallic finishes. EFSA migration testing protocols shape reformulation priorities for European market access. Milan-area technical centers validate heat-seal coating chemistry for sensitive formulations.
China
Domestic beverage brands in the Yangtze River Delta and Pearl River Delta experiment with nitrogen-flush pouch trials for flat soft drink variants. The country's national food safety regulator monitors aluminum ion thresholds in acidic contact applications. Shanghai-area converters supply thin-gauge foil substrates for regional barrier laminate production.
Aluminum Beverage Bags Market Competitive Environment
Top-tier vendors anchor rolled aluminum supply and vertical equipment control, while mid-tier converters compete on heat-seal chemistry and coating specialization. The vendor base stratifies across substrate suppliers with captive rolling capacity, flexible packaging specialists with laminating expertise, and diversified material companies with polymer compounding capabilities. Two dominant competitive moves are reshaping positioning: backward integration into foil rolling to secure thin-gauge substrate supply, and strategic partnerships with digital printing equipment providers to capture craft beverage short-run demand.
Among North American metal packaging specialists, Ball Corporation and Silgan Holdings occupy positions that exemplify equipment-centric competitive strategies, while Novelis represents the substrate-supply archetype with rolled aluminum leadership. Constantia Flexibles sits within the European flexible packaging specialist tier where heat-seal coating chemistry differentiation determines converter selection for sensitive formulations.
| Leading Market Players |
|---|
| Silgan Holdings |
| Novelis |
| Ball Corporation |
| Sonoco Products Company |
| Alcoa Corporation |
| Crown Holdings |
| Amcor plc |
| Constantia Flexibles |
| Ardagh Group |
| Others |
Value Chain & Pricing Dynamics
Backward integration into thin-gauge foil rolling anchors supply position for European converters while insulating them from aluminum substrate volatility that compresses margins for equipment-dependent competitors. This upstream control over barrier layer feedstock translates directly into pricing power against co-packers retrofitting lines in Bavaria and North Rhine-Westphalia.
Pricing Analysis
The bundled-vs-unbundled service split separates substrate-only suppliers from converters offering full laminate-to-line validation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and heat-seal chemistry complexity. Pricing pressure stems from EFSA migration testing queue times that delay European market access. Food and beverage manufacturers with captive formulation expertise show lowest price sensitivity; institutional soft drink buyers demand commodity flat bags at minimum unit cost.
Supply Chain Analysis
Reverse-logistics flows for aluminum-polymer hybrid structures remain undeveloped because mechanical separation processes cannot recover foil from polyethylene-polypropylene laminates. Primary supply concentrates in Germany, France, and Italy where skilled co-packer workforces operate retrofitted forming-fill-seal lines. Raw material dependencies center on rolled aluminum substrate, acid-resistant copolymer sealants, and heat-seal coating chemistries. Single-source vulnerability in thin-gauge foil rolling exposes converters to input cost swings. Distribution runs through beverage co-packers and direct platform procurement by craft spirits brands in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum beverage bags market functions as a stable compounder where regulatory-driven material redesign sustains steady replacement demand across extended producer responsibility schemes.
For Market Incumbents: Anchor rolled aluminum supply through captive rolling capacity or long-term offtake agreements with European mills to defend against substrate volatility. Deepen heat-seal coating chemistry specialization for EFSA-compliant energy drink formulations as acid-resistant copolymer qualification becomes the priority lever against emerging Asian competitors. For New Entrants and Emerging Players: The price-point gap between premium embossed spirits pouches and economy institutional flat bags offers white-space entry through mid-tier spouted pouch formats for pediatric juice applications. Target Bavarian co-packers retrofitting lines for resealable fitment-integrated structures. Pursue direct platform procurement relationships with California craft beverage incubator brands to bypass legacy distributor channels. For Investors and Strategic Acquirers: Consolidation pressure builds where heat-seal coating chemistry expertise concentrates among mid-tier European flexible packaging specialists with laminating capabilities but without captive foil supply. Long-term viability favors converters with certified recyclable designs under Germany's VerpackG and France's AGEC law. Monitor EFSA enforcement timing on aluminum ion migration thresholds as the inflection signal for acid-resistant sealant layer demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foil Rolling | Captive thin-gauge substrate supply insulates Novelis and European mills from aluminum price volatility. |
| Heat-Seal Chemistry Certification | EFSA-compliant coating validation opens European energy drink market access for Constantia Flexibles. |
| Digital Printing Partnership | HP Indigo and Xeikon system integration captures California craft spirits short-run variable decoration demand. |
| Co-Packer Line Retrofit | Forming-fill-seal equipment conversion in Bavaria and North Rhine-Westphalia enables spouted pouch production scale. |
| Recyclable Design Certification | VerpackG and AGEC law compliance creates first-mover advantage in German and French extended producer responsibility schemes. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a complete demand picture for aluminum beverage bag procurement. Primary fieldwork engaged beverage co-packer operations directors, flexible packaging converter technical leads, brand owner packaging procurement managers, and regulatory affairs specialists at EFSA and FDA. Secondary validation drew from customs trade data for aluminum foil and laminate imports, EU Green Deal implementation tracking databases, SEC filings by metal packaging specialists, and ECHA restriction proposal documentation. Bottom-up volume estimates from co-packer line capacity and retrofit timelines triangulated against top-down category spend analysis.
Comparable-period anchoring used historical pouch adoption curves in adjacent flexible packaging categories to calibrate penetration assumptions across the projection horizon. The analytical framework modeled demand by product type, application acidity level, end-user procurement scale, and material recyclability certification tier. CAGRs derived from segment-level volume build-ups incorporating line retrofit timelines, EFSA enforcement probability weighting, and extended producer responsibility scheme adoption rates. Industry-specific inputs included aluminum oxide nanocoating pilot scale-up trajectories and nitrogen-flush soft drink trial outcomes.
Caveats apply where EFSA migration testing queue times or aluminum substrate supply disruptions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement timing and co-packer retrofit completion rates. Practitioners should monitor VerpackG certification approval velocity and acid-resistant copolymer qualification timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bulk Bag Divider Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Bag & Bag Aerosol Can Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Lay Flat Bags Market
Bags and Containers
Hanging Bags Market