
 Fresh Food Packaging Market | 2026-2036
Fresh Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Food Packaging Market Intelligence
The BRCGS Global Standard for Packaging Materials is reorganizing the supplier landscape by establishing stringent safety and quality benchmarks for food-contact applications. This certification gates market access for suppliers aiming to serve major food processors and retailers. Amcor plc leverages its global manufacturing footprint to provide consistent packaging solutions to multinational clients. Sealed Air Corporation specializes in high-performance flexible films and vacuum packaging systems that extend product shelf life. Meanwhile, Mondi plc competes through its diverse portfolio of paper-based and flexible plastic solutions.
Fresh food packaging encompasses materials and systems engineered to preserve the quality, safety, and integrity of perishable goods from farm to consumer. These solutions often incorporate technical features like controlled gas permeability for modified atmosphere packaging (MAP) or high-barrier properties against oxygen and moisture. The primary commercial purpose is to reduce food spoilage and waste across the supply chain. Flexible packaging formats lead the market in volume for applications like fruits and vegetables due to material efficiency, while biodegradable polymers represent the fastest-growing material segment.
Regulatory frameworks from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) define stringent requirements for food-contact materials. These rules govern chemical migration, material composition, and overall safety, directly impacting product design and market entry. Concurrently, sustainability mandates, including the EU Green Deal, are forcing a shift toward recyclable and compostable packaging formats. Decisions regarding material circularity and compliance with evolving extended producer responsibility schemes will define future competitive positioning.
Market Dynamics
The central dynamic in the fresh food packaging market is the structural tension between escalating regulatory pressure for material circularity, exemplified by the EU Green Deal, and the unyielding technical demand for shelf-life extension to reduce food waste.
Growth Catalysts
- E-Commerce Expansion:The growth of direct-to-consumer grocery delivery services necessitates robust, individual-item packaging solutions that maintain freshness and prevent damage throughout the last-mile logistics chain.
- Food Waste Reduction Policies:Government initiatives aimed at curbing food spoilage, particularly in developed economies, stimulate demand for advanced packaging like modified atmosphere packaging (MAP) that extends product viability.
- Biodegradable Polymer Development:Advances in materials like polylactic acid (PLA) and polyhydroxyalkanoates (PHA) provide compostable alternatives for single-use applications, meeting both consumer and regulatory demand for sustainable options.
Market Restraints
- Input Cost Volatility:Manufacturer profitability is exposed to price fluctuations in key raw materials, especially petroleum-derived resins like polyethylene and polypropylene, which are subject to global commodity market dynamics.
- Recycling Infrastructure Gaps:The limited availability of collection and sorting infrastructure for flexible films and multi-material structures in many regions hinders the development of a true circular economy for these formats.
- Regulatory Compliance Costs:Adherence to stringent food-contact regulations from bodies like the FDA and EFSA requires significant investment in material testing, certification, and documentation, creating barriers for smaller suppliers.
Strategic Opportunities
- Active and Intelligent Packaging:Integrating technologies such as ethylene scavengers for produce or time-temperature indicators for meats offers a significant value-add by actively preserving quality and providing spoilage information.
- Paper-Based Solutions:Developing high-performance, recyclable paper and board packaging with advanced coatings for moisture and grease resistance can capture market share from plastics in categories like fresh bakery and produce.
- Emerging Market Cold Chains:The build-out of refrigerated supply chains in Southeast Asia and Latin America creates new demand for sophisticated packaging solutions to support the export of perishable goods.
Industry Challenges
- Material Standardization:The lack of global standards for compostable and biodegradable materials leads to consumer confusion and contamination of recycling streams, complicating end-of-life processing for all packaging types.
- Capital Investment for New Materials:Transitioning production lines to accommodate emerging materials, such as mono-material laminates or bio-polymers, requires substantial capital expenditure on new machinery and process validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Food Packaging Market |
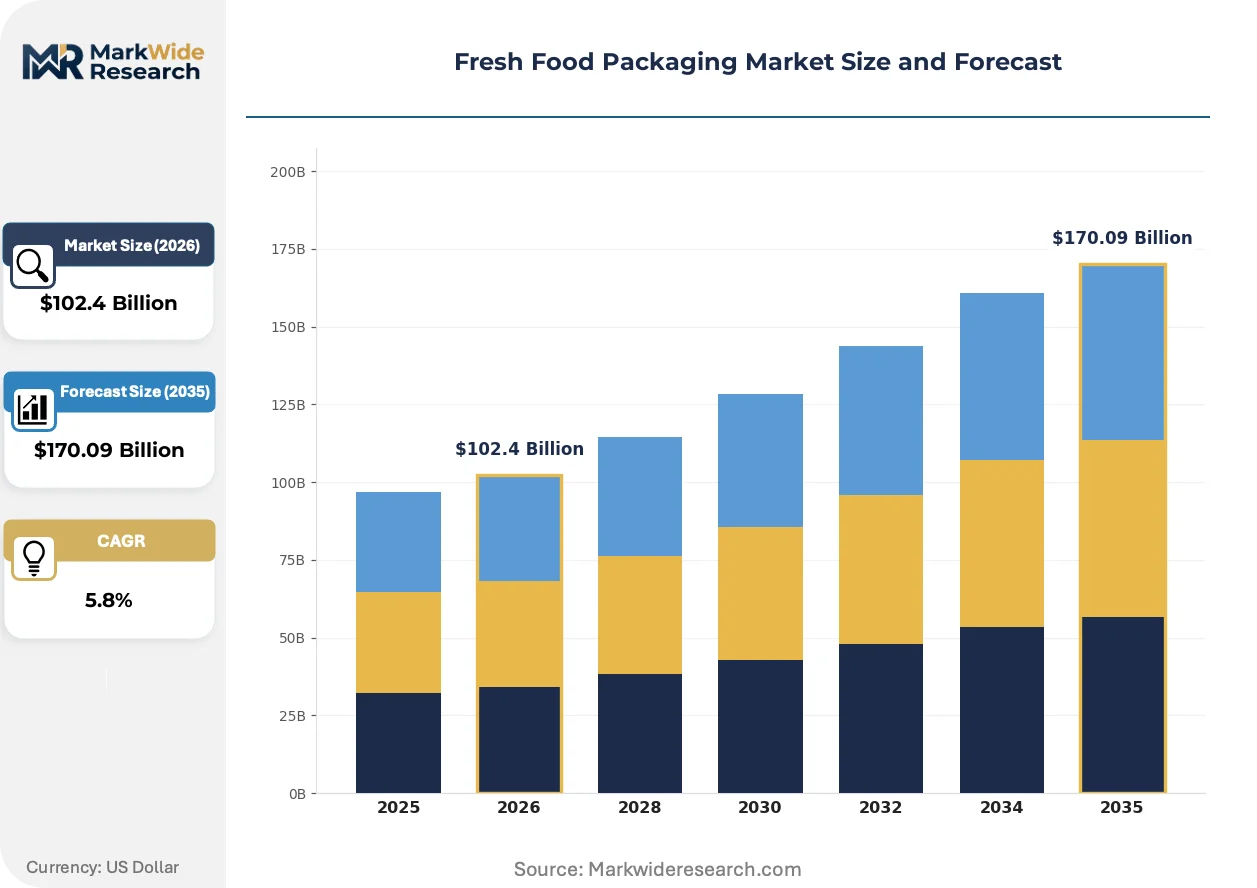
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $170.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Packaging, Flexible Packaging, Vacuum Packaging, Modified Atmosphere Packaging, Biodegradable Packaging Packaging Material: Plastic, Paperboard, Aluminum, Glass, Biodegradable Polymers Application: Fruits, Vegetables, Meat, Seafood, Dairy Products End User: Supermarkets, Foodservice Providers, Food Processors, Online Retailers |
| Companies Covered | Amcor plc, DS Smith Plc, Mondi plc, Sealed Air Corporation, International Paper Co., Huhtamaki Oyj, Sonoco Products Company, Coveris, ProAmpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Food Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science and digital technologies. This intersection aims to solve the dual challenges of enhancing supply chain visibility while simultaneously meeting aggressive sustainability targets set by regulators and consumers.
Mono-material flexible films, engineered from a single polymer like polyethylene, provide a key technological advancement. These materials are designed for compatibility with existing mechanical recycling streams, a feature highly valued by consumer packaged goods companies. Adoption is accelerating for products like frozen vegetables and snack foods, where this technology is supplanting traditional multi-layer laminates that hinder circularity.
Regulations such as the EU's Packaging and Packaging Waste Regulation (PPWR) are setting mandatory recycling targets and recycled content minimums. This directly impacts material selection, compelling producers to redesign packaging for improved recyclability and incorporate post-consumer resin (PCR). The beverage and household goods sectors are most affected, driving innovation in chemical recycling to produce food-grade PCR.
Consumer demand for transparency is driving the integration of digital watermarks and QR codes directly onto packaging. This shift augments static on-pack information, allowing brands to communicate detailed provenance, nutritional data, and end-of-life instructions. This trend is most prominent in the organic produce and premium protein segments in North American and European retail markets.
Fresh Food Packaging Market Segmentation
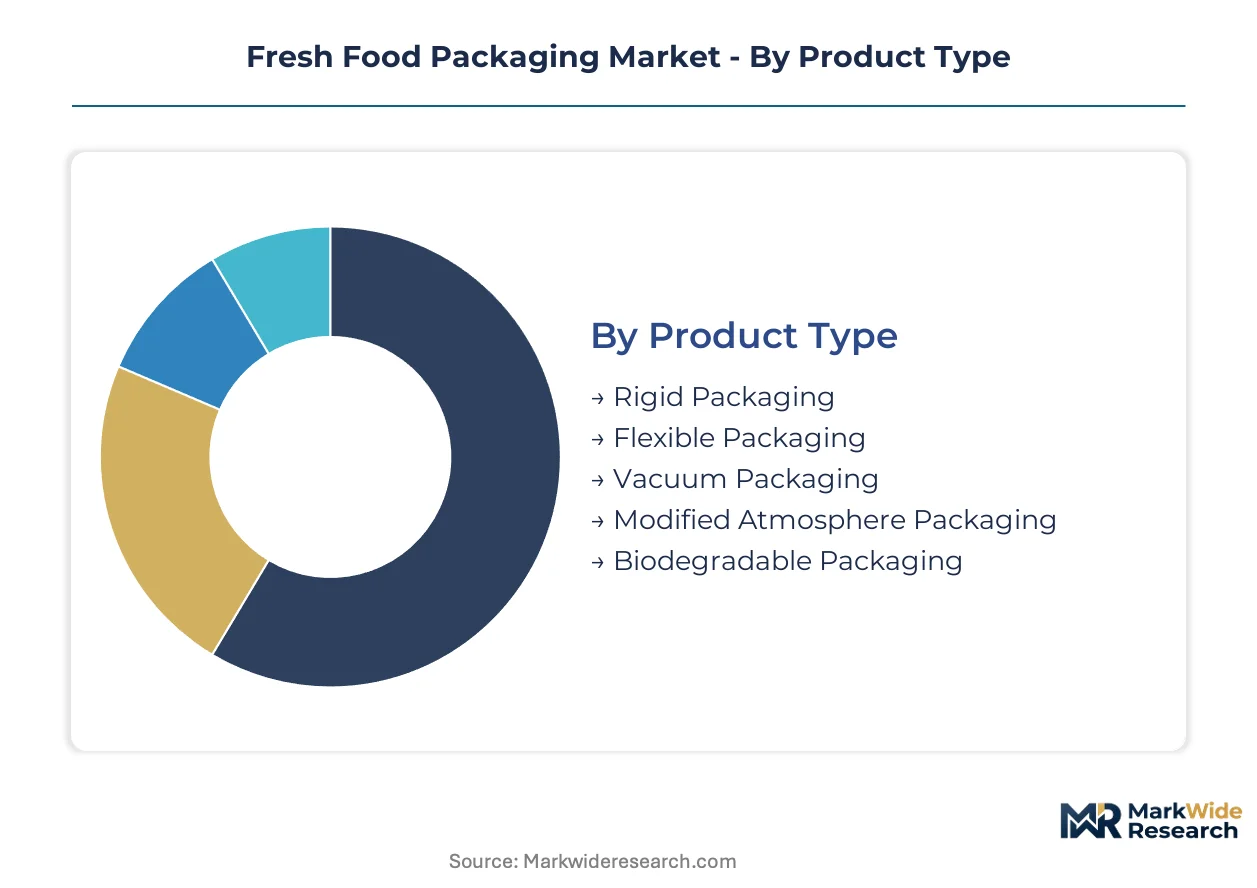
The fresh food packaging market segments reflect distinct material properties, application requirements, and end-user demands across the supply chain. Understanding these differentiations is critical for manufacturers to align product development with evolving consumer preferences and stringent regulatory mandates.
Product Type:
Certain product types demonstrate varying levels of adoption across different geographies, influenced by local dietary habits and supply chain maturity.
- Flexible Packaging:This category includes films, pouches, and bags engineered for material efficiency and adaptability, often featuring controlled gas permeability for modified atmosphere packaging. Demand is concentrating in global markets for fruits and vegetables, driven by e-commerce expansion and food waste reduction policies, particularly within Germany.
- Biodegradable Packaging:Comprising materials like polylactic acid (PLA) and polyhydroxyalkanoates (PHA), these solutions offer compostable alternatives for single-use applications. This segment sees significant demand in the European Union, propelled by the EU Green Deal and consumer preference for sustainable options.
- Rigid Packaging:Containers such as trays, clamshells, and bottles provide structural protection and stacking strength for various fresh produce and dairy items.
- Vacuum Packaging:This method removes air from the package, creating an oxygen-free environment to significantly extend the shelf life of highly perishable goods like meat and seafood.
- Modified Atmosphere Packaging:MAP systems actively alter the internal gas composition of a package to slow respiration rates and microbial growth, widely applied for fresh-cut produce and poultry.
Flexible Packaging commands the established base. The steepest expansion runs through Biodegradable Packaging.
Packaging Material:
Material selection is primarily dictated by the specific barrier properties required for product preservation and the sustainability goals of the brand and region.
- Plastic:This broad category includes polyethylene, polypropylene, and PET, offering versatility in form, barrier properties against moisture and oxygen, and cost-effectiveness. Demand for plastic packaging remains widespread across all food applications, though it faces escalating pressure for recyclability and circularity from regulations like the EU's Packaging and Packaging Waste Regulation (PPWR).
- Biodegradable Polymers:These materials, including starch-based polymers and cellulose, are designed to decompose naturally, addressing concerns about plastic pollution. This material segment experiences rapid uptake in regions with advanced composting infrastructure and strong sustainability mandates, such as parts of Western Europe.
- Paperboard:Used extensively for cartons, trays, and wraps, paperboard provides structural integrity and printability, often requiring specialized coatings for moisture and grease resistance.
- Aluminum:Primarily used for foils and trays, aluminum offers excellent barrier properties against light, moisture, and oxygen, making it suitable for certain dairy and ready-meal applications.
- Glass:Valued for its inertness, transparency, and premium perception, glass is utilized for products like dairy, sauces, and some specialty produce.
Plastic remains foundational for diverse applications. Biodegradable Polymers gain traction most quickly.
Application:
The volume of packaging consumed varies significantly across different food applications, driven by consumption patterns and preservation needs.
- Fruits:Packaging solutions for fruits focus on preventing bruising, managing respiration, and extending shelf life, often utilizing flexible films with controlled permeability or rigid clamshells for delicate items. E-commerce expansion and food waste reduction policies stimulate demand for advanced fruit packaging.
- Vegetables:Solutions for vegetables range from breathable bags for leafy greens to modified atmosphere packaging for fresh-cut varieties, aiming to maintain crispness and nutritional value. Germany shows pronounced consumer preferences for sustainable and shelf-life extending solutions in this segment.
- Meat:Packaging for meat prioritizes high-barrier properties against oxygen to prevent spoilage and maintain color, commonly employing vacuum packaging or modified atmosphere packaging.
- Seafood:Similar to meat, seafood packaging requires robust barrier properties and often incorporates vacuum or MAP technologies to preserve freshness and prevent bacterial growth.
- Dairy Products:This category includes packaging for milk, yogurt, cheese, and other dairy items, emphasizing hygiene, barrier protection, and often opaque materials to prevent light degradation.
Fruits and Vegetables dominate the market. Seafood is experiencing rapid uptake.
End User:
Each end-user type has distinct packaging requirements, influencing material choices and format specifications.
- Online Retailers:This segment requires robust, individual-item packaging solutions designed to withstand the rigors of last-mile logistics, protecting freshness and preventing damage during direct-to-consumer grocery delivery. The expansion of e-commerce necessitates innovation in this area.
- Supermarkets:These large-format stores demand packaging that is shelf-ready, visually appealing for consumer purchase, and often designed for bulk display or multi-pack options. Consumer preferences for sustainable and convenient formats influence supermarket procurement.
- Foodservice Providers:Packaging for foodservice focuses on bulk formats, ease of handling, and maintaining product integrity during transport to restaurants, cafeterias, and catering operations.
- Food Processors:These entities require packaging that integrates seamlessly with automated filling and sealing lines, often prioritizing cost-efficiency, barrier performance, and regulatory compliance for large-scale production.
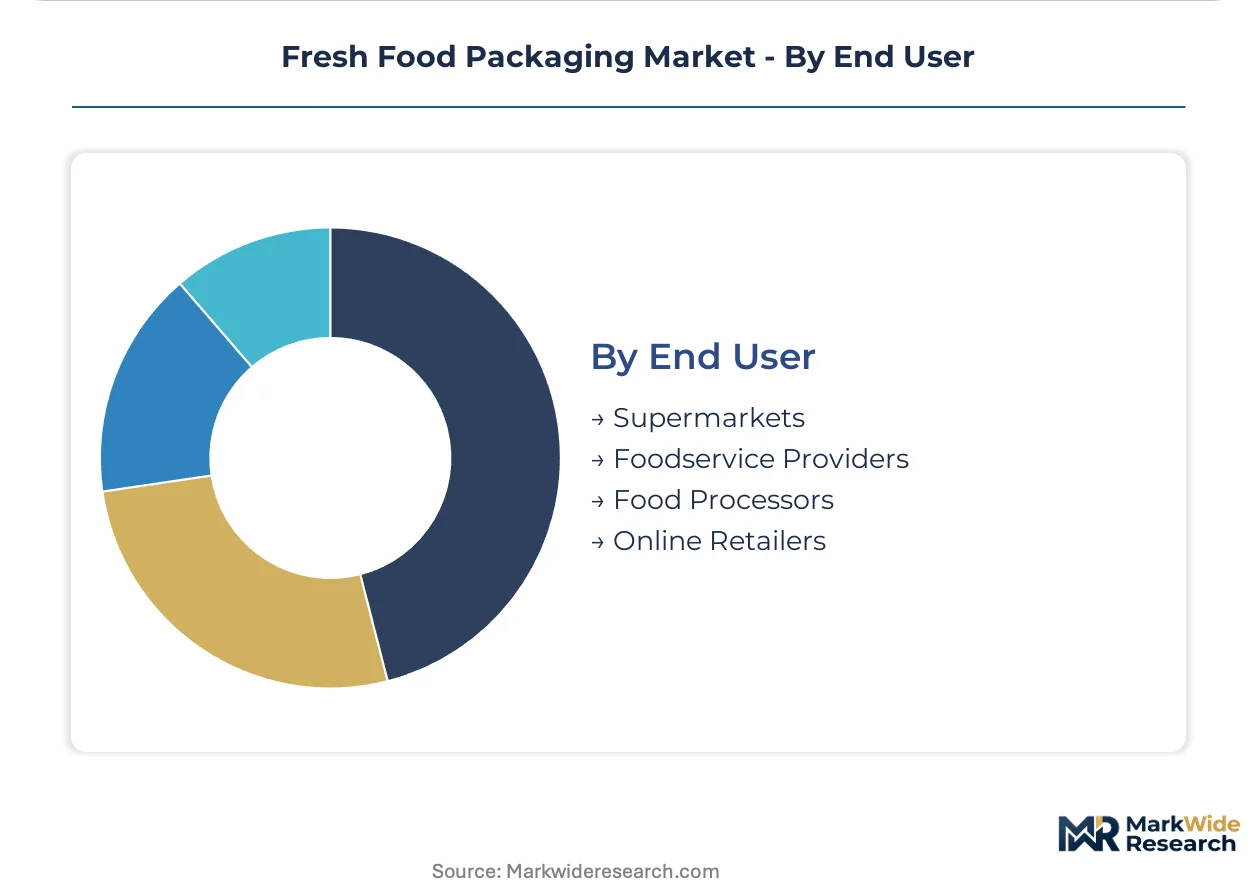
Supermarkets form the mature core. Online Retailers present significant future growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer preferences for sustainable and shelf-life extending solutions drive regional market dynamics. Online retailers and supermarkets concentrate demand for innovative fresh food packaging across diverse geographies. Regulatory frameworks from bodies like the FDA and EFSA define stringent requirements for food-contact materials.
Germany
German consumers prioritize sustainable and shelf-life extending fresh food packaging solutions. The EU Green Deal and REACH regulation directly influence material selection and product design within the country. Packaging manufacturers in the Rhine-Ruhr region focus on developing advanced barrier films and compostable alternatives.
United States
E-commerce expansion and robust cold chain logistics necessitate specialized packaging for fresh produce in the United States. FDA regulations govern chemical migration and material composition for all food-contact substances. The agricultural heartland of California drives demand for innovative fruit and vegetable packaging solutions.
China
China's expanding middle class and heightened food safety concerns stimulate demand for high-barrier fresh food packaging. The country's GB standards define specific requirements for packaging materials and their applications. Manufacturing hubs in the Yangtze River Delta are rapidly adopting automated packaging lines for fresh goods.
India
Modern retail expansion and ongoing cold chain infrastructure development boost demand for fresh food packaging across India. The Food Safety and Standards Authority of India (FSSAI) establishes guidelines for safe food contact materials. Packaging producers in Maharashtra focus on cost-effective, shelf-life extending solutions for perishable items.
Brazil
Brazil's significant agricultural exports and growing urban consumer base drive demand for advanced fresh food packaging. The National Health Surveillance Agency (ANVISA) regulates food packaging safety and material composition. Packaging innovators in São Paulo develop solutions for both domestic distribution and international perishable shipments.
Fresh Food Packaging Market Key Industry Players
Player mix skews toward established global manufacturers and specialized material providers. The market exhibits a tiered structure, with large-scale incumbents competing alongside niche innovators. Strategic archetypes include integrated packaging giants, high-performance flexible film specialists, and sustainable paper-based solution developers. Companies pursue portfolio diversification and geographic expansion to solidify their market presence.
Within the global integrated packaging solutions archetype, Amcor plc represents a large-scale manufacturing presence, serving a broad client base. Sealed Air Corporation exemplifies providers specializing in high-performance flexible films, crucial for extending product shelf life and ensuring product integrity. Mondi plc, a company offering diverse material solutions, anchors the segment for both paper-based and flexible plastic formats, catering to evolving sustainability demands. These entities collectively demonstrate the varied approaches to market leadership, from broad-spectrum offerings to specialized material innovations across fresh food applications globally.
| Leading Market Players |
|---|
| Amcor plc |
| DS Smith Plc |
| Mondi plc |
| Sealed Air Corporation |
| International Paper Co. |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Coveris |
| ProAmpac LLC |
| Others |
Cost & Logistics Intelligence
Biodegradable polymers displacing traditional plastics simultaneously reshapes supply geography and pricing economics in fresh food packaging. This shift introduces higher material costs for sustainable options while traditional plastic segments navigate commodity market volatility.
Pricing Analysis
Long-term contract-based pricing with resin indexation remains a dominant model for fresh food packaging. Price differentiation stems from specialized barrier properties for modified atmosphere packaging (MAP) and compostable certification levels. Pricing pressure trends upward due to significant R&D investments in sustainable materials and stringent regulatory compliance costs. Foodservice providers exhibit the highest price sensitivity, prioritizing cost-efficiency for bulk formats, while online retailers demonstrate lower sensitivity for robust, individual-item packaging.
Supply Chain Analysis
Just-in-time inventory strategies primarily support high-volume commodity plastic packaging, contrasting with strategic stockpiles for specialized films and advanced biodegradable polymers. Geographic supply concentration for base resins includes major petrochemical hubs in China and the United States, while advanced packaging technologies often originate from Germany. The supply chain draws from key raw materials like polyethylene, polypropylene, and polylactic acid. Commodity price volatility for petroleum-derived resins presents a significant structural risk. Distribution runs through direct sales channels to large food processors and major supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fresh food packaging market is experiencing a cyclical recovery, driven by rebounding consumer spending on fresh produce and renewed sustainability mandates.
For Market Incumbents:
Consolidate market position by acquiring specialized bio-polymer manufacturers to internalize material innovation. Invest heavily in mono-material film production lines to meet evolving circularity mandates like the EU's PPWR. The threat of new regulatory shifts necessitates proactive R&D into advanced barrier coatings for paper-based solutions. Leverage global manufacturing footprints to provide consistent, compliant packaging solutions across diverse multinational client bases.
For New Entrants and Emerging Players:
Lead with active packaging solutions, such as ethylene scavengers for produce or time-temperature indicators for meats. Target the underpenetrated segment of small-to-medium food processors seeking certified sustainable options. The most penetrable application area involves specialized paper-based alternatives for fresh bakery and sensitive produce items. A direct-to-consumer go-to-market angle, focusing on online grocery platforms, offers significant growth potential.
For Investors and Strategic Acquirers:
The market sits at a growth acceleration phase that favors innovators in material science and digital integration. Long-term viability remains strong, driven by the dual imperatives of food waste reduction and circular economy principles over the next decade. Acquisition targets should include startups with patented bio-polymer technologies or advanced chemical recycling processes. The adoption rates of mono-material laminates by major consumer packaged goods companies serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Mono-Material Films | Increases supply of recyclable packaging compatible with existing mechanical recycling infrastructure. |
| Technology Licensing for Barrier Coatings | Accelerates the development of moisture and grease resistant paper-based solutions. |
| Strategic Partnership with Waste Managers | Addresses recycling infrastructure gaps and improves end-of-life processing for flexible formats. |
| Product Launch of Active Packaging | Enhances shelf life and provides real-time spoilage information for highly perishable goods. |
| Green Certification Program Development | Establishes clear standards for compostable and biodegradable materials, reducing consumer confusion. |
Research Approach
A standing panel of packaging engineers, food safety regulators, retail procurement managers, and material scientists provided ongoing calibration for market insights. This approach combined primary interviews with industry stakeholders and secondary validation from diverse data sources. Secondary research included FDA and EFSA guidelines, industry association reports, and company investor filings, facilitating bottom-up and top-down triangulation.
Outputs were consistently validated against external benchmarks to ensure methodological rigor across the analysis window. The analytical framework modeled segmentation dimensions including Product Type, Packaging Material, Application, End User, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary quantitative model, incorporating industry-specific inputs such as e-commerce penetration rates and food waste reduction targets.
Underlying assumptions cover prevailing economic conditions and current regulatory landscapes, with deviation risk concentrated in raw material price shocks or unforeseen new regulatory mandates. Revision becomes warranted when key market conditions cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Europe Food Contract Manufacturing and Packaging Market
Food Packaging
Desserts Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
PET Food Trays Market
Food Packaging
Canned Food Packaging Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Ice Cream Packaging Market
Food Packaging
Pizza Box Market