
 Disposable Hot Cups & Lids Market | 2026-2036
Disposable Hot Cups & Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Hot Cups & Lids Market Analytics
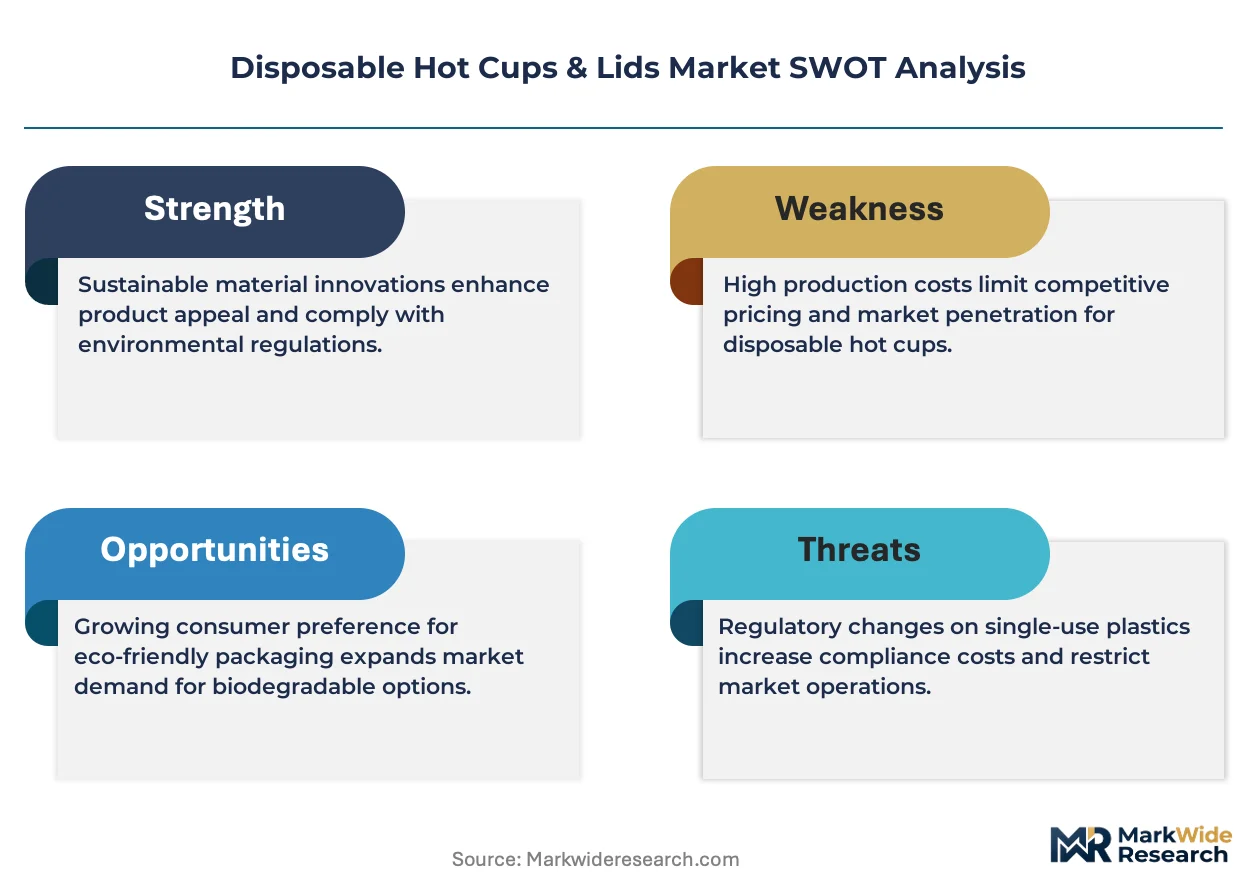
The EU Single-Use Plastics Directive is expanding compliance costs for polystyrene-dependent producers across the European market. Dart Container Corporation leverages its thermoforming expertise to navigate material substitution timelines. Huhtamaki Oyj anchors its position through fiber-based innovation pipelines. Graphic Packaging International LLC dominates North American paperboard cup supply with integrated mill assets.
Disposable hot cups and lids are single-use foodservice containers engineered to maintain beverage temperatures between 60°C and 85°C while preventing leakage during consumer handling; wall structures range from single-wall paperboard to double-wall insulated designs with polyethylene or PLA barrier coatings. Paper cups lead volume globally due to compatibility with conventional hot-fill equipment and established recycling streams. Biodegradable cups represent the fastest-expanding material category as PLA and molded fiber formulations achieve cost parity in premium foodservice channels. The 12 oz and 16 oz size brackets capture the majority of margin pools through high-turnover coffee and tea applications.
FDA food-contact substance regulations govern barrier coating approvals in the United States, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that reshape cost allocation across the value chain. China's GB standards for food-contact plastics and paper products impose testing protocols that influence export-oriented manufacturing decisions. Stakeholders must monitor evolving compostability certification requirements across multiple jurisdictions to secure market access.
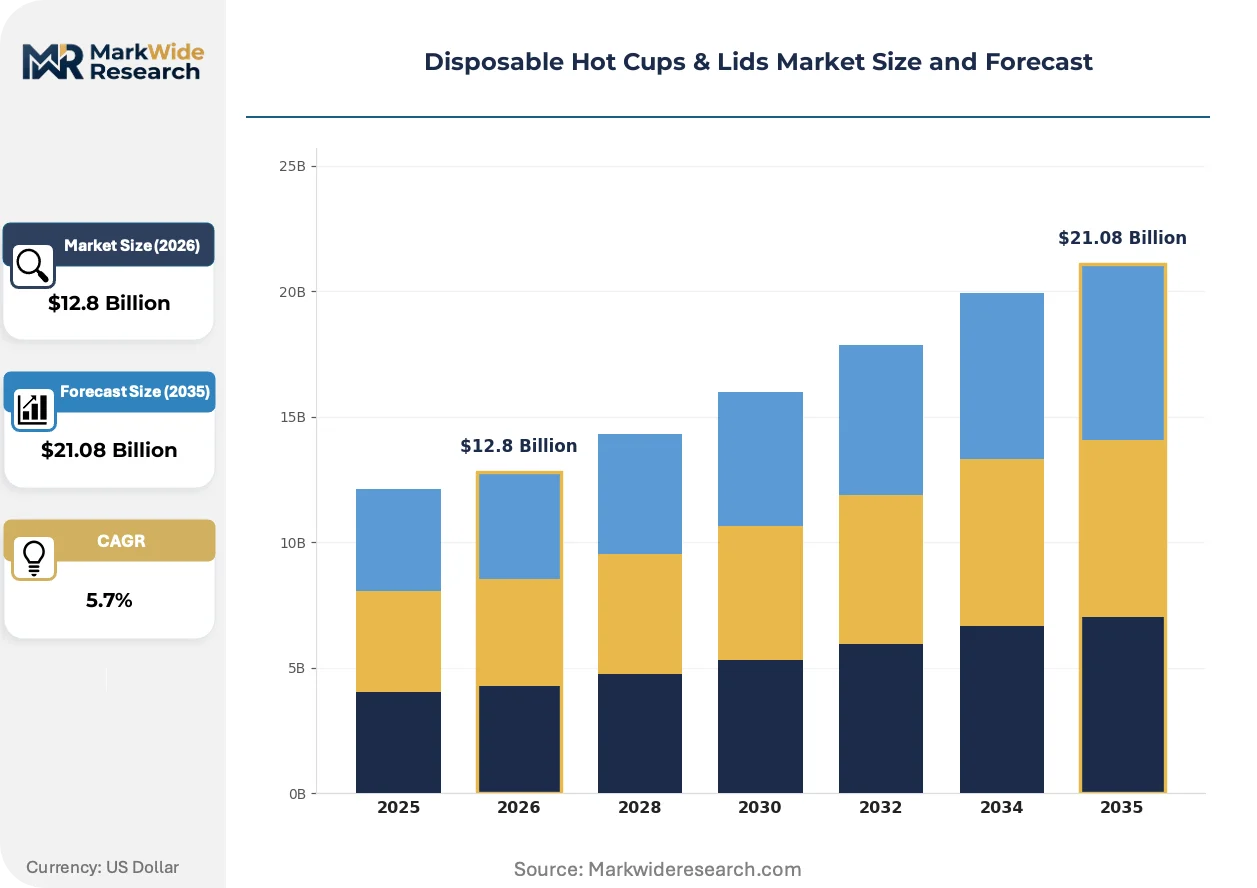
Market Dynamics
Material substitution timelines are compressing as the EU Single-Use Plastics Directive forces polystyrene-dependent producers to retool thermoforming lines ahead of 2030 enforcement milestones.
Growth Catalysts
- Compostable packaging mandates:Quick-service restaurants across Canada and the United States are scaling procurement of fiber-based cups to meet corporate sustainability targets. This procurement shift is accelerating demand for molded fiber lid systems.
- Urban foodservice corridor expansion:China's tier-one cities are witnessing concentrated demand from specialty coffee chains requiring temperature-stable 12 oz and 16 oz formats with integrated splash-resistant closures.
- Extended producer responsibility schemes:The EU Packaging and Packaging Waste Regulation is reallocating end-of-life costs across the value chain, incentivizing lightweighting and recyclability investments by converters.
Market Restraints
- Barrier coating cost volatility:Polyethylene and PLA resin prices fluctuate with fossil fuel and agricultural feedstock markets, squeezing margins for double-wall insulated cup manufacturers.
- Thermoforming equipment lock-in:Polystyrene-dependent producers in Germany and France face stranded asset risk as retrofitting timelines lag behind regulatory phase-out schedules.
- Performance gaps in fiber lids:Molded fiber closures struggle to match polypropylene snap-fit reliability above 80°C, limiting adoption in high-temperature tea applications.
Strategic Opportunities
- India's organized foodservice penetration:Quick-service chains in Mumbai and Bangalore represent underdeveloped demand for 8 oz and 12 oz single-wall formats with compostable certification.
- Aqueous barrier coating convergence:Water-based polyethylene-free coatings combined with high-speed cup-forming equipment enable recyclability claims without PLA price premiums.
- Direct-store-delivery channel innovation:Coffee roasters are bypassing broadline distributors to source custom-printed cups with shorter lead times and minimum order quantity flexibility.
Industry Challenges
- Compostability certification fragmentation:Divergent ASTM D6400, EN 13432, and Australia's AS 4736 testing protocols force manufacturers to maintain multiple certification portfolios for cross-border sales.
- Hot-fill line reconfiguration:Transitioning from PE-coated to PLA-lined cups requires seal-bar temperature adjustments and forming die modifications that extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Hot Cups & Lids Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Cups, Foam Cups, Plastic Cups, Biodegradable Cups Size: 8 oz, 12 oz, 16 oz, 20 oz Material: Polystyrene, Polypropylene, PLA, Paperboard Distribution Channel: Online Retailers, Convenience Stores, Supermarkets, Foodservice |
| Companies Covered | Pactiv LLC, Sabert Corporation, Dart Container Corporation, Tair Chu Enterprise Co., Ltd., Michael Procos S.A., Berry Global Group, Inc., Genpak, LLC, Graphic Packaging International LLC, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Hot Cups & Lids Market Evolving Landscape
Barrier coating chemistry and forming equipment are converging to eliminate polyethylene from hot-fill applications without sacrificing heat-seal integrity or line speed.
Water-based barrier coatings are consolidating technical validation across North American and European cup-forming operations. Major coffee chains in Seattle and London are qualifying these formulations for 90-day rollout timelines. The technology is consolidating supplier positions by collapsing the distinction between recyclable and compostable cup categories.
REACH restrictions on intentionally added microplastics are forcing reformulation of conventional PE barrier coatings across EU member states. German and Italian converters face 2026 compliance deadlines requiring migration testing documentation. Fiber-based cup producers with pre-validated aqueous coatings are capturing displaced volume from polystyrene-dependent competitors.
Consolidated procurement by multi-brand restaurant operators is compressing supplier rosters and extending contract durations. Broadline distributors in Chicago and Toronto are losing share to direct manufacturer relationships as buyers prioritize traceability and custom print capabilities. This concentration is most visible in the 16 oz specialty coffee segment where brand differentiation commands premium positioning.
Disposable Hot Cups & Lids Market Segmentation
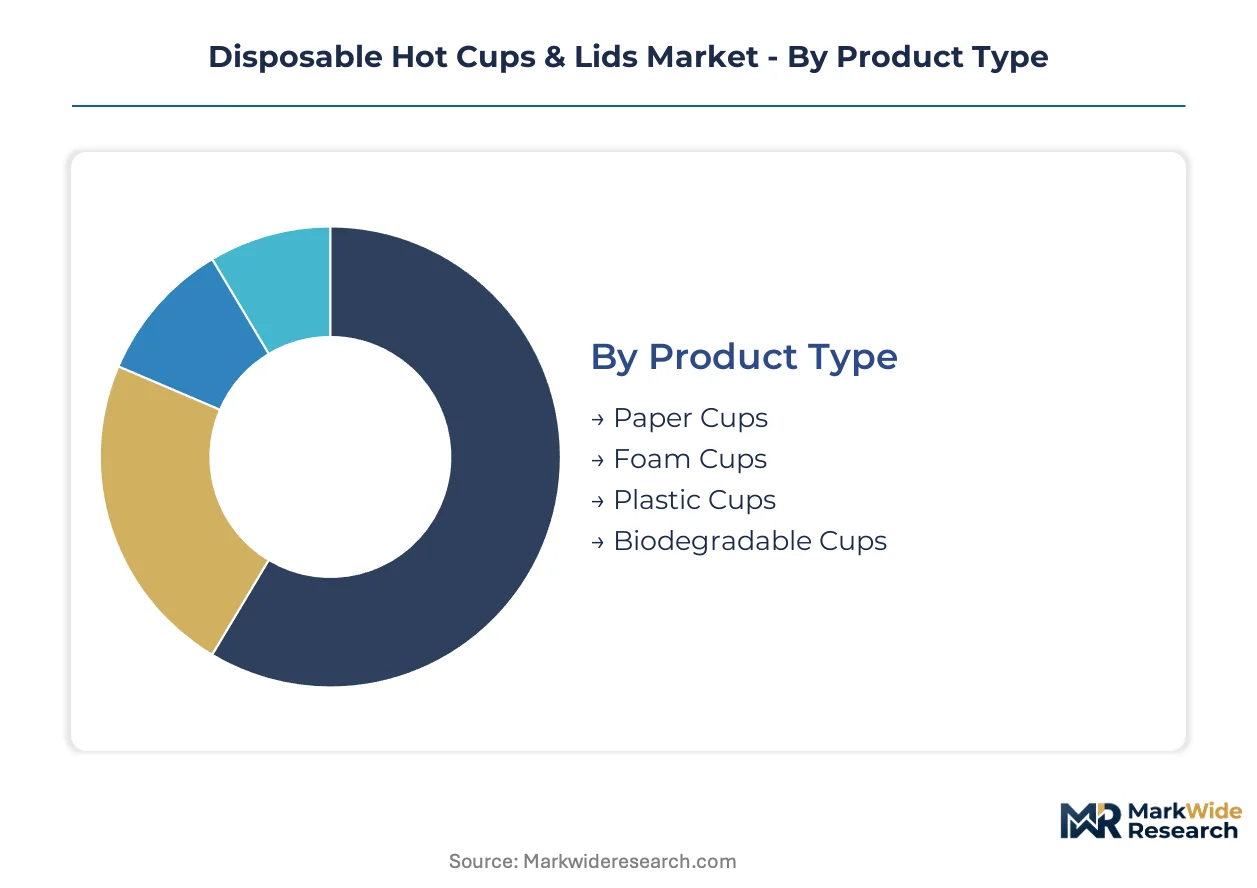
Product differentiation in disposable hot cups and lids hinges on thermal performance specifications, barrier coating chemistry, and end-of-life disposal pathways. Each segment category carries distinct margin profiles and regulatory exposure that reshape supplier positioning across foodservice channels.
Product Type:
Customization intensity varies sharply across this category, from commodity-grade foam cups with minimal print options to fully bespoke biodegradable formats with embedded traceability codes.
- Paper Cups:Single-wall and double-wall constructions with polyethylene or PLA barrier coatings dominate quick-service coffee applications. Demand concentrates in China's urban foodservice corridors where specialty chains require temperature-stable formats with integrated splash-resistant closures.
- Biodegradable Cups:Molded fiber and PLA-lined formulations achieve cost parity in premium channels through compostability certification. North American quick-service restaurants are scaling procurement to meet corporate sustainability targets, accelerating demand for matched lid systems.
- Foam Cups:Expanded polystyrene constructions retain thermal insulation advantages but face regulatory phase-outs across EU member states under the Single-Use Plastics Directive.
- Plastic Cups:Polypropylene and PET alternatives serve high-temperature tea applications where fiber lids struggle with snap-fit reliability above 80°C.
Leading the category by volume: Paper Cups. Expanding most quickly: Biodegradable Cups.
Size:
Volume concentration and margin capture diverge across this dimension, with mid-size formats anchoring coffee chain profitability while larger sizes serve fountain beverage and specialty tea segments.
- 12 oz:The workhorse format for specialty coffee chains balances portion control with perceived value. Seattle and London-based roasters are qualifying aqueous barrier coatings for this size bracket to support 90-day rollout timelines.
- 16 oz:Premium positioning commands highest margins through brand differentiation and custom print capabilities. Direct-store-delivery channels favor this size for shorter lead times and flexible minimum order quantities.
- 8 oz:Concentrated demand from European espresso cultures and Indian organized foodservice penetration in Mumbai and Bangalore.
- 20 oz:Fountain beverage and iced coffee applications in North American convenience stores drive intermittent demand with lower price per ounce economics.
Capturing majority margin pools: 12 oz and 16 oz formats. Gaining share fastest: 8 oz in emerging markets.
Material:
Substitution timelines and equipment lock-in risks define competitive positioning as converters navigate divergent regulatory phase-out schedules.
- Paperboard:Integrated mill assets at major North American suppliers dominate supply through compatibility with conventional hot-fill equipment and established recycling streams. Graphic Packaging International LLC leverages captive fiber supply to control cost volatility.
- PLA:Agricultural feedstock pricing and compostability certification requirements create entry barriers that fiber-based competitors with pre-validated aqueous coatings are exploiting to capture displaced polystyrene volume.
- Polystyrene:Thermoforming equipment lock-in in Germany and France generates stranded asset risk as retrofitting timelines lag behind EU enforcement milestones.
- Polypropylene:Snap-fit lid reliability in high-temperature applications sustains demand despite pressure from fiber-based alternatives in lower-temperature coffee service.
Supply concentrates in: Paperboard. Facing steepest displacement pressure: Polystyrene.
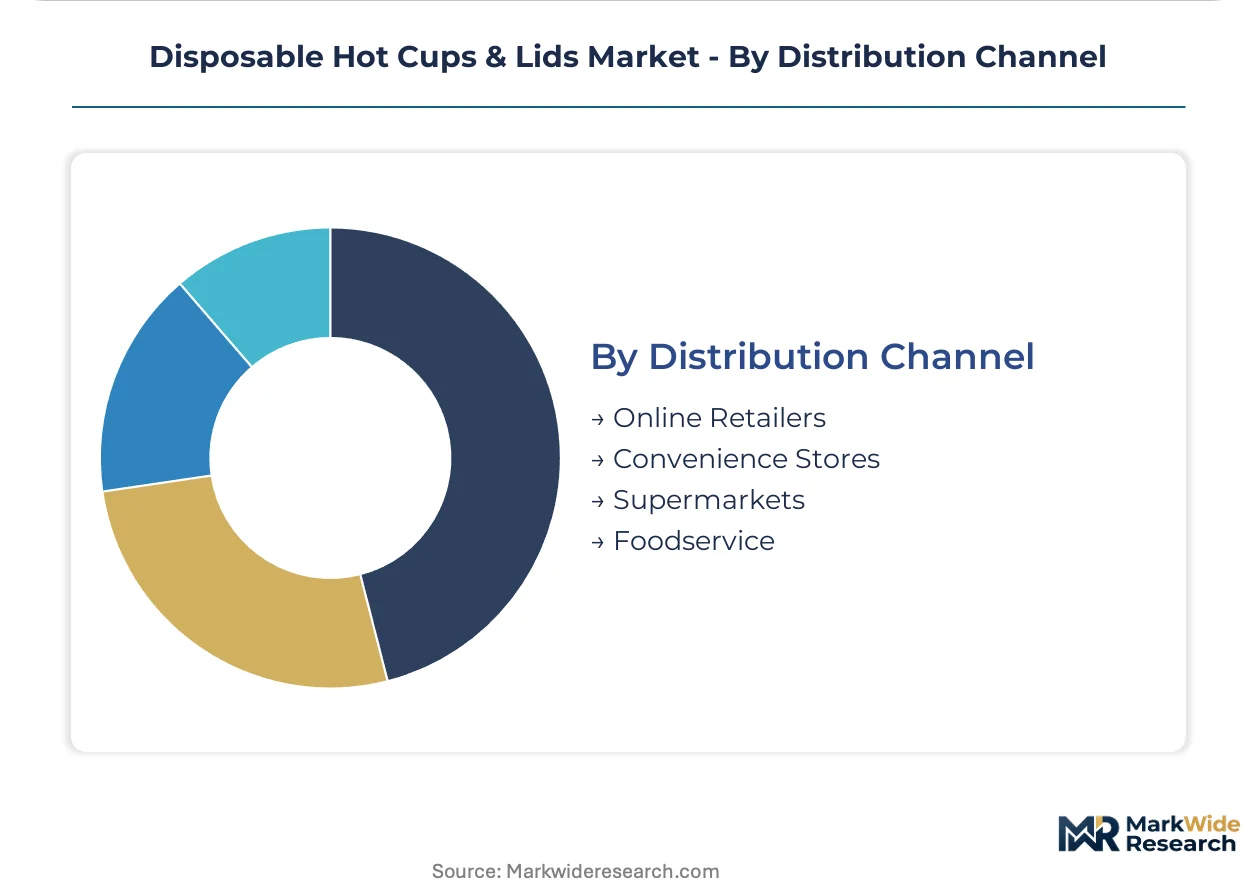
Distribution Channel:
Channel consolidation and disintermediation pressures are reshaping supplier relationships, with traceability requirements and custom print capabilities favoring direct manufacturer engagement over broadline intermediation.
- Foodservice:Multi-brand restaurant operators are compressing supplier rosters and extending contract durations. Chicago and Toronto broadline distributors are losing share to direct relationships as buyers prioritize lot traceability.
- Online Retailers:Coffee roasters bypassing traditional distribution to source custom-printed cups with shorter lead times. This channel favors suppliers with digital print capabilities and flexible minimum order quantities.
- Supermarkets:Private-label procurement concentrates volume with converters offering tiered pricing across premium, standard, and economy certification grades.
- Convenience Stores:Fountain beverage and grab-and-go coffee applications drive demand for 20 oz and 16 oz formats with standardized lid interchangeability.
Commanding highest growth trajectory: Online Retailers. Retaining volume dominance: Foodservice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate thermoforming equipment and barrier coating R&D, drawing foreign direct investment into compostable packaging conversion lines. Tax incentives in these zones accelerate material substitution timelines for export-oriented manufacturers.
United States
Quick-service restaurant chains in Seattle and Chicago are scaling aqueous barrier coating procurement to meet corporate sustainability targets. FDA food-contact substance regulations govern polyethylene and PLA liner approvals, extending qualification timelines for new formulations. Pacific Northwest coffee roasters bypass broadline distributors to source custom-printed 16 oz cups through direct manufacturer relationships.
Germany
Polystyrene-dependent thermoforming operations in Bavaria face stranded asset risk as retrofitting timelines lag behind EU Single-Use Plastics Directive enforcement milestones. REACH restrictions on intentionally added microplastics force reformulation of conventional barrier coatings by 2026. North Rhine-Westphalia converters with pre-validated aqueous coatings capture displaced volume from foam cup producers.
China
Specialty coffee chains in Shanghai and Beijing drive concentrated demand for temperature-stable 12 oz and 16 oz formats with integrated splash-resistant closures. GB standards for food-contact plastics and paper products impose testing protocols that influence export manufacturing decisions. Yangtze River Delta mill complexes supply integrated paperboard cup production with captive fiber sourcing.
India
Organized foodservice penetration in Mumbai and Bangalore represents underdeveloped demand for 8 oz and 12 oz single-wall formats with compostable certification. FSSAI regulations on food-contact materials create compliance barriers for imported PLA-lined products. Maharashtra-based quick-service chains are qualifying domestic molded fiber suppliers for tier-one city expansion.
United Kingdom
London-based coffee roasters are consolidating procurement around direct-store-delivery channels to secure shorter lead times and flexible minimum order quantities. The EU Packaging and Packaging Waste Regulation's extended producer responsibility schemes reshape cost allocation for UK converters post-Brexit. Southeast England distribution hubs handle cross-channel logistics for aqueous-coated cup exports to continental markets.
Disposable Hot Cups & Lids Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material technology and distribution channel vectors. The vendor base stratifies into three tiers: integrated mill operators controlling captive fiber supply, specialized thermoforming houses with equipment flexibility, and regional converters serving local foodservice accounts. Two dominant competitive moves are reshaping positioning: backward integration into barrier coating chemistry and direct-to-roaster distribution partnerships that disintermediate broadline distributors.
Within the integrated mill tier, Graphic Packaging International LLC and Huhtamaki Oyj exemplify archetypes of fiber-based supply chain control. Dart Container Corporation represents the thermoforming heritage segment navigating material substitution timelines. These three companies anchor distinct strategic positions without overlapping capability claims.
| Leading Market Players |
|---|
| Pactiv LLC |
| Sabert Corporation |
| Dart Container Corporation |
| Tair Chu Enterprise Co., Ltd. |
| Michael Procos S.A. |
| Berry Global Group, Inc. |
| Genpak, LLC |
| Graphic Packaging International LLC |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
Barrier coating resin costs transmit directly from fossil fuel and agricultural feedstock markets into three-tier pricing structures across premium, standard, and economy levels. Polyethylene and PLA price volatility squeezes double-wall insulated cup margins while aqueous coating investments command procurement premiums from sustainability-focused buyers.
Pricing Analysis
Lead-time-driven pricing separates direct-manufacturer relationships from broadline distributor channels, with Pacific Northwest coffee roasters paying premiums for sub-90-day custom print deliveries. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with compostable PLA-lined formats commanding top positioning. Cost compression in standard-grade paperboard is intensifying because integrated mill operators leverage captive fiber supply. Quick-service restaurant chains exhibit highest price sensitivity through consolidated procurement rosters, while specialty coffee roasters show lowest sensitivity for traceability-assured direct sourcing.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta mill complexes that anchor global paperboard cup substrate supply. Manufacturing gravity draws from China, the United States, and Germany for thermoforming equipment and barrier coating R&D. Raw material dependencies rest on wood pulp, PE resin, and PLA feedstock from corn starch. Tariff exposure on Chinese-manufactured substrates generates supply chain risk for North American converters. Distribution runs through direct-store-delivery channels that disintermediate Chicago and Toronto broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable hot cups and lids market sits in aqueous barrier coating transition, with water-based polyethylene-free formulations displacing conventional PE and PLA linings.
For Market Incumbents: Deepen backward integration into barrier coating chemistry to capture margin pools escaping to specialty chemical suppliers. Secure pre-validated aqueous coating formulations ahead of REACH microplastic restrictions. Add thermoforming flexibility in North American mill assets to offset stranded polystyrene equipment risk in EU member states. For New Entrants and Emerging Players: Enter via India's organized foodservice corridor in Mumbai and Bangalore, where FSSAI compliance barriers slow multinational penetration. Target 8 oz and 12 oz single-wall formats with domestic molded fiber supply qualification. Pursue direct-manufacturer relationships with Maharashtra-based quick-service chains expanding tier-one city footprints. For Investors and Strategic Acquirers: Aqueous coating validation announcements by Seattle and London coffee roasters are the leading indicator that recyclability-claim convergence is accelerating material substitution timelines. Five-to-ten-year viability favors converters with integrated mill positions and pre-certified compostable portfolios. Watch for German and Italian converters capturing displaced polystyrene volume as retrofitting timelines lag EU enforcement milestones.| Strategic Initiative | Industry Significance |
|---|---|
| Aqueous Barrier Coating Scale-Up | Water-based PE-free formulations enable recyclability claims without PLA price premiums. |
| Direct-Store-Delivery Channel Buildout | Custom-print capabilities with flexible MOQs capture share from broadline distributors. |
| Compostability Certification Investment | Multi-jurisdictional ASTM D6400 and EN 13432 portfolios secure cross-border market access. |
| Thermoforming Equipment Flexibility | Retrofit-ready lines navigate EU Single-Use Plastics Directive phase-out schedules. |
| Integrated Mill Capacity Expansion | Captive fiber supply at Yangtze River Delta complexes controls cost volatility exposure. |
Research Methodology
Independent corroboration across converter operations managers, quick-service restaurant procurement directors, and barrier coating R&D leads underwrites the qualitative findings. Primary interviews with foodservice distribution channel partners and sustainability compliance officers combined with secondary validation from FDA food-contact substance filings, EU Packaging and Packaging Waste Regulation documentation, and Chinese GB standards testing protocols. Bottom-up shipment data triangulates against top-down demand modeling from urban foodservice corridor expansion metrics.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include product type, size bracket, material chemistry, and distribution channel structure. CAGRs derive from weighted-average growth contributions by segment. Forecast inputs incorporate compostability certification adoption curves and thermoforming equipment retrofitting timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU enforcement acceleration or PLA feedstock price spikes. Forecasts reflect documented assumptions about material substitution velocity and regulatory compliance deadlines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Pizza Box Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Food Can Market
Food Packaging
Egg Packaging Market
Food Packaging
Edible Oil Packaging Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Bamboo Plate Market
Food Packaging
Global Fresh Meat Packaging Market
Food Packaging
Ambient Food Products Packaging Market