
 Food Packaging Market | 2026-2036
Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Market Intelligence
The integration of active and intelligent packaging technologies is tilting product development focus from passive containment to dynamic shelf-life extension. Amcor leverages its global manufacturing footprint to introduce smart-enabled flexible films across multiple food categories. Sealed Air specializes in vacuum skin packaging and shrink bags that incorporate freshness indicators for the meat and seafood industries. Mondi Group competes by offering a diverse portfolio that includes both high-barrier plastic films and sustainable paper-based alternatives.
Food packaging encompasses materials and containers designed to protect food from physical, chemical, and biological contamination during transport, storage, and retail. This includes multi-layer barrier films, often incorporating materials like ethylene vinyl alcohol (EVOH) or metalized films, to control oxygen and moisture transmission rates. While plastic remains the dominant material due to its versatility, paperboard is gaining share in dry goods applications. The ready-to-eat meals segment represents the fastest-growing application, demanding advanced tray and pouch solutions with retort capabilities.
Regulatory frameworks, including the US FDA's food contact material regulations and the European Food Safety Authority's (EFSA) migration testing protocols, govern material safety. In parallel, sustainability mandates such as the EU's Circular Economy Action Plan and national standards from India's FSSAI are pushing for recyclable and compostable material adoption. Converter and brand owner success now depends on navigating these divergent material safety and environmental compliance requirements across key markets.
Market Dynamics
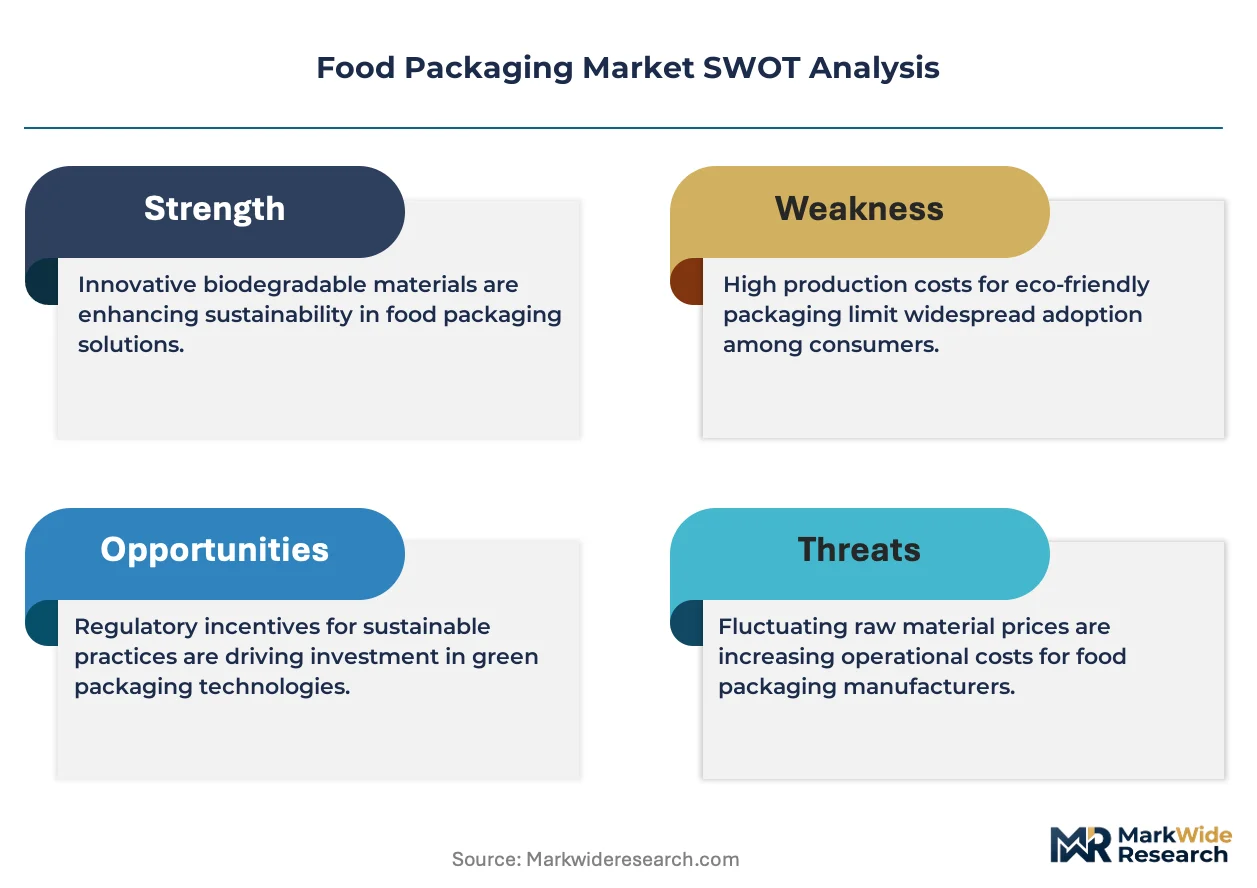
The fundamental tension between achieving advanced material performance and meeting stringent sustainability mandates is the central force shaping the food packaging market. Converters must reconcile the need for high-barrier properties, essential for shelf-life extension, with global regulatory pressure for recyclability and compostability.
Growth Catalysts
- Ready-to-Eat Meal Expansion:The proliferation of ready-to-eat meals, particularly in urban centers, requires advanced pouch and tray solutions with features like retort capability and microwave safety, pulling material innovation forward.
- Regulatory Mandates for Sustainability:Policies such as the EU's Circular Economy Action Plan are compelling brand owners to adopt packaging made from recycled content or biodegradable polymers, creating a direct demand signal for these materials.
- Organized Retail Growth in India:The rapid expansion of supermarkets and hypermarkets in India is increasing the consumption of pre-packaged foods, creating significant volume demand for standardized and protective packaging formats.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of petrochemical-based raw materials, such as polymer resins, create margin pressure for converters and introduce pricing uncertainty for brand owners.
- Performance Gaps in Sustainable Materials:Many current biodegradable and compostable polymers do not yet match the oxygen and moisture barrier properties of conventional multi-layer plastic films, limiting their use in sensitive applications.
- Divergent International Regulations:Navigating conflicting food contact safety standards, such as migration limits set by the US FDA versus those from Europe's EFSA, adds complexity and cost to global product launches.
Strategic Opportunities
- Active Packaging Technologies:Developing packaging with integrated oxygen scavengers or ethylene absorbers offers a clear path to extend the shelf life of fresh produce, directly addressing the food waste reduction imperative.
- Digitalization for Traceability:The integration of unique digital identifiers, like advanced QR codes or NFC tags, enables full supply chain traceability, a feature increasingly valued by consumers and regulators.
- Paper-based Barrier Solutions:Innovations in coating technologies for paper and paperboard are creating viable, recyclable alternatives to flexible plastic films for a range of dry and fatty food applications.
Industry Challenges
- Recycling Infrastructure Deficiencies:The lack of standardized, at-scale collection and sorting infrastructure for emerging flexible and multi-material packaging formats hinders the establishment of a truly circular economy.
- Capital Investment for Re-tooling:Shifting production from traditional plastics to alternative materials like molded fiber or compostable biopolymers requires significant capital expenditure on new machinery and processing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Market |
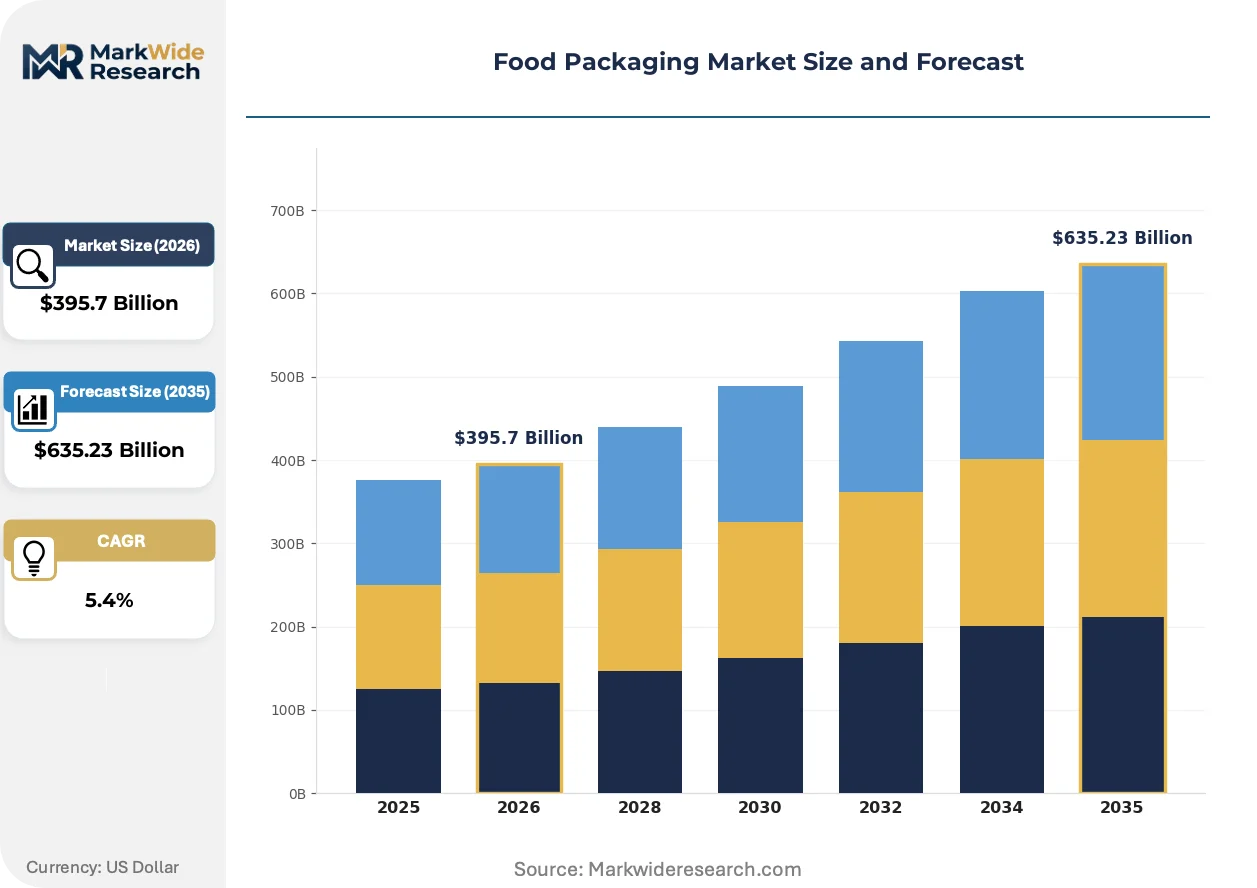
| Market Size in 2026 | $395.7 Billion |
| Market Size in 2035 | $635.23 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Paperboard, Glass, Aluminum, Biodegradable Polymers, Metalized Films Packaging Type: Flexible Packaging, Rigid Containers, Pouches, Trays, Bottles, Wraps Application: Beverages, Ready-to-Eat Meals, Dairy Products, Bakery, Meat & Seafood, Confectionery End User: Food Processing Units, Retail Chains, Foodservice Providers, Caterers, Restaurants, Institutional Kitchens |
| Companies Covered | Mondi Group, ProAmpac, Amcor, Huhtamaki Oyj, Constantia Flexibles, Sealed Air, Smurfit Westrock, International Paper, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Market Strategic Shifts & Innovations
Product development is pivoting from passive containment toward dynamic, intelligent systems. This evolution is driven by a convergence of consumer demand for transparency, regulatory pressure for waste reduction, and material science breakthroughs that enable new functionalities.
Monomaterial flexible films, engineered for enhanced recyclability, are designed to match the protective barrier properties of complex multi-layer structures. Food and beverage CPGs are accelerating adoption of these materials for products like coffee and snacks to meet public sustainability commitments. This trend is collapsing the historical trade-off between high performance and circularity, forcing innovation across the polymer industry.
The European Union’s Packaging and Packaging Waste Regulation (PPWR) establishes aggressive targets for recycled content and material circularity. Its provisions compel converters to redesign packaging portfolios and secure reliable supplies of post-consumer recycled (PCR) resins. The fresh food and beverage segments are most impacted, spurring investment in advanced chemical recycling to produce food-grade materials.
Consumer insistence on verifiable data regarding product origin and freshness is driving the integration of smart packaging elements. On-pack features like QR codes connected to blockchain platforms are displacing static "best by" dates for high-value categories, including seafood and premium meats. This behavioral shift is most visible in Japan and Western Europe, where food safety and authenticity are primary purchasing drivers.
Food Packaging Market Segmentation
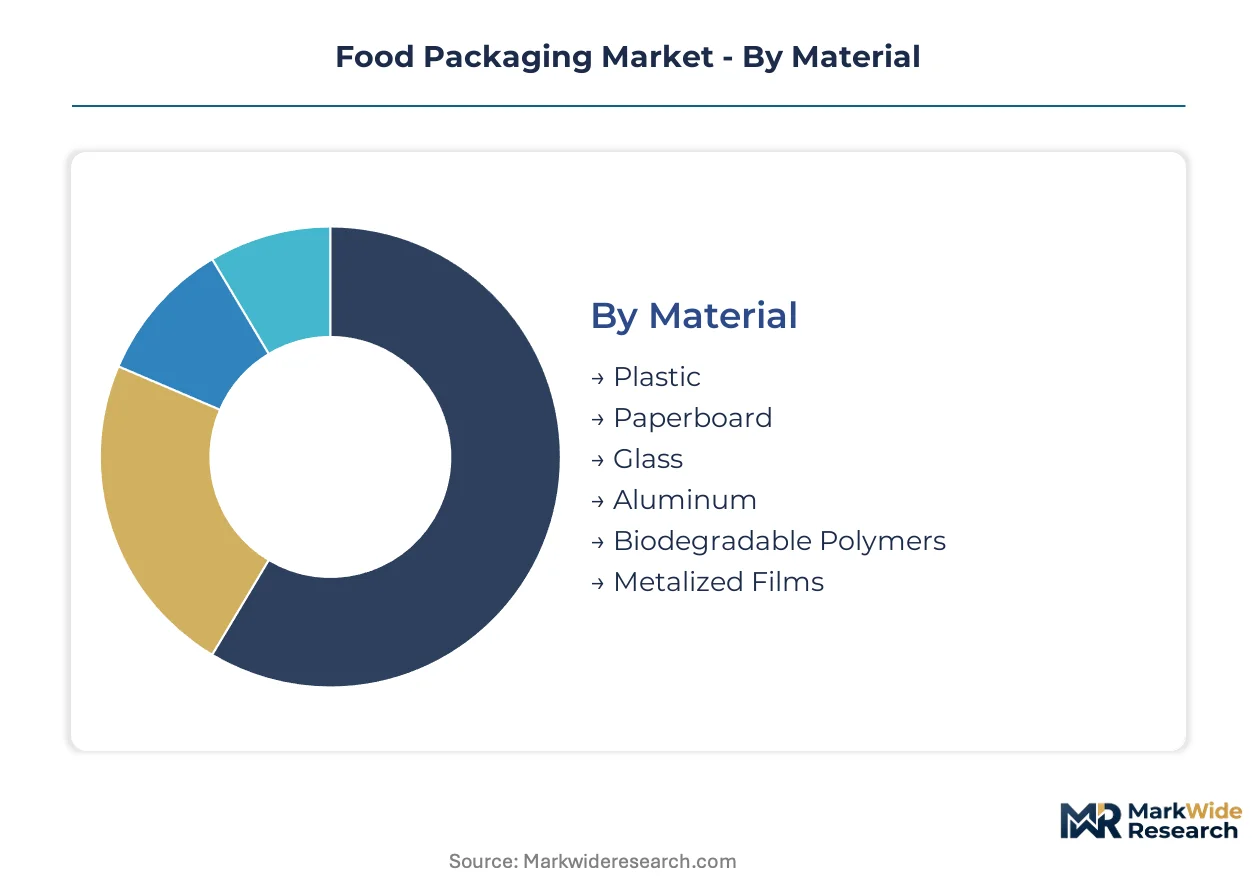
The Food Packaging Market's comprehensive segmentation reveals diverse material, format, application, and end-user requirements driving industry growth. Understanding these distinct segments allows manufacturers to tailor solutions for specific protection needs. This detailed breakdown highlights key innovation areas.
Material:
The material segment reflects a dynamic interplay between mature solutions and emerging, sustainable alternatives across various food packaging needs.
- Plastic:This versatile material, including PET, PP, and PE, offers excellent barrier properties, light weight, and cost-effectiveness for a wide array of food products. Demand concentrates in ready-to-eat meals and beverages due to its adaptability.
- Biodegradable Polymers:Comprising materials like PLA and PHA, these polymers offer environmentally friendly alternatives designed to break down naturally. Their adoption accelerates across Europe, driven by stringent regulatory mandates.
- Paperboard:Utilized for dry goods and frozen foods, paperboard offers a renewable and recyclable option, often with barrier coatings.
- Glass:Valued for its inertness and premium perception, glass is primarily used for beverages, sauces, and preserves.
- Aluminum:Lightweight and highly recyclable, aluminum foils and cans offer superior barrier performance for processed foods.
- Metalized Films:These films integrate a thin metal layer onto plastic substrates, enhancing barrier properties against light and moisture.
Plastic retains volume leadership; Biodegradable Polymers hold the steepest expansion curve.
Packaging Type:
Packaging type segmentation reveals varying cost structures and functional priorities, from economical flexible solutions to specialized rigid formats.
- Flexible Packaging:This category includes films, bags, and sachets, offering lightweight, customizable solutions with efficient material use. Its widespread application in snacks and confectionery reflects cost-efficiency.
- Pouches:Often multi-layered, pouches provide convenience, extended shelf life, and retort capabilities, especially for ready-to-eat meals. Their growth is pronounced in urban centers.
- Rigid Containers:These durable containers, including tubs and jars, provide structural integrity and protection for dairy products and sauces.
- Trays:Predominantly used for fresh produce, meat, and ready meals, trays offer presentation and protection with sealing films.
- Bottles:Primarily glass or plastic, bottles are essential for beverages, oils, and dressings, ensuring secure containment.
- Wraps:Thin films, such as cling film, are used for primary and secondary packaging of fresh foods and bulk items.
Flexible Packaging dominates the market; Pouches are gaining share rapidly.
Application:
The application segment delineates packaging requirements based on the unique characteristics and preservation needs of diverse food categories.
- Ready-to-Eat Meals:This segment demands advanced tray and pouch solutions with features like microwaveability, retort capabilities, and extended shelf life. India's expanding organized retail sector drives significant demand.
- Meat & Seafood:Packaging for these products requires high-barrier properties to control oxygen and moisture, often employing vacuum skin packaging. Consumer demand for freshness indicators in Western Europe influences innovation.
- Beverages:This category relies on bottles, cartons, and cans that provide secure sealing and protection from light and oxygen.
- Dairy Products:Packaging for dairy, including cups, bottles, and pouches, focuses on hygiene, barrier properties, and cold chain compatibility.
- Bakery:Bread, pastries, and cakes utilize flexible films and paperboard boxes, balancing moisture control with product visibility.
- Confectionery:This segment uses various flexible films, wrappers, and rigid boxes to protect delicate products and enhance shelf appeal.
Ready-to-Eat Meals represent the fastest-growing application; Beverages maintain significant volume.
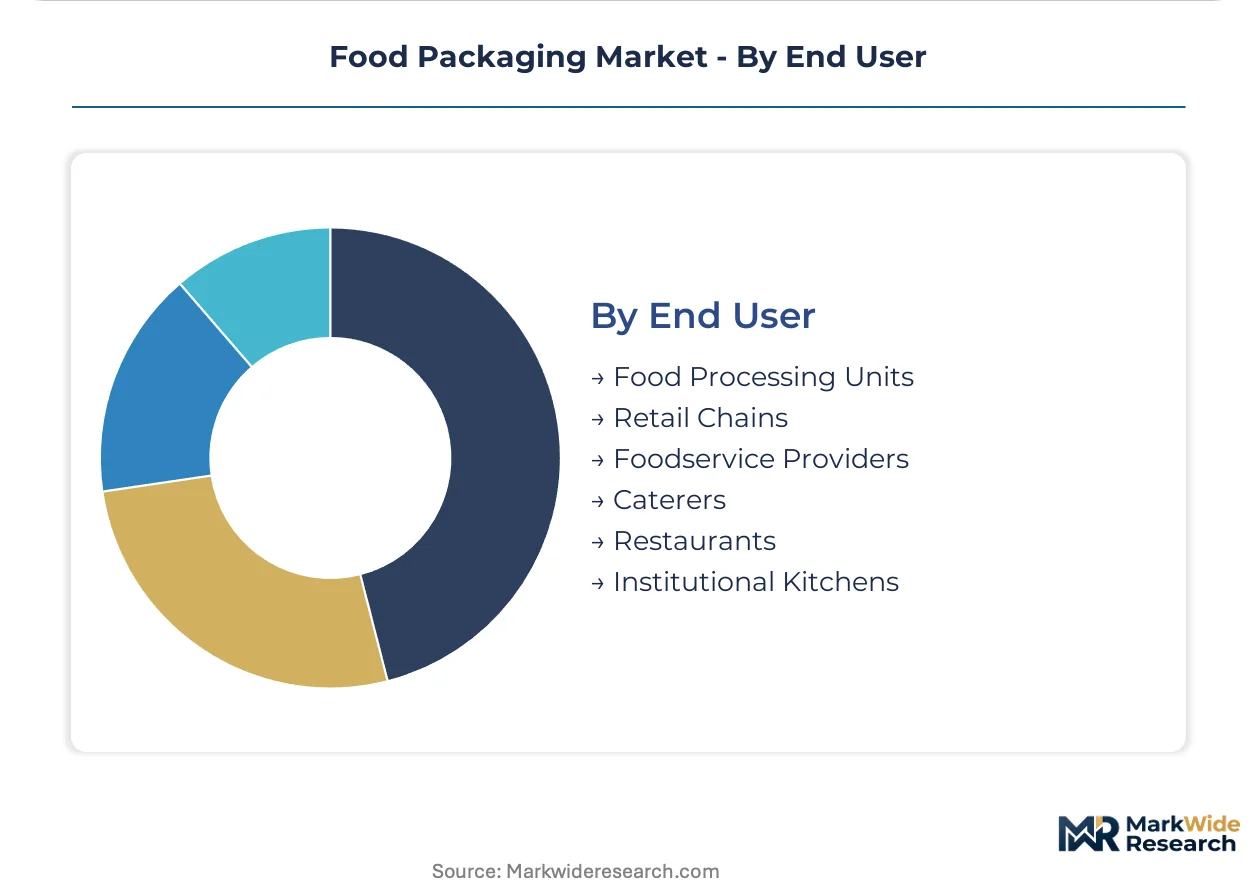
End User:
The end-user segment highlights distinct purchasing patterns and volume requirements across the food supply chain, influencing packaging design.
- Food Processing Units:These large-scale operations require high-volume, standardized packaging solutions for raw ingredients and processed foods, focusing on efficiency. Their demand for bulk packaging influences material choices.
- Retail Chains:Supermarkets and hypermarkets demand consumer-ready packaging that offers shelf appeal, product information, and ease of handling. The expansion of organized retail in India drives substantial volume.
- Foodservice Providers:This segment includes institutions and catering services requiring bulk and portion-controlled packaging for prepared meals.
- Caterers:Caterers utilize specialized packaging for transport and presentation of prepared meals, prioritizing temperature retention and aesthetics.
- Restaurants:Restaurants use packaging for takeout and delivery, focusing on heat retention, leak prevention, and brand presentation.
- Institutional Kitchens:Hospitals, schools, and corporate cafeterias require durable, safe, and often portion-controlled packaging for large-scale meal distribution.
Food Processing Units drive the largest volumes; Retail Chains are expanding their packaging diversity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration in food packaging often centers on countries with large, evolving consumer bases and robust food processing industries. These regions demonstrate significant demand for both convenience-driven and sustainable packaging solutions. Global manufacturers strategically align with local market needs, adapting to diverse regulatory landscapes.
United States
Consumer demand for convenience foods and e-commerce drives innovation in flexible and protective packaging. The US FDA's food contact material regulations ensure product safety and material compliance. California's initiatives, like plastic reduction targets, influence sustainable packaging development nationwide.
China
Expansion of modern retail channels and a rising middle class propel the need for packaged food and beverage options. China's GB standards for food packaging materials establish strict safety and quality benchmarks. The Yangtze River Delta region sees significant investment in advanced packaging manufacturing capabilities.
Germany
Sustainability mandates and a strong focus on circular economy principles shape packaging material choices. The EU's Circular Economy Action Plan compels manufacturers to adopt recyclable and recycled content solutions. Bavaria's food processing clusters actively integrate paper-based and compostable packaging innovations.
India
Rapid urbanization and the growth of organized retail are increasing the consumption of packaged and ready-to-eat meals. The FSSAI mandates specific standards for food packaging, ensuring hygiene and consumer safety. The Delhi-NCR region experiences high demand for innovative, portion-controlled packaging formats.
Brazil
Shifting consumer lifestyles and a large domestic market boost the demand for processed and convenience foods. ANVISA regulations govern food contact materials, influencing packaging design and material selection. São Paulo's extensive food industry drives the adoption of advanced barrier films and flexible packaging solutions.
Food Packaging Market Key Industry Players
Channel-controlling players compete with product-specialist players in the food packaging market, creating a dynamic competitive environment. The market exhibits a tiered structure, from large integrated material producers to niche solution providers. Strategic archetypes include global diversified packaging giants, regional flexible packaging converters, and material science innovators. Portfolio diversification and strategic partnerships are dominant competitive moves among established firms.
Among the global diversified packaging giants, Amcor and Mondi Group exemplify broad material and format capabilities across multiple food categories. Amcor, with its extensive manufacturing footprint, represents a scale-driven approach to flexible films and specialized packaging. Mondi Group occupies a position as a provider of both high-barrier plastic films and sustainable paper-based alternatives, showcasing material versatility. Sealed Air, on the other hand, sits within the specialized solutions archetype, focusing on vacuum skin packaging and freshness indicators for specific applications like meat and seafood.
| Leading Market Players |
|---|
| Mondi Group |
| ProAmpac |
| Amcor |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Sealed Air |
| Smurfit Westrock |
| International Paper |
| Tetra Pak |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's extensive packaging manufacturing capacity significantly influences pricing power across Asian markets, particularly for flexible films. This localized capacity dynamic reduces lead times and logistics costs, directly impacting the final price points for regional brand owners.
Pricing Analysis
Cost-plus contracts, often indexed to petrochemical resin prices, dominate pricing models for conventional plastic packaging. Price differentiation stems from barrier performance specifications and customization levels, reflecting specialized material blends. Pricing pressure stems from volatile raw material input costs, particularly for polymers, impacting converter margins. Retail chains and large food processing units exhibit the most price sensitivity, while niche segments requiring highly specialized barrier films are less sensitive.
Supply Chain Analysis
Upstream feedstock sourcing for polymer resins primarily originates from petrochemical hubs in the Middle East and North America. Geographic supply concentration for advanced packaging manufacturing exists in China, Germany, and the United States. Key raw material dependencies include polymer resins, paper pulp, and aluminum ingots. Commodity price volatility represents a significant structural risk across the supply chain. Downstream distribution typically runs through regional converters to brand owners and large food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires specialized expertise in sustainable material science and circular economy integration, creating a capability gap for many traditional players. Developing advanced recycling technologies and bio-based material formulations remains a critical skill shortage.
For Market Incumbents: Entrench existing market share by investing in monomaterial flexible film research and development. This addresses the regulatory threat posed by the EU's Packaging and Packaging Waste Regulation. Leverage established global manufacturing footprints to scale production of certified recycled content solutions, securing long-term supply agreements with major CPGs.
For New Entrants and Emerging Players: Niche applications for biodegradable polymers in Europe represent a penetrable entry point, particularly for fresh produce and ready-to-eat meals. Focus on developing compostable pouch and tray solutions that meet specific regional certification standards. A go-to-market strategy should emphasize material performance equivalence to traditional plastics, coupled with verifiable sustainability credentials.
For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-driven consolidation play because regulatory mandates are forcing portfolio restructuring. Target vertically integrated material science firms specializing in advanced barrier coatings for paperboard or chemical recycling technologies. The signal to watch is the widespread commercial adoption of food-grade recycled plastics across diverse product categories, indicating market readiness for circular solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Biopolymer Development | Addresses performance gaps in sustainable materials for sensitive food applications, enhancing product viability. |
| Chemical Recycling Infrastructure Investment | Enables the production of food-grade recycled content, meeting regulatory requirements and brand commitments. |
| Digital Traceability Platform Integration | Enhances supply chain transparency and consumer trust, particularly for high-value food categories. |
| Paper-based Barrier Coating Innovation | Offers recyclable alternatives to plastic films, expanding sustainable options for dry and fatty foods. |
| Global Manufacturing Footprint Optimization | Reduces logistics costs and improves responsiveness to regional demand shifts and regulatory changes. |
Research Approach
A standing panel of packaging engineers, material scientists, retail procurement managers, and regulatory compliance officers provided ongoing calibration for market sizing and trend validation. This primary interview data was triangulated with extensive secondary research from sources including EU Circular Economy Action Plan documents, US FDA food contact regulations, and FSSAI standards. Both bottom-up and top-down approaches were employed to ensure robust market estimation.
Scenario-bracketing framed the market projections across the analysis window, considering various economic and regulatory trajectories. The analytical framework modeled segmentation dimensions including material type, packaging format, application, and end-user, alongside regional regulatory clusters. Compound Annual Growth Rates were derived from historical data analysis and expert consensus, with petrochemical price forecasts and consumer spending on ready-to-eat meals serving as key inputs.
Macroeconomic conditions sit as an overlay; deviation in energy prices and global trade policies would shift the trajectory of material costs and market growth. Forecasts reflect assumptions documented through stakeholder consultations and secondary research, acknowledging potential impacts from future regulatory changes. Cross-checking against external market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Desserts Packaging Market
Food Packaging
On-The-Go Breakfast Packaging Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Canada Disposable Tableware Market
Food Packaging
Middle East and Africa Canned Food Packaging Market
Food Packaging
Egg Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Insulated Food and Beverage Carriers Market
Food Packaging
Oven Bags and Pouches Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Cake Box Market