
 Chocolate Wrapping Films Market | 2026-2036
Chocolate Wrapping Films Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate Wrapping Films Market Analysis
ISO 22000 certification is rotating as the baseline qualification for suppliers serving multinational confectionery accounts. Amcor Plc leverages its global food safety credentials to anchor long-term contracts with premium chocolate houses. Mondi Group sustains competitive position through integrated kraft paper and film operations across Central European production hubs. Constantia Flexibles specializes in cold-seal lacquer technologies that protect temperature-sensitive cocoa formulations during high-speed wrapping.
Chocolate wrapping films are multilayer polymeric laminates, typically incorporating aluminum oxide-coated polyethylene or oriented polypropylene with moisture vapor transmission rates below 0.5 g/m²/day, engineered to prevent fat bloom and odor migration in temperate supply chains. Polypropylene variants dominate volume due to balanced stiffness and seal integrity at 30-50 micron gauges. Digital printing technology is displacing gravure in short-run seasonal campaigns, while flexographic systems retain economics for year-round stock-keeping units with repeat artwork.
FDA food contact notifications govern substrate chemistry for US-bound chocolate exports, while EU REACH restrictions on phthalate plasticizers and the Packaging and Packaging Waste Regulation mandate recyclability disclosures across European supply chains. BIS certification requirements for imported flexible packaging materials create compliance gates for suppliers targeting India's expanding confectionery sector. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material recyclability targets as these reshape specification sheets and capital allocation priorities.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing a substrate transition from multilayer laminates toward mono-material recyclable films, compressing R&D timelines and rewiring supplier qualification protocols across European chocolate manufacturing clusters.
Growth Catalysts
- High-barrier sustainable films:Premium confectionery houses in Switzerland and Belgium are specifying aluminum oxide-coated polyethylene with sub-0.5 g/m²/day moisture vapor transmission rates to extend shelf life without compromising recyclability credentials.
- Digital printing adoption:Short-run seasonal campaigns are migrating from gravure to digital systems, enabling faster artwork turnaround for limited-edition chocolate releases.
- ISO 22000 certification mandates:Multinational confectionery accounts now require baseline food safety credentials, filtering supplier pools and anchoring long-term contract structures.
Market Restraints
- Aluminum oxide coating cost volatility:Vacuum deposition equipment and ceramic target materials carry capital-intensive production economics that constrain mid-tier film converters.
- German supply concentration:Critical cold-seal lacquer formulation expertise clusters around Central European production hubs, creating single-source vulnerability for temperature-sensitive cocoa wrapping applications.
- REACH phthalate restrictions:ECHA limitations on plasticizer chemistry force reformulation cycles that extend qualification timelines by 12-18 months for EU-bound exports.
Strategic Opportunities
- India confectionery expansion:BIS certification requirements for imported flexible packaging create compliance gates that early-mover suppliers can leverage to capture share in the subcontinent's premium chocolate segment.
- Mono-material recyclability tailwinds:Extended producer responsibility frameworks in Germany and France are mandating recyclability disclosures that favor integrated kraft paper and film operations.
- Cold-seal flexographic convergence:High-speed wrapping lines are combining temperature-sensitive seal technologies with water-based ink systems to protect cocoa fat bloom integrity at line speeds above 800 packages per minute.
Industry Challenges
- Multilayer delamination expertise:Separating oriented polypropylene from polyethylene tie layers without contaminating recycle streams requires polymer science capabilities scarce outside established European film houses.
- FDA notification timelines:Food contact notifications for substrate chemistry changes average 180-240 days, compressing product development windows for US-bound chocolate exports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate Wrapping Films Market |
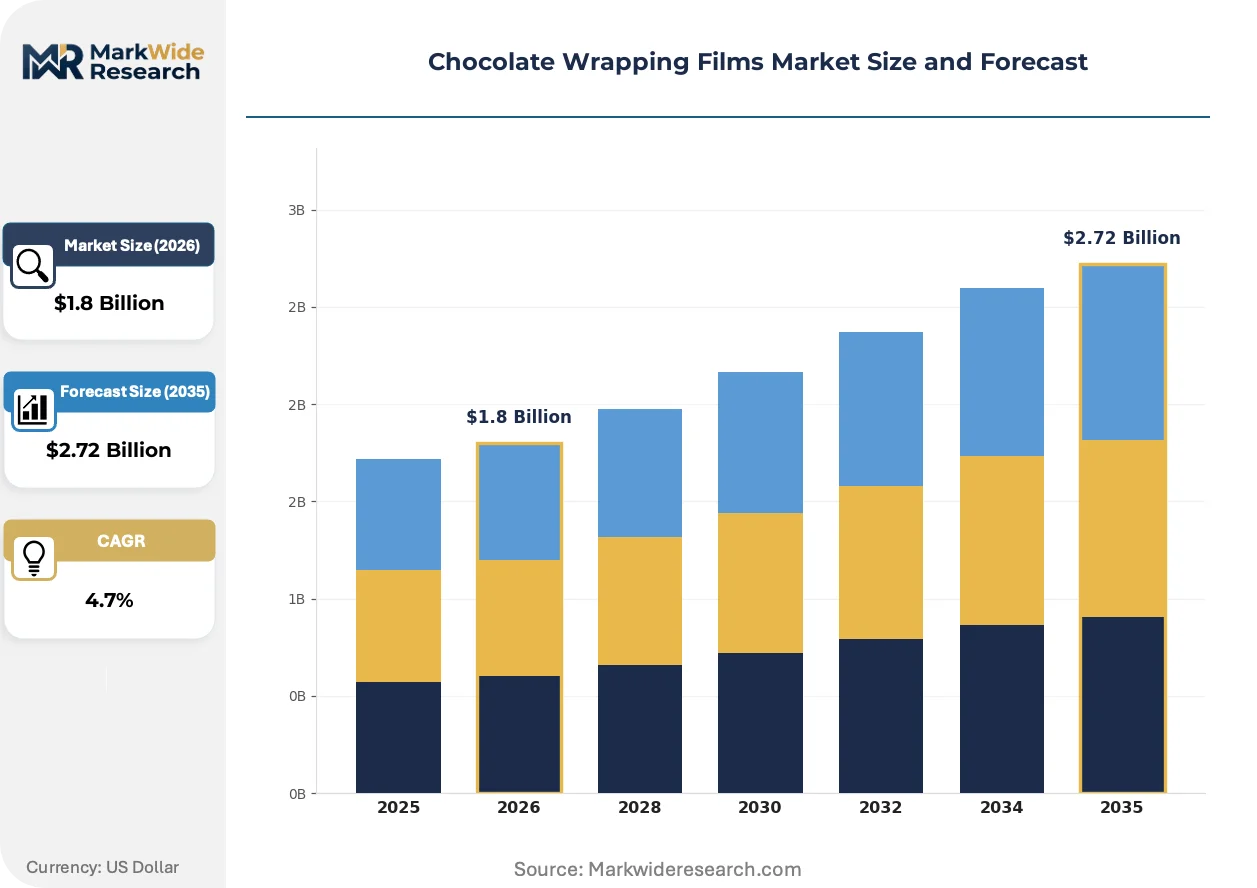
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, BOPP, PVC Film Thickness: 30 microns, 50 microns, 70 microns, 100 microns Printing Technology: Flexographic, Gravure, Digital, Offset End User: Confectionery Manufacturers, Retailers, Food Service, Others |
| Companies Covered | Amcor Plc, Mondi Group, Multifilm Packaging Corporation, Taghleef Industries Group, Innovia Films, Uflex Ltd., Polysack Ltd., Constantia Flexibles, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate Wrapping Films Market Emerging Trajectories
Active barrier coating technologies and digital production workflows are compressing the traditional film-to-package value chain, while regulatory recyclability mandates are redefining material specification standards across temperate supply chains.
Atomic layer deposition of aluminum oxide onto oriented polypropylene substrates is replacing conventional metallization for premium chocolate applications requiring fat bloom protection and optical clarity. Swiss and Belgian luxury confectionery houses are specifying these coatings for 30-50 micron gauge structures. This nanoscale barrier technology is miniaturizing the functional layer thickness while maintaining sub-0.5 g/m²/day moisture vapor transmission performance.
REACH restrictions on phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are mandating mono-material construction and recyclability disclosures across European supply chains. Film converters are reformulating sealant layers and eliminating polyamide tie layers to achieve single-polymer identification codes. Premium chocolate segments in Germany and Switzerland are responding with accelerated qualification timelines for polyethylene-only laminates.
Specification-driven procurement is consolidating around food safety certification tiers rather than unit cost minimization. Multinational confectionery accounts are unbundling artwork services from substrate supply and directly contracting digital print providers for seasonal campaigns. This pattern is most visible in Western Europe where ISO 22000 credentials now gate entry to tier-one supplier lists.
Chocolate Wrapping Films Market Segmentation
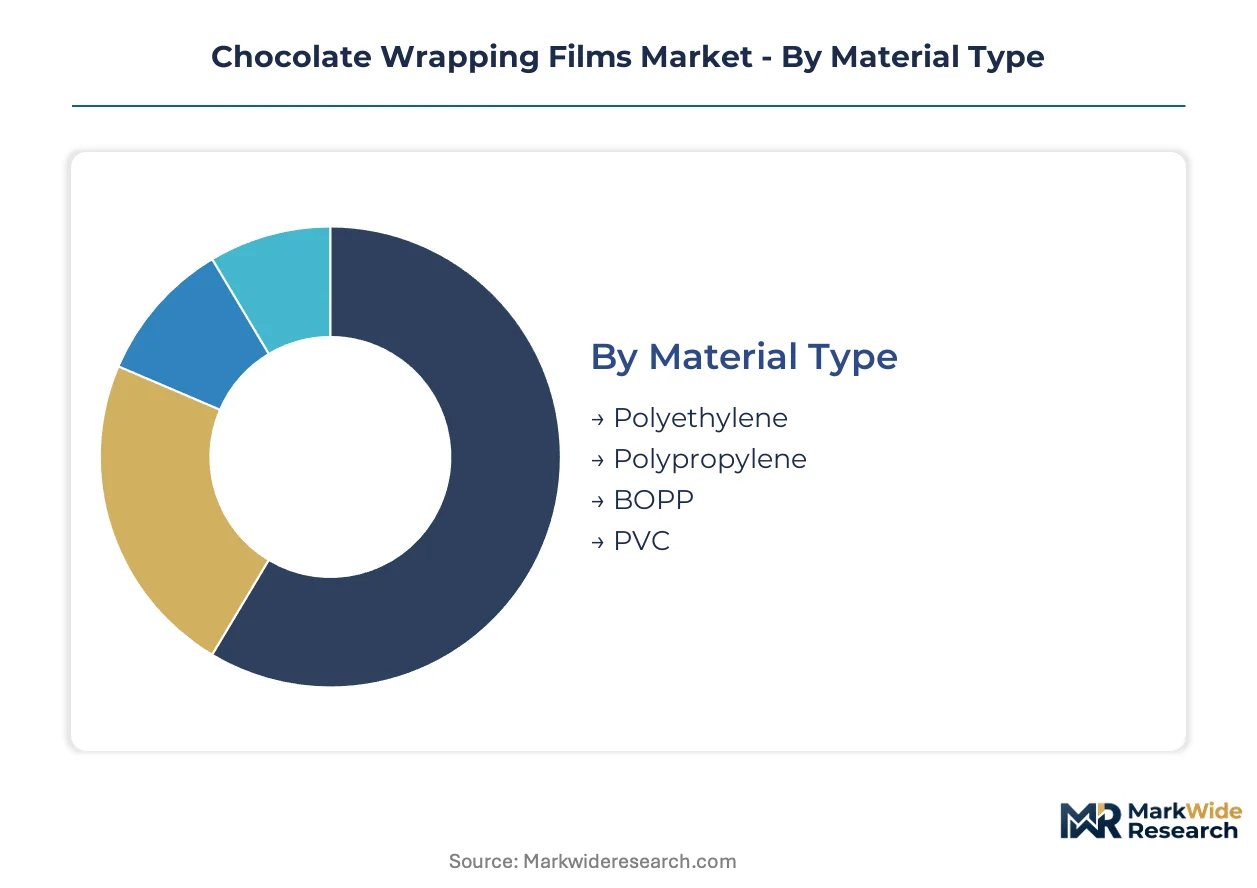
Segmentation in chocolate wrapping films reveals how material science, printing economics, and end-use requirements fragment procurement decisions across the value chain. Film converters must align gauge specifications with barrier performance needs while balancing digital agility against gravure unit economics.
Material Type:
Margin pools concentrate in high-barrier coated substrates where aluminum oxide deposition commands premium pricing over commodity polyolefins.
- Polyethylene:Aluminum oxide-coated variants achieve sub-0.5 g/m²/day moisture vapor transmission rates critical for fat bloom prevention in Swiss premium chocolate houses. Recyclability credentials under EU Packaging and Packaging Waste Regulation are accelerating mono-material polyethylene specifications across German manufacturing clusters.
- Polypropylene:Oriented polypropylene dominates volume throughput due to balanced stiffness and seal integrity at 30-50 micron gauges. Belgian confectionery accounts specify biaxially oriented structures for high-speed wrapping lines exceeding 800 packages per minute.
- BOPP:Biaxial orientation delivers optical clarity and dimensional stability for luxury chocolate presentation layers.
- PVC:Phthalate plasticizer restrictions under ECHA REACH have compressed PVC adoption to niche pharmaceutical-adjacent confectionery applications.
The dominant share belongs to polypropylene, while polyethylene is closing the gap fastest as recyclability mandates reshape specification sheets.
Film Thickness:
Cost tier stratification separates premium confectionery protection from economy chocolate overwrapping applications.
- 30 microns:Ultra-thin gauges serve single-serve chocolate portions where material minimization meets barrier requirements. Swiss luxury houses deploy atomic layer deposition on 30-micron oriented polypropylene to maintain optical clarity while achieving metallization-grade fat bloom protection.
- 50 microns:Mid-range structures balance stiffness for form-fill-seal automation with sufficient barrier for temperate supply chain distribution. German chocolate manufacturing clusters specify 50-micron polyethylene laminates for year-round stock-keeping units with extended shelf-life protocols.
- 70 microns:Heavy-duty gauges support block chocolate and seasonal gift packaging requiring puncture resistance.
- 100 microns:Maximum protection structures serve export-bound chocolate with extended logistics timelines and humidity exposure.
50-micron specifications command the largest volume commitment, though 30-micron variants are expanding most quickly as deposition technologies thin functional barrier layers.
Printing Technology:
Application-driven procurement separates high-volume brand equity maintenance from agile seasonal campaign execution.
- Flexographic:Water-based ink systems dominate year-round production with repeat artwork economics. Belgian and German converters combine flexographic printing with cold-seal lacquer technologies to protect cocoa fat bloom integrity at accelerated line speeds.
- Digital:Short-run seasonal campaigns are migrating from gravure to digital workflows for limited-edition chocolate releases. Swiss premium houses unbundle artwork services from substrate supply and contract digital print providers directly for Valentine's and Easter collections.
- Gravure:Long-run efficiency retains economics for flagship brand packaging with stable annual volumes.
- Offset:Lithographic transfer serves secondary chocolate packaging and point-of-sale display applications.
Flexographic systems retain the dominant installed base, while digital is gaining share fastest as campaign cycle compression rewards artwork agility.
End User:
Customer type determines specification stringency, with food safety certification tiers filtering supplier access across account categories.
- Confectionery Manufacturers:Multinational accounts mandate ISO 22000 certification as baseline qualification, anchoring long-term contract structures with integrated film converters. Swiss and Belgian chocolate houses specify aluminum oxide-coated structures with documented moisture vapor transmission performance for premium product lines.
- Retailers:Private-label chocolate programs prioritize mono-material recyclability to meet extended producer responsibility disclosures in Germany and France. Retail procurement teams are consolidating supplier pools around converters with integrated kraft paper and film operations.
- Food Service:Institutional chocolate portions require cost-optimized overwrapping with basic moisture protection.
- Others:Specialty applications include pharmaceutical chocolate coatings and nutraceutical delivery formats.
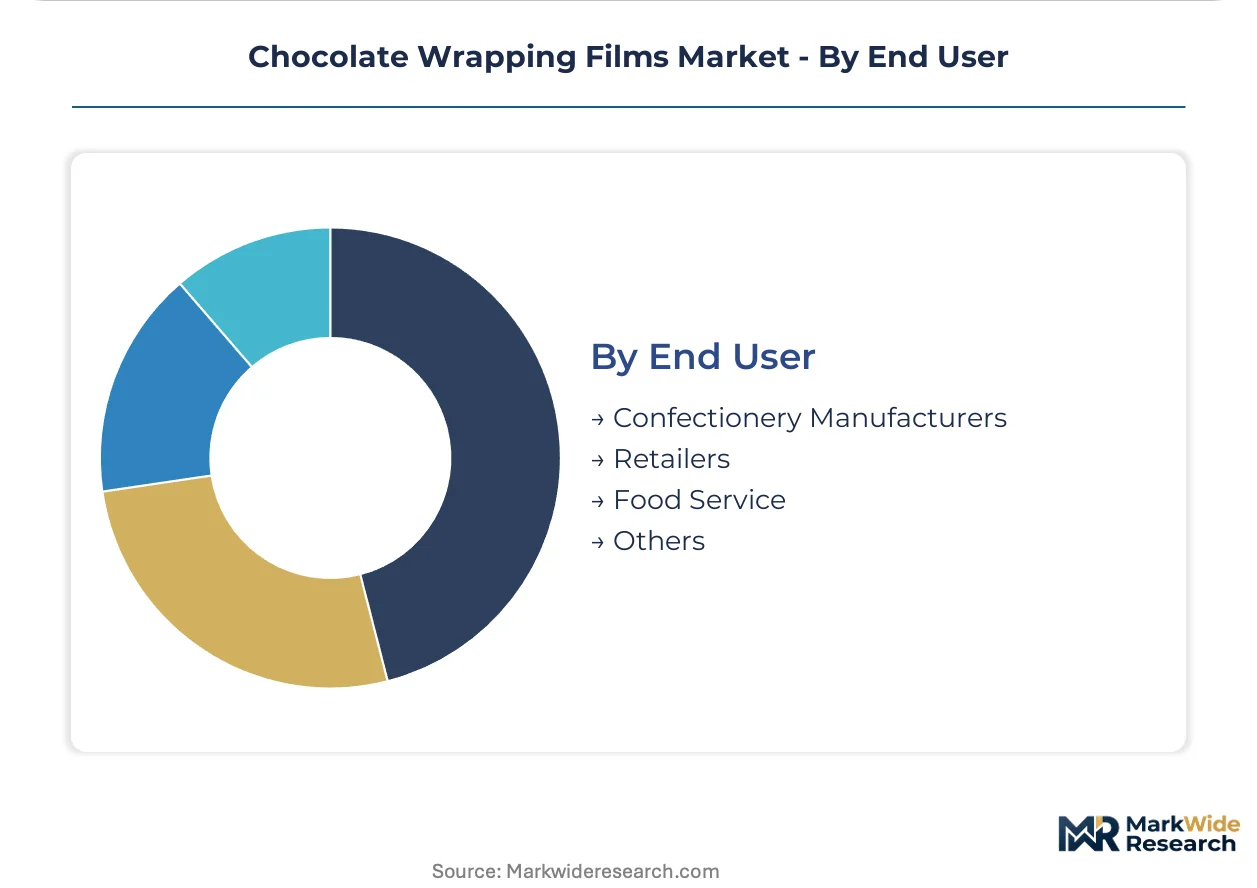
Confectionery manufacturers represent the dominant procurement volume, while retailer private-label programs are climbing the fastest as sustainability specifications reshape sourcing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Western Europe's dominance in chocolate wrapping film distribution, connecting German and Swiss confectionery clusters to global cocoa supply chains.
Germany
Cologne and Hamburg manufacturing clusters drive specification-intensive procurement for high-barrier mono-material films. The EU Packaging and Packaging Waste Regulation mandates recyclability disclosures that accelerate polyethylene-only laminate qualifications. Bavarian film converters are consolidating cold-seal lacquer expertise to serve temperature-sensitive cocoa formulations at line speeds exceeding 800 packages per minute.
Switzerland
Swiss luxury chocolate houses in Vevey and Zurich specify aluminum oxide-coated structures with sub-0.5 g/m²/day moisture vapor transmission rates. Swissmedic oversight of food contact materials aligns with EU REACH restrictions on phthalate plasticizers. Geneva-based procurement teams unbundle artwork services from substrate supply, contracting digital print providers directly for seasonal collections.
Belgium
Brussels and Antwerp chocolate manufacturing clusters anchor demand for biaxially oriented polypropylene at 30-50 micron gauges. The EU Green Deal's extended producer responsibility frameworks pressure converters toward integrated kraft paper and film operations. Flemish production hubs specialize in flexographic systems with water-based inks for year-round stock-keeping units.
India
Maharashtra and Gujarat confectionery expansion drives imported flexible packaging demand for premium chocolate segments. BIS certification requirements create compliance gates that filter supplier pools for multinational accounts. Mumbai-based chocolate manufacturers are accelerating ISO 22000 mandates as baseline qualification for film converter partnerships.
United States
New Jersey and Pennsylvania distribution corridors handle FDA-governed substrate chemistry for chocolate exports. FDA food contact notification timelines averaging 180-240 days compress product development windows for reformulated sealant layers. Chicago-area confectionery accounts are migrating short-run seasonal campaigns from gravure to digital production workflows.
Chocolate Wrapping Films Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers and substrate technology vectors. The vendor base clusters around three concentration nodes: integrated multinational packaging houses with global food safety credentials, regional film converters with cold-seal lacquer expertise, and specialty substrate developers with barrier coating capabilities. Strategic archetypes include scale-driven laminators, certification-anchored contract holders, and agile digital print integrators. Competitive moves concentrate on backward integration into polymer resin operations and geographic expansion into India's BIS-regulated import environment.
Within the integrated multinational tier, Amcor Plc and Mondi Group exemplify archetypes of certification-anchored market presence. Constantia Flexibles occupies a position among cold-seal technology specialists serving temperature-sensitive applications. These three entities represent distinct competitive vectors: global contract anchoring, integrated kraft-film operations, and lacquer-based seal expertise.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Multifilm Packaging Corporation |
| Taghleef Industries Group |
| Innovia Films |
| Uflex Ltd. |
| Polysack Ltd. |
| Constantia Flexibles |
| Berry Global Inc. |
| Others |
Supply Flow & Price Mechanics
Atomic layer deposition of aluminum oxide onto oriented polypropylene is displacing conventional metallization across European chocolate manufacturing clusters, simultaneously concentrating vacuum deposition equipment ownership in German and Swiss production hubs while compressing pricing premiums for barrier-grade substrates. This substitution dynamic rewires procurement economics as buyers trade off optical clarity against recyclability credentials under EU Packaging and Packaging Waste Regulation mandates.
Pricing Analysis
Volume-discount tiering structures separate multinational confectionery accounts from mid-tier converters, with ISO 22000 certification and aluminum oxide deposition capabilities commanding premium positioning over commodity polyolefin suppliers. Price differentiation rests on barrier performance documentation and cold-seal lacquer formulation expertise, with Swiss and Belgian luxury houses least sensitive to unit cost and private-label retailers most responsive to mono-material recyclability premiums. Cost compression in standard-grade polyethylene laminates is intensifying as German film converters consolidate capacity and extend payment terms to defend share.
Supply Chain Analysis
Inventory lead times for aluminum oxide-coated substrates stretch longer than commodity polyolefin alternatives due to vacuum deposition equipment constraints concentrated in Germany, Switzerland, and Belgium. Raw material flows draw from Saudi petrochemical feedstock, Austrian kraft paper operations, and Italian printing ink formulators, creating tariff exposure at multiple upstream nodes. Distribution runs through Rotterdam container terminals into Cologne, Vevey, and Antwerp manufacturing clusters, with single-source vulnerability in cold-seal lacquer chemistry clustering around Bavarian specialty chemical houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across this market as regulatory recyclability mandates splinter procurement requirements, with extended producer responsibility frameworks in Germany and France creating distinct specification tiers that niche specialists can exploit against integrated multinational incumbents.
For Market Incumbents: Secure backward integration into polymer resin operations to capture margin pools escaping to petrochemical suppliers, while anchoring long-term contracts through ISO 22000 certification investments that filter supplier pools for multinational confectionery accounts. Cold-seal lacquer formulation expertise represents a defendable moat against emerging Asian competitors targeting European premium segments. For New Entrants and Emerging Players: Differentiate on digital print integration for short-run seasonal campaigns, targeting Swiss and Belgian luxury chocolate houses that unbundle artwork services from substrate supply. India's BIS-regulated import environment offers the most penetrable geography, with Mumbai-based confectionery manufacturers accelerating food safety mandates that early movers can leverage through certification partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European film converters holding cold-seal lacquer expertise and established relationships with German manufacturing clusters. Five-to-ten year viability hinges on successful mono-material transition execution; the signal to watch is qualification timeline compression for polyethylene-only laminates as EU recyclability disclosures harden into procurement mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin | Captures upstream margin pools from Saudi petrochemical suppliers serving German converters. |
| Digital Print Capability Acquisition | Enables direct artwork contracting with Swiss luxury houses for seasonal campaign execution. |
| ISO 22000 Certification Investment | Gates entry to multinational confectionery supplier lists under tightening food safety protocols. |
| Mono-Material Laminate Qualification | Aligns substrate portfolios with EU Packaging and Packaging Waste Regulation recyclability mandates. |
| India Market Entry through BIS Partnership | Establishes compliance credentials for Maharashtra and Gujarat confectionery expansion demand. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with film converter plant managers, confectionery procurement leads, cold-seal lacquer formulators, and digital print operations heads; and secondary validation through EU REACH regulatory filings, BIS certification databases, customs trade records, and SEC disclosures from listed packaging multinationals. Bottom-up volume modeling triangulated against top-down market sizing across material type, thickness gauge, printing technology, and end-user segmentation dimensions.
Across the projection horizon, analytical frameworks modeled demand elasticity to regulatory shifts, substitution dynamics between aluminum oxide deposition and conventional metallization, and geographic expansion patterns into BIS-regulated import environments. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators and industry-specific inputs including vacuum deposition equipment capacity expansion and digital print adoption curves in seasonal campaign execution.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated India confectionery expansion would require recalibration. Forecasts reflect documented assumptions regarding mono-material qualification timelines and cold-seal lacquer supply concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Polystyrene Films Market
Poly film
Packaging Film Market
Poly film
Resealable Films Market
Poly film
Asia Pacific Plastic Packaging Film Market
Poly film
Polymer Waterproof Rolls Market
Poly film
Starch-Based Plastic Films Market
Poly film
High Density Polyethylene Film Market
Poly film
Polyolefin (POF) Shrink Film Market
Poly film
Craft Plastic Films Market
Poly film
Global Specialty Films Polymer Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
APET Film Market
Poly film
Polytetrafluoroethylene (PTFE) Films Market
Poly film
Egypt Plastic Packaging Films Market
Poly film
North America Polyimide Films Market
Poly film
India Plastic Packaging Film Market