
 Cardboard Tubs Market | 2026-2036
Cardboard Tubs Market Size, Share, and Industry Trends Forecast 2026-2036
Cardboard Tubs Market Outlook
The EU Green Deal is restructuring demand patterns across European consumer packaged goods. Smurfit WestRock leverages integrated pulp-to-box operations across Ireland and continental plants to capture converted demand. DS Smith anchors its competitive position through circular design services that help food brands eliminate plastic windows and liners. Mondi Group differentiates via barrier-coated kraft innovations that extend shelf life without polymer laminates.
Cardboard tubs are cylindrical or polygonal containers fabricated from spirally wound or convolute-wound paperboard layers, typically ranging from 0.5 to 5 millimeter wall thickness depending on load requirements. These structures serve primary containment functions for dry goods, semi-moist foods, and personal care products where rigidity and printability outweigh moisture barrier demands. Round tubs retain dominant share in food service and ice cream applications where automated filling lines favor rotational symmetry. Recycled material grade volumes are expanding fastest as brand owners publish plastic reduction commitments that specify post-consumer fiber minimums. Coated grades command margin premiums in personal care where oil resistance and surface gloss influence shelf appeal.
EMA and EFSA frameworks govern fiber contact materials and migration limits for food-grade cardboard tubs across Europe, while EPA guidelines shape virgin pulp sourcing and effluent standards for US-based producers. REACH compliance requirements for coatings and adhesives constrain formulation choices and favor water-based barrier systems over solvent alternatives. Stakeholders must monitor evolving extended producer responsibility schemes that shift collection and recycling costs toward packaging originators.
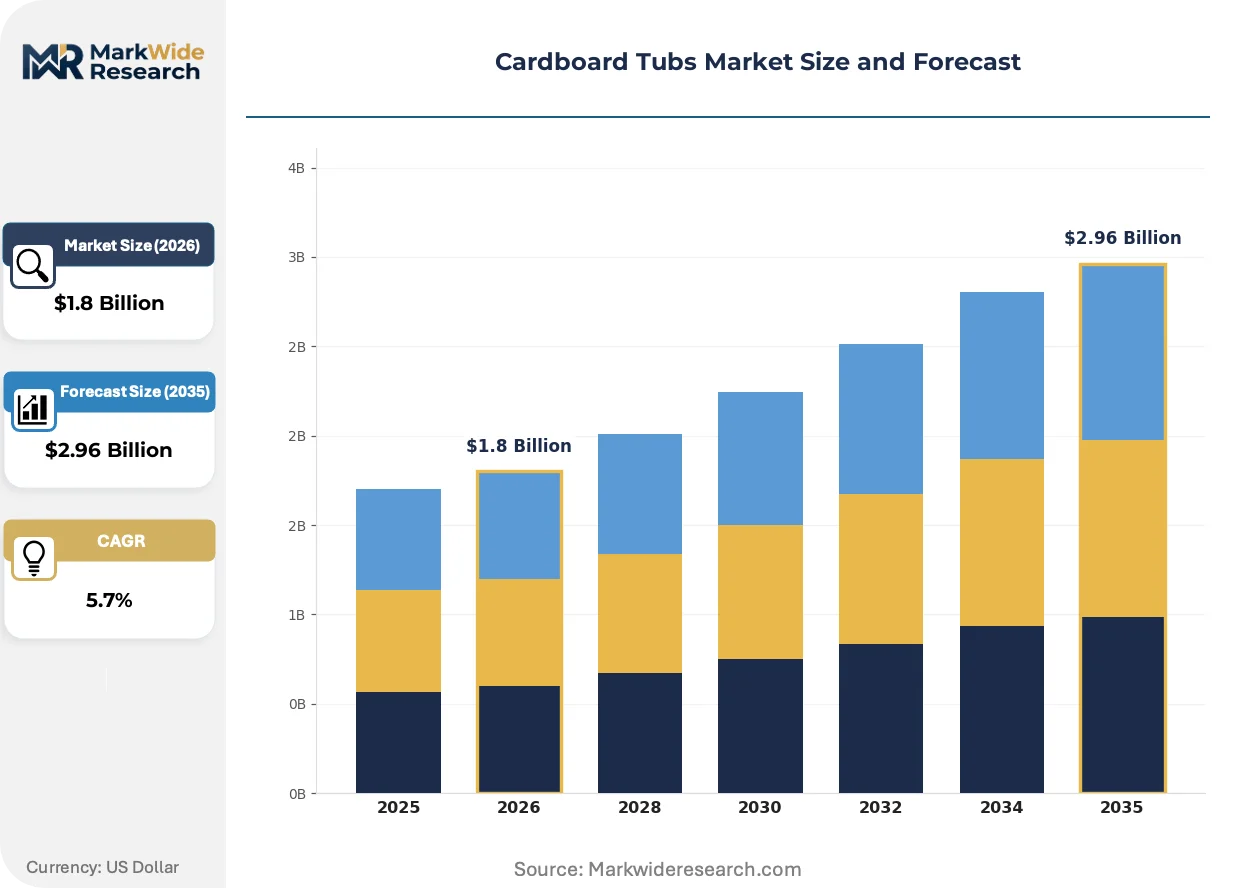
Market Dynamics
The EU Green Deal's packaging waste directives are forcing food brands to eliminate plastic windows and polymer laminates from cylindrical containers, converting structural demand toward fiber-based barrier solutions.
Growth Catalysts
- EU Green Deal Packaging Directives:Mandatory plastic reduction targets in food-contact packaging are accelerating brand-owner transitions to fiber-based tubs across Central European processing clusters.
- Ice Cream Automated Filling:Round rotational symmetry in cardboard tubs aligns with high-speed dairy processing lines, sustaining equipment compatibility during material switches.
- Post-Consumer Fiber Minimums:Corporate plastic reduction commitments specifying recycled content thresholds are pulling virgin-grade buyers into certified recycled material streams.
Market Restraints
- Pulp Price Volatility:Kraft linerboard input costs fluctuate with Nordic softwood supply cycles, compressing converter margins during quarterly contract renegotiations.
- Moisture Barrier Limitations:Uncoated fiber structures fail in semi-moist food applications exceeding 48-hour shelf exposure, capping addressable market segments.
- REACH Formulation Constraints:Water-based adhesive systems required for coating compliance deliver inferior oil resistance versus solvent alternatives, narrowing personal care applicability.
Strategic Opportunities
- Barrier-Coated Kraft Convergence:Oxygen-scavenging layers married to heat-sealable fiber surfaces are opening extended-shelf-life dairy applications previously locked to multilayer plastics.
- Extended Producer Responsibility Schemes:Germany's VerpackG implementation shifts collection cost burdens toward packaging originators, rewarding domestic converter scale.
- Personal Care Premium Positioning:Oil-resistant coated grades with surface gloss control capture margin premiums in cosmetic tub applications where visual shelf appeal commands price separation.
Industry Challenges
- Migration Testing Timelines:EFSA compliance documentation for new barrier coatings extends 18-24 months, delaying product launches against faster plastic approval cycles.
- Spiral Winding Skill Scarcity:Convolute-wound tube production requires specialized press operators and adhesive viscosity control expertise concentrated in legacy German and Irish plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardboard Tubs Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Tubs, Square Tubs, Rectangular Tubs, Custom-Shaped Tubs End User: Food Industry, Personal Care, Healthcare, Retail Size: Small, Medium, Large, Extra Large Material Grade: Recycled, Virgin, Coated, Uncoated |
| Companies Covered | International Paper, Smurfit WestRock, DS Smith, Mondi Group, Rengo Co., Ltd., Packaging Corporation of America, Oji Holdings Corporation, Georgia-Pacific LLC, Marshall Paper Tube Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardboard Tubs Market Strategic Shifts
Material science advances in barrier-coated kraft are collapsing the performance gap between fiber tubs and polymer alternatives, while regulatory compliance automation is compressing certification cycles for food-contact applications.
Barrier-coated kraft technology is integrating oxygen-scavenging polymers directly into fiber substrates, eliminating separate laminate layers. Dairy processors in Germany and the Netherlands are adopting these structures for extended-shelf-life yogurt applications at pilot scale. This convergence is integrating shelf-life performance into mono-material formats that qualify for existing paper recycling streams.
REACH compliance automation platforms are reducing coating formulation approval cycles from 24 months to 14 months for water-based barrier systems. Industrial consequence includes accelerated R&D pipeline throughput for converters serving pan-European food brands. Personal care segments with oil-resistance requirements remain most affected, driving investment in fluorine-free repellency chemistry.
Brand-owner procurement teams are consolidating supplier panels around integrated pulp-to-box operators capable of circular design services. Frozen dessert and ice cream categories are consolidating purchases through three-year framework agreements that bundle material innovation commitments with volume guarantees. This concentration is most visible in Germany, where paperboard processing clusters offer same-day technical service response to Central European co-packing facilities.
Cardboard Tubs Market Segmentation
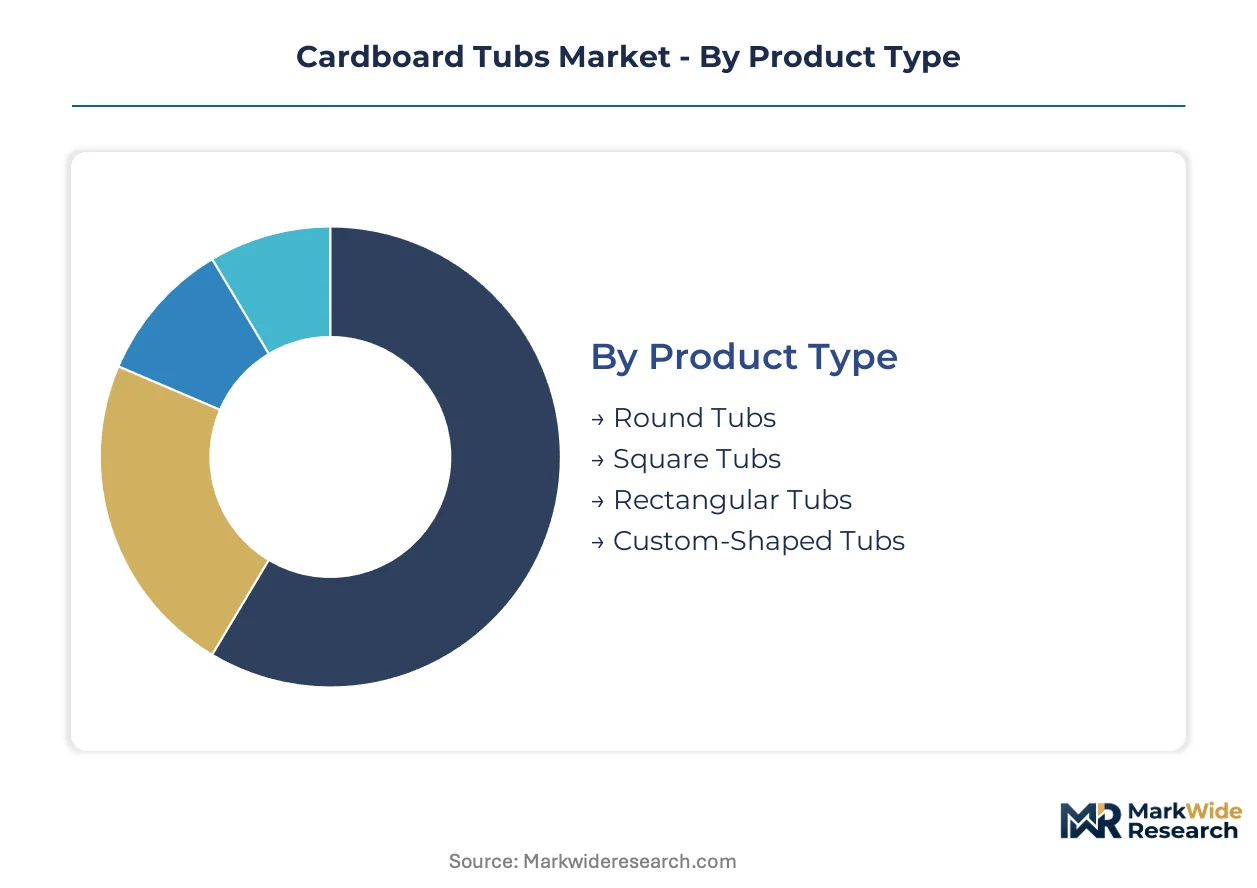
Cardboard tub specifications diverge sharply across filling equipment, barrier requirements, and shelf-life demands. Material-grade selection and geometric form factor determine converter capital allocation and recycling stream compatibility.
Product Type:
Round tub production demands the highest capital intensity due to precision mandrel tooling and automated sealing stations required for rotational symmetry.
- Round Tubs:Spirally wound construction with 0.5-3mm wall thickness accommodates high-speed dairy filling lines. Ice cream processors in Germany favor this geometry for thermal shock resistance during frozen distribution. Mandrel diameter standardization across 75mm-150mm ranges enables tooling reuse across flavor changeovers.
- Square Tubs:Convolute-wound corners require reinforced edge bead application and specialized press configurations. Personal care brands specify square profiles for shelf differentiation and label adhesion surface maximization. Corner radius tolerances below 2mm demand manual inspection stations that elevate labor content.
- Rectangular Tubs:Flat panel construction suits dry goods consolidation where pallet density outweighs filling speed priorities.
- Custom-Shaped Tubs:Polygonal and oval dies serve premium cosmetic positioning with die-cut window integration.
Most installed capacity flows through round tub formats. Expansion is steepest in custom-shaped variants as cosmetic brands pursue shelf differentiation.
End User:
Food industry procurement concentrates volume in frozen dairy applications where EFSA migration limits govern coating selection.
- Food Industry:Dry goods, semi-moist foods, and frozen desserts dominate fiber tub consumption. Ice cream automated filling lines in the Netherlands and Germany specify round rotational symmetry for equipment compatibility. Post-consumer fiber minimums in corporate sustainability commitments are accelerating material transitions.
- Personal Care:Oil-resistant coated grades with surface gloss control command margin premiums. Cosmetic tub applications require REACH-compliant water-based barrier systems that deliver inferior resistance versus solvent alternatives.
- Healthcare:Sterile barrier specifications and migration documentation extend 18-24 months for EFSA compliance.
- Retail:Private-label dry goods consolidation favors standardized rectangular formats for logistics efficiency.
Food industry volumes anchor converter utilization. Personal care applications generate the highest per-unit margins.
Size:
Medium and large formats absorb the majority of kraft linerboard tonnage through ice cream and yogurt applications.
- Small:Single-serve portions under 150ml serve sampling programs and airline catering.
- Medium:250-500ml capacities dominate family-size frozen dessert positioning in Central European retail.
- Large:1-2 liter institutional formats require reinforced base boards for stacking strength.
- Extra Large:Bulk food service containers exceed 5 liters with corrugated outer sleeves for handling rigidity.
Medium sizes carry the heaviest throughput. Extra large formats are climbing the fastest through food service contract consolidation.
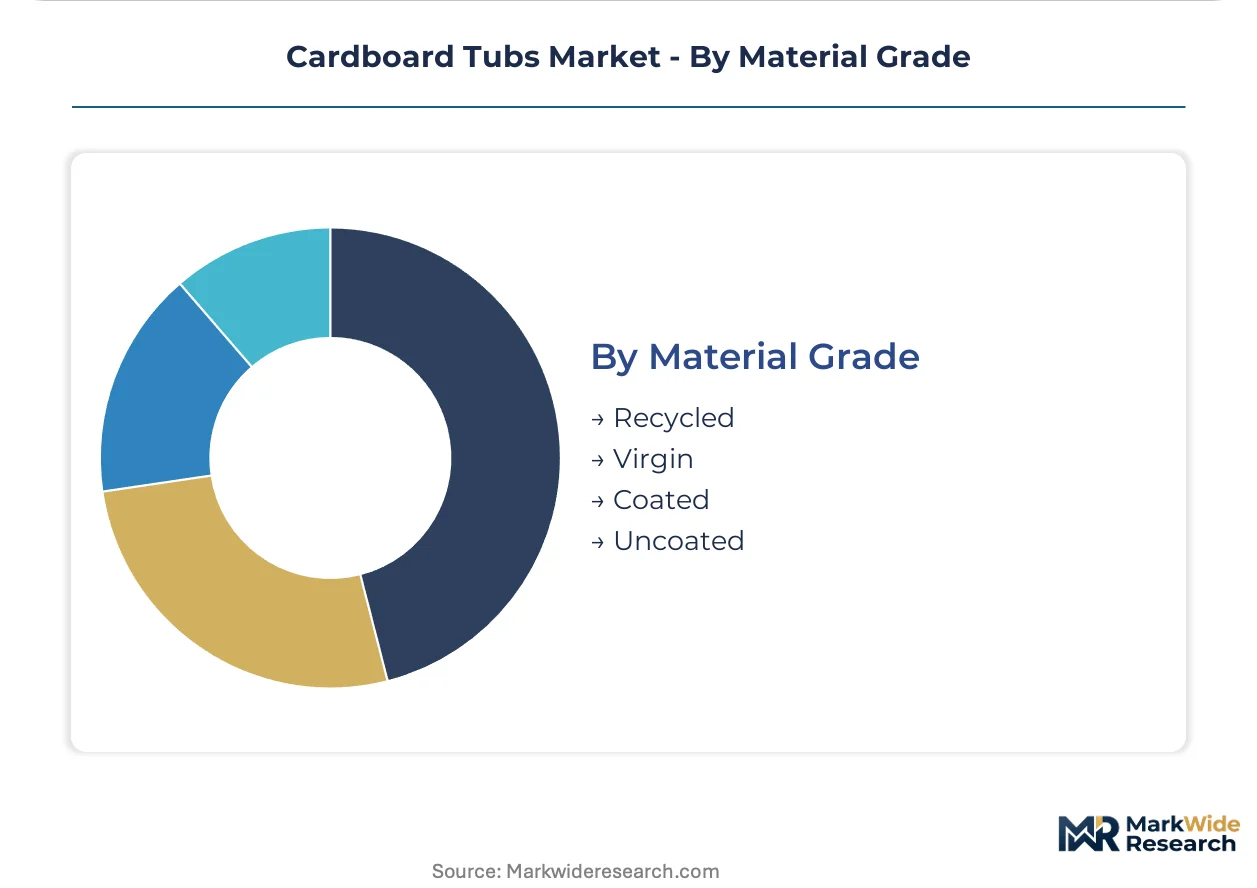
Material Grade:
Coated grades require the steepest upfront investment in barrier formulation R&D and migration testing documentation.
- Recycled:Post-consumer fiber streams are expanding fastest as brand owners publish plastic reduction commitments specifying certified recycled minimums. Germany's VerpackG implementation rewards domestic converter scale with collection cost visibility.
- Virgin:Nordic softwood kraft pulp delivers superior strength consistency for high-speed winding operations. Pulp price volatility with supply cycles compresses converter margins during quarterly contract renegotiations.
- Coated:Oxygen-scavenging layers married to heat-sealable fiber surfaces open extended-shelf-life dairy applications. Water-based adhesive systems required for REACH compliance narrow personal care applicability.
- Uncoated:Basic grades serve dry goods where moisture barrier demands remain minimal and cost positioning dominates.
Recycled material volumes are gaining share fastest. Coated grades capture the highest margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spiral-wound paperboard tub production first scaled in Germany during the 1950s, establishing the technical foundation that now serves Central European dairy processors. Today, converter clusters in Ireland, the Netherlands, and the Nordic states extend this legacy through automated winding lines and barrier-coating R&D centers.
Germany
Ice cream filling lines in Baden-Württemberg and Bavaria consume the highest per-capita volumes of round cardboard tubs in Europe. The VerpackG extended producer responsibility framework shifts collection cost burdens toward packaging originators, rewarding domestic converter scale. Paperboard processing clusters around Hamburg and the Rhine-Ruhr corridor deliver same-day technical service to Central European co-packing facilities.
Netherlands
Dairy processors in Friesland and Utrecht pilot oxygen-scavenging barrier coatings for extended-shelf-life yogurt applications. EFSA migration documentation requirements govern coating selection for food-contact applications. Rotterdam-area logistics hubs consolidate tub shipments for re-export to Nordic and British retail chains.
Ireland
Integrated pulp-to-box operations across Cork and Dublin leverage Nordic softwood supply chains for virgin kraft linerboard consistency. EPA effluent standards shape virgin pulp sourcing decisions for US-owned parent operations. Smurfit WestRock's continental plants anchor technical service networks serving UK and continental demand.
United States
Frozen dessert processors in the Midwest and Southeast specify round rotational symmetry for equipment compatibility during high-speed filling. FDA food-contact notification processes govern barrier coating approvals, with timelines typically shorter than EFSA equivalents. Georgia-Pacific and Packaging Corporation of America operate winding facilities in the Southeast and Pacific Northwest.
Japan
Cosmetic brands in the Kanto and Kansai regions specify square and custom-shaped tubs for shelf differentiation in dense retail environments. METI circular economy guidelines accelerate mono-material format adoption. Oji Holdings and Rengo Co., Ltd. operate convolute-winding facilities with specialized press configurations for premium personal care applications.
Cardboard Tubs Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier-coating capability and circular design service depth. The vendor base organizes into three tiers: integrated pulp-to-box operators with captive fiber supply, specialized tube converters with mandrel tooling expertise, and regional job shops serving private-label dry goods. Three strategic archetypes dominate competitive positioning: backward-integrated fiber producers, barrier-technology licensors, and circular-design consultants. M&A activity concentrates on coating technology acquisitions and regional converter roll-ups.
Among integrated operators, Smurfit WestRock and DS Smith exemplify the pulp-to-box archetype with Ireland and UK-based production networks. Mondi Group occupies a specialist position in barrier-coated kraft innovation. International Paper and Georgia-Pacific anchor the North American tier with Southeast and Pacific Northwest winding capacity. Marshall Paper Tube Co., Inc. represents the specialized converter segment with focused mandrel tooling expertise.
| Leading Market Players |
|---|
| International Paper |
| Smurfit WestRock |
| DS Smith |
| Mondi Group |
| Rengo Co., Ltd. |
| Packaging Corporation of America |
| Oji Holdings Corporation |
| Georgia-Pacific LLC |
| Marshall Paper Tube Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Central European dairy co-packers concentrate procurement volumes through three-year framework agreements, locking in contract-based long-term offtake pricing that bundles barrier-coating innovation commitments with volume guarantees. This buyer concentration rewards integrated pulp-to-box operators with pricing power while compressing regional job shop margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates oxygen-scavenging barrier grades from basic recycled fiber and uncoated commodity tubs. Price differentiation hinges on EFSA migration certification status and virgin kraft pulp content ratios. Cost compression in standard-grade recycled material is intensifying because Nordic softwood supply cycles inflate linerboard input costs quarterly. Private-label retail buyers exhibit highest price sensitivity, while cosmetic brands purchasing oil-resistant coated grades demonstrate least elasticity.
Supply Chain Analysis
Spiral-winding press operator shortages in legacy German and Irish plants constrain convolute-wound tube production expansion. Geographic supply concentration centers on Germany, Ireland, and the Netherlands, with Nordic softwood kraft pulp and water-based barrier coatings as critical inputs. Single-source vulnerability sits with specialized mandrel tooling suppliers concentrated in Baden-Württemberg. Distribution runs through Rotterdam-area logistics hubs consolidating tub shipments for re-export to British and Nordic retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cardboard tubs market represents a late-cycle quality story as food brands shift procurement specifications toward EFSA-certified barrier-coated grades with post-consumer fiber minimums. Premium-grade converters capture expanding margin pools while commodity players face input cost compression.
For Market Incumbents: Cement backward integration into Nordic softwood pulp supply chains to insulate margin structures from quarterly linerboard price volatility. Acquire specialized mandrel tooling capabilities in Germany to defend against emerging barrier-technology licensors entering through coating formulation partnerships. Prioritize circular design service investments that help food brands eliminate plastic windows ahead of EU Green Deal enforcement timelines.
For New Entrants and Emerging Players: Begin with personal care applications in Japan's Kanto region, where square and custom-shaped tub demand outpaces domestic convolute-winding capacity. Target cosmetic brands seeking shelf differentiation through polygonal dies and die-cut window integration. Pursue licensing arrangements with fluorine-free repellency chemistry developers to bypass 18-24 month EFSA migration testing barriers.
For Investors and Strategic Acquirers: Integrated pulp-to-box operators with captive fiber supply are the most active acquirers in this space, consolidating regional tube converters to capture VerpackG extended producer responsibility cost advantages. Five-to-ten year viability favors barrier-technology licensors with oxygen-scavenging patent positions over commodity recycled-grade producers. Monitor Germany's VerpackG implementation pace as the key inflection signal for domestic converter scale premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating R&D Partnership | Oxygen-scavenging layer development opens extended-shelf-life dairy applications previously locked to plastics. |
| Extended Producer Responsibility Compliance Investment | Germany's VerpackG implementation rewards domestic converter scale with collection cost visibility advantages. |
| Spiral-Winding Capacity Expansion | Automated mandrel lines in Ireland and Germany reduce lead times for Central European dairy processors. |
| Post-Consumer Fiber Certification Program | Certified recycled minimums meet corporate plastic reduction commitments specifying fiber-based alternatives. |
| REACH-Compliant Adhesive Formulation | Water-based barrier systems replace solvent alternatives for personal care oil-resistance applications. |
Study Parameters
Coverage spans Germany, Ireland, the Netherlands, the United States, and Japan, with primary inputs from each. Primary interviews with dairy procurement directors, cosmetic brand packaging managers, spiral-winding plant engineers, and barrier-coating R&D leads combined with secondary validation from EFSA migration documentation databases, EU Green Deal directive filings, and Nordic pulp trade association reports. Bottom-up volume modeling across product types and material grades triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects and segment-shift contributions. Segmentation dimensions modeled include geometric form factor, end-use industry, material grade tier, and regional regulatory cluster. CAGRs derived from logistic curve fitting to historical adoption patterns, with industry-specific inputs incorporating EU packaging waste directive implementation schedules and dairy processor automation investment cycles.
Several conditions sit outside the modeled scope, including sudden REACH formulation amendments, Nordic softwood supply disruptions from climate events, and EFSA migration testing timeline compressions. Forecasts reflect assumptions about regulatory enforcement consistency and brand-owner plastic reduction commitment durability. Material deviation in pulp price volatility or barrier-coating approval acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Tubes Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Europe Paper Cone Market
Paper & Paperboard Packaging
Tracing Paper Market
Paper & Paperboard Packaging
Europe Mailer Packaging Market
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
UAE Corrugated Board Packaging Market
Paper & Paperboard Packaging
Polycoated Paper Packaging Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Paper IBC Container Market
Paper & Paperboard Packaging
Pre-Impregnated Paper Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Aluminum Foil Laminated Paper Market
Paper & Paperboard Packaging
Self-Sealing Paper Bands Market