
 Self-Compacting Concrete Market | 2026-2036
Self-Compacting Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Compacting Concrete Market Intelligence
Germany's Rhine-Ruhr corridor is narrowing the gap between specialty admixture supply and precast manufacturing demand. LafargeHolcim leverages its vertical integration into cement and additives to control formulation consistency across European batching plants. HeidelbergCement AG anchors its competitive position through R&D intensity in low-carbon binder systems for self-compacting grades. BASF SE differentiates via superplasticizer chemistry leadership, particularly for high-strength and fiber-reinforced variants.
Self-compacting concrete is a highly flowable, non-segregating concrete that spreads into place under its own weight without mechanical vibration, typically achieving slump-flow values exceeding 650 mm through precise gradation of aggregates and high-range water reducers. Its primary purpose is to ensure complete form filling and dense reinforcement encapsulation in complex geometries where conventional compaction proves impractical or impossible. Fiber-reinforced and high-strength product types command premium positioning due to infrastructure resilience specifications and bridge deck applications where durability governs procurement decisions. Silica fume and superplasticizer mix design technologies are gaining share as performance thresholds for tunnel linings and shotcrete applications intensify across OECD infrastructure programs.
EMA and REACH frameworks in Europe govern chemical admixture composition and environmental release profiles, while ISO standards harmonize rheological test methods for cross-border project qualification. These regulatory layers elevate compliance costs for smaller batching operations but simultaneously consolidate procurement toward certified national suppliers capable of documentation traceability. Stakeholders must monitor evolving embodied carbon thresholds under the EU Green Deal, as future specification criteria will likely privilege mix designs with supplementary cementitious material substitution rates that exceed current baseline requirements.
Market Dynamics
EU Green Deal embodied carbon thresholds are compressing formulation margins across European batching operations while simultaneously privileging suppliers with captive supplementary cementitious material streams.
Growth Catalysts
- Seismic-resistant infrastructure mandates:Japan's infrastructure developers specify self-compacting concrete for high-rise and bridge applications where reinforcement density prevents mechanical vibration. METI building codes accelerate specification in Tokyo-Osaka corridor projects.
- REACH chemical admixture harmonization:ECHA registration requirements for polycarboxylate ether superplasticizers standardize cross-border supply chains. German precast manufacturers leverage documentation traceability to qualify for pan-European infrastructure tenders.
- Precast manufacturing cluster densification:Rhine-Ruhr industrial corridor concentration creates dedicated demand pools for high-flow concrete with slump-flow values exceeding 650 mm. Batch plant specialization reduces transport-induced segregation risk.
Market Restraints
- Superplasticizer cost volatility:Naphthalene and polycarboxylate ether feedstock prices fluctuate with crude oil derivatives. Smaller batching operations lack hedging instruments to stabilize input costs.
- Supplementary cementitious material supply concentration:Silica fume availability concentrates in ferrosilicon-producing regions. Geographic distance from Nordic and Chinese metallurgical plants elevates landed costs for inland European producers.
- ISO rheological test method fragmentation:National deviations in slump-flow and V-funnel protocols create cross-border qualification friction. Project-specific testing requirements duplicate laboratory expenditure.
Strategic Opportunities
- F-Gas Regulation low-carbon binder incentives:EU regulatory frameworks privilege mix designs with fly ash and slag substitution rates above baseline thresholds. R&D investment in calcined clay activation chemistry captures specification premiums.
- Fiber-reinforced tunnel lining applications:Synthetic and steel fiber integration addresses shotcrete rebound reduction in OECD infrastructure programs. Alpine and Scandinavian tunneling contractors specify hybrid reinforcement systems.
- Digital batching integration:IoT-enabled rheology sensors and automated viscosity adjustment compress quality variance. Japanese contractors pilot real-time slump-flow monitoring for seismic-resistant pours.
Industry Challenges
- Specialized rheology technician scarcity:Formulation chemistry expertise for superplasticizer-aggregate interaction modeling concentrates at major admixture suppliers. Independent batching plants face recruitment bottlenecks.
- CE marking timeline compression:Construction product regulation compliance for novel mix designs extends laboratory testing cycles. Smaller producers struggle with documentation resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Compacting Concrete Market |
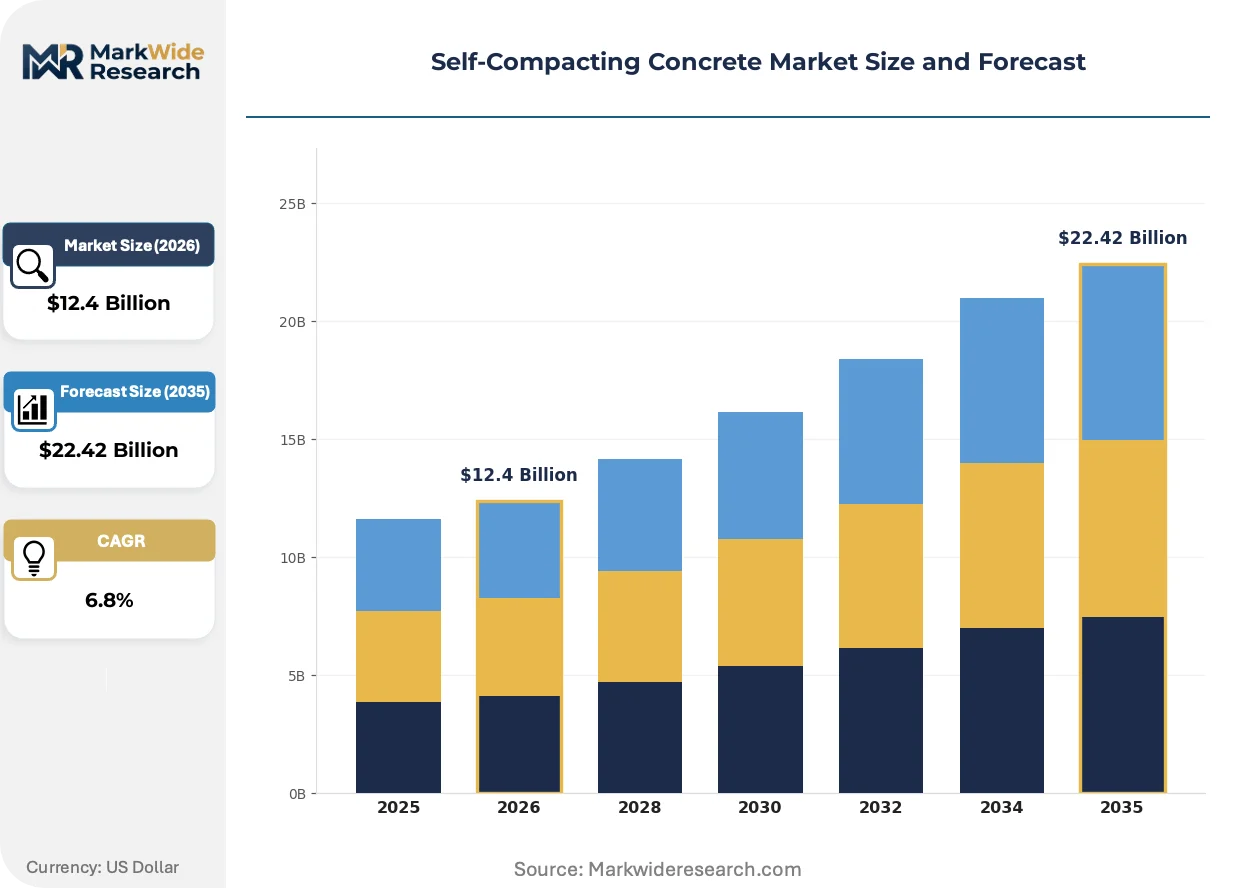
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Strength, Fiber Reinforced, Lightweight, Pre-packed Application: Bridges, Tunnel Linings, Precast Elements, Shotcrete End User: Construction Firms, Infrastructure Developers, Precise Fabricators, Civil Contractors Mix Design Technology: Silica Fume, Fly Ash, Limestone Powder, Superplasticizer |
| Companies Covered | LafargeHolcim, HeidelbergCement AG, BASF SE, Ultratech Cement, Tarmac, CEMEX S.A.B. de C.V., ACC Limited, Kilsaran, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Compacting Concrete Market Strategic Shifts & Innovations
Formulation chemistry and quality verification methods are digitizing across the value chain, compressing batch-to-batch variance while embedding embodied carbon tracking into procurement specifications.
Machine vision slump-flow measurement is digitizing quality assurance protocols. Japanese infrastructure contractors deploy camera-based spread diameter analysis to eliminate operator-dependent measurement error. Real-time viscosity profiling enables just-in-time superplasticizer adjustment at the pump, reducing rejection rates for seismic-resistant pours.
EU F-Gas Regulation and REACH substance restriction timelines are tightening environmental release profiles for chemical admixtures. ECHA evaluation of polycarboxylate ether biodegradability elevates formulation disclosure requirements. German precast clusters respond by certifying closed-loop water recycling at batching plants to demonstrate compliance.
Buyer specification behavior is pivoting toward embodied carbon disclosure as a primary qualification criterion. Infrastructure procurement departments in the Rhine-Ruhr corridor now require Environmental Product Declarations with global warming potential calculations. This documentation burden filters supplier pools toward vertically integrated cement-admixture producers with in-house life-cycle assessment capability.
Self-Compacting Concrete Market Segmentation
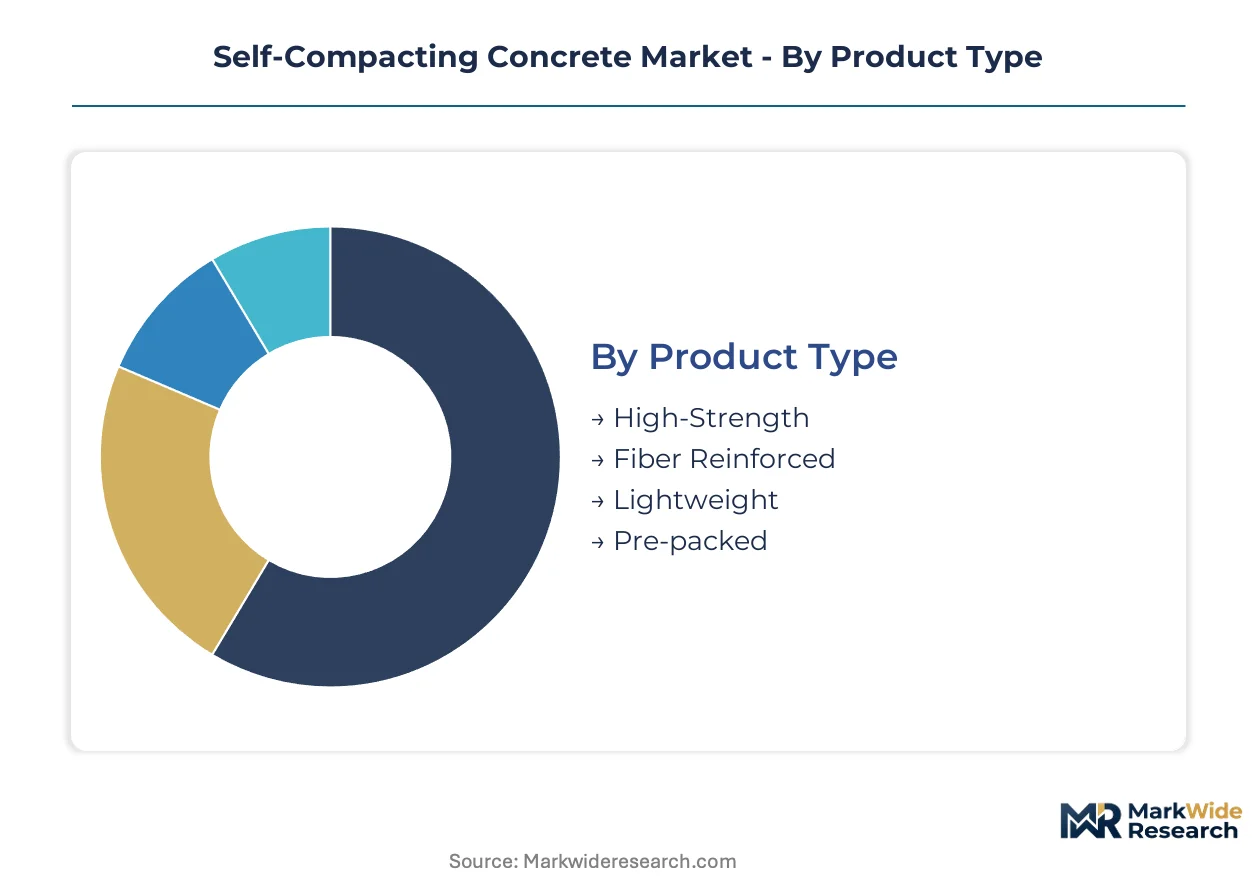
Self-compacting concrete procurement decisions cascade through four interdependent dimensions. Product type governs performance specifications for seismic-resistant infrastructure. Application context determines rheology requirements and reinforcement density tolerances.
Product Type:
Cost tier differentiation separates premium-performance formulations from commodity-grade alternatives for standard precast operations.
- High-Strength:Compressive strength ratings exceeding 60 MPa enable slender structural members in high-rise construction. Japan's METI building codes for seismic-resistant towers in the Tokyo-Osaka corridor specify this grade for core wall applications where reinforcement congestion blocks vibration equipment.
- Fiber Reinforced:Synthetic polypropylene or steel fiber additions between 0.5-2.0% by volume control plastic shrinkage cracking and improve post-crack ductility. Alpine tunneling contractors in Austria and Switzerland specify hybrid fiber systems for shotcrete linings where rebound reduction governs material efficiency.
- Lightweight:Expanded shale or clay aggregate substitution reduces dead load for long-span bridge decks. German Rhine-Ruhr precast manufacturers leverage this variant for facade panels where transport weight limits constrain logistics.
- Pre-packed:Factory-blended dry mixes with pre-measured admixtures ensure batch-to-batch consistency for remote construction sites. Civil contractors in Scandinavia deploy this format for island infrastructure where on-site quality control infrastructure is limited.
High-Strength holds installed capacity. Fiber Reinforced is rotating up the share rankings.
Application:
Volume concentration patterns track infrastructure investment cycles and urban densification imperatives across OECD construction markets.
- Bridges:Complex box-girder geometries with dense post-tensioning ducts demand slump-flow values above 700 mm for complete encapsulation. Japan's Honshu-Shikoku Bridge Authority specifications for cable-stayed decks privilege self-compacting grades for segmental construction joints.
- Tunnel Linings:Permanent shotcrete support in drill-and-blast excavations requires low rebound formulations with rapid early strength development. The Brenner Base Tunnel project between Austria and Italy consumes specialized fiber-reinforced variants for waterproof membrane compatibility.
- Precast Elements:Factory-controlled curing environments enable high-turnover production of architectural cladding and structural components. Germany's Rhine-Ruhr corridor batching plants supply this segment with just-in-time delivery windows under 90 minutes.
- Shotcrete:Wet-mix pumping applications for slope stabilization and mining support prioritize adhesion and build-up thickness. Swedish infrastructure contractors specify silica fume-modified formulations for rock bolt anchorage zones in subarctic conditions.
Precast Elements commands volume leadership. Tunnel Linings is climbing the fastest.
End User:
Customer type determines procurement sophistication, with specification authority concentrating at infrastructure developers and dispersing through subcontractor tiers.
- Construction Firms:General contractors with in-house concrete operations optimize mix designs for project-specific formwork complexity. Japanese mid-tier builders in Osaka's commercial district specify self-compacting concrete for transfer beam pours where rebar density exceeds 400 kg per cubic meter.
- Infrastructure Developers:State-owned or quasi-public entities with multi-decade asset ownership horizons prioritize life-cycle cost over first-cost minimization. Germany's federal transport authority embeds durability clauses in bridge tenders that privilege low-permeability self-compacting formulations.
- Precise Fabricators:Specialty precast producers with architectural surface finish requirements demand ultra-stable rheology for exposed aggregate aesthetics. Italian facade specialists serving Milan's commercial real estate market specify color-matched variants with controlled efflorescence.
- Civil Contractors:Heavy infrastructure specialists with tunneling or marine expertise maintain captive admixture laboratories for rapid field adjustment. Norwegian coastal road projects employ this capability for underwater concrete placements in fjord crossings.
Infrastructure Developers holds specification authority. Precise Fabricators is gaining share fastest.
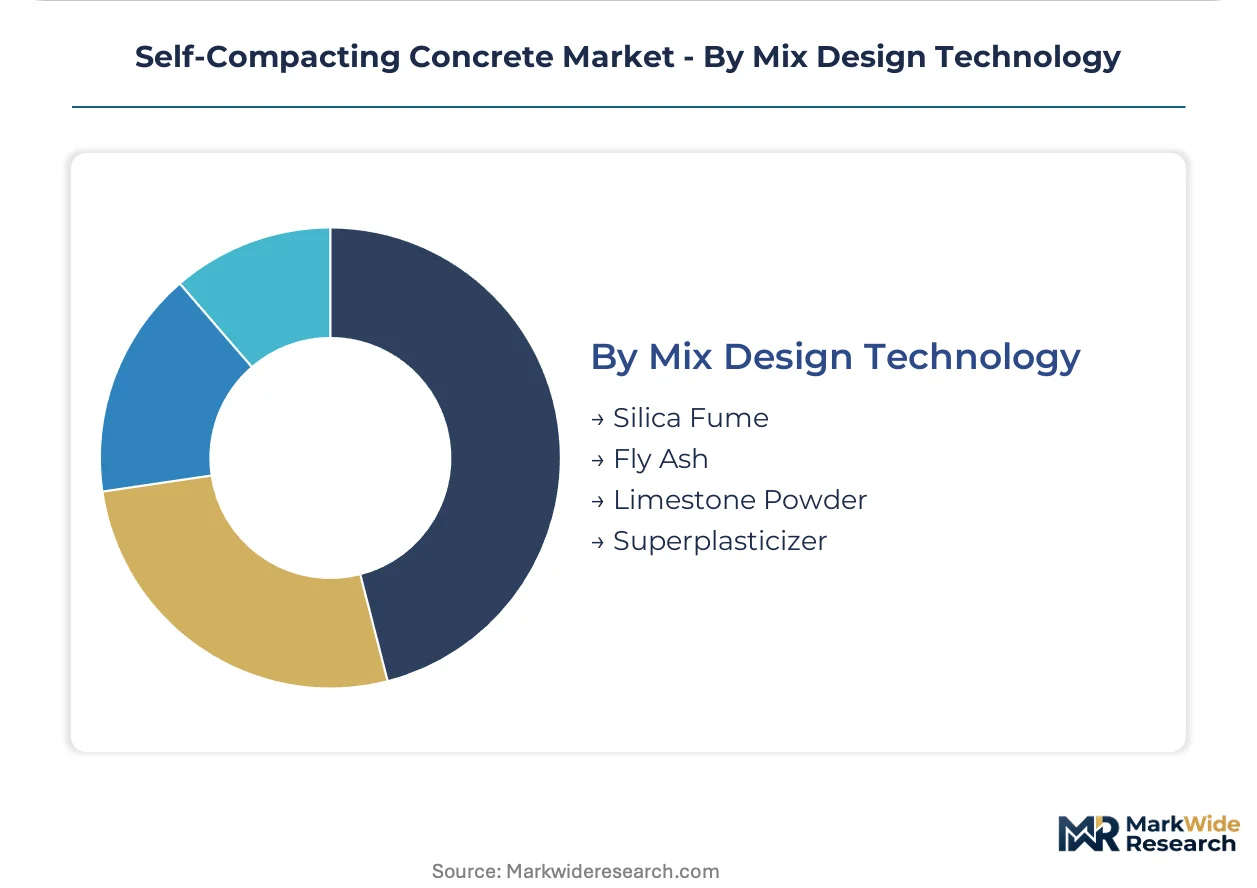
Mix Design Technology:
Supply concentration for supplementary cementitious materials and chemical admixtures shapes regional formulation availability and landed cost structures.
- Silica Fume:Ultra-fine amorphous silica from ferrosilicon smelting reduces permeability and enhances bond to steel reinforcement. Nordic metallurgical plant proximity gives Scandinavian producers cost advantage for marine exposure specifications.
- Fly Ash:Coal combustion residue provides spherical particle morphology for lubrication and long-term pozzolanic strength gain. German lignite power plant closures under EU Green Deal timelines are compressing regional supply availability.
- Limestone Powder:Finely ground calcium carbonate filler enables clinker substitution without supplementary cementitious material dependency. French producers in the Paris basin leverage local quarry integration for low-carbon mix designs.
- Superplasticizer:Polycarboxylate ether polymers enable water reduction above 30% while maintaining flow retention. BASF's Ludwigshafen production complex anchors European supply for high-performance variants with tailored adsorption kinetics.
Superplasticizer dominates formulation value. Limestone Powder is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel anchors Austria's position as a demand center for fiber-reinforced tunnel lining formulations. Japan's seismic-resistant high-rise construction drives specification intensity across the Tokyo-Osaka corridor. Germany's Rhine-Ruhr industrial cluster concentrates precast manufacturing demand for high-flow concrete with stringent slump-flow requirements.
Japan
Seismic-resistant infrastructure mandates from METI building codes accelerate self-compacting concrete specification for core wall applications. The Tokyo-Osaka corridor generates concentrated demand where reinforcement density exceeds 400 kg per cubic meter. Kanto region contractors deploy real-time slump-flow monitoring for transfer beam pours in commercial high-rises.
Germany
The Rhine-Ruhr industrial corridor creates dedicated demand pools for precast elements with just-in-time delivery windows under 90 minutes. EU Green Deal embodied carbon thresholds and REACH chemical admixture harmonization elevate compliance documentation requirements. Bavarian tunneling contractors specify low-permeability formulations for federal transport authority bridge tenders.
Austria
Alpine tunneling programs including the Brenner Base Tunnel consume specialized fiber-reinforced variants for waterproof membrane compatibility. ECHA evaluation of polycarboxylate ether biodegradability drives formulation disclosure at batching plants. Tyrol region shotcrete applications prioritize hybrid reinforcement systems for drill-and-blast excavation support.
India
Urban densification imperatives across metropolitan construction markets expand specification for complex geometries in high-rise commercial towers. BIS standards harmonize rheological test methods for cross-border project qualification. Maharashtra infrastructure developers specify self-compacting grades for Mumbai metro expansion and coastal road projects.
United States
Long-span bridge deck applications drive demand for lightweight variants with expanded shale aggregate substitution. EPA environmental release profiles govern chemical admixture composition for federal infrastructure tenders. Pacific Northwest precast fabricators supply architectural cladding with controlled efflorescence for Seattle commercial real estate markets.
Self-Compacting Concrete Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and admixture supply. The vendor base organizes around three strategic archetypes: vertically integrated cement-admixture producers with captive supplementary cementitious material streams, specialty chemical suppliers with superplasticizer R&D depth, and regional batching operators with project-specific formulation agility. Competitive positioning hinges on backward integration into cement and additives, plus documentation traceability for CE marking compliance.
Among European-based integrated producers, LafargeHolcim and HeidelbergCement AG exemplify platform control through in-house production of cement and admixtures. BASF SE occupies a position within the specialty chemical tier, representing superplasticizer chemistry leadership particularly for high-strength and fiber-reinforced variants. These three anchors illustrate how formulation consistency and life-cycle assessment capability filter supplier pools toward certified national players.
| Leading Market Players |
|---|
| LafargeHolcim |
| HeidelbergCement AG |
| BASF SE |
| Ultratech Cement |
| Tarmac |
| CEMEX S.A.B. de C.V. |
| ACC Limited |
| Kilsaran |
| Sika AG |
| Others |
Cost & Logistics Intelligence
The Rhine-Ruhr industrial corridor's batching plant density concentrates formulation capacity within a 150-kilometer radius, granting precast manufacturers leverage over transport-cost absorption and enabling just-in-time premium pricing for slump-flow values exceeding 650 mm. This geographic compression tightens margins for inland competitors while rewarding corridor-based operators with volume-scaled procurement power.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and project complexity. Premium tiers attach to fiber-reinforced and high-strength formulations with CE marking documentation for seismic-resistant infrastructure, while economy grades serve standard precast elements with relaxed rheology tolerances. Price differentiation hinges on superplasticizer chemistry intensity and supplementary cementitious material substitution rates. Cost compression in the standard tier is intensifying because German lignite plant closures under EU Green Deal timelines are constraining fly ash supply. Infrastructure developers demonstrate lowest price sensitivity due to life-cycle cost ownership horizons, whereas mid-tier construction firms negotiate aggressively on first-cost minimization.
Supply Chain Analysis
Extended payment terms from major precast fabricators to admixture suppliers now stretch to 90-120 days, compressing working capital for independent batching operations and favoring vertically integrated cement-admixture producers with captive financing capacity. Raw material sourcing draws from Nordic metallurgical plants for silica fume, German chemical complexes for polycarboxylate ether superplasticizers, and regional quarries for limestone powder filler. Single-source vulnerability concentrates in ferrosilicon-derived silica fume, where geographic distance from Scandinavian production elevates landed costs for southern European batching plants. Distribution runs through project-specific direct delivery contracts rather than distributor networks, with Rhine-Ruhr corridor plants maintaining dedicated fleet allocation for sub-90-minute delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The self-compacting concrete market is accelerating through a technology inflection as machine vision slump-flow measurement and IoT-enabled rheology sensors compress quality variance below historical baselines. EU embodied carbon disclosure mandates are simultaneously repositioning procurement authority toward suppliers with integrated life-cycle assessment capability.
For Market Incumbents: Insulate formulation consistency advantages by deepening backward integration into cement and supplementary cementitious material streams, particularly calcined clay activation chemistry for low-carbon binder systems. Secure CE marking documentation traceability ahead of Construction Product Regulation timeline compression, as smaller competitors face laboratory testing cycle extensions that disqualify them from pan-European infrastructure tenders. The threat of digital-native batching entrants with automated viscosity adjustment capabilities demands preemptive IoT infrastructure deployment. For New Entrants and Emerging Players: Mid-market commercial construction in India's Maharashtra and Karnataka corridors represents the most penetrable entry point, where BIS standards harmonization creates cross-border qualification pathways without incumbent documentation legacy. Fiber-reinforced shotcrete for Scandinavian tunneling contractors offers a second white-space target, given hybrid reinforcement system specification intensity and limited regional admixture R&D depth. A go-to-market angle anchored in real-time slump-flow monitoring partnerships with Japanese equipment vendors differentiates technical credibility. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialty chemical suppliers with superplasticizer polymer architecture expertise over commodity cement producers, as formulation chemistry complexity concentrates value capture upstream. Long-term viability across a 5-10 year window rests on calcined clay and limestone calcined clay cement activation capabilities that satisfy tightening EU Green Deal substitution thresholds. The signal to watch is ECHA evaluation timelines for polycarboxylate ether biodegradability, which would elevate disclosure requirements and filter acquisition targets toward closed-loop water recycling certification.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Activation R&D | Captures EU Green Deal specification premiums for low-carbon binder systems. |
| Machine Vision Quality Integration | Eliminates operator-dependent slump-flow measurement error for seismic-resistant pours. |
| Closed-Loop Water Recycling Certification | Demonstrates ECHA compliance ahead of polycarboxylate ether biodegradability evaluation. |
| Rhine-Ruhr Corridor Capacity Expansion | Compresses transport-induced segregation risk for just-in-time precast delivery. |
| Fly Ash Supply Agreement Diversification | Hedges German lignite plant closure risk under EU Green Deal timelines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings from integrated cement-admixture producers, ECHA substance registration databases, and EU Construction Product Regulation compliance documentation. Primary interviews engaged batching plant managers, precast fabricator procurement leads, tunneling contractor project engineers, and superplasticizer R&D directors at specialty chemical suppliers. Secondary validation incorporated customs trade data for silica fume and polycarboxylate ether feedstocks, HeidelbergCement AG and LafargeHolcim sustainability disclosures, and BIS standards harmonization notifications. Bottom-up volume modeling triangulated against top-down infrastructure investment forecasts from OECD and national transport authority pipelines.
Forecast inputs incorporate product type segmentation across high-strength, fiber-reinforced, lightweight, and pre-packed formulations; application segmentation spanning bridges, tunnel linings, precast elements, and shotcrete; and mix design technology segmentation by silica fume, fly ash, limestone powder, and superplasticizer chemistry. End-user segmentation distinguishes construction firms, infrastructure developers, precise fabricators, and civil contractors by procurement sophistication and specification authority. CAGRs derive from regression analysis of historical specification intensity against infrastructure investment cycles, cement clinker substitution rate trajectories, and seismic-resistant building code adoption timelines across the Tokyo-Osaka corridor and EU federal transport authority programs.
Macroeconomic conditions sit as an overlay; deviation in construction output indices, crude oil derivative pricing for superplasticizer feedstocks, or EU Green Deal implementation pace would shift the trajectory. Forecasts reflect assumptions documented in primary stakeholder interviews and secondary regulatory filings. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Offshore Structural Analysis Software Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Europe Structural Health Monitoring Market