
 Offshore Structural Analysis Software Market | 2026-2036
Offshore Structural Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Structural Analysis Software Market Outlook
DNV-ST-C203 is decoupling legacy certification pathways from modern digital-twin workflows, forcing engineering firms to rebuild analytical stacks around probabilistic fatigue methods. Bentley Systems leverages its OpenWindPower platform to anchor North Sea project pipelines, while ANSYS sustains R&D intensity in composite riser simulation. Dassault Systèmes differentiates through 3DEXPERIENCE integration across shipyard and offshore contractor ecosystems.
Offshore Structural Analysis Software encompasses computational platforms that model hydrodynamic loading, fatigue life prediction, and ultimate strength verification for fixed and floating marine structures using finite element meshes, spectral wave theory, and coupled aero-hydro-servo-elastic solvers. These tools enable oil and gas operators and offshore wind developers to certify structural integrity before fabrication and installation. Finite Element Analysis dominates current licensing revenue as operators retrofit aging jacket platforms in the North Sea and Gulf of Mexico. Cloud-Based deployment is expanding fastest among mid-size marine contractors seeking elastic compute for storm-response simulations without capital-intensive server farms.
The American Bureau of Shipping, DNV, and API RP 2MET shape software validation requirements through harmonized offshore steel and composite standards that vendors must embed as native design checks. China's Maritime Safety Administration and the EU's Offshore Safety Directive are converging on digital audit trails for structural calculations, tightening market access for uncertified tools. Stakeholders must monitor whether classification societies mandate real-time sensor fusion as a standard input for platform recertification cycles.
Market Dynamics
Probabilistic fatigue methods mandated by DNV-ST-C203 are decoupling legacy certification from digital-twin workflows, forcing engineering firms to rebuild analytical stacks and abandon deterministic legacy codes.
Growth Catalysts
- Floating Wind Expansion:Offshore wind developers in the North Sea corridor deploy spectral wave solvers to certify semi-submersible platform designs before fabrication.
- ISO Standard Updates:The International Organization for Standardization's revised offshore structural standards embed fatigue life prediction as mandatory for platform recertification cycles.
- Cloud Elasticity:Mid-size marine contractors adopt cloud-based deployment for storm-response simulations without capital-intensive server infrastructure.
Market Restraints
- Compute Cost Volatility:GPU-intensive coupled aero-hydro-servo-elastic simulations face input cost spikes from semiconductor supply concentration in East Asian foundries.
- Legacy Code Lock-in:Decades of in-house Fortran-based jacket analysis tools create technical debt that resists probabilistic method migration.
- Classification Society Fragmentation:Divergent validation requirements between the American Bureau of Shipping and DNV create regulatory friction for multi-jurisdiction projects.
Strategic Opportunities
- Real-Time Sensor Fusion:Platform operators in Norway's North Sea corridor pilot digital-twin recertification using live structural health monitoring data streams.
- Composite Riser Simulation:Convergence of composite material modeling with spectral wave theory opens new application white space in deepwater production systems.
- EU Offshore Safety Directive:Digital audit trail mandates for structural calculations create regulatory tailwind for certified software vendors in European waters.
Industry Challenges
- Probabilistic Method Expertise Gap:Engineering firms struggle to hire specialists capable of implementing DNV-ST-C203-compliant fatigue reliability analysis.
- Legacy System Integration:Coupling modern cloud-native solvers with on-premise finite element databases requires expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Structural Analysis Software Market |
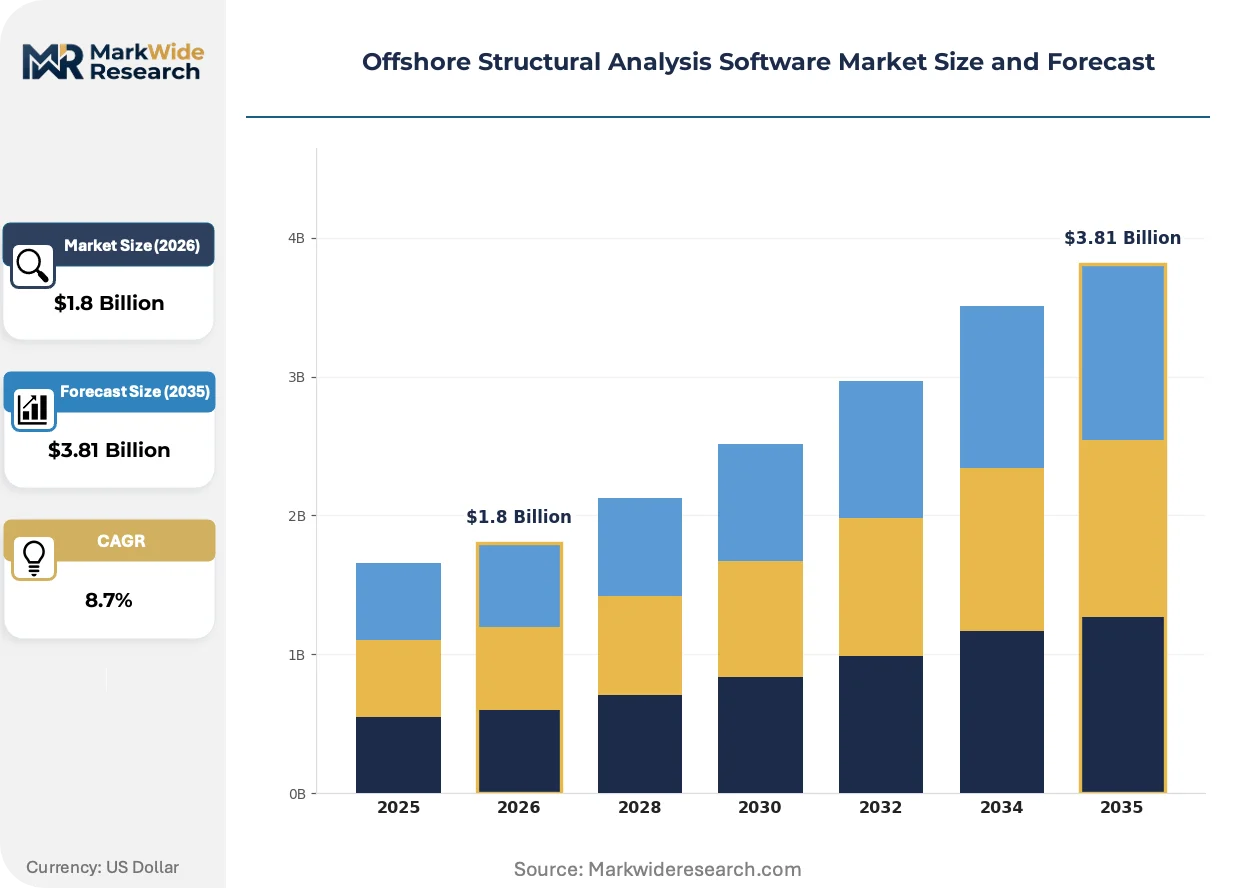
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Finite Element Analysis, Computational Fluid Dynamics, Design Optimization, Structural Integrity Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Engineering Firms, Oil & Gas Companies, Marine Contractors, Research Institutions Solution: Analysis Tools, Simulation Services, Consulting, Support Services |
| Companies Covered | Dassault Systèmes, AxisVM, Bentley Systems, Technical Co., Ltd., LIRALAND Group, ANSYS, Hexagon AB, Hottinger Brüel & Kjær, Dlubal Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Structural Analysis Software Market Strategic Shifts
Digital-twin architectures are rewriting how offshore structures undergo certification, compressing validation timelines from months to weeks through continuous simulation-sensor feedback loops.
Probabilistic digital-twin platforms is rewriting the certification economics for floating offshore wind projects. Developers in the North Sea corridor deploy these tools to validate platform designs against thousand-year storm scenarios. The structural consequence is compressing front-end engineering design cycles while raising the bar for deterministic legacy software.
DNV-ST-C203's decoupling of legacy pathways from modern workflows forces engineering firms to abandon deterministic fatigue codes. The industrial consequence is a bifurcation between certified probabilistic platforms and deprecated legacy tools. North Sea operators and Gulf of Mexico jacket retrofit projects face the steepest compliance cliffs.
Subscription-based licensing for cloud-native solvers displaces perpetual license models among mid-size marine contractors. Direct vendor relationships replace systems integrator intermediaries for simulation procurement. This channel shift concentrates in Norway's offshore engineering cluster where Equinor and Aker Solutions drive platform renewal programs.
Offshore Structural Analysis Software Market Segmentation
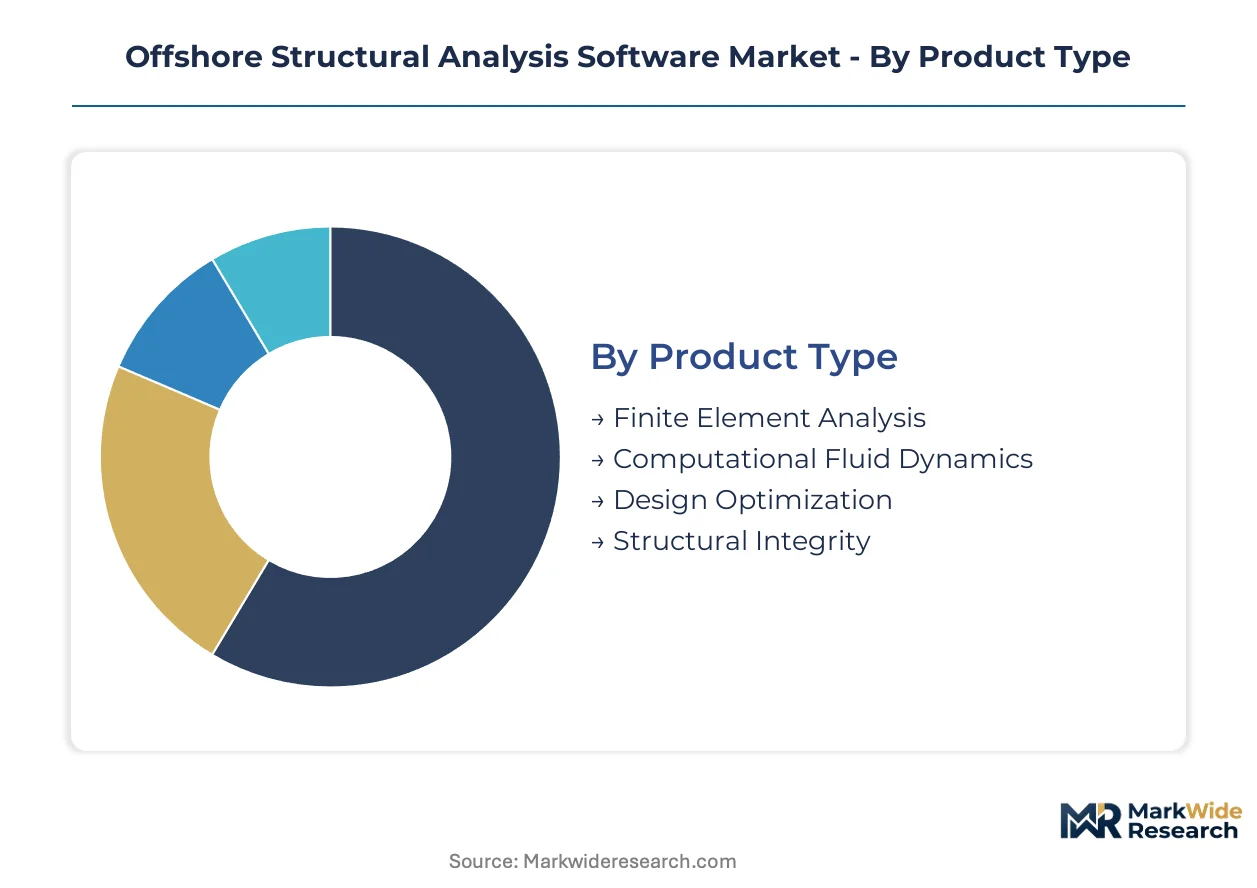
Offshore structural analysis software vendors configure product roadmaps around four intersecting dimensions: physics solver type, infrastructure delivery mode, buyer organizational structure, and service wrap depth. Each segmentation axis carries distinct margin profiles and competitive moats that reshape vendor positioning across the North Sea, Gulf of Mexico, and emerging Asian offshore wind corridors.
Product Type:
Supply concentrates among vendors mastering spectral wave solvers and coupled aero-hydro-servo-elastic engines, with licensing revenue pooling where certification mandates are strictest.
- Finite Element Analysis:Mesh-based structural solvers dominate current licensing revenue as operators retrofit aging jacket platforms. North Sea engineering firms deploy these tools for DNV-ST-C203 compliance, though legacy Fortran codes face deprecation pressure from probabilistic method mandates.
- Computational Fluid Dynamics:Hydrodynamic loading simulation captures vortex-induced vibration and slamming loads on floating platforms. Demand clusters among semi-submersible designers in Norway's offshore engineering corridor, where Equinor drives platform renewal programs requiring thousand-year storm validation.
- Design Optimization:Topology and parametric optimization tools automate scantling reduction for weight-sensitive floating wind structures.
- Structural Integrity:Fatigue life prediction and crack propagation modules anchor recertification workflows for aging fixed platforms in the Gulf of Mexico.
Finite Element Analysis absorbs the bulk of installed capacity; Computational Fluid Dynamics is expanding most quickly.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from elastic cloud consumption favored by mid-size contractors managing project volatility.
- On-Premise:Perpetual license models with dedicated HPC clusters serve supermajors and classification societies requiring air-gapped security for proprietary platform designs. Total cost of ownership concentrates in hardware refresh cycles and specialist IT staffing.
- Cloud-Based:Elastic compute for storm-response simulations eliminates server farm capital expenditure. Marine contractors in Norway's North Sea corridor adopt this model fastest, matching compute spend to project cadence without stranded asset risk.
- Hybrid:Sensitive pre-processing on-premise couples with burst compute to public cloud for nonlinear collapse analysis.
- SaaS:Subscription-native solvers displace systems integrator intermediaries, with direct vendor relationships concentrating among agile engineering boutiques.
On-Premise retains the deepest installed base; Cloud-Based climbs the fastest as procurement shifts toward operational expenditure models.
End User:
Customer type determines solution complexity and contract duration, with oil and gas operators demanding integrated certification pathways and research institutions driving algorithmic innovation.
- Engineering Firms:Multi-physics platform houses rebuild analytical stacks around DNV-ST-C203 probabilistic fatigue methods, abandoning deterministic legacy codes. Talent scarcity for reliability analysis specialists constrains expansion timelines.
- Oil & Gas Companies:Supermajor operators mandate digital-twin readiness for platform recertification, piloting real-time sensor fusion in Norway's North Sea assets. Procurement leverage forces vendor consolidation around integrated 3DEXPERIENCE-class ecosystems.
- Marine Contractors:Installation-focused players prioritize storm-response simulation elasticity over deep customization.
- Research Institutions:Academic and national laboratory users advance composite riser modeling and spectral wave theory convergence, though commercialization pathways remain indirect.
Oil & Gas Companies command the largest contract values; Engineering Firms are gaining share fastest as floating wind project pipelines deepen.
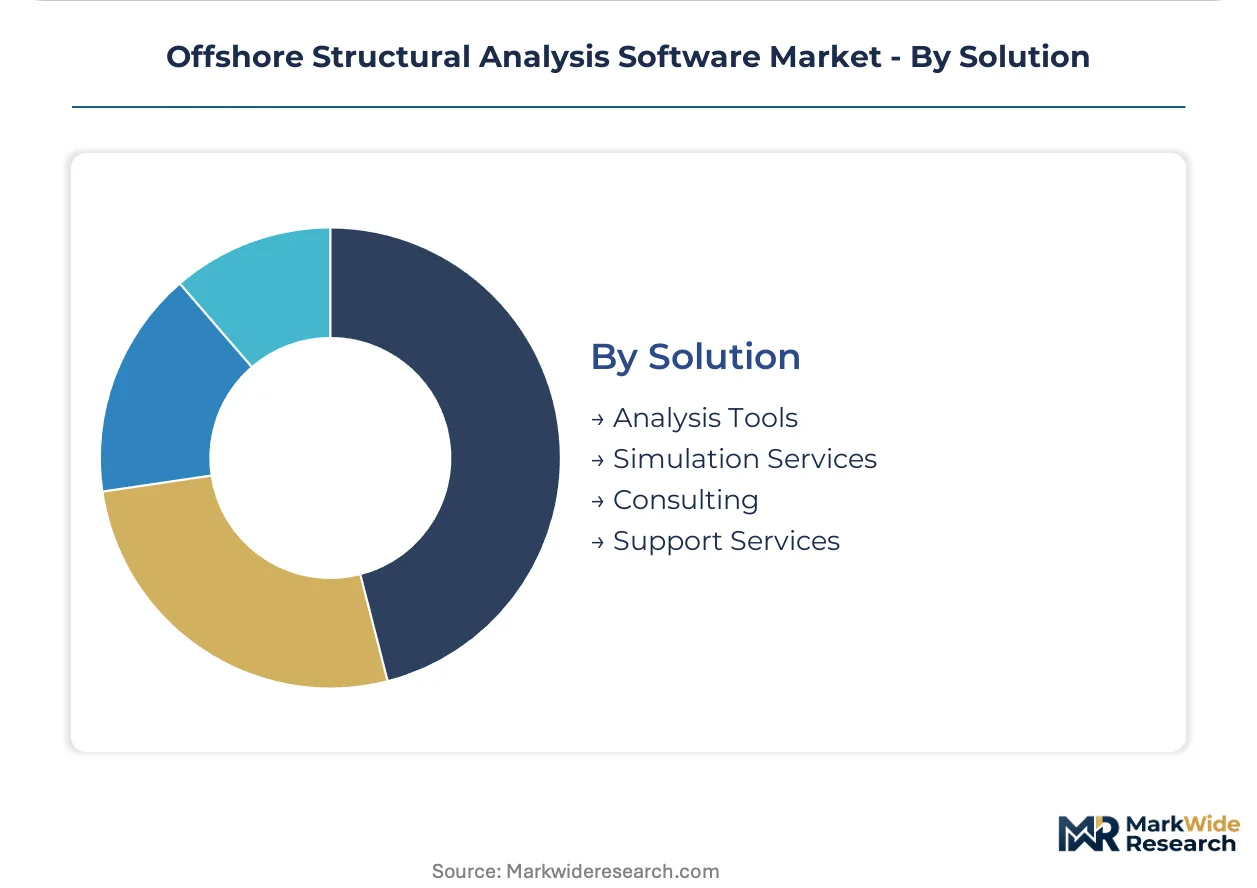
Solution:
Margin structure varies sharply across the service depth spectrum, with pure software licensing yielding recurring revenue and consulting engagements capturing project-specific value.
- Analysis Tools:Native design check modules embedding ABS, DNV, and API RP 2MET standards command premium pricing where regulatory validation is mandatory. Vendors compete on solver speed and certification society pre-approval.
- Simulation Services:Managed analysis engagements address peak demand spikes and specialized expertise gaps, particularly for probabilistic fatigue implementation. Norwegian engineering clusters consume these services heavily during platform renewal cycles.
- Consulting:Front-end engineering design support and regulatory submission preparation carry project-based pricing.
- Support Services:Maintenance, training, and version migration contracts stabilize vendor revenue streams.
Analysis Tools capture the majority of recurring revenue; Simulation Services show the steepest expansion trajectory as engineering firms outsource DNV-ST-C203 compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore structural analysis software demand concentrates where floating wind deployment and aging platform recertification overlap. Norway's North Sea corridor leads platform renewal investment, while the United States and China scale floating foundation certification programs.
Norway
Equinor drives demand for probabilistic fatigue analysis across its floating wind portfolio and aging oil platform inventory. The Norwegian Petroleum Safety Authority enforces digital audit trail requirements for structural recertification submissions. Stavanger and Trondheim engineering clusters host concentrated vendor development activity around DNV-ST-C203 compliance tools.
United States
Gulf of Mexico jacket retrofit programs and Atlantic Coast floating wind leases sustain licensing growth for spectral wave solvers. The Bureau of Safety and Environmental Enforcement mandates structural integrity management systems for offshore facility life extension. Houston engineering consultancies anchor the largest North American user base for coupled aero-hydro-servo-elastic platforms.
China
State-owned developers deploy analysis software for South China Sea deepwater platform designs and offshore wind farm certification. The Maritime Safety Administration requires digital calculation documentation for floating structure approvals. Shanghai and Shenzhen marine engineering institutes concentrate domestic solver development and classification society pre-certification testing.
United Kingdom
North Sea decommissioning schedules and Dogger Bank floating wind leases drive fatigue life prediction tool adoption. The Health and Safety Executive's offshore safety case regulations embed structural reliability analysis in platform operational permits. Aberdeen maintains its position as the primary engineering services hub for North Sea asset integrity management.
Germany
Offshore wind turbine foundation designers in the North Sea and Baltic procurement zones require hydrodynamic loading simulation for monopile and jacket structures. The Federal Maritime and Hydrographic Agency enforces structural calculation standards aligned with IEC 61400-3-1 for offshore wind. Hamburg and Bremen harbor engineering clusters specialize in port infrastructure and offshore converter platform analysis.
Offshore Structural Analysis Software Market Competitive Environment
European software houses anchor the integrated simulation platform tier; North American specialists hold positions in high-performance computing and composite material modeling. Market structure bifurcates between full-suite vendors embedding classification society design checks and point-solution providers addressing specific physics domains. Three archetypes dominate: legacy finite element platform extenders, cloud-native solver developers, and shipyard-integrated ecosystem players. Competitive intensity centers on certification society pre-approval acquisition and direct sales channel displacement of systems integrator intermediaries.
Within the integrated platform tier, Dassault Systèmes and Bentley Systems exemplify ecosystem-centric positioning through shipyard and contractor workflow embedding. ANSYS occupies a position among physics-specialist houses with concentrated R&D in multi-physics coupling. These three companies represent distinct strategic postures: comprehensive vertical integration, maritime industry verticalization, and solver performance leadership respectively.
| Leading Market Players |
|---|
| Dassault Systèmes |
| AxisVM |
| Bentley Systems |
| Technical Co., Ltd. |
| LIRALAND Group |
| ANSYS |
| Hexagon AB |
| Hottinger Brüel & Kjær |
| Dlubal Software |
| Others |
Value Chain & Pricing Dynamics
Probabilistic fatigue specialists concentrated in Norway's Stavanger-Trondheim corridor command 40-60% labor-cost premiums over deterministic legacy coders, compressing margin spreads between premium-certified probabilistic platforms and deprecated deterministic tools.
Pricing Analysis
Volume concentrates in perpetual on-premise licenses for supermajors and classification societies, while margin pools in subscription-native cloud solvers for mid-size marine contractors. Three-tier pricing structure across certification-grade premium, standard compliance, and economy deterministic tiers separates DNV-ST-C203 pre-approved platforms from legacy Fortran-based tools. Pricing pressure stems from GPU-intensive coupled aero-hydro-servo-elastic simulations facing semiconductor supply concentration volatility. Marine contractors exhibit highest price sensitivity due to project-cadence matching needs, while oil and gas operators absorb premium pricing for integrated certification pathways.
Supply Chain Analysis
Direct-to-engineering-firm channels displace systems integrator intermediaries for simulation procurement, with vendor development activity clustering in Norway, the United States, and China. Software development draws from spectral wave theory research institutions, GPU compute infrastructure, and classification society validation partnerships. Single-source vulnerability concentrates in East Asian semiconductor foundries feeding GPU-intensive solver hardware. Distribution runs through maritime engineering clusters anchored by Equinor-driven platform renewal programs in the North Sea corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained by probabilistic fatigue expertise scarcity, with DNV-ST-C203 compliance cliffs propping pricing power for certified platforms.
For Market Incumbents: Extend certification society pre-approval coverage across emerging floating wind jurisdictions before cloud-native entrants capture mid-size contractor relationships. Anchor defensive positioning through backward integration into real-time sensor fusion hardware for digital-twin recertification workflows. Threaten margin compression from GPU compute cost volatility demands elastic pricing structures.
For New Entrants and Emerging Players: EU Offshore Safety Directive digital audit trail mandates in European waters open a window for SaaS-native entrants to bypass incumbent systems integrator lock-in. Target simulation services white space where engineering firms outsource DNV-ST-C203 compliance complexity during platform renewal cycles. Pursue direct sales channel displacement of Norwegian engineering cluster procurement intermediaries.
For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native solver developers given subscription-based licensing displacement of perpetual models across mid-size marine contractors. Long-term viability favors platforms embedding real-time sensor fusion for operational digital-twin recertification. Monitor classification society mandates on live structural health monitoring data as inflection signal for platform renewal spend acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | 3DEXPERIENCE-class ecosystems capture oil and gas operator procurement consolidation around integrated certification pathways. |
| Acquisition of Specialist Firm | Probabilistic fatigue boutiques address talent scarcity constraining engineering firm DNV-ST-C203 compliance timelines. |
| Geographic Expansion | China Maritime Safety Administration digital documentation requirements create regulatory tailwind for certified solver vendors. |
| Strategic Partnership | Classification society co-development agreements embed native design checks as competitive moats against point-solution providers. |
| Product Launch | Composite riser simulation modules open application white space in deepwater production systems convergence. |
Study Parameters
Document review covered classification society standards documentation, offshore project development databases, and regulatory filing records, complemented by interviews with platform engineering directors, marine contractor procurement leads, software vendor product managers, and DNV certification specialists. Secondary validation drew from American Bureau of Shipping technical bulletins, ISO offshore structural standards revisions, and EU Offshore Safety Directive implementation guidance. Bottom-up licensing revenue estimates triangulated against top-down floating wind capacity forecasts.
Installed base and revenue outputs reflect solver-type segmentation by deployment model, end-user organizational structure, and service wrap depth across the projection horizon. CAGRs derived from elasticity-adjusted adoption curves for cloud-based deployment among mid-size contractors. Industry-specific inputs incorporated DNV-ST-C203 compliance timeline assumptions and floating wind project pipeline visibility from North Sea lease rounds.
The model assumes a particular technology adoption path; alternative pathways for deterministic-to-probabilistic method migration would alter the outlook if legacy code lock-in persists beyond anticipated deprecation cliffs. Forecasts reflect assumptions on classification society harmonization and GPU supply chain stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
UK Facade Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Concrete Slabs Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Prestressed Concrete Market