
 Global Concrete Restoration Market | 2026-2036
Global Concrete Restoration Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Restoration Market Analysis
Multi-source procurement for specialty repair chemicals is rebalancing toward regional blending partnerships as logistics costs reshape contractor supply chains. Sika AG leverages its global manufacturing footprint to sustain bulk mortar availability across diverse climate zones. BASF SE anchors its position through R&D intensity in polyurethane injection systems. Mapei S.p.A differentiates via localized technical service networks that control specification influence at the project level.
Concrete restoration encompasses the structural and cosmetic rehabilitation of deteriorated concrete elements through engineered repair materials, typically involving cementitious overlays with compressive strengths exceeding 35 MPa or epoxy-based bonding agents with tensile adhesion above 2 MPa, to extend service life and restore load-bearing capacity. Epoxy and polymer-modified systems occupy the premium tier where infrastructure owners demand rapid return-to-service and chloride resistance, while repair mortar technology dominates volume due to its compatibility with conventional placement methods and lower material cost. The infrastructure application segment leads absolute demand as aging bridge decks and tunnel linings require systematic intervention, whereas commercial building owners increasingly specify microtoppings for aesthetic resurfacing with minimal downtime.
ASTM International governs material performance benchmarks for patch repair and overlay systems in the United States, while the EU Construction Products Regulation mandates CE marking for structural repair mortars sold across member states, creating compliance barriers for non-certified suppliers. The US Federal Highway Administration's bridge inspection standards indirectly drive restoration volume by mandating condition ratings that trigger rehabilitation timelines. Stakeholders must monitor evolving embodied carbon thresholds in public procurement criteria, as these specifications will determine which material chemistries retain eligibility for government-funded infrastructure work.
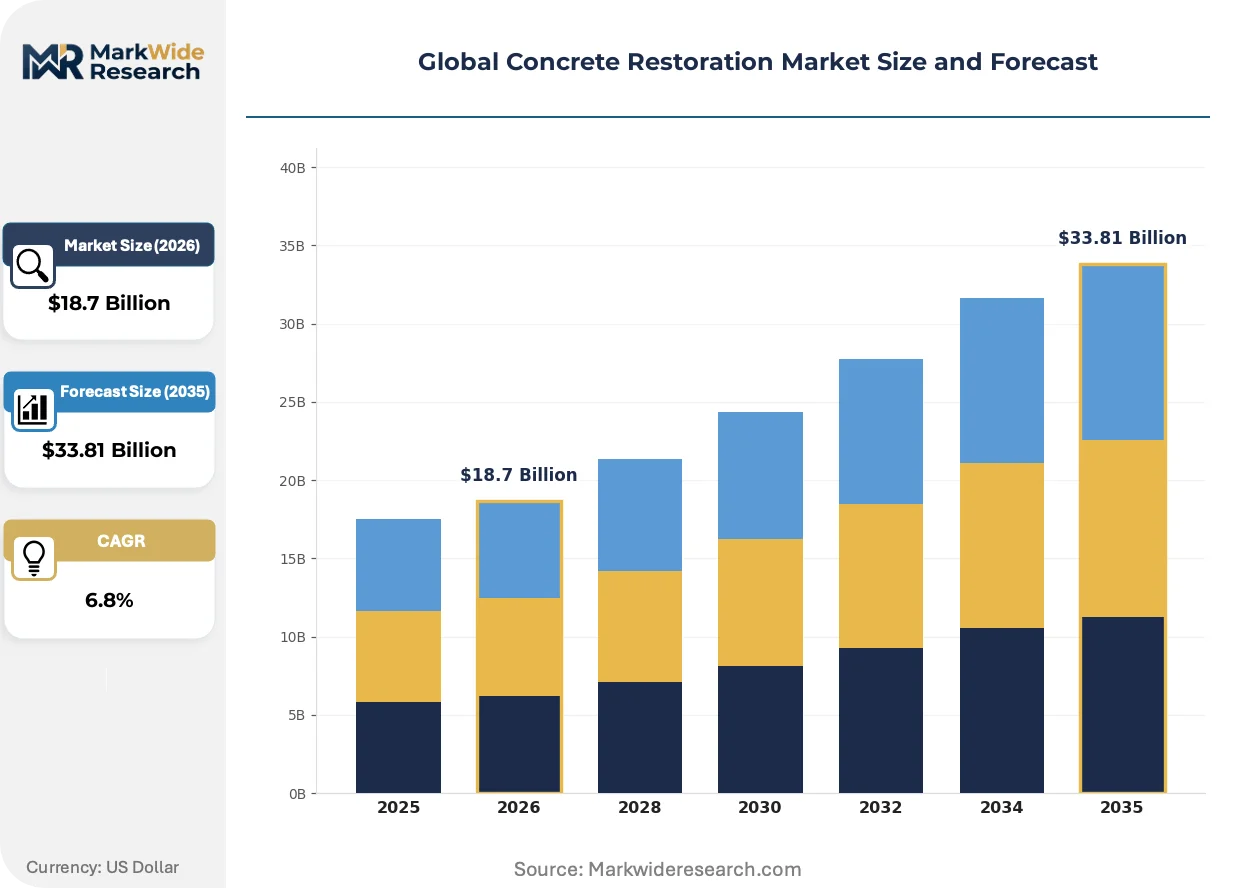
Market Dynamics
Bridge deck chloride contamination and freeze-thaw cycling are compressing rehabilitation timelines across OECD infrastructure networks, forcing asset owners to prioritize rapid-cure polymer systems over conventional cementitious repairs.
Growth Catalysts
- Federal infrastructure renewal mandates:Germany's federal transport budget allocates structural intervention priority over new concrete construction, accelerating specification of high-performance repair mortars.
- Polyurethane injection technology:Deep crack sealing in tunnel linings now demands elastomeric grouts with controlled expansion characteristics, displacing traditional epoxy injection for dynamic load conditions.
- EU Green Deal embodied carbon thresholds:Public procurement criteria in France and Italy now favor geopolymer and alkali-activated repair binders with 40-60% lower carbon footprints than Portland cement equivalents.
Market Restraints
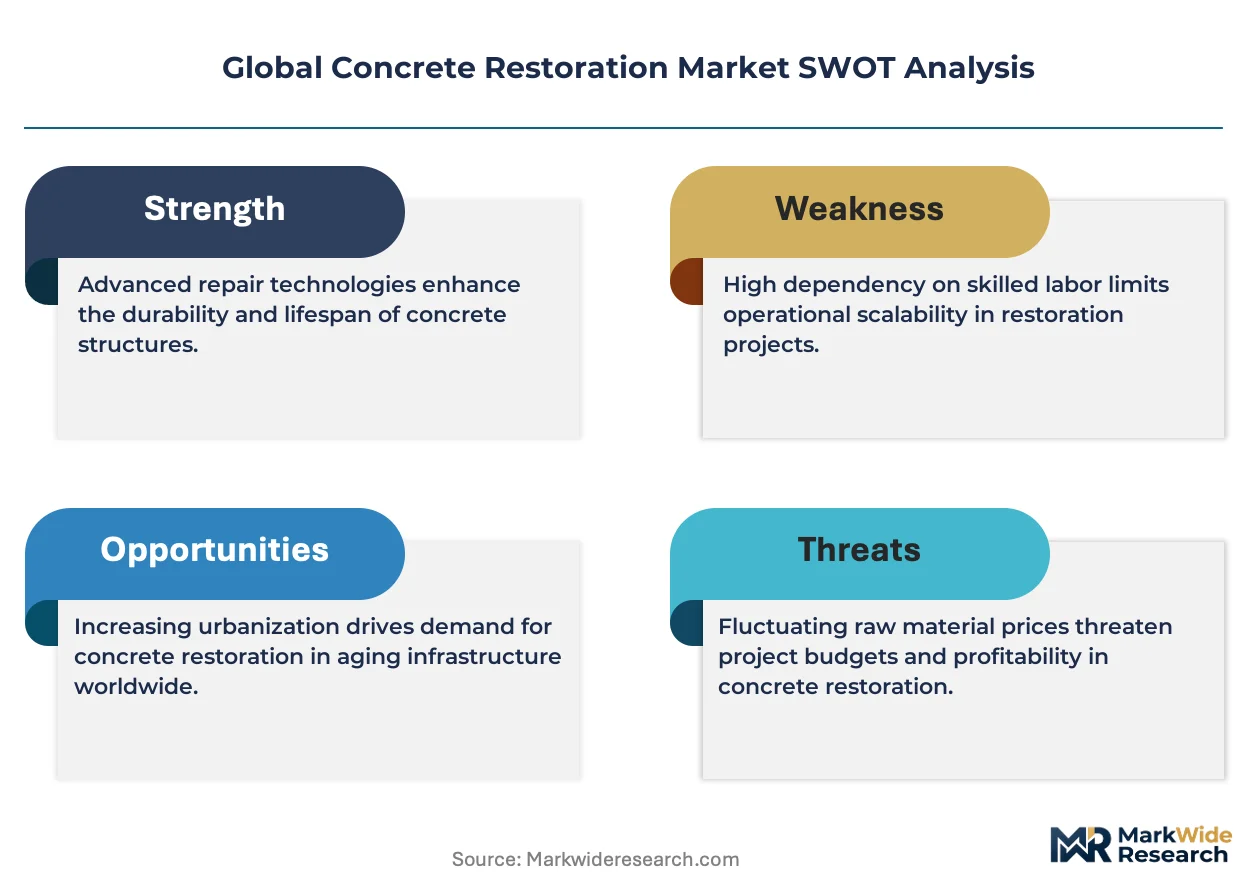
- Epoxy resin feedstock volatility:Bisphenol-A and amine hardener price swings tied to crude oil derivatives compress contractor margins on specification-critical bonding agents.
- CE marking compliance barriers:Non-EU manufacturers face 12-18 month certification timelines for structural repair mortars under the Construction Products Regulation, limiting market access.
- Technical performance gaps in ultra-low-cement formulations:Early-age strength development in geopolymer repairs remains inconsistent below 10°C, restricting cold-climate deployment.
Strategic Opportunities
- India's National Infrastructure Pipeline:Urban metro expansion and port modernization create first-mover advantage for contractors establishing localized blending capacity.
- Digital specification platforms:Cloud-based material selection tools are compressing the engineer-to-contractor information loop, enabling real-time performance data exchange.
- Carbon border adjustment mechanisms:The EU's CBAM creates competitive positioning for regional manufacturers with verified low-carbon supply chains.
Industry Challenges
- Certified applicator scarcity:ICRI and ACI certification requirements for spray-applied repair systems outpace training program throughput in North America.
- Legacy substrate compatibility:Pre-1970s concrete with high alkali content requires specialized surface preparation protocols, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Restoration Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Polymer, Microtoppings Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Property Owners, Government, Developers Technology: Overlay, Injection, Repair Mortar, Shotcrete |
| Companies Covered | Sika AG, BASF SE, Mapei S.p.A, Fosroc International, Master Builders Solutions, Saint-Gobain Weber, Pidilite Industries, RPM International Inc., The Euclid Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Restoration Market Emerging Trajectories
Material science convergence with digital quality assurance is compressing the specification-to-application cycle, while regulatory carbon accounting redefines acceptable binder chemistry across public infrastructure procurement.
Self-healing concrete admixtures containing encapsulated bacterial spores or mineral precursors are unifying structural repair with preventive maintenance. German tunnel operators and Dutch maritime authorities specify these systems for submerged elements where access for manual intervention is restricted. The technology is unifying the traditional separation between new construction durability design and aftermarket restoration, enabling single-contractor responsibility across asset lifecycles.
The EU Construction Products Regulation's harmonized technical specifications for structural repair mortars are mandating third-party notified body certification for CE marking. This regulatory tightening eliminates non-compliant suppliers from public procurement eligibility lists. Infrastructure agencies in Spain and Poland now require digital CE marking traceability through blockchain-verified supply chain documentation.
Asset owners are consolidating repair specification authority through centralized engineering procurement centers, displacing distributed project-level decision-making. Major highway authorities in the United Kingdom and Japan now mandate pre-approved product lists with locked formulations, restricting contractor substitution. This concentration is most visible in bridge deck rehabilitation programs where lifecycle cost modeling overrides first-cost considerations.
Global Concrete Restoration Market Segmentation
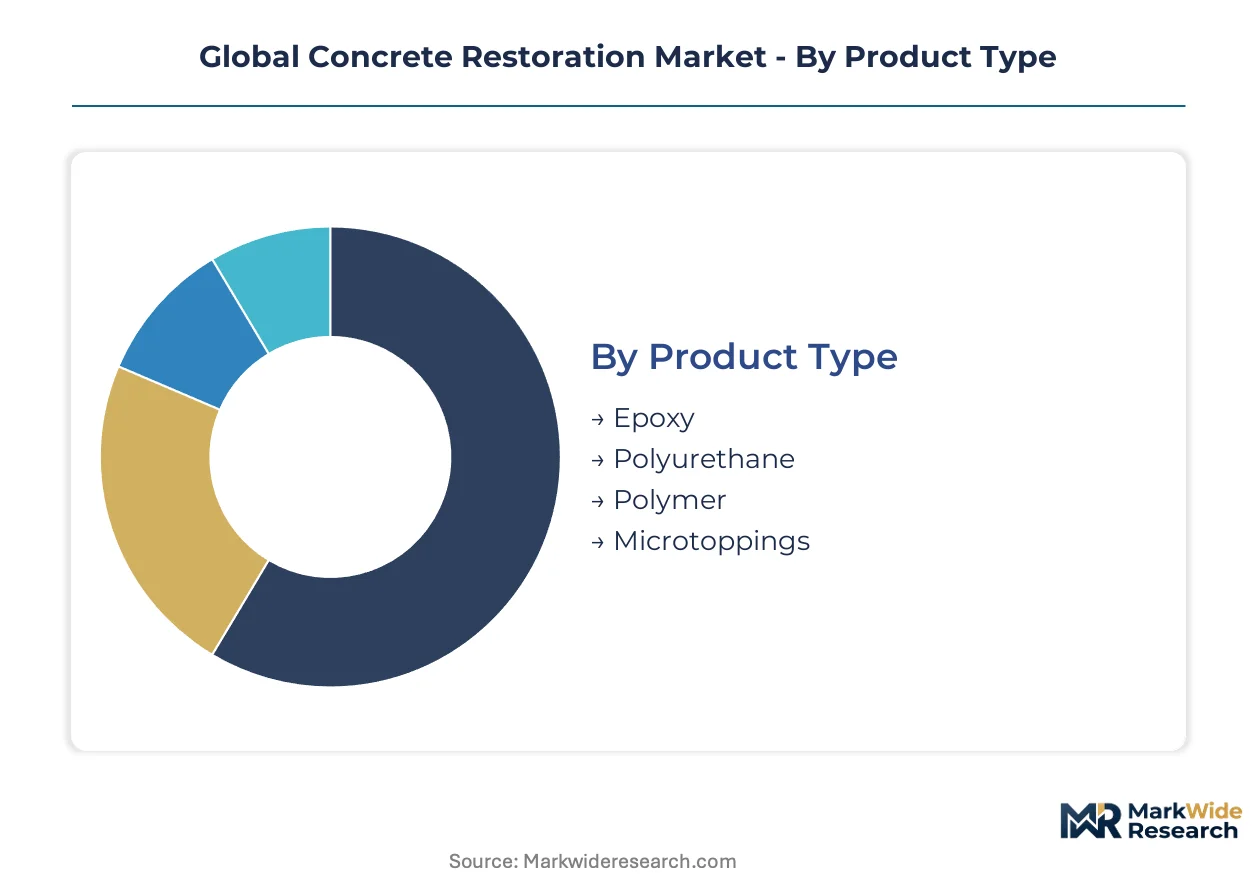
Material certification requirements fragment procurement strategies across product categories, with CE marking under the EU Construction Products Regulation and ASTM compliance in the United States creating divergent qualification pathways for repair system suppliers.
Product Type:
CE marking mandates under the EU Construction Products Regulation apply unevenly across chemistry classes, with structural repair mortars facing full Notified Body certification while cosmetic microtoppings navigate simplified attestation routes.
- Epoxy:Two-component systems formulated from bisphenol-A resins and amine hardeners achieve tensile adhesion above 2 MPa for structural bonding applications. Bridge deck rehabilitation programs in Germany and Japan specify rapid-cure epoxies where chloride ingress resistance determines warranty terms.
- Polyurethane:Elastomeric injection grouts with controlled expansion characteristics displace rigid chemistries in dynamic load environments. Deep crack sealing in Swiss and Austrian tunnel linings now requires these systems for seismic accommodation.
- Polymer:Latex-modified cementitious systems balance compatibility with conventional placement methods against enhanced durability. Federal highway contracts in the United States favor these formulations for overlay applications where rapid return-to-service compresses traffic disruption windows.
- Microtoppings:Thin-section resurfacing materials, typically 3-6 mm applied thickness, serve aesthetic restoration with minimal substrate preparation. Commercial building owners in France and Italy specify these for lobby and atrium refurbishment with same-day reoccupancy.
Repair mortar technology sits at the top of the volume ranking, with polyurethane injection systems climbing the fastest as tunnel operators prioritize elastomeric crack accommodation over rigid epoxy sealing.
Application:
Project scale and asset ownership structure determine specification authority concentration, with centralized engineering procurement centers displacing distributed decision-making in high-volume infrastructure verticals.
- Residential:Single-family and multi-unit property restorations emphasize cosmetic microtoppings and decorative overlays with compressed curing schedules. Homeowner association budgets in Florida and California drive seasonal demand spikes for pool deck and driveway resurfacing.
- Commercial:Retail, hospitality, and office assets prioritize aesthetic microtoppings with minimal operational downtime. Shopping center operators in the United Kingdom and Australia now mandate pre-approved product lists with locked formulations to standardize lifecycle cost modeling.
- Industrial:Manufacturing floors and warehouse slabs demand high-build overlays resistant to chemical exposure and heavy wheeled traffic. Food processing facilities in Denmark and the Netherlands specify polyurethane-modified systems for thermal shock resistance in cold storage environments.
- Infrastructure:Bridge decks, tunnel linings, and port structures require systematic intervention under federal renewal mandates. Germany's federal transport budget allocates structural intervention priority over new construction, accelerating specification of certified repair mortars for highway assets.
Infrastructure applications command the largest absolute spend, with commercial building retrofits expanding most quickly as ESG disclosure requirements elevate lifecycle cost visibility.
End User:
Technical capability and procurement sophistication vary sharply across stakeholder categories, with certified applicator scarcity constraining deployment velocity for spray-applied systems in contractor-dependent segments.
- Contractors:General and specialty restoration firms execute the majority of field placement, with ICRI and ACI certification requirements for spray-applied shotcrete outstripping training program throughput in North America. Large infrastructure contractors in Canada and the United States maintain captive supply agreements to secure bulk mortar availability.
- Property Owners:Commercial real estate investment trusts and industrial facility operators increasingly retain direct specification authority through centralized engineering procurement centers. Japanese railway operators and British highway authorities now mandate locked-formulation pre-approved product lists.
- Government:Federal, state, and municipal agencies control infrastructure rehabilitation timelines through condition rating systems that trigger mandatory intervention. The US Federal Highway Administration's bridge inspection standards indirectly drive restoration volume by mandating rehabilitation timelines for deficient ratings.
- Developers:New construction firms specify self-healing admixtures and preventive durability systems that unify structural design with lifecycle maintenance responsibility. Dutch maritime authorities and German tunnel operators require these systems for submerged elements with restricted access.
Contractors handle the greatest project volume, with government agencies gaining specification influence fastest through centralized procurement consolidation.
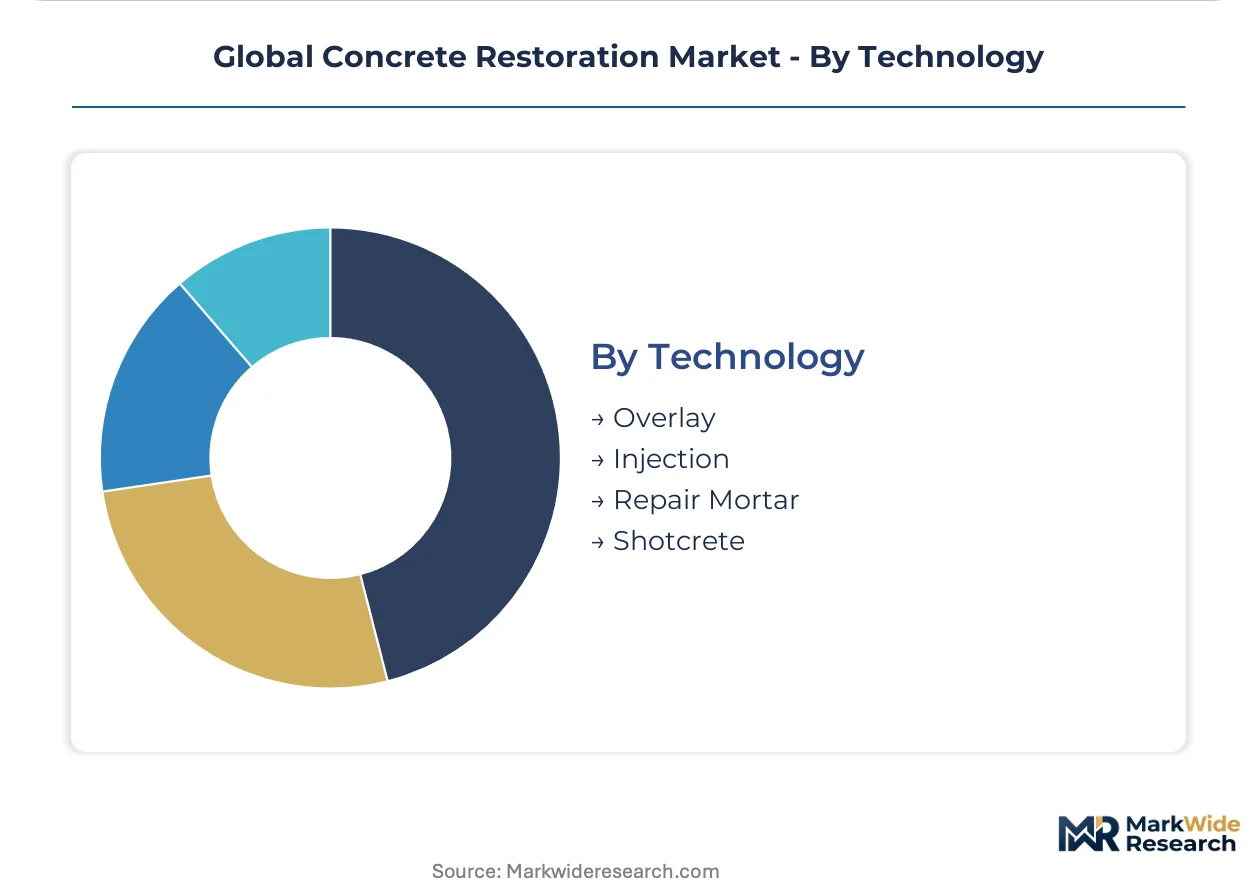
Technology:
Placement methodology determines labor skill requirements and equipment capital intensity, with spray-applied systems facing certified applicator bottlenecks while trowel-applied methods leverage conventional trade labor pools.
- Overlay:Cementitious and polymer-modified surface courses restore profile and protect substrate from further deterioration. Bridge deck rehabilitation in the United States and Germany specifies high-performance overlays where chloride resistance determines warranty duration.
- Injection:Pressure-injected resins seal static and dynamic cracks in structural elements. Elastomeric polyurethane grouts with controlled expansion characteristics now displace epoxy injection for tunnel lining repairs in seismic zones of Japan and Italy.
- Repair Mortar:Hand-placed or form-and-pour cementitious systems restore section loss in columns, beams, and walls. Compatibility with conventional placement methods and lower material cost relative to polymer systems sustains volume dominance across climate zones.
- Shotcrete:Pneumatically applied concrete and mortar enables rapid coverage of complex geometries and overhead surfaces. ICRI certification requirements for nozzleman qualification constrain deployment velocity in North American infrastructure programs.
Repair mortar technology anchors volume leadership through compatibility advantages, with injection systems recording the steepest expansion trajectory as tunnel operators prioritize elastomeric crack sealing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's federal infrastructure renewal programs anchor regional demand concentration, with bridge deck rehabilitation and tunnel lining projects driving specification of certified repair systems across diverse climate zones.
United States
Federal highway bridge inspection mandates trigger systematic rehabilitation timelines across state transportation departments. The Federal Highway Administration's condition rating standards indirectly compel restoration volume through deficiency thresholds. Texas and California DOTs concentrate procurement authority for polymer-modified overlay systems.
Germany
Federal transport budget allocations prioritize structural intervention over new concrete construction. The EU Green Deal's embodied carbon thresholds favor low-cement geopolymer formulations in public procurement. Bavaria and North Rhine-Westphalia host the densest contractor networks for certified repair mortar application.
China
Urban metro expansion and high-speed rail tunnel maintenance create sustained demand for injection grouts and shotcrete systems. National dual carbon goals push state-owned developers toward alkali-activated repair binders. Yangtze River Delta municipalities specify rapid-cure systems for compressed traffic disruption windows.
India
National Infrastructure Pipeline commitments to port modernization and metro construction accelerate specification of durable repair materials. Bureau of Indian Standards certification requirements create compliance barriers for imported structural mortars. Maharashtra and Gujarat concentrate blending capacity for localized supply to western coastal infrastructure.
Japan
Seismic retrofit programs for aging highway tunnels and bridge substructures drive elastomeric injection grout demand. Ministry of Land, Infrastructure, Transport and Tourism mandates locked-formulation pre-approved product lists. Kansai region operators specify controlled-expansion polyurethane systems for dynamic load accommodation.
Global Concrete Restoration Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue geopolymer and carbon-reduced formulations to capture sustainability-driven specification shifts. The vendor base stratifies across three archetypes: global chemical conglomerates with integrated supply chains, regional specialists with localized technical service networks, and construction-materials divisions of diversified industrial groups. Competitive positioning hardens through CE marking certification velocity and pre-approved product list penetration. M&A activity concentrates on regional blending assets; strategic partnerships lock in raw material supply for epoxy resin feedstocks.
Within the global integrated tier, Sika AG and BASF SE exemplify archetype dominance through manufacturing footprint breadth and R&D infrastructure scale. Mapei S.p.A occupies a distinct position as a family-controlled specialist with dense technical service presence in Mediterranean and Middle Eastern markets. These three anchors represent the competitive standard against which regional challengers benchmark certification timelines and specification influence.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Mapei S.p.A |
| Fosroc International |
| Master Builders Solutions |
| Saint-Gobain Weber |
| Pidilite Industries |
| RPM International Inc. |
| The Euclid Chemical Company |
| Others |
Supply Flow & Price Mechanics
Geopolymer binder technology adoption across EU infrastructure procurement simultaneously compresses material cost premiums and redistributes manufacturing capacity toward regional blending hubs with validated low-carbon supply chains. This chemistry transition rewards producers with captive alkali-activated precursor sourcing while penalizing importers dependent on Portland cement feedstock logistics.
Pricing Analysis
Epoxy resin and amine hardener feedstock volatility draws from crude oil derivative markets, forcing cost pass-through into structural bonding agent tiers. Three-tier pricing structure across rapid-cure premium, standard polymer-modified, and economy cementitious levels reflects certification grade and volume scale differentiation. Cost compression in mid-tier latex-modified systems is intensifying because contractor procurement consolidation demands bulk mortar availability guarantees. Small regional applicators exhibit highest price sensitivity, while centralized highway authority procurement centers prioritize lifecycle cost modeling over first-cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for structural repair mortars under EU Construction Products Regulation CE marking protocols mandate qualified backup suppliers for critical infrastructure projects. Manufacturing gravity centers on Germany, the United States, and China, with regional blending partnerships expanding in India and Southeast Asia to compress logistics costs. Raw material dependencies encompass bisphenol-A epoxy resins, polyurethane prepolymers, and alkali-activated geopolymer precursors. Single-source vulnerability persists for specialty amine hardeners amid European chemical sector consolidation. Distribution runs through captive supply agreements between global producers and large infrastructure contractors, supplemented by technical service networks controlling specification influence at project level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Concrete Restoration Market functions as a stable compounder anchored by irreversible infrastructure renewal mandates across OECD bridge and highway networks. Federal transport budget allocations in Germany and condition rating triggers in the United States institutionalize steady demand visibility.
For Market Incumbents: Deploy CE marking certification velocity as the priority lever. Accelerate notified body approvals for geopolymer repair mortars ahead of embodied carbon procurement thresholds tightening across France and Italy. Establish captive alkali-activated precursor supply through backward integration into regional slag and fly ash sourcing. Consolidate specification influence by locking formulations into pre-approved product lists at major highway authorities. For New Entrants and Emerging Players: Regional blending partners offer the fastest channel to bypass 12-18 month CE marking barriers for imported structural mortars. Target India's National Infrastructure Pipeline metro and port modernization segments where Bureau of Indian Standards certification creates defendable moats against global suppliers. Pursue white-space positioning in ultra-low-cement cold-climate formulations addressing early-age strength gaps below 10°C deployment thresholds. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with dense technical service networks and localized blending assets. Five-to-ten year viability rests on carbon border adjustment mechanism positioning and verified supply chain documentation capability. Acquisition focus should center on Mediterranean and Middle Eastern service-heavy operators with pre-approved product list penetration. Monitor EU Green Deal embodied carbon threshold enforcement velocity as the critical inflection signal for chemistry substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali-Activated Precursors | Secures supply chain positioning ahead of EU CBAM enforcement on carbon-intensive imports. |
| CE Marking Certification Acceleration | Notified body approval velocity determines eligibility for Germany's federal infrastructure renewal contracts. |
| Regional Blending Partnership Expansion | Localized production in Maharashtra and Gujarat addresses India's Bureau of Indian Standards compliance barriers. |
| Pre-Approved Product List Penetration | Locked formulations at British and Japanese highway authorities secure multi-year specification continuity. |
| Digital Specification Platform Development | Cloud-based material selection tools compress engineer-to-contractor information loops for real-time performance data exchange. |
Methodological Framework
Bottom-up infrastructure and commercial building modeling reconciled against top-down specialty chemical supply tracking forms the analytical core of this study. Primary interviews with bridge maintenance engineers, tunnel rehabilitation contractors, polymer R&D directors, and highway authority procurement officers combined with secondary validation from ASTM International standards databases, EU Construction Products Regulation CE marking registries, Federal Highway Administration bridge condition reports, and national transport budget appropriations documentation. Triangulation across demand-side project pipelines and supply-side manufacturing capacity ensures segmentation integrity.
Historical trendline analysis of repair mortar volume and polymer system value trajectories anchored projection frameworks across the modeling period. Segmentation dimensions encompass material chemistry class, application vertical, placement technology, and regional regulatory cluster. CAGRs derive from weighted average of infrastructure renewal program commitments, commercial building ESG disclosure adoption curves, and geopolymer formulation penetration assumptions. Industry-specific forecast inputs include federal transport budget allocation trajectories and embodied carbon procurement threshold implementation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement velocity and epoxy resin feedstock price volatility. Projections reflect assumptions regarding CE marking regulatory stability and alkali-activated binder technical performance maturation. Deviation in carbon border adjustment mechanism implementation timelines or geopolymer cold-climate strength development breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Philippines Structural Insulated Panels Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
FRP Bridge Market
Structural Engineering
North America Facade Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
Prestressed High Strength Concrete Pipe Pile Market