
 Europe Bridge Bearings Market | 2026-2036
Europe Bridge Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bridge Bearings Market Foresight
Rail bridge rehabilitation across Central Europe is expanding faster than highway replacement cycles. Mageba SA leverages its Swiss manufacturing base to dominate high-load pot bearing contracts for Alpine rail tunnels. Trelleborg sustains competitive positioning through advanced elastomeric compound R&D for vibration-dampening applications. Gumba GmbH & Co. KG anchors its presence in German-speaking markets with specialized cast-in-place installation services.
Bridge bearings are structural interface devices engineered to transmit loads while accommodating thermal expansion, rotation, and horizontal movement between superstructure and substructure elements. European specifications typically require polytetrafluoroethylene sliding surfaces paired with stainless steel mating plates to achieve coefficient of friction below 0.05 under design loads. Elastomeric bearings remain the volume leader for moderate-load highway applications, though margin pools concentrate in extra-high-load pot bearings for heavy rail corridors. Sliding material configurations represent the fastest-expanding category as engineers specify maintenance-free alternatives for inaccessible bridge locations.
CE marking under the Construction Products Regulation and Eurocode EN 1337 govern bearing design validation across EU member states, while ECHA REACH compliance restricts certain rubber plasticizers in elastomeric compounds. National regulators in Italy and Switzerland impose supplementary seismic qualification protocols that filter supplier eligibility. Stakeholders must monitor pending EU taxonomy alignment rules that will reclassify embodied carbon thresholds for steel and elastomer inputs.
Market Dynamics
The EU Green Deal's embodied carbon thresholds are compressing material choices across European bridge procurement, forcing substitution toward low-friction sliding configurations and away from conventional steel-elastomer assemblies.
Growth Catalysts
- Rail infrastructure renewal:Germany and France are expanding procurement volumes for elastomeric and pot bearing systems through dedicated federal bridge replacement programs.
- Eurocode EN 1337 updates:Revised European standards for bearing design validation are accelerating material qualification cycles and filtering supplier pools toward certified manufacturers.
- Alpine seismic requirements:Switzerland and Italy impose stricter national qualification protocols for seismic-resistant designs, creating specialized demand pockets for high-performance pot bearings.
Market Restraints
- Steel price volatility:Stainless steel mating plates constitute 35-45% of sliding bearing input costs, exposing margins to commodity swings.
- Elastomer compound restrictions:ECHA REACH compliance limits certain rubber plasticizers, forcing reformulation of established elastomeric bearing recipes.
- Supplier concentration in Alpine corridors:Swiss and Austrian manufacturers dominate high-load pot bearing production, creating bottleneck risk for large rail contracts.
Strategic Opportunities
- Polish and Romanian highway expansion:EU Cohesion Fund allocations for trans-European corridor completion are opening procurement windows in underpenetrated Central European markets.
- Maintenance-free specifications:Inaccessible bridge locations in Norwegian fjord crossings and Scottish Highlands are driving specification of self-lubricating PTFE-stainless sliding systems.
- EU taxonomy alignment rules:Pending reclassification of embodied carbon thresholds will reward suppliers with verified low-carbon steel and recycled elastomer inputs.
Industry Challenges
- Seismic certification timelines:Italian and Swiss national protocols require extended qualification periods that delay contract execution by 8-14 months.
- Cast-in-place installation skill scarcity:Specialized anchoring techniques for pot bearings face limited trained contractor availability in Baltic states and Southeast Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bridge Bearings Market |
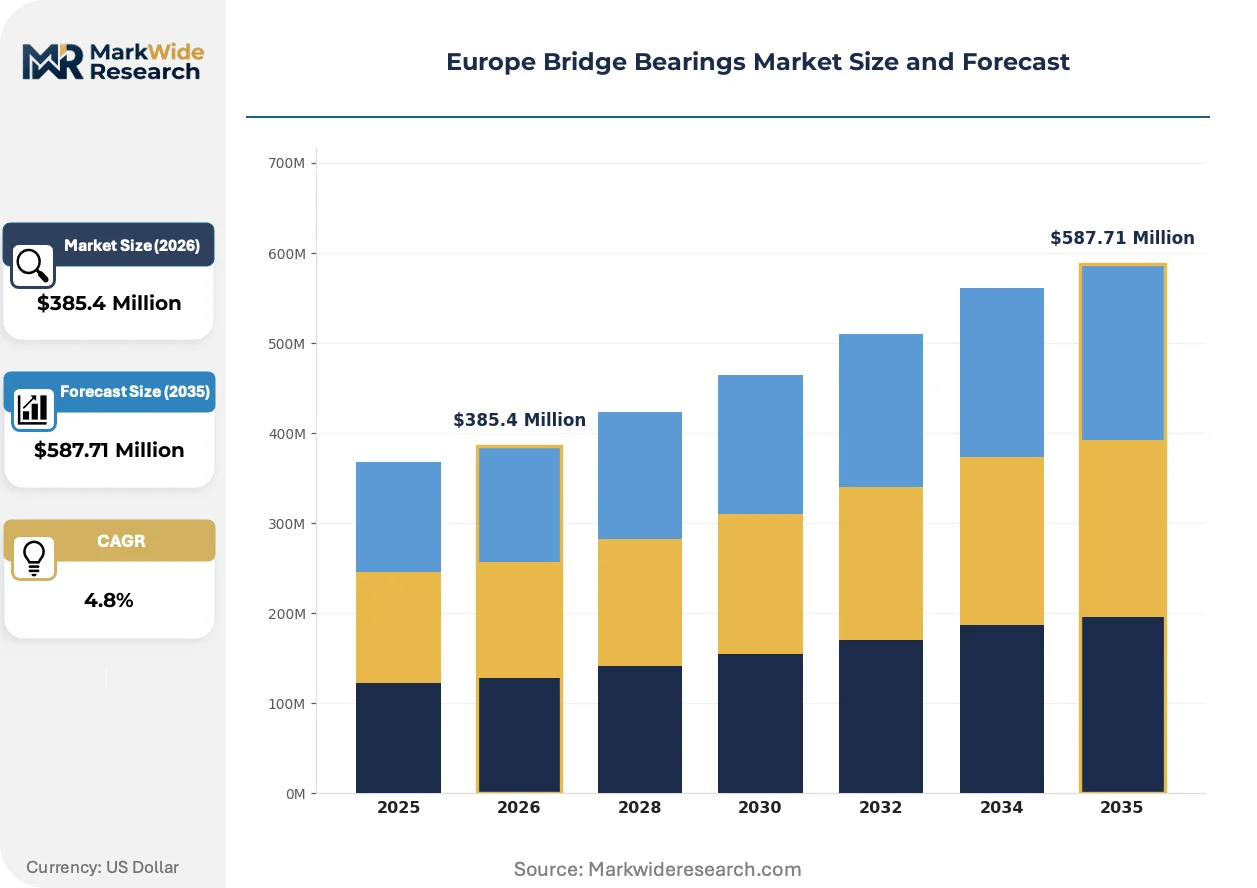
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $587.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Elastomeric, Pot, Metal, Sliding Application Area: Highway Bridges, Rail Bridges, Pedestrian Bridges, Industrial Structures Load Rating: Moderate, High, Extra High, Special Loads Installation Method: Precast, Cast-in-Place, Field-Bonded, Replacement |
| Companies Covered | Gumba GmbH & Co. KG, VICODA, Mageba SA, VSL International, Granor Rubber & Engineering, Trelleborg, Ekspan Ltd., CCL, Freyssinet Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bridge Bearings Market Shifts & Advancements
Material substitution and regulatory compression are converging to reshape European bearing specification patterns. Engineers now prioritize lifecycle carbon metrics alongside mechanical performance, while procurement offices consolidate supplier relationships to manage compliance complexity.
PTFE-stainless steel sliding surface technology is consolidating market share across maintenance-critical installations. Norwegian and Scottish bridge authorities specify these configurations for remote locations where access costs dominate lifecycle economics. The shift is consolidating procurement volumes toward suppliers with integrated PTFE sintering and precision machining capabilities, compressing the viable vendor base for high-specification contracts.
The EU Green Deal's embodied carbon disclosure requirements are tightening material traceability obligations. Construction Product Regulation CE marking now demands documented carbon intensity for steel and elastomer inputs, forcing bearing manufacturers to requalify supply chains. German and Austrian rail operators have responded by inserting carbon thresholds directly into technical specifications, filtering tenders before price evaluation.
Asset owner procurement offices are bundling bearing supply with installation and 30-year maintenance commitments. French and Italian highway concessionaires have pioneered integrated service contracts that transfer performance risk to manufacturers. This restructuring is visible most acutely in Alpine tunnel projects, where single-source accountability reduces interface disputes between civil and mechanical contractors.
Europe Bridge Bearings Market Segmentation
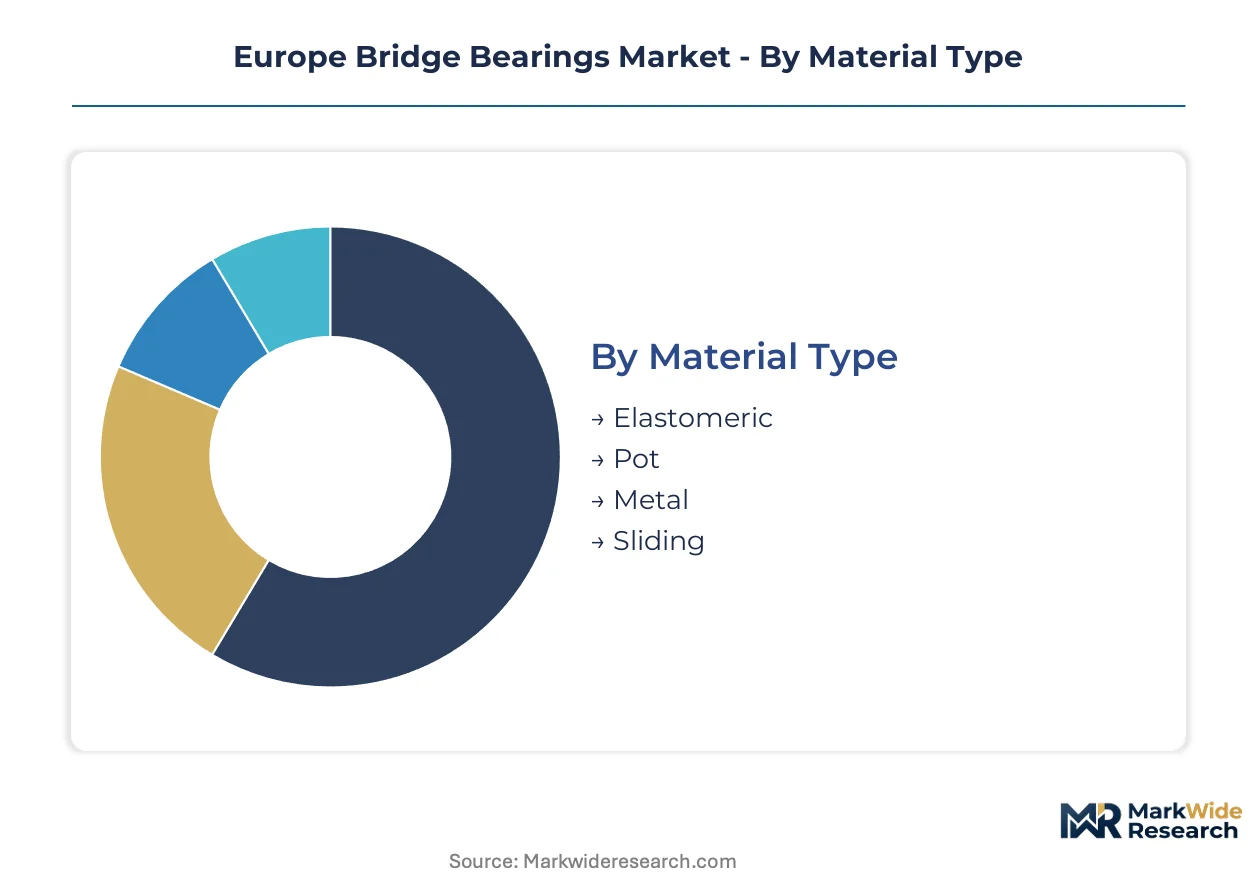
Bridge bearing specification across Europe fragments across material chemistry, structural application, and installation logistics. Procurement offices weight lifecycle carbon metrics against seismic performance requirements, compressing vendor eligibility while expanding contract complexity.
Material Type:
Rail corridor renewal cycles in Germany and France are accelerating material substitution decisions as engineers balance load capacity against embodied carbon thresholds.
- Elastomeric:Reinforced rubber-steel laminate construction dominates highway bridge applications across Central Europe. German federal procurement channels concentrate demand for moderate-load configurations, though ECHA REACH compliance is forcing reformulation of legacy compound recipes.
- Pot:Steel piston-and-cylinder assemblies with elastomeric discs handle extra-high loads in Alpine rail tunnels. Swiss and Austrian specifications for seismic resistance filter supply toward integrated manufacturers with precision machining capabilities.
- Metal:Steel-on-steel spherical bearings serve specialized industrial structures requiring multi-directional rotation capacity. Limited deployment concentrates in heavy manufacturing zones of northern Italy.
- Sliding:PTFE-stainless steel configurations deliver maintenance-free performance for inaccessible Norwegian fjord crossings and Scottish Highland bridges.
Volume placements concentrate in elastomeric bearings for highway renewal; the faster expansion belongs to sliding configurations as remote infrastructure specifications tighten.
Application Area:
Asset owner risk transfer strategies are reshaping contract bundling across bridge categories, with rail operators pioneering integrated supply-maintenance agreements.
- Highway Bridges:Moderate-load elastomeric bearings dominate replacement cycles across French and Italian concession networks. Procurement offices now bundle 30-year maintenance commitments with initial supply contracts.
- Rail Bridges:Extra-high-load pot bearings face stringent seismic qualification in Alpine corridors. German federal programs and French SNCF renewal budgets concentrate demand for certified high-performance systems.
- Pedestrian Bridges:Lightweight elastomeric configurations serve urban footbridge programs in Dutch and Belgian cities. Aesthetic integration requirements filter toward specialized architectural bearing suppliers.
- Industrial Structures:Custom metal bearings accommodate heavy machinery vibration and thermal cycling in German chemical processing and steel manufacturing facilities.
Contract value concentrates in rail bridge rehabilitation; pedestrian bridge specifications are gaining share fastest as urban active-transport infrastructure expands.
Load Rating:
Engineering offices are consolidating specification tiers as Eurocode EN 1337 revisions compress design safety margins and accelerate qualification cycles.
- Moderate:Standard elastomeric bearings serve routine highway and pedestrian applications. Polish and Romanian highway expansion programs under EU Cohesion Fund allocations concentrate procurement volumes.
- High:Reinforced pot configurations handle primary rail corridors and heavy industrial structures. CE marking validation under Construction Products Regulation governs supplier eligibility.
- Extra High:Specialized pot and sliding systems accommodate Alpine tunnel seismic loads and heavy freight rail. Swiss national protocols impose extended qualification timelines that delay contract execution.
- Special Loads:Custom-engineered bearings address unique geometric constraints or extreme thermal ranges in Norwegian Arctic crossings and high-altitude Italian viaducts.
Procurement volume clusters in moderate-load highway specifications; extra-high-load configurations are climbing fastest as Alpine rail investment accelerates.
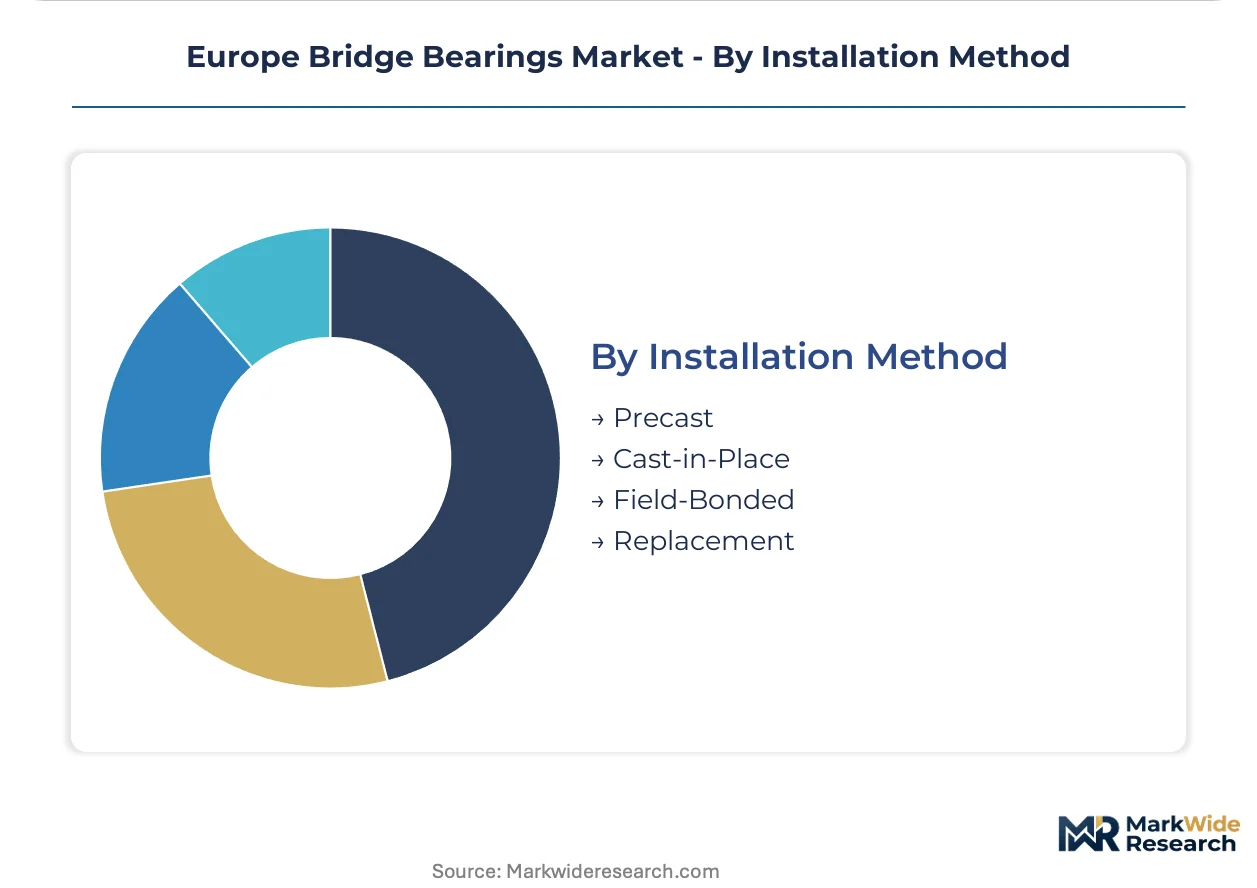
Installation Method:
Contractor capability scarcity across Southeast Europe and Baltic states is filtering project awards toward suppliers with integrated installation services or certified partnership networks.
- Precast:Factory-integrated bearings simplify quality control for standardized highway bridge components. German and Austrian precast concrete suppliers dominate regional supply chains.
- Cast-in-Place:Specialized anchoring techniques for pot bearings face limited trained contractor availability outside German-speaking markets. Gumba GmbH anchors presence through installation service bundling.
- Field-Bonded:Elastomeric bearing replacement without superstructure lifting serves operational rail corridors. Night-window installation protocols in France and Belgium compress allowable work durations.
- Replacement:Retrofit configurations accommodate legacy substructure geometries while upgrading load capacity. Italian and Swiss seismic retrofit programs concentrate demand for engineered adaptation solutions.
Project flow concentrates in precast installation for new construction; replacement methodologies are gaining traction fastest as aging bridge inventories force intervention decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alpine corridor tax incentives and EU Cohesion Fund allocations are concentrating bridge bearing demand across Central European manufacturing zones and Nordic infrastructure corridors.
Germany
Federal rail bridge replacement programs and autobahn rehabilitation cycles are accelerating procurement for elastomeric and pot bearing systems. The KBA and federal transport ministry enforce strict CE marking validation under Construction Products Regulation for all structural components. Industrial concentration clusters in North Rhine-Westphalia and Bavaria, where precast concrete suppliers integrate bearing procurement into standardized highway component manufacturing.
Switzerland
Alpine rail tunnel seismic requirements and Gotthard Base Corridor maintenance cycles are expanding demand for extra-high-load pot bearings. Swissmedic and federal transport authorities impose supplementary national qualification protocols that extend certification timelines. Precision machining capabilities concentrate in the Zurich industrial belt and Aargau manufacturing corridor, where integrated manufacturers dominate high-specification contracts.
France
SNCF rail network renewal budgets and highway concession 30-year maintenance bundling are reshaping procurement patterns toward integrated supply-service contracts. ANSM and transport ministry regulations align with Eurocode EN 1337 updates to filter supplier eligibility. Demand concentrates in the Île-de-France rail hub and Rhône-Alpes Alpine crossings, where concession operators pioneer performance-risk transfer agreements.
Italy
Seismic retrofit programs for aging viaducts and Alpine tunnel upgrades are driving specification of certified high-performance bearings. National civil protection protocols and infrastructure ministry requirements impose extended qualification periods for seismic-resistant designs. Industrial activity clusters in Lombardy and Piedmont, where engineering offices consolidate specification tiers around lifecycle carbon metrics.
Poland
EU Cohesion Fund highway expansion and trans-European corridor completion are opening procurement windows in previously underpenetrated markets. National road authority technical specifications adopt Eurocode EN 1337 standards with phased compliance deadlines. Manufacturing and logistics activity concentrates in the Silesian industrial region and Warsaw metropolitan construction zones, where precast installation methods dominate new bridge construction.
Europe Bridge Bearings Market Competitive Landscape
Top-tier vendors anchor high-load pot bearing production for Alpine rail corridors, while mid-tier specialists capture highway elastomeric volumes through installation service bundling. The vendor base stratifies across integrated precision manufacturers, compound R&D houses, and installation-centric service providers. Dominant competitive moves include backward integration into PTFE sintering capabilities and geographic expansion through certified partnership networks in Southeast Europe.
Among Swiss and German integrated manufacturers, Mageba SA and Gumba GmbH & Co. KG exemplify the precision machining and installation service archetypes respectively. Trelleborg occupies a position representing advanced elastomeric compound development for vibration-dampening specifications. These three anchors illustrate how competitive positioning fragments across material chemistry expertise, manufacturing scale, and field service capability rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| Gumba GmbH & Co. KG |
| VICODA |
| Mageba SA |
| VSL International |
| Granor Rubber & Engineering |
| Trelleborg |
| Ekspan Ltd. |
| CCL |
| Freyssinet Limited |
| Others |
Supply & Pricing Matrix
PTFE sintering technology adoption among Swiss and German manufacturers is compressing production economics for high-specification sliding bearings while concentrating supply relationships around integrated precision machining clusters. This dual effect rewards backward-integrated producers with carbon-compliant steel sourcing and squeezes compound-dependent elastomeric specialists facing REACH reformulation costs.
Pricing Analysis
Short-lead-time premiums for seismic-qualified pot bearings in Alpine corridors command substantial markups over standard highway elastomeric configurations. Project-based contract structures dominate, with price differentiation resting on CE marking tier and installation service bundling. Cost compression in moderate-load highway segments is intensifying because Polish and Romanian procurement offices prioritize unit economics over lifecycle metrics. Municipal bridge authorities exhibit highest price sensitivity; rail operators with 30-year maintenance bundling demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for legacy pot bearings from Alpine tunnel maintenance cycles are creating secondary material streams that supplement virgin PTFE and stainless steel inputs. Geographic concentration centers on Switzerland, Germany, and Austria for precision-machined high-load components. Raw material dependencies draw from Swedish low-carbon steel, Italian stainless producers, and specialized elastomer compounders in the Netherlands. Single-source vulnerability persists in seismic disc elastomer formulations qualified under Swissmedic protocols. Distribution runs through precast concrete suppliers in German-speaking markets and certified installation contractors in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around carbon-compliant integrated manufacturers, with EU taxonomy alignment rules forcing compound-dependent specialists toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from REACH-compliant elastomer reformulation by securing captive PTFE sintering capacity and carbon-verified steel supply agreements. Defensive consolidation moves should prioritize German and Austrian rail contractor networks before EU Green Deal procurement filters tighten supplier pools further. For New Entrants and Emerging Players: The price-point gap between premium Alpine seismic bearings and economy highway elastomerics offers white-space entry through Polish and Romanian Cohesion Fund corridors. Target moderate-load precast installation segments with CE marking investment and certified partnership networks in Southeast Europe where contractor scarcity fragments incumbent control. For Investors and Strategic Acquirers: Re-rating potential sits with Swiss and German precision manufacturers holding integrated machining and carbon-compliant steel sourcing given pending EU taxonomy threshold enforcement. Acquisition focus should center on mid-cap specialists with seismic qualification pipelines and installed maintenance contract backlogs. The signal to watch is Italian and Swiss national protocol acceleration timelines as contract execution delays compress valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTFE Sintering | Captive supply of low-friction surfaces reduces dependency on Swiss specialty chemical suppliers. |
| Carbon-Verified Steel Supply Agreement | EU taxonomy alignment rewards documented low-carbon intensity for Alpine rail procurement. |
| Seismic Qualification Pipeline Investment | Swissmedic and Italian civil protection protocols filter contract eligibility toward certified manufacturers. |
| Installation Service Network Expansion | Certified contractor partnerships in Poland and Romania capture Cohesion Fund highway expansion. |
| 30-Year Maintenance Contract Bundling | French and Italian concession operators transfer performance risk through integrated supply-service agreements. |
Research Methodology
Trade association publications, Eurocode EN 1337 technical committees, and ECHA regulatory filings formed the secondary backbone, supplemented by customs data for steel and elastomer inputs. Primary interviews with bridge procurement officers at German federal transport agencies, Swiss rail infrastructure planners, French highway concession operators, and Italian seismic engineering consultants validated demand assumptions. Bottom-up and top-down triangulation cross-checked volume estimates against capacity disclosures from precision machining clusters.
Bottom-up modeling anchored forecasts to project-level procurement pipelines across Alpine corridor rail renewals and Central European highway expansion. Segmentation dimensions included material type, load rating tier, application area, and installation methodology. CAGRs were derived from weighted project timelines and regulatory phase-in schedules. Industry-specific inputs encompassed seismic qualification timeline data from Swissmedic and embodied carbon threshold evolution under EU Green Deal implementation.
Inputs from Italian and Swiss national protocol disclosure channels were available through the study window; gaps in real-time contractor capacity data from Baltic states and Southeast Europe introduce uncertainty bands around installation service revenue forecasts. Forecasts reflect documented assumptions regarding regulatory phase-in and commodity price stabilization. Material deviation in EU taxonomy enforcement timing or Alpine rail budget allocation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Translucent Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
High Strength Concrete Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
UK Facade Market