
 Underwater Concrete Market | 2026-2036
Underwater Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Underwater Concrete Market Intelligence
Alkali-activated binders are displacing conventional Portland cement in select marine pours, and this material transition is realigning cost structures for contractors bidding on North Sea infrastructure. Sika AG leverages its admixture portfolio to anchor premium positioning in anti-washout and self-leveling systems for tidal zone applications. Heidelberg Materials sustains geographic dominance through captive cement supply and coastal batching assets in Northern Europe. BASF SE differentiates via R&D intensity in rheology-modifying polymers that extend placement windows in cold-water environments.
Underwater concrete denotes cementitious mixtures engineered for placement and curing in submerged conditions, typically incorporating anti-washout admixtures, microsilica, and controlled slump flow exceeding 500 mm to prevent segregation during free-fall or tremie delivery. Its primary commercial purpose is to form durable structural elements where dewatering proves technically unfeasible or economically prohibitive. Ready-mix dominates volume throughput owing to batch-plant proximity at major port clusters, while shotcrete gains share in tunnel linings and scour repair where access constraints favor pneumatic placement. Fiber-reinforced concrete commands margin premiums for offshore structures subject to cyclic wave loading, whereas self-consolidating formulations reduce labor intensity in deep tremie pours.
EMA construction product regulations, EU F-Gas restrictions on coastal equipment, and national marine licensing regimes in Germany and the Netherlands collectively elevate compliance burdens for admixture suppliers and contractors. These frameworks shape demand by mandating extended service-life predictions and restricting leachable chloride thresholds in tidal exposure zones. Stakeholders must monitor evolving carbon-border adjustments and coastal resilience bonds that will redirect procurement criteria toward low-carbon binder systems and certified durability performance.
Market Dynamics
Offshore wind farm procurement is compressing placement windows and demanding anti-washout admixtures that cure reliably in North Sea tidal zones, forcing contractors to restructure batching logistics around coastal port clusters.
Growth Catalysts
- EU Green Deal coastal mandates:The Netherlands, Germany, and Denmark now require extended service-life predictions for marine infrastructure, tightening specifications for low-carbon binder systems in tidal exposure zones.
- Alkali-activated binder chemistry:This material transition reduces embodied carbon in select marine pours and realigns cost structures for contractors bidding on North Sea infrastructure contracts.
- Port cluster batching concentration:Ready-mix throughput concentrates at major Northern European port facilities, reducing transport distance to offshore wind foundation sites.
Market Restraints
- Anti-washout admixture supply concentration:Specialty chemical production for marine-grade rheology modifiers concentrates among limited European suppliers, creating input vulnerability for contractors.
- EU F-Gas restrictions:Coastal placement equipment faces refrigerant compliance burdens that elevate maintenance costs and compress equipment availability windows during peak pour seasons.
- Geopolymer technical limitations:Alkali-activated binders exhibit variable early-strength development in cold-water environments, restricting their deployment in deep tremie applications.
Strategic Opportunities
- Tidal energy foundation specifications:Emerging turbine anchoring projects in Scottish and French coastal zones create demand for fiber-reinforced concrete formulations resistant to cyclic wave loading.
- Carbon-border adjustment mechanisms:EU CBAM implementation redirects procurement criteria toward certified low-carbon binder systems, rewarding early adopters with compliance advantages.
- Shotcrete channel expansion:Pneumatic placement gains share in tunnel linings and scour repair where access constraints favor mobile batching over fixed plant infrastructure.
Industry Challenges
- Marine concrete technologist scarcity:Specialized expertise in tremie pour sequencing and anti-washout admixture dosing remains concentrated among aging Northern European engineering cadres.
- EMA construction product certification timelines:Extended durability testing protocols for submerged applications delay product registration and compress bidding windows for novel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underwater Concrete Market |
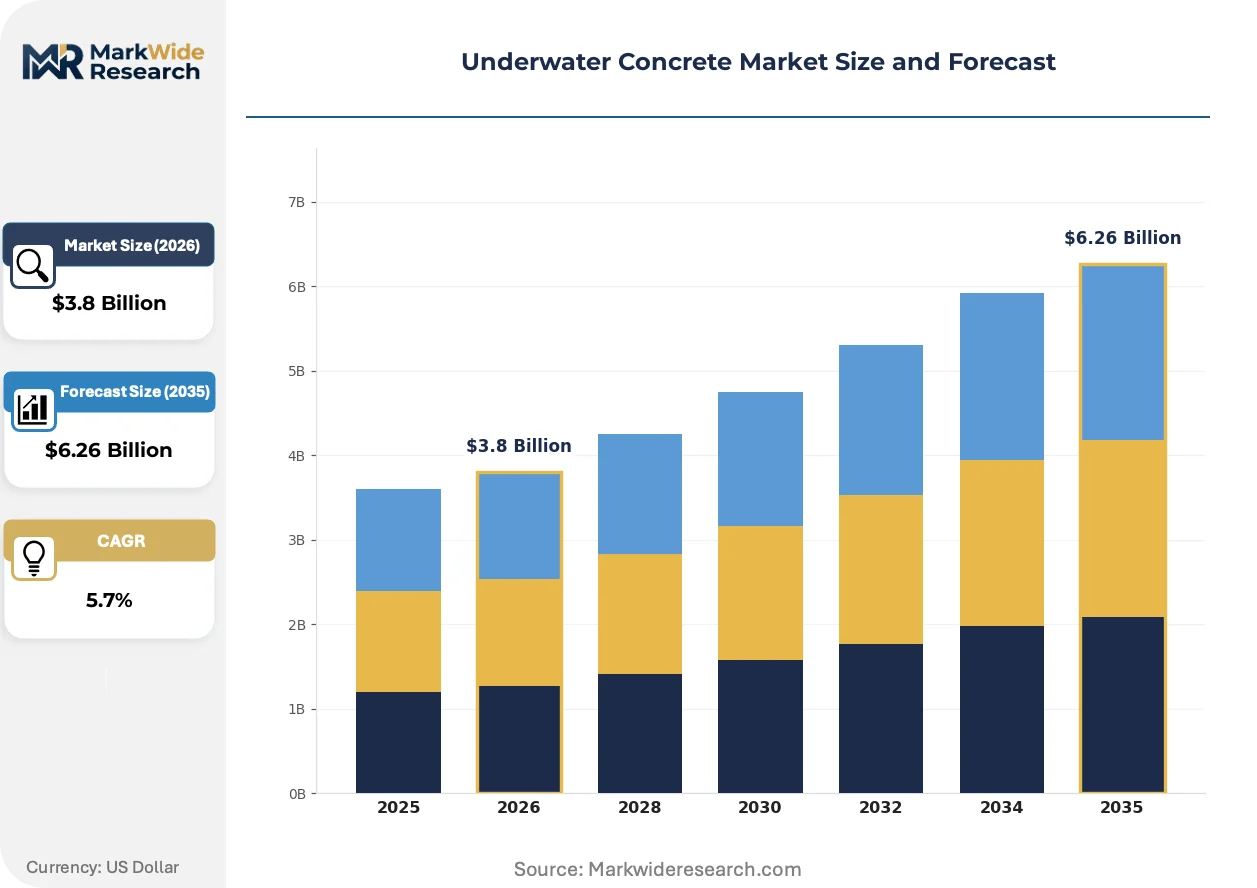
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-Mix, Shotcrete, Grout, Precast Application: Marine Construction, Underwater Repair, Dams, Offshore Structures End User: Construction Companies, Marine Engineers, Government Agencies, Contractors Technology: High-Performance Concrete, Self-Consolidating Concrete, Fiber-Reinforced Concrete, Lightweight Concrete |
| Companies Covered | Conmix Ltd, Mapei S.p.A., Sika AG, Five Star Products, Inc., BASF SE, Cemex S.A.B. de C.V., Rockbond SCP Ltd, RPM International Inc., Heidelberg Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underwater Concrete Market Strategic Shifts & Innovations
Material chemistry advances and procurement restructuring are converging to redefine competitive positioning in marine-grade concrete supply, with durability certification and carbon intensity emerging as primary differentiation vectors.
Alkali-activated binders are consolidating their role in select North Sea marine pours as contractors seek Portland cement alternatives that satisfy EU Green Deal carbon thresholds. Offshore wind developers in Danish and German waters are specifying these systems for non-structural elements, compressing the timeline for conventional binder dominance in tidal zone applications.
REACH and EU F-Gas regulations are tightening compliance burdens for admixture suppliers serving coastal infrastructure markets. The ECHA restriction roadmap on persistent organic pollutants is forcing reformulation of certain rheology-modifying polymers, with marine contractors in the Netherlands and Germany absorbing testing costs for replacement chemistries.
Buyer concentration among major offshore wind developers is compressing supplier negotiation cycles and unbundling after-sales technical support from material supply contracts. Danish and British project aggregators now demand dedicated batching assets within specified port radii, reshaping distribution economics for ready-mix producers serving North Sea foundation markets.
Underwater Concrete Market Segmentation
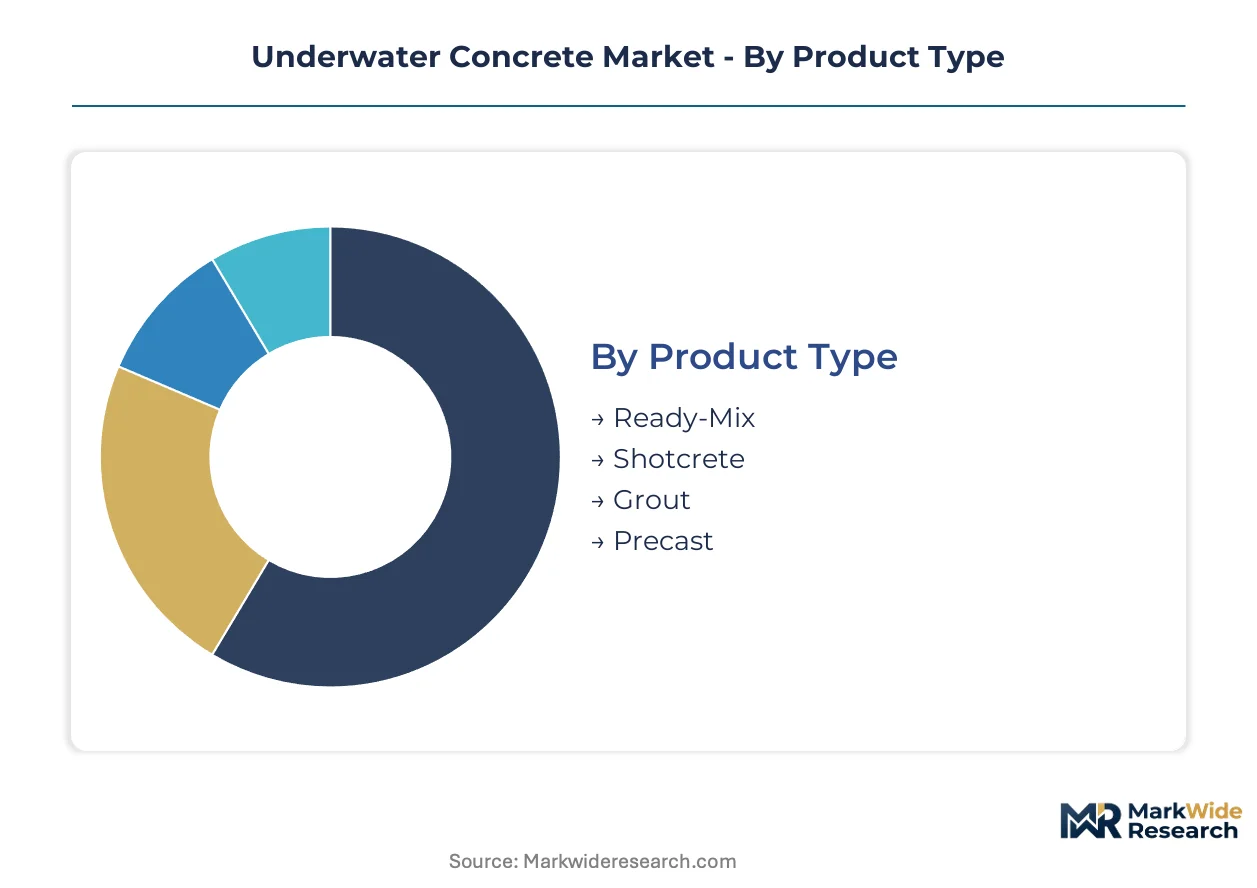
Underwater concrete procurement splits sharply between high-volume commodity pours and premium formulations commanding technical premiums. Contractors select product categories based on placement method constraints, while technology tiers separate cost-driven infrastructure from durability-critical offshore assets.
Product Type:
Ready-mix dominates tonnage through coastal batch-plant proximity, while shotcrete and specialty grouts capture margin in constrained-access applications.
- Ready-Mix:Batch-plant production with controlled slump flow exceeding 500 mm and anti-washout admixtures for tremie delivery. Demand concentrates at Northern European port clusters serving offshore wind foundation contracts, where transport radius economics favor fixed-plant infrastructure.
- Shotcrete:Pneumatic placement of cementitious mixtures through hoses at high velocity, enabling overhead and vertical application without formwork. Scottish and Norwegian tunnel contractors specify this method for scour repair and subsea infrastructure rehabilitation where tremie access proves impossible.
- Grout:High-fluidity cementitious slurry for void filling, pile grouting, and structural connections in marine environments.
- Precast:Factory-cured concrete elements for modular deployment in tidal zones and breakwater construction.
Mature deployment sits with Ready-Mix. Newer deployment is concentrated in Shotcrete for mobile repair applications.
Application:
Offshore wind procurement now exceeds traditional marine construction in annual pour volumes, reshaping contractor specialization requirements.
- Marine Construction:Port facilities, breakwaters, and coastal defense structures requiring mass concrete placement in tidal exposure zones. Dutch and German government agencies drive specification tightening through EU Green Deal coastal mandates, extending service-life predictions for submerged elements.
- Offshore Structures:Wind turbine foundations, oil platform substructures, and tidal energy anchoring systems subject to cyclic wave loading. Danish and British developers compress placement windows and mandate fiber-reinforced formulations for monopile and jacket foundation applications.
- Underwater Repair:Scour protection, structural rehabilitation, and emergency patching of existing marine infrastructure.
- Dams:Underwater concrete placement for hydroelectric facility maintenance and new construction in reservoir environments.
Volume leadership belongs to Marine Construction. Steepest expansion trajectory characterizes Offshore Structures.
End User:
Buyer concentration among major offshore wind developers compresses supplier negotiation cycles and unbundles technical support from material contracts.
- Construction Companies:General contractors executing marine infrastructure with captive batching assets and established admixture supplier relationships.
- Marine Engineers:Specialized firms designing placement sequencing and durability specifications for complex submerged environments.
- Government Agencies:Dutch Rijkswaterstaat, German coastal authorities, and Danish maritime regulators mandating compliance with EMA construction product regulations and extended service-life predictions.
- Contractors:Marine specialists bidding on North Sea foundation work with dedicated tremie equipment and anti-washout admixture expertise.
Procurement authority concentrates with Government Agencies. Technical specification influence rests with Marine Engineers.
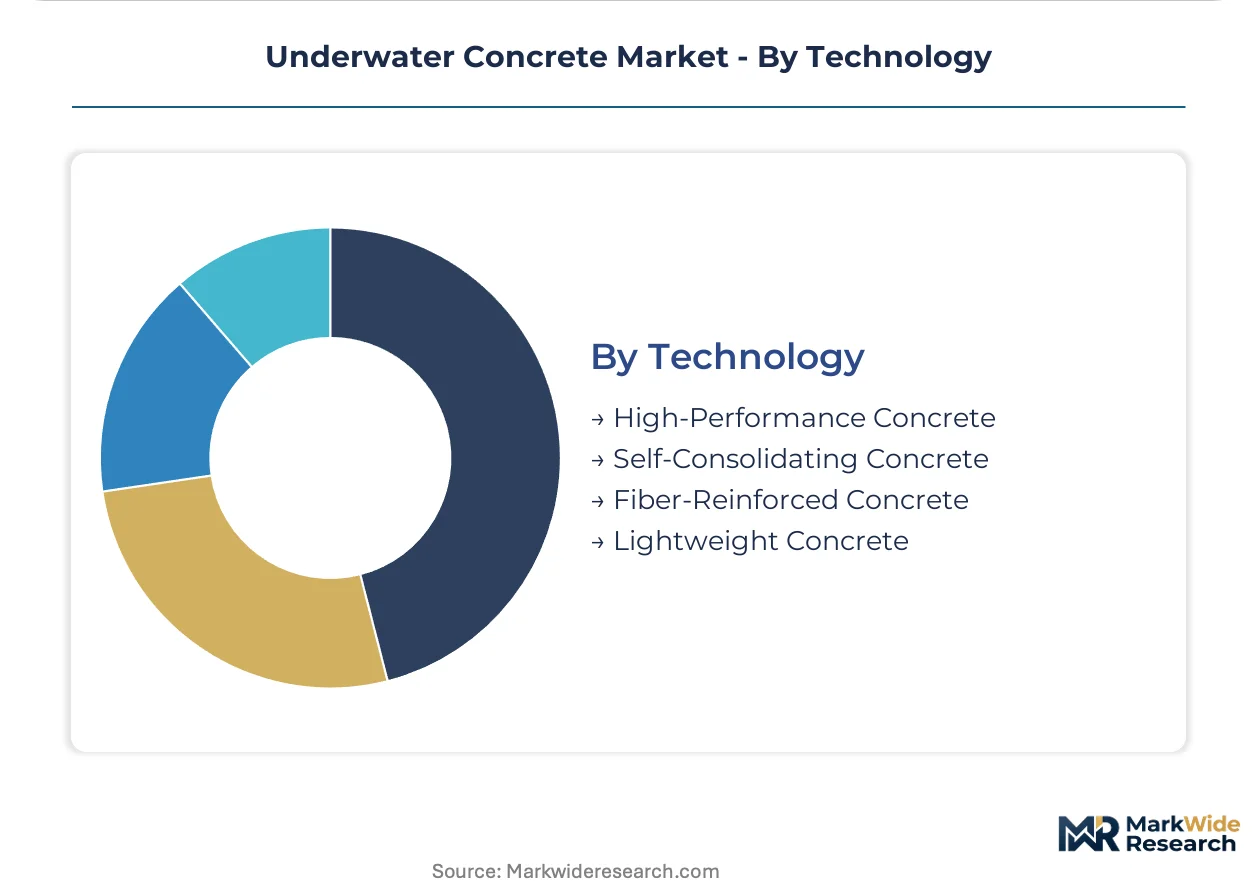
Technology:
Material chemistry advances are consolidating competitive differentiation around carbon intensity and durability certification.
- Self-Consolidating Concrete:Highly flowable mixtures requiring no mechanical vibration, reducing labor intensity in deep tremie pours for offshore wind foundations. North Sea contractors specify this technology for monopile base grouting where placement access is restricted.
- Fiber-Reinforced Concrete:Steel or synthetic fiber additions improving crack resistance and fatigue performance under cyclic wave loading. Tidal energy projects in Scottish and French coastal zones specify these formulations for turbine anchoring structures.
- High-Performance Concrete:Dense microstructure achieving low permeability and extended durability in submerged service.
- Lightweight Concrete:Reduced density formulations for floating structures and applications where dead load minimization proves critical.
Specification penetration is deepest with Self-Consolidating Concrete. Fastest specification growth characterizes Fiber-Reinforced Concrete.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind foundation procurement concentrates pour volumes in Northern European port clusters, where coastal batching assets and anti-washout admixture supply chains align with tidal zone placement requirements. Contractors restructure logistics around specific harbor facilities to compress transport radii and meet compressed construction windows.
Germany
North Sea offshore wind expansion and Elbe River port modernization drive specification tightening for self-consolidating concrete in monopile base grouting. The Federal Maritime and Hydrographic Agency mandates extended durability testing for submerged structural elements under national marine licensing regimes. Bremerhaven and Cuxhaven anchor the heaviest batching concentration, with contractors positioning dedicated tremie equipment for foundation pours.
Netherlands
Rijkswaterstaat coastal protection mandates and Maasvlakte port expansion multiply annual pour volumes for marine-grade formulations. EU Green Deal implementation requires low-carbon binder systems in all publicly procured tidal infrastructure, accelerating alkali-activated chemistry adoption. Rotterdam port clusters concentrate ready-mix supply capacity within specified radii of North Sea wind farm sites.
Denmark
Kriegers Flak and Thor offshore wind zones compress placement seasons and demand fiber-reinforced concrete for jacket foundation applications. Danish Energy Agency procurement guidelines specify anti-washout performance thresholds for cold-water curing environments. Esbjerg harbor facilities host the densest contractor equipment staging for Baltic and North Sea foundation work.
United Kingdom
Dogger Bank and Scottish tidal energy projects specify fiber-reinforced formulations resistant to cyclic wave loading on turbine anchoring structures. Marine Management Organisation licensing extends service-life prediction requirements for submerged concrete elements. Aberdeen and Great Yarmouth port infrastructure supports the mobile batching systems deployed for remote foundation sites.
France
Saint-Nazaire offshore wind zones and English Channel port reinforcement create demand for shotcrete in scour repair applications where tremie access proves impossible. Agence de l'environnement et de la maîtrise de l'énergie regulations tighten leachable chloride thresholds in tidal exposure zones. Dunkirk and Le Havre coastal facilities concentrate pneumatic placement expertise for constrained-access marine rehabilitation.
Underwater Concrete Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with admixture chemistry providers commanding premium positioning against commodity batching operators. The market structures around three tiers: multinational chemical conglomerates with marine-grade R&D pipelines, regional ready-mix producers with captive coastal assets, and specialized grout manufacturers serving repair niches. Strategic moves concentrate on backward integration into binder supply and geographic clustering around North Sea port infrastructure.
Within the multinational chemical tier, Sika AG and BASF SE exemplify premium positioning through rheology-modifying polymer portfolios. Heidelberg Materials anchors the integrated producer archetype with captive cement supply and coastal batching concentration. Among specialized admixture developers, Mapei S.p.A. occupies a position representing Italian formulation expertise in anti-washout systems.
| Leading Market Players |
|---|
| Conmix Ltd |
| Mapei S.p.A. |
| Sika AG |
| Five Star Products, Inc. |
| BASF SE |
| Cemex S.A.B. de C.V. |
| Rockbond SCP Ltd |
| RPM International Inc. |
| Heidelberg Materials |
| Others |
Cost & Logistics Intelligence
Anti-washout admixture costs cascade through three distinct pricing tiers as specialty chemical production concentrates among limited European suppliers and contractors absorb formulation premiums for marine-grade rheology modifiers. Rotterdam port clusters and Bremerhaven batching facilities anchor geographic cost differentials, with transport radius economics compressing margins for ready-mix producers serving remote North Sea foundation sites.
Pricing Analysis
Volume leadership sits with commodity ready-mix pours for port expansion and coastal defense, while fiber-reinforced and self-consolidating formulations command technical premiums for offshore wind monopile applications. Price differentiation rests on certification grade under EMA construction product regulations and anti-washout performance tier validated for cold-water curing. Cost compression in standard-grade mixes is intensifying as buyer concentration among Danish and British offshore wind developers compresses supplier negotiation cycles. Government agencies exhibit lowest price sensitivity given EU Green Deal mandate compliance requirements, whereas independent marine contractors face acute margin pressure from fixed-plant infrastructure investments.
Supply Chain Analysis
Direct-to-contractor channels handle hyperscale offshore wind developer demand through dedicated batching assets positioned within specified port radii, while distributor networks serve smaller marine repair and scour protection contracts. Production gravity centers on Germany, the Netherlands, and Denmark, where coastal batching infrastructure aligns with North Sea tidal zone placement requirements. Raw material flows draw from captive cement supply at Heidelberg Materials facilities, imported microsilica, and specialty rheology-modifying polymers subject to ECHA restriction roadmaps. Single-source vulnerability concentrates in anti-washout admixture chemistry, where REACH compliance burdens force reformulation cycles that delay product registration and compress bidding windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas restrictions on coastal placement equipment function as a cost-of-compliance barrier that rewards incumbents with existing refrigerant-compliant fleets and certified maintenance infrastructure, effectively raising capital requirements for prospective market entrants.
For Market Incumbents: Deploy backward integration into alkali-activated binder supply to anchor carbon-border adjustment compliance advantages as EU CBAM implementation redirects procurement criteria. Capacity addition in Scottish and French tidal energy zones captures emerging fiber-reinforced concrete demand, while defending against specialty grout manufacturers encroaching on repair niches through pneumatic placement expertise. For New Entrants and Emerging Players: Alkali-activated chemistry R&D partnerships offer a technology-first wedge into Dutch and German government agency procurement mandated by EU Green Deal coastal protection requirements. Shotcrete channel expansion in Norwegian tunnel markets and French scour repair applications represents the most penetrable white-space, with mobile batching systems enabling go-to-market positioning without fixed-plant capital intensity. For Investors and Strategic Acquirers: Danish Energy Agency specification tightening for cold-water anti-washout performance is the leading indicator that durability certification assets will command acquisition premiums across the medium-term horizon. Coastal batching specialists with EMA-compliant product registrations and captive port infrastructure represent the target archetype, with early-strength development breakthroughs in geopolymer formulations serving as the critical signal to monitor for material chemistry inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Binder Supply | Captive alkali-activated chemistry production secures EU CBAM compliance advantages for North Sea contracts. |
| Capacity Expansion in Port Cluster Zones | Rotterdam and Bremerhaven batching assets reduce transport radii to offshore wind foundation sites. |
| Long-term Supply Agreement with Offshore Developers | Dogger Bank and Kriegers Flak project aggregators demand dedicated tremie equipment commitments. |
| Joint Venture for Anti-Washout Admixture R&D | ECHA restriction roadmap compliance accelerates replacement chemistry development timelines. |
| Geographic Expansion into Tidal Energy Zones | Scottish and French turbine anchoring projects specify fiber-reinforced formulations for cyclic wave loading. |
Research Approach
Multi-period observation of pour volume trends at Northern European port clusters, anti-washout admixture specification evolution, and offshore wind foundation contract awards anchored the trend analysis, supplemented by interviews with marine concrete technologists, coastal batching plant managers, procurement leads at offshore wind developers, and regulatory affairs specialists at admixture suppliers. Secondary validation drew from EMA construction product filings, EU F-Gas regulation implementation notices, Rijkswaterstaat procurement databases, and national marine licensing records in Germany and Denmark. Bottom-up project pipeline assessment and top-down market sizing triangulated volume and value estimates.
Input-output matrix modeling connected segmentation dimensions including product type, application category, end-user archetype, and technology tier to derive expansion trajectories across the projection horizon. CAGRs were computed from annual pour volume estimates at identified port clusters, with forecast inputs incorporating EU Green Deal implementation pace, offshore wind capacity auction schedules, and alkali-activated binder adoption curves in tidal exposure specifications.
Several conditions sit outside the modeled scope, including unannounced regulatory shifts in marine licensing regimes, breakthrough geopolymer formulations that overcome early-strength limitations in deep tremie applications, and macroeconomic disruptions to coastal infrastructure budgets. Forecasts reflect assumptions regarding continued EU Green Deal enforcement and stable anti-washout admixture supply availability. Practitioners should monitor ECHA restriction roadmap updates and carbon-border adjustment mechanism implementation details for early signals of procurement criteria redirection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine and Coastal Engineering
Wind Turbine Installation Vessel Market
Marine and Coastal Engineering
Asia-Pacific Offshore Crane Market
Marine and Coastal Engineering
Bilge Pump Market
Marine and Coastal Engineering
Marine Heat Exchanger Market
Marine and Coastal Engineering
Marine Cranes Market
Marine and Coastal Engineering
Work Barges Market
Marine and Coastal Engineering
Flood Control Sandbags Market
Marine and Coastal Engineering
Global Pipe Laying Vessel Market
Marine and Coastal Engineering
Ship Gangways Market
Marine and Coastal Engineering
Crane Barge Market
Marine and Coastal Engineering
Global Marine Ventilation Systems Market
Marine and Coastal Engineering
Middle East Offshore Crane Market
Marine and Coastal Engineering
Marine Manifolds and Risers Market
Marine and Coastal Engineering
Global Seismic Vessels Market
Marine and Coastal Engineering
Ship-To-Shore Cranes Market
Marine and Coastal Engineering
Seismic Support Vessels Market