
 Europe Timber Construction Connectors Market | 2026-2036
Europe Timber Construction Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Timber Construction Connectors Market Analytics
Subscription-based connector calibration and digital load-path verification is hardening into a standard service layer that timber engineers now bundle with hardware procurement. Simpson Strong-Tie Company, Inc. leverages its software-integrated catalog to anchor specification workflows across Nordic markets. Pitzl Metallbau GmbH & Co. KG sustains dominance in concealed timber-steel hybrid connections through precision-milled stainless steel grades. MiTek, Inc. competes with automated truss-plate manufacturing systems that occupy central European prefabrication hubs.
Timber construction connectors are mechanical fastening elements—nail plates, brackets, dowels, and proprietary connectors—typically fabricated from galvanized or stainless steel to transfer shear, tension, and moment loads between wood members. Their primary purpose is to ensure structural integrity in engineered wood systems while accommodating wood's hygroscopic movement and anisotropic strength properties. Nail plates and brackets command the largest volume share in residential timber framing, while composite-material connectors represent the fastest-growing material category as architects pursue corrosion resistance in exposed applications. Steel-grade connectors retain the deepest margin pools due to certification requirements under Eurocode 5 and manufacturer-specific ETA approvals.
CE marking under the Construction Products Regulation, Eurocode 5 design standards, and the EU Green Deal's building-renovation wave collectively shape product testing protocols and specification gatekeeping across member states. Germany's DIBt approvals and France's CSTB evaluations create divergent national certification paths that connector manufacturers must navigate for market access. Stakeholders should monitor how the EU Deforestation Regulation's traceability requirements will cascade into timber-grade documentation and connector compatibility standards for certified supply chains.
Market Dynamics
The EU Green Deal's embodied-carbon thresholds are redirecting specification decisions toward engineered wood systems, concentrating connector demand in Germany's mass-timber corridor where CLT and glulam building codes have matured fastest.
Growth Catalysts
- EU Green Deal building-renovation wave:The regulation mandates carbon-performance disclosure for new construction, pushing architects toward timber frames that require specialized connector systems for seismic and wind-load compliance.
- Multi-story residential timber frames:German, French, and Swedish developers are scaling 8-12 story CLT structures, creating sustained specification pull for moment-resisting brackets and heavy-duty dowel systems.
- Digital load-path verification:Subscription-based calibration services bundled with hardware procurement are hardening into standard practice among Nordic timber engineers.
Market Restraints
- Galvanized steel price volatility:Zinc input costs swing with energy-intensive smelting economics, compressing margin pools for standard nail-plate manufacturers serving price-sensitive residential contractors.
- Divergent national certification paths:Germany's DIBt approvals and France's CSTB evaluations create redundant testing burdens that delay product launches and fragment inventory requirements.
- Structural adhesive substitution:High-performance epoxy bonding systems are capturing select applications in concealed timber-steel hybrid joints, threatening stainless-steel connector volumes in premium architectural exposed connections.
Strategic Opportunities
- France's lagging mass-timber adoption:CSTB evaluation backlogs have slowed CLT code maturation relative to Germany, creating first-mover advantage for connector manufacturers who pre-certify to French protocols.
- EU Deforestation Regulation traceability:Certified timber-grade documentation requirements will cascade into connector compatibility standards, favoring suppliers with integrated chain-of-custody systems.
- BIM-to-fabrication workflows:Convergence of structural modeling software with CNC timber processing is enabling just-in-time connector kitting services that reduce on-site labor hours.
Industry Challenges
- Eurocode 5 specialist engineering shortage:Timber-specific structural design expertise concentrates in German and Austrian universities, creating talent bottlenecks for French and Italian project teams scaling mass-timber capabilities.
- ETA approval timeline compression:European Technical Assessment protocols for novel connector geometries require 18-24 month validation cycles that misalign with fast-track construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Timber Construction Connectors Market |
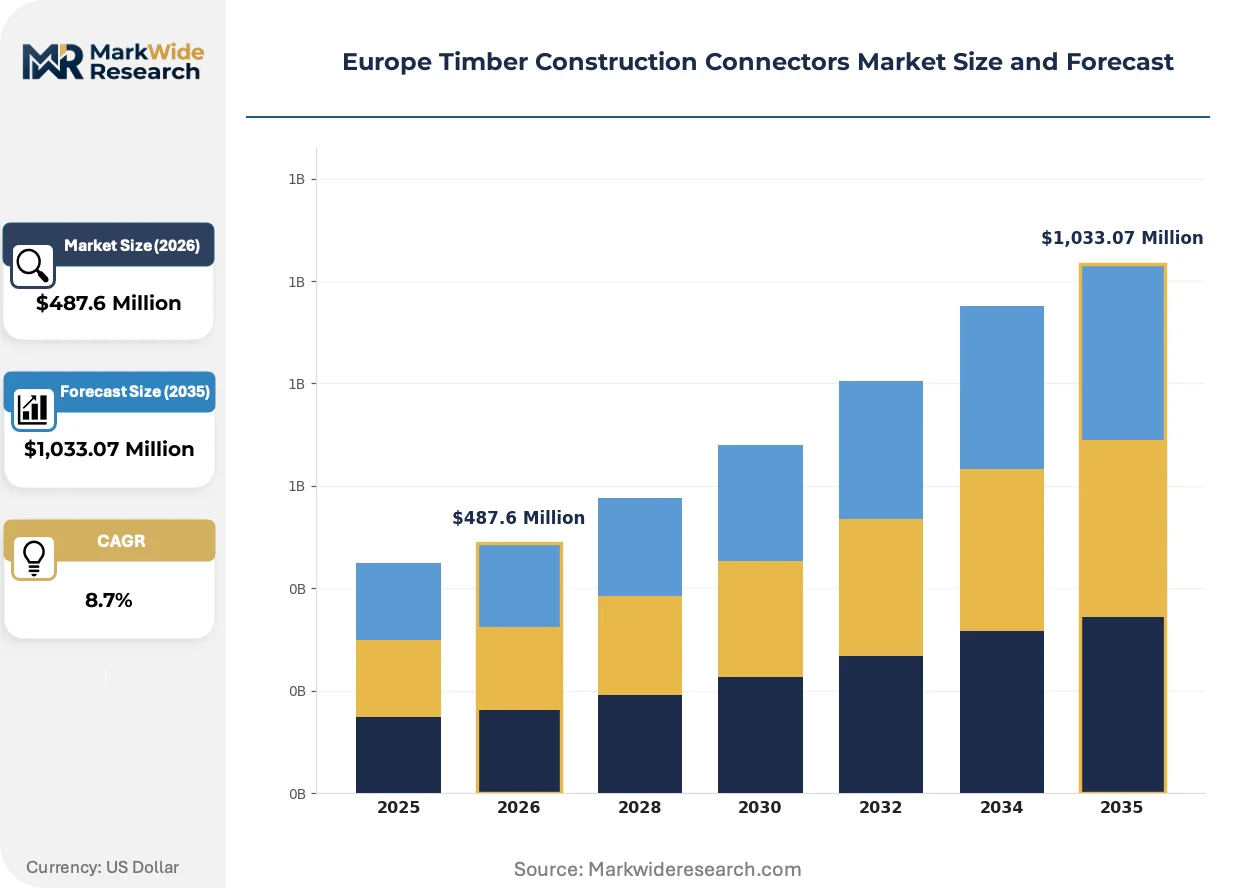
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nail Plates, Wooden Dowels, Brackets, Connectors Material: Steel, Aluminum, Plastic, Composite Application: Residential Buildings, Commercial Structures, Bridges, Eco-Friendly Projects End User: Contractors, Architects, Engineers, DIY Enthusiasts |
| Companies Covered | E.u.r.o.Tec GmbH, Cullen Timber Engineering Connectors, Simpson Strong-Tie Company, Inc., Pitzl Metallbau GmbH & Co. KG, GH Baubeschlöge GmbH, MiTek, Inc., BPC Building Products Limited, BeA Timber Connectors, Knapp GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Timber Construction Connectors Market Evolving Landscape
Digital integration and material science advances are restructuring how connectors are specified, procured, and deployed across European timber construction workflows.
Composite-material connectors fabricated from glass-fiber-reinforced polymers are overtaking stainless steel in exposed architectural applications where corrosion resistance and thermal bridging reduction outweigh premium pricing. Specifiers in Nordic coastal markets specify these systems for waterfront structures. The shift is compressing addressable volume for traditional steel-grade suppliers in aesthetic-critical segments.
CE marking under the Construction Products Regulation now requires enhanced fire-performance declarations for timber connectors used in buildings above four stories. Manufacturers must submit new test data to notified bodies. German producers with existing DIBt fire-ratings are adapting documentation fastest, while French suppliers face CSTB evaluation backlogs.
Specification authority is migrating from general contractors to timber engineering consultancies who bundle connector selection with structural liability. These firms in Austria and Switzerland now mandate digital load-path verification as a condition of hardware procurement. The model concentrates purchasing power among fewer decision-makers and rewards suppliers with integrated software-hardware offerings.
Europe Timber Construction Connectors Market Segmentation
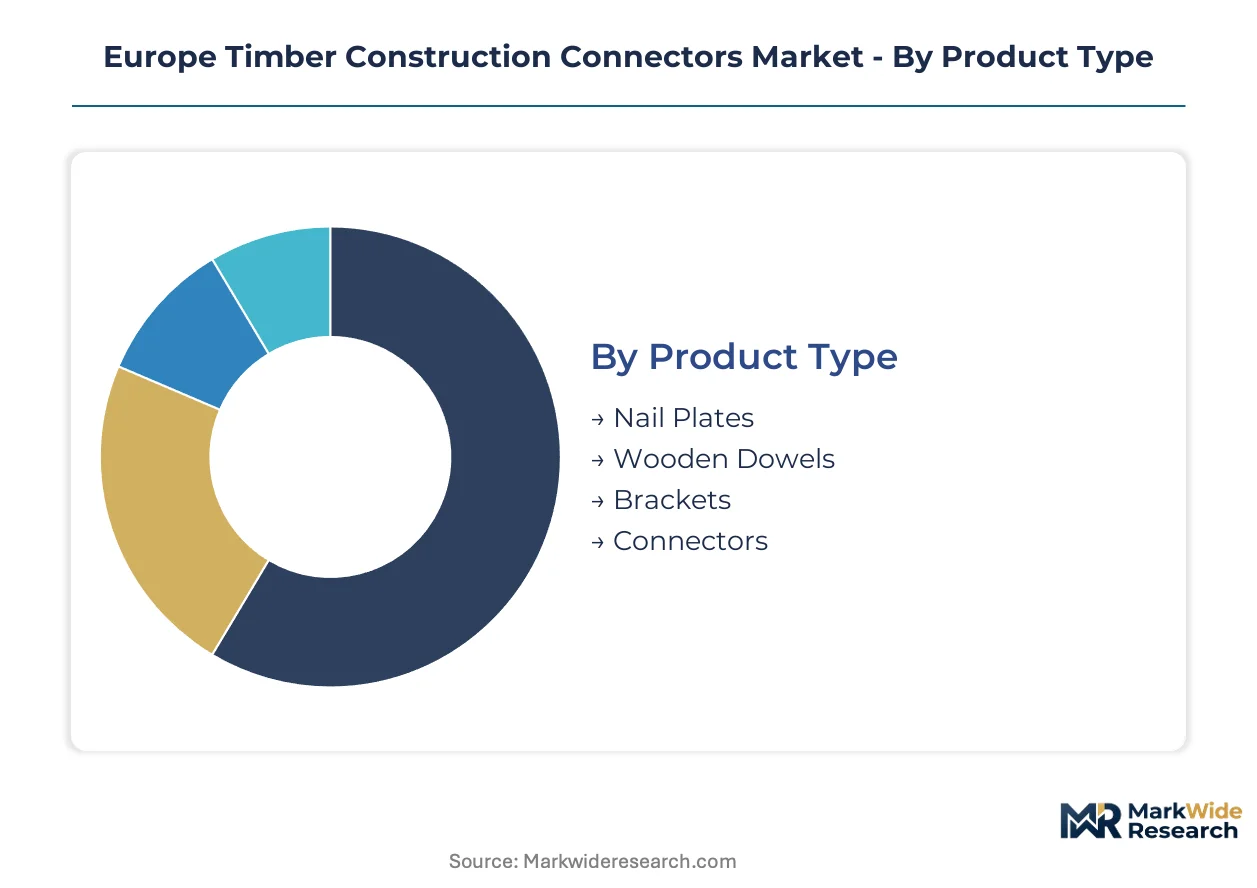
Connector specification in Europe's timber construction market fragments across product architectures, material grades, and project typologies. Each segment carries distinct certification burdens and margin structures that shape manufacturer positioning strategies.
Product Type:
Capital intensity concentrates in precision-forged brackets and moment-resisting connectors, where CNC machining and heat-treatment equipment demand seven-figure upfront investment. Stamped nail plates require lower tooling thresholds but compete on volume scale.
- Nail Plates:Stamped galvanized steel plates with integral teeth transfer shear loads between timber members in truss assemblies. German prefabrication hubs in Bavaria and Baden-Württemberg absorb the highest volumes as automated truss lines dominate residential framing procurement.
- Wooden Dowels:Cylindrical hardwood or engineered dowels provide concealed shear transfer in aesthetic-exposed mass-timber structures. French and Swiss architects specify these for visible CLT connections where metal hardware would compromise visual continuity, though Eurocode 5 design complexity limits contractor adoption.
- Brackets:Angle and T-configurations fabricated from bent steel plate accommodate beam-column joints in platform-frame construction. Nordic markets favor concealed stainless variants for coastal humidity exposure.
- Connectors:Proprietary multi-axis systems including moment-resisting bases and hold-down anchors anchor multi-story timber cores against seismic and wind overturning. German DIBt approvals gate market access for these safety-critical components.
Nail plates absorb the bulk of installed capacity; connectors are expanding most quickly as eight-to-twelve story timber structures proliferate.
Material:
Raw material procurement strategies diverge sharply across grades, with specialty stainless and fiber-reinforced composites requiring qualified supplier relationships that standard mild steel does not.
- Steel:Galvanized mild steel dominates volume production for nail plates and standard brackets, while austenitic stainless grades (AISI 304/316) command premium positioning in coastal Nordic specifications. CE marking and Eurocode 5 compliance testing create fixed cost barriers that favor integrated mills with in-house metallurgical laboratories.
- Aluminum:Extruded and cast aluminum alloys offer weight advantages for prefabricated panel systems where crane capacity constraints govern design. Italian and Austrian facade specialists specify these for lightweight curtain-wall connections in hybrid timber-steel structures.
- Plastic:Injection-molded thermoplastics serve temporary bracing and non-structural alignment fixtures in residential framing. Price sensitivity among French and Polish contractors limits specification to lowest-tier applications.
- Composite:Glass-fiber-reinforced polymer formulations deliver corrosion immunity and thermal break performance for exposed architectural joints. Norwegian and Swedish waterfront projects drive specification as building physics regulations tighten on thermal bridging.
Steel retains the deepest specification penetration; composite formulations are climbing the fastest as coastal markets harden corrosion-resistance requirements.
Application:
Project scale and structural liability exposure segment demand, with multi-story commercial work requiring engineered-to-order solutions that residential tract development does not.
- Residential Buildings:Platform-frame single-family and low-rise multifamily construction consumes standardized nail plates and angle brackets through prefabrication channels. German volume builders in the mass-timber corridor drive procurement consolidation toward approved manufacturer lists.
- Commercial Structures:Office and institutional mass-timber projects demand project-specific connector engineering for long-span beams and lateral force-resisting systems. French commercial developers face CSTB evaluation backlogs that delay hardware specification on fast-track tenders.
- Bridges:Timber deck and hybrid arch structures require fatigue-rated connections with documented performance under cyclic loading. Alpine markets in Austria and Switzerland maintain specialized supplier relationships for these infrastructure applications.
- Eco-Friendly Projects:Passive House and net-zero certifications drive specification toward low-embodied-carbon connection systems with environmental product declarations. Nordic public procurement mandates increasingly require documented supply-chain transparency for these segments.
Residential buildings anchor volume demand; commercial structures are gaining share fastest as mass-timber office construction scales.
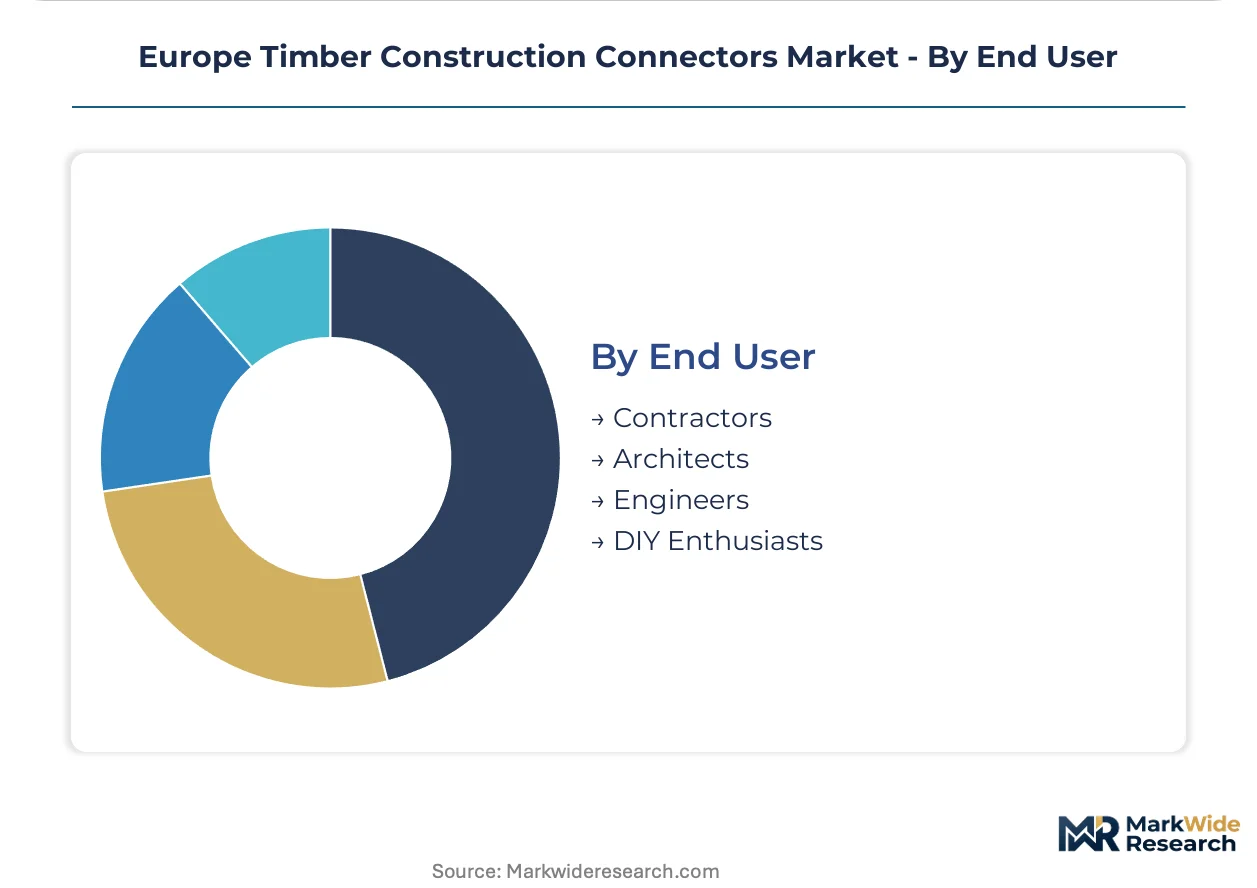
End User:
Technical authority and liability exposure concentrate specification power, with engineers and architects displacing contractors in high-complexity project decisions.
- Contractors:Volume homebuilders and regional timber-frame erectors procure standardized hardware through distribution with minimal engineering involvement. Price competition and inventory availability govern purchasing in German and Polish residential markets.
- Architects:Design-led practices in Switzerland and the Netherlands specify exposed connection aesthetics that mandate concealed or architecturally finished hardware. Visual mock-up approvals extend procurement timelines but sustain premium pricing.
- Engineers:Structural timber consultancies in Austria and Germany now bundle connector selection with liability-bearing design services. These firms mandate digital load-path verification and pre-approved manufacturer status as procurement preconditions.
- DIY Enthusiasts:Retail-channel consumers purchase basic brackets and fasteners for garden structures and small extensions. Big-box retailers in France and the UK stock limited CE-marked ranges with installation guidance.
Contractors move the highest hardware tonnage; engineers are consolidating specification authority fastest on complex projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's mass-timber corridor from Stuttgart to Munich anchors European connector specification volume, with Bavarian prefabrication hubs consuming precision-forged hardware for CLT and glulam assemblies.
Germany
Bavarian and Baden-Württemberg prefabrication lines drive nail-plate consumption for automated truss manufacturing. DIBt approvals under the Construction Products Regulation gate market access for moment-resisting connectors. Stuttgart's engineering consultancies bundle digital load-path verification with hardware procurement, concentrating specification authority among timber specialists.
France
Commercial developers in Île-de-France scale eight-to-twelve story mass-timber offices, creating demand for heavy-duty dowel systems. CSTB evaluation backlogs delay hardware specification on fast-track tenders. Auvergne-Rhône-Alpes timber-frame manufacturers face certification bottlenecks that advantage pre-approved German suppliers.
Sweden
Stockholm's waterfront residential towers specify glass-fiber-reinforced polymer connectors for corrosion immunity in Baltic Sea exposure. The National Board of Housing, Building and Planning enforces stringent thermal-bridge regulations that displace stainless steel in aesthetic-critical joints. Gothenburg engineering firms mandate environmental product declarations for public procurement compliance.
Austria
Alpine bridge and infrastructure projects in Tyrol and Vorarlberg require fatigue-rated timber-steel hybrid connections. Austrian timber consultancies in Graz and Innsbruck anchor specification workflows for Central European mass-timber exports. The country's technical universities concentrate Eurocode 5 expertise that engineers across the region license for complex projects.
Switzerland
Zurich and Geneva design practices specify concealed hardwood dowels for exposed CLT connections in luxury residential and institutional work. Swiss building physics regulations tighten on thermal performance, favoring composite connectors that reduce bridging. Basel-area timber processors integrate CNC fabrication with just-in-time hardware kitting for reduced site labor.
Europe Timber Construction Connectors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Europe's timber connector market. Integrated mills with in-house metallurgical laboratories dominate galvanized steel volume production, while specialized fabricators occupy premium niches requiring precision machining. The market structures around three archetypes: scale-driven stamped-metal suppliers, precision-forged specialists, and software-integrated system providers. Consolidation pressures favor manufacturers with captive DIBt and CSTB certification pipelines, while geographic expansion into lagging French and Italian markets represents the dominant competitive vector.
Among German-based fabricators, Pitzl Metallbau GmbH & Co. KG and GH Baubeschlöge GmbH exemplify the precision-forged specialist archetype, occupying positions in concealed timber-steel hybrid connections where stainless steel grades command premium positioning. Simpson Strong-Tie Company, Inc. represents the software-integrated system provider model, with its catalog anchoring specification workflows across Nordic markets where digital load-path verification has become standard procurement practice.
| Leading Market Players |
|---|
| E.u.r.o.Tec GmbH |
| Cullen Timber Engineering Connectors |
| Simpson Strong-Tie Company, Inc. |
| Pitzl Metallbau GmbH & Co. KG |
| GH Baubeschlöge GmbH |
| MiTek, Inc. |
| BPC Building Products Limited |
| BeA Timber Connectors |
| Knapp GmbH |
| Others |
Value Network & Pricing Analysis
London Metal Exchange zinc futures volatility cascades through galvanized steel input costs, fragmenting European timber connector markets into three pricing tiers that track certification burden and metallurgical grade rather than manufacturing geography alone.
Pricing Analysis
Margin tightening in standard nail-plate tiers reflects energy-intensive zinc smelting economics that German volume builders pass through to residential contractors. Three-tier pricing structure across DIBt-certified moment-resisting systems, CE-marked standard brackets, and non-certified economy hardware separates specification authority from price-sensitive procurement. Stainless steel grades for Nordic coastal exposure command widest spreads due to AISI 316 alloy premiums. French CSTB evaluation backlogs concentrate pricing power among pre-approved German suppliers.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Munich, and Hamburg anchor hub-and-spoke patterns that feed Bavarian prefabrication hubs with just-in-time precision. Supply concentrates in Germany, Austria, and Italy, with raw material draws from Swedish specialty steel mills and Turkish galvanized coil producers. Single-source vulnerability sits with DIBt-certified heat-treatment facilities that gate moment-resisting connector output. Distribution runs through timber engineering consultancies who bundle hardware procurement with digital verification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where CE marking and DIBt approval timelines erect barrier-to-entry moats that favor capitalized incumbents with captive certification pipelines.
For Market Incumbents: Extend software-integrated catalog offerings into French and Italian markets where CSTB evaluation backlogs delay competitor entry. Backward integration into specialty stainless steel grades secures margin pools against galvanized price volatility. Structural adhesive substitution in concealed hybrid joints threatens premium connector volumes; counter with enhanced fire-performance declarations for above-four-story applications. For New Entrants and Emerging Players: BIM-to-fabrication workflow integration offers entry into timber engineering consultancies who now mandate digital load-path verification. France's lagging mass-timber adoption presents the most penetrable geography; pre-certification to CSTB protocols before commercial scale-up creates first-mover positioning. Target kitting services that reduce on-site labor hours for fast-track commercial tenders. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-forged specialists with existing DIBt fire-ratings in Germany's mass-timber corridor. Long-term viability hinges on consolidation of specification authority among timber engineering consultancies rather than contractor channels. Watch EU Deforestation Regulation traceability implementation as inflection indicator for integrated chain-of-custody systems.| Strategic Initiative | Industry Significance |
|---|---|
| DIBt Certification Pipeline Investment | Accelerates market access for moment-resisting connectors in Germany's CLT corridor. |
| Software-Hardware Bundle Development | Anchors specification workflows among Nordic timber engineering consultancies. |
| Composite Material R&D Partnership | Captures waterfront specification share as Swedish thermal-bridge regulations tighten. |
| French CSTB Pre-Certification Program | Creates first-mover advantage before CLT code maturation accelerates. |
| Timber-Grade Traceability Integration | Aligns connector documentation with EU Deforestation Regulation supply-chain mandates. |
Research Methodology
Multi-period observation of DIBt approval timelines, CSTB evaluation backlogs, and galvanized steel input costs anchored the trend analysis, supplemented by interviews with timber engineering consultants, prefabrication plant managers, and structural hardware procurement leads at French commercial developers. Secondary validation drew from Eurocode 5 technical committee minutes, Construction Products Regulation notified body disclosures, and European timber trade association production statistics. Bottom-up connector shipment estimates triangulated against top-down mass-timber construction permits.
Input-output matrices modeled demand across product type, material grade, application scale, and end-user technical authority dimensions throughout the forecast period. CAGRs derived from regression analysis of historical specification rates against CLT building code maturation indices and EU Green Deal renovation wave implementation timelines. Industry-specific forecast inputs included automated truss line capacity utilization rates and timber engineering consultancy licensing patterns.
Several conditions sit outside the modeled scope, including potential harmonization of DIBt and CSTB evaluation protocols, breakthrough structural adhesive performance thresholds, and abrupt zinc supply disruptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Wood Shingles Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
Africa Construction Chemicals Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Nordic Solar Shades Market