
 Philippines Structural Insulated Panels Market | 2026-2036
Philippines Structural Insulated Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Structural Insulated Panels Market Analytics
Philippine panel manufacturers is restructuring domestic supply chains to serve archipelago logistics and typhoon-resistant construction codes. Ultra Insulated Panel Systems Corporation leverages vertical integration from foam core production to finished panel delivery. ENERCON Specialty Building Systems Corporation anchors its position through R&D intensity in polyurethane formulations. Kingspan Group competes via global manufacturing scale adapted to Philippine project specifications.
Structural insulated panels are composite building elements comprising rigid foam insulation bonded between two structural facings, typically oriented strand board or metal sheets, delivering thermal resistance values exceeding conventional framed walls while enabling rapid enclosure of building envelopes. The product category spans EPS, XPS, polyurethane, and glass wool cores, with polyurethane commanding premium positioning due to superior R-value per inch and structural bond strength demanded in high-rise commercial applications. Installation type segments split across prefab, modular, on-site, and retrofit methods, with prefab and modular approaches capturing expanding share as Philippine developers seek to compress construction schedules and reduce on-site labor dependency.
The Department of Public Works and Highways enforces National Building Code provisions that incentivize thermal performance standards, while the Board of Investments administers incentive structures for energy-efficient construction materials under the Investment Priorities Plan. BIS certification requirements for imported panel components create compliance thresholds that filter supplier participation. Stakeholders must monitor pending amendments to green building rating systems and local government unit permitting timelines that determine project viability.
Market Dynamics
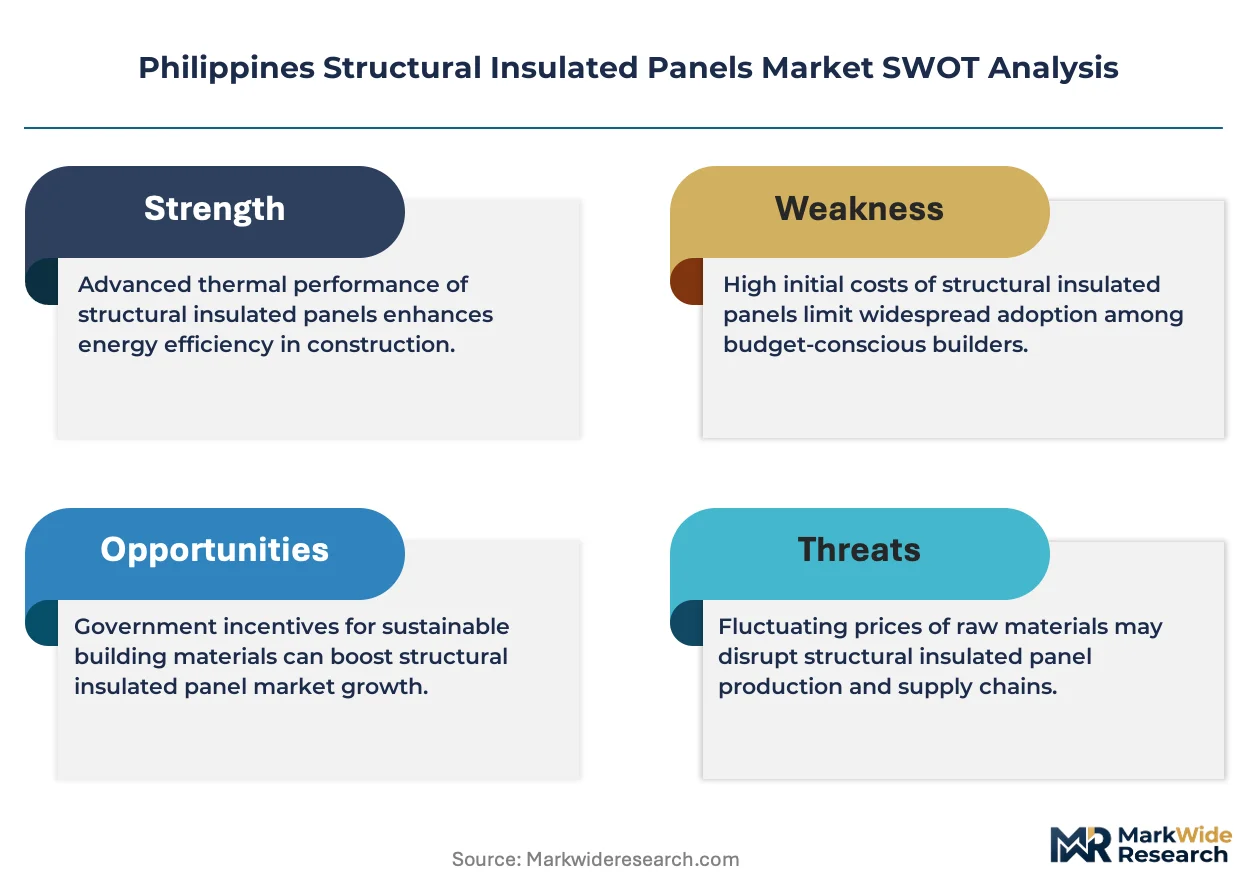
The Philippines SIP market pivots on the DPWH's 2024 National Building Code amendments mandating thermal performance benchmarks for commercial structures above 500 square meters, compressing approval timelines for compliant materials while penalizing conventional framed construction with extended permitting delays.
Growth Catalysts
- Metro Manila Density Mandates:Local government units in Quezon City and Taguig now fast-track building permits for prefabricated envelope systems, reducing administrative cycles from 90 days to 45 days for SIP-based projects.
- Board of Investments Incentives:The Investment Priorities Plan grants income tax holidays and duty exemptions on imported foam core machinery to manufacturers achieving 40% local value-added thresholds.
- Polyurethane Core Chemistry:Advancements in fire-retardant blowing agents enable R-7 thermal ratings per inch, satisfying high-rise commercial specifications previously reserved for concrete curtain walls.
Market Restraints
- Petrochemical Input Volatility:MDI and polyol feedstock prices fluctuate with regional naphtha cracking capacity, compressing panel producer margins when Brent crude exceeds $80 per barrel.
- BIS Certification Bottlenecks:Bureau of Indian Standards import conformity assessment for OSB facings creates 60-90 day customs holds, disrupting just-in-time project schedules.
- Skilled Installer Scarcity:The Philippine construction sector trains fewer than 200 certified SIP technicians annually against projected demand for 800+ specialized installers through 2030.
Strategic Opportunities
- Visayas Archipelago Expansion:Iloilo and Bacolod developers lack local panel fabrication capacity, creating first-mover advantages for producers establishing Cebu satellite facilities with inter-island barge logistics.
- Retrofit Channel Development:Existing commercial buildings in Makati CBD face DPWH-mandated energy audits, opening envelope-overhaul contracts for external SIP cladding systems.
- Green Building Rating Convergence:BERDE certification alignment with ASEAN Energy Management System standards unlocks preferential financing from LandBank and DBP for certified projects.
Industry Challenges
- Typhoon-Resistant Connection Engineering:Panel-to-foundation anchoring systems must demonstrate 250 kph wind-load resistance under PAGASA revised hazard maps, requiring proprietary testing protocols absent from international standards.
- Inter-Island Logistics Friction:Roll-on/roll-off vessel capacity constraints between Luzon and Mindanao inflate landed costs by 18-22% versus Metro Manila delivery, fragmenting national pricing consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Structural Insulated Panels Market |
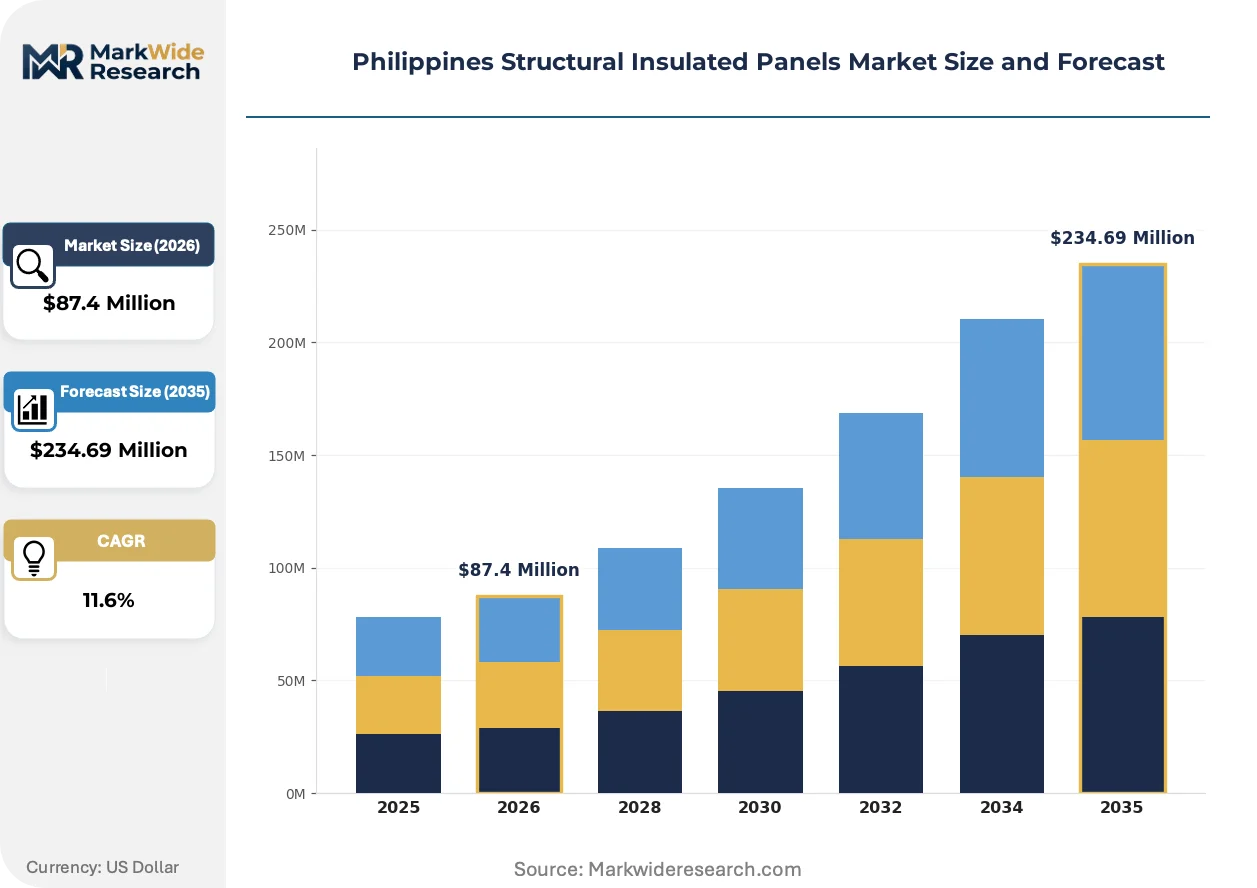
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPS, XPS, Polyurethane, Glass Wool Application: Residential, Commercial, Industrial, Agricultural Installation Type: Prefab, Modular, On-Site, Retrofit End User: Construction Companies, Architects, Builders, Homeowners |
| Companies Covered | Ultra Insulated Panel Systems Corporation, iSTEEL, Union Galvasteel Corporation, Metalink, VBLLU INC, ENERCON Specialty Building Systems Corporation, Kingspan Group, SUPERSONIC MANUFACTURING INC, Jackon Insulation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Structural Insulated Panels Market Evolving Landscape
Material science breakthroughs and procurement model evolution are compressing traditional construction timelines while reconfiguring how Philippine developers source building envelope systems.
Polyurethane foam cores with graphite-enhanced cell structures are integrating nanoscale thermal barriers that boost R-values without thickness penalties. High-rise commercial developers in Ortigas Center and Bonifacio Global City specify these panels to maximize leasable floor area within height restrictions. The technology is integrating fire-safety and thermal performance into single specification sheets, reducing consultant coordination cycles by 30%.
The DPWH's pending adoption of ISO 52016-1 energy calculation standards will mandate whole-building thermal modeling for permit approval. Engineering consultancies are retraining staff in dynamic simulation software to maintain accreditation. Residential subdivision developers in Cavite and Laguna provinces face the steepest compliance learning curves, driving demand for pre-certified panel system packages.
Direct manufacturer-to-developer contracting is displacing traditional general contractor intermediaries for envelope packages. Ayala Land and SM Prime Holdings now issue separate SIP procurement tenders parallel to structural bids, compressing subcontractor margins. This pattern concentrates most visibly in Clark and Subic special economic zones where foreign contractors import familiar specification standards.
Philippines Structural Insulated Panels Market Segmentation
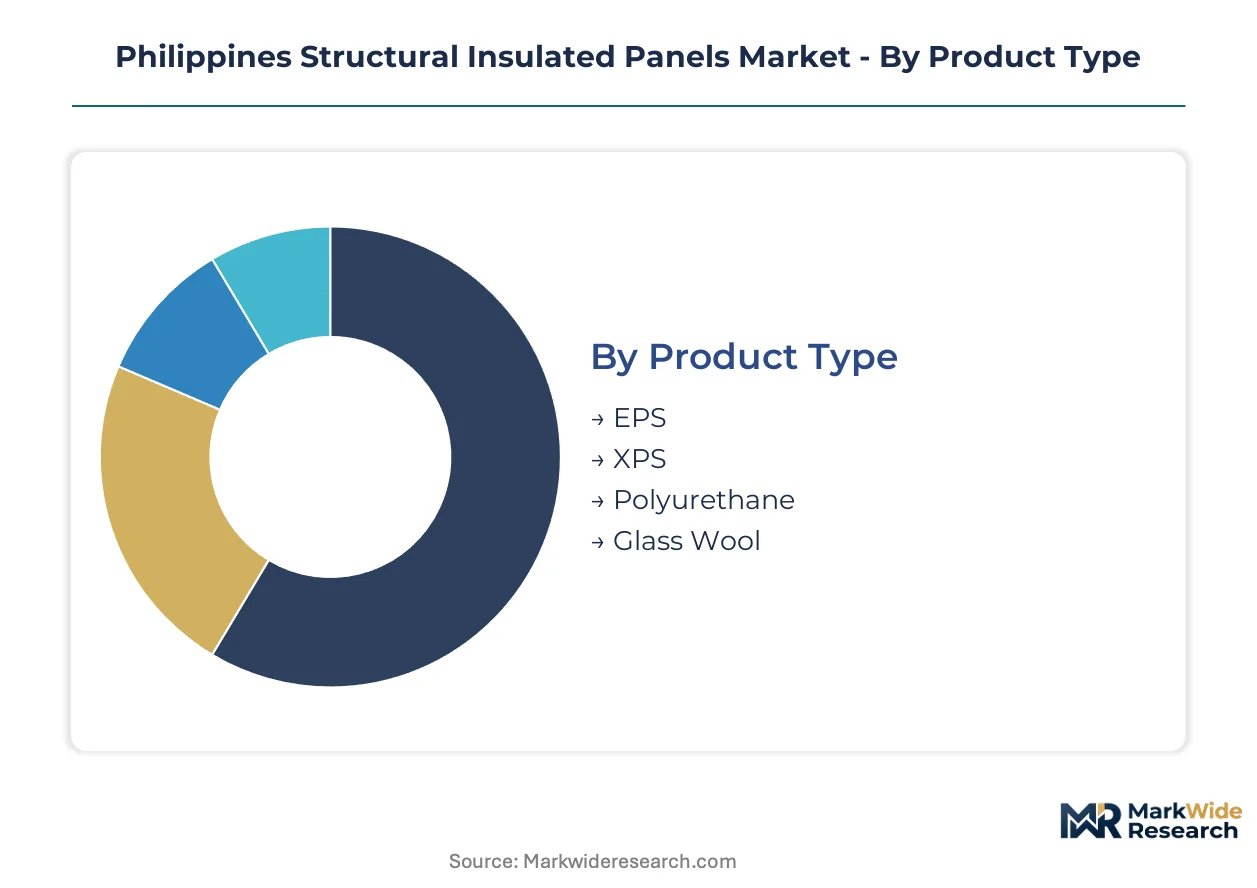
Segmentation reveals how DPWH thermal performance mandates and BIS certification requirements filter across different panel specifications and project delivery methods. Each dimension carries distinct compliance burdens that reshape procurement priorities for Philippine developers.
Product Type:
Certification intensity varies by core chemistry, with polyurethane and glass wool facing stricter BIS fire-safety testing than expanded polystyrene variants.
- Polyurethane:Closed-cell foam chemistry delivers R-7 thermal resistance per inch through graphite-enhanced cell structures. Bonifacio Global City high-rise developers specify these panels to maximize leasable floor area within height restrictions, though MDI feedstock volatility compresses margins when Brent crude exceeds $80 per barrel.
- EPS:Expanded polystyrene cores offer cost-effective R-4 performance for single-story residential subdivisions in Cavite and Laguna provinces. DPWH permitting timelines for EPS-based projects run shorter due to established testing protocols, accelerating developer cash conversion cycles.
- XPS:Extruded polystyrene provides moisture-resistant performance for agricultural cold storage facilities in Central Luzon.
- Glass Wool:Mineral fiber cores satisfy fire-rated commercial specifications in Makati CBD retrofit applications.
Polyurethane sits at the top of the volume ranking, with glass wool climbing the fastest as BERDE certification requirements tighten.
Application:
Project scale determines which segments absorb the steepest compliance learning curves under pending ISO 52016-1 energy modeling mandates.
- Commercial:Office towers and retail complexes above 500 square meters face mandatory thermal performance benchmarks under 2024 National Building Code amendments. Ortigas Center developers pre-certify envelope packages to compress permitting cycles, with whole-building dynamic simulation now required for DPWH approval.
- Residential:Subdivision housing in Quezon City and Taguig benefits from fast-tracked 45-day permits for prefabricated envelope systems. Cavite and Laguna developers face the steepest compliance learning curves, driving demand for pre-certified panel packages from vertically integrated suppliers.
- Industrial:Clark and Subic special economic zone factories require rapid enclosure to meet foreign contractor schedules.
- Agricultural:Poultry and cold storage facilities in Central Luzon prioritize moisture-resistant XPS cores.
Commercial commands the largest project values, with residential expanding most quickly as local government unit incentives proliferate.
Installation Type:
Delivery method selection directly determines labor certification requirements and inter-island logistics complexity.
- Prefab:Factory-finished panels ship from Metro Manila fabrication plants to Quezon City and Taguig construction sites, reducing on-site labor dependency. The Philippine construction sector trains fewer than 200 certified SIP technicians annually against projected demand for 800+ specialized installers through 2030, constraining expansion velocity.
- Modular:Volumetric units integrate structural, mechanical, and envelope systems for Clark special economic zone projects. Foreign contractors import familiar specification standards, displacing traditional general contractor intermediaries for envelope packages.
- On-Site:Panel assembly at project location persists in Mindanao where roll-on/roll-off vessel capacity constraints inflate landed costs by 18-22%.
- Retrofit:External cladding systems target Makati CBD buildings facing DPWH-mandated energy audits.
Prefab holds the dominant share, with retrofit gaining share fastest as existing commercial stock faces efficiency mandates.
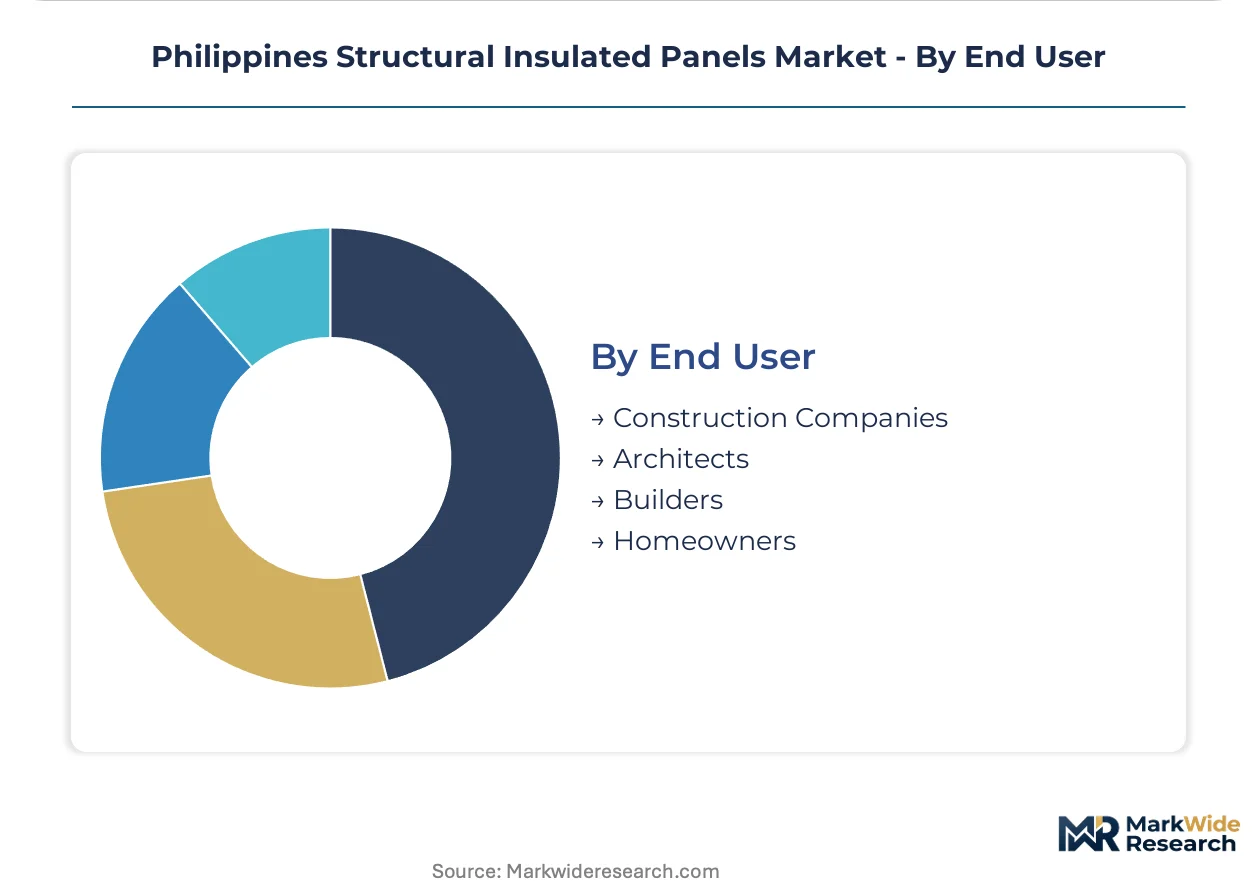
End User:
Procurement authority concentration varies sharply across buyer categories, with institutional developers bypassing traditional subcontractor networks.
- Construction Companies:Large Philippine contractors aggregate envelope specifications across multiple projects, extracting volume discounts from panel manufacturers. Direct manufacturer-to-developer contracting now runs parallel to structural bids, compressing subcontractor margins.
- Builders:Smaller construction firms serving Iloilo and Bacolod lack local fabrication capacity, creating first-mover advantages for Cebu satellite facilities with inter-island barge logistics.
- Architects:Design consultants specify fire-retardant polyurethane formulations for high-rise commercial applications.
- Homeowners:Individual buyers in residential subdivisions rely on developer-specified panel systems.
Construction companies dominate procurement volume, with builders representing the steepest expansion trajectory as Visayas archipelago development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between Philippine regions are redirecting panel fabrication capacity toward areas with streamlined permitting and proximity to raw material terminals. DPWH thermal performance mandates apply uniformly, yet local government unit processing speeds and logistics infrastructure create arbitrage opportunities for producers.
Metro Manila
Quezon City and Taguig municipal governments fast-track building permits for prefabricated envelope systems, compressing administrative cycles from 90 days to 45 days. The Board of Investments administers income tax holidays for manufacturers achieving 40% local value-added thresholds. Ortigas Center and Bonifacio Global City clusters concentrate high-rise commercial specifications demanding fire-retardant polyurethane cores with R-7 thermal ratings.
Central Luzon
Clark and Subic special economic zones attract foreign contractors importing familiar specification standards for rapid factory enclosure projects. The Investment Priorities Plan grants duty exemptions on imported foam core machinery to qualified producers. Pampanga and Tarlac provinces host agricultural cold storage facilities prioritizing moisture-resistant XPS panels for poultry and refrigerated warehousing applications.
Calabarzon
Cavite and Laguna residential subdivision developers face steep compliance learning curves under pending ISO 52016-1 energy modeling mandates. DPWH permitting timelines for EPS-based projects run shorter due to established testing protocols, accelerating developer cash conversion cycles. Batangas port infrastructure supports chemical feedstock imports for polyurethane production.
Visayas
Iloilo and Bacolod developers lack local panel fabrication capacity, creating first-mover advantages for Cebu satellite facilities with inter-island barge logistics. Roll-on/roll-off vessel capacity constraints between Luzon and Mindanao inflate landed costs by 18-22% versus Metro Manila delivery. Cebu City concentrates demand for prefabricated systems serving hospitality and commercial projects.
Mindanao
Davao and Cagayan de Oro construction markets rely on on-site panel assembly due to fragmented inter-island shipping schedules. PAGASA revised hazard maps mandate 250 kph wind-load resistance for panel-to-foundation anchoring systems. Mindanao development corridors face skilled installer scarcity, with fewer than 200 certified SIP technicians trained annually against projected demand.
Philippines Structural Insulated Panels Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulations and regional logistics optimization. The Philippine SIP market structures around three archetypes: domestic vertically integrated fabricators controlling foam core production, international building envelope conglomerates adapting global specifications, and regional metal roofing specialists extending into insulated panel systems. Competitive moves concentrate on Cebu satellite facility establishment and direct manufacturer-to-developer contracting that displaces traditional general contractor intermediaries.
Among domestic fabricators, Ultra Insulated Panel Systems Corporation exemplifies vertical control from foam core production through finished panel delivery. ENERCON Specialty Building Systems Corporation anchors the specialty tier through polyurethane formulation intensity. Kingspan Group represents international scale adapted to Philippine project specifications. These three occupy distinct competitive positions without overlapping strategic territory.
| Leading Market Players |
|---|
| Ultra Insulated Panel Systems Corporation |
| iSTEEL |
| Union Galvasteel Corporation |
| Metalink |
| VBLLU INC |
| ENERCON Specialty Building Systems Corporation |
| Kingspan Group |
| SUPERSONIC MANUFACTURING INC |
| Jackon Insulation |
| Others |
Value Network & Pricing Analysis
Brent crude benchmarks cascading through MDI and polyol feedstock markets stratify Philippine panel pricing across three performance tiers. Polyurethane core manufacturers absorb petrochemical volatility when oil exceeds threshold levels, compressing margins on premium specifications while EPS-based residential systems maintain pricing stability through established supply contracts.
Pricing Analysis
Distributor markups on imported OSB facings widen spreads between domestic and foreign-sourced panel systems. Three-tier pricing structure across premium fire-retardant polyurethane, standard graphite-enhanced EPS, and economy-grade XPS agricultural panels reflects certification grade and volume scale differentiation. Cost compression in the premium tier is intensifying because MDI feedstock volatility erodes producer margins during oil price spikes. Residential subdivision developers in Cavite and Laguna provinces exhibit highest price sensitivity, while Bonifacio Global City commercial developers prioritize thermal performance over unit cost.
Supply Chain Analysis
BIS certification requirements for imported facing materials gate supplier participation and fragment sourcing options. Raw material procurement draws from South Korean MDI producers, Chinese polyol specialists, and domestic Batangas port chemical terminals. OSB facing supply rests on Canadian and European timber processors subject to extended customs conformity assessments. Single-source vulnerability concentrates in certified fire-retardant blowing agent formulations. Distribution runs through Metro Manila fabrication hubs with satellite barge logistics to Cebu serving Visayas archipelago projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines SIP market functions as a geographic-arbitrage play where 45-day permitting in Quezon City and Taguig against 90-day conventional cycles in other jurisdictions creates developer margin capture opportunities.
For Market Incumbents: Deepen backward integration into foam core production to defend against petrochemical margin squeeze. Secure captive MDI supply arrangements with Korean petrochemical majors. Establish Cebu satellite fabrication capacity to preempt Visayas archipelago entrants before inter-island logistics infrastructure matures.
For New Entrants and Emerging Players: Capture Iloilo and Bacolod white-space markets lacking local panel fabrication capacity. Target agricultural cold storage applications in Central Luzon where moisture-resistant XPS specifications face limited specialist competition. Pursue direct-to-developer contracting models that bypass traditional general contractor intermediaries.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional logistics fragmentation and certification bottlenecks favor scaled producers with integrated supply chains. Five-to-ten year viability favors vertically integrated fabricators controlling core chemistry through finished panel delivery. Acquisition target archetypes include Cebu-based metal roofing specialists extending into insulated panel systems. The signal to watch is DPWH adoption of ISO 52016-1 energy calculation standards accelerating compliance-driven specification consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cebu Satellite Facility Establishment | Inter-island barge logistics reduce Visayas landed costs against Luzon-origin supply. |
| Backward Integration into Polyurethane Chemistry | In-house MDI-polyol blending insulates margins from Brent crude volatility spikes. |
| Direct Manufacturer-to-Developer Contracting | Ayala Land and SM Prime Holdings now issue parallel SIP tenders compressing subcontractor margins. |
| Fire-Retardant Formulation Certification | BIS-compliant blowing agent chemistry unlocks high-rise commercial specifications in Ortigas Center. |
| Retrofit Channel Development | Makati CBD energy audit mandates open external cladding overhaul contracts for existing commercial stock. |
Research Methodology
Bottom-up construction project modeling reconciled against top-down foam core production tracking forms the analytical core of this study. Primary interviews with DPWH regulatory officers, Philippine contractor procurement leads, panel fabrication plant managers, and BERDE certification consultants combined with secondary validation from Bureau of Investments incentive filings, DPWH National Building Code amendment records, and PAGASA hazard map revisions. Trade data from Philippine customs authorities and petrochemical import manifests anchored supply-side triangulation.
Input-output matrices mapped polyurethane, EPS, XPS, and glass wool core chemistry against commercial, residential, industrial, and agricultural application segments throughout the forecast period. Installation type splits across prefab, modular, on-site, and retrofit methods were modeled with regional delivery cost differentials. CAGRs derived from project pipeline analysis across Metro Manila, Central Luzon, Calabarzon, Visayas, and Mindanao development corridors. Feedstock price elasticity and skilled installer training capacity constrained expansion velocity assumptions.
DPWH regulatory amendment timing, petrochemical price volatility, and inter-island shipping capacity constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on incentive plan continuity and certification protocol stability. A model refresh is warranted upon material change in National Building Code thermal performance enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Americas Structural Insulated Panel Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Cold-Formed Steel Market
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Fabricated Structural Steel Market
Structural Engineering
Metal Structural Insulation Panels Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
North America Facade Market